
 Thermoplastic Polyester Engineering Resin (TPER) Market | 2026-2036
Thermoplastic Polyester Engineering Resin (TPER) Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Polyester Engineering Resin (TPER) Market Analytics
Buyer concentration among automotive electrification programs is broadening as legacy OEMs and battery startups diversify resin procurement across multiple qualified suppliers. Celanese Corporation leverages its acetyl chain integration to secure captive feedstock for PBT production. Mitsubishi Engineering-Plastics Corporation anchors Asian supply through dedicated compounding facilities serving Toyota and Honda tier networks. DuPont competes on high-heat polymer expertise inherited from long-cycle industrial specialization.
Thermoplastic Polyester Engineering Resin denotes a class of melt-processable polyesters—principally PET, PBT, and copolyesters—exhibiting crystallinity between 30-50%, glass transition temperatures of 70-80°C, and tensile strengths exceeding 50 MPa in reinforced grades, engineered primarily for dimensional stability under mechanical load and thermal cycling in precision-molded components. Polybutylene Terephthalate dominates volume through automotive connector and sensor housing applications where hydrolysis resistance proves critical. Copolyester grades represent the fastest-expanding margin pool as medical device manufacturers and food-contact packaging producers seek amorphous clarity combined with chemical sterilization tolerance. Polyethylene Terephthalate reinforced compounds sustain mature industrial positioning in pump housings and valve bodies where cost-performance ratios outweigh premium material specifications.
The US EPA oversees emissions compliance for resin manufacturing facilities under Clean Air Act Title V permitting, while the EU REACH framework mandates registration and restricted substance protocols for terephthalic acid and butanediol feedstocks entering European polymer supply chains. China's MEE enforces dual carbon goals that tighten energy intensity benchmarks for PTA and BDO intermediates, redirecting capacity investments toward lower-carbon process routes. Stakeholders must monitor regulatory divergence between jurisdictions to align product certification strategies with diverging chemical safety and carbon accounting standards.
Market Dynamics
Automotive electrification is forcing resin qualification cycles to compress from 36 months to 18 months as battery pack architectures iterate faster than traditional powertrain programs. Tier-1 suppliers must now validate hydrolysis-resistant PBT grades across multiple temperature zones simultaneously.
Growth Catalysts
- China's dual carbon goals:Domestic EV production scales are concentrating demand for lightweight connector housings. MEE enforcement redirects PTA capacity toward lower-carbon process routes.
- Medical device sterilization protocols:Copolyester clarity grades penetrate autoclave-compatible instrument trays. Amorphous transparency replaces polycarbonate in cyclic steam exposure applications.
- REACH substance restrictions:European chemical safety protocols phase out legacy flame retardants in automotive interiors. Reformulation mandates accelerate halogen-free PBT compound development.
Market Restraints
- Feedstock concentration:Purified terephthalic acid supply clusters along China's eastern seaboard. Geopolitical friction threatens just-in-time resin production schedules.
- Butanediol price volatility:BDO spot markets swing with acetylene-based process economics. PBT margin compression follows raw material cost spikes without downstream pass-through mechanisms.
- Polyamide substitution:PA66 glass-filled grades retain cost advantage in non-hydrolysis-critical underhood applications. Temperature performance overlap limits PBT expansion in engine bay modules.
Strategic Opportunities
- India's PLI scheme for automotive:Component localization mandates create virgin demand for engineering resin compounding. Domestic EV assembly triggers resin qualification programs at Pune and Chennai tier-1 clusters.
- Closed-loop chemical recycling:Depolymerization-to-repolymerization routes for post-industrial PET scrap yield food-contact certified copolyesters. Circular material claims differentiate packaging film producers.
- 5G base station deployment:High-frequency connector housings require dielectric-stable PBT grades with controlled moisture absorption. Telecom infrastructure buildouts in Southeast Asia specify these materials.
Industry Challenges
- Color-matching complexity:Automotive OEMs demand batch-to-batch consistency across 15-year vehicle lifespans. Pigment dispersion in crystalline PBT requires specialized twin-screw compounding expertise.
- Multi-jurisdiction certification backlog:UL yellow card, VDE, and China CQC approvals run sequentially rather than parallel. 18-month validation timelines delay new grade commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Polyester Engineering Resin (TPER) Market |
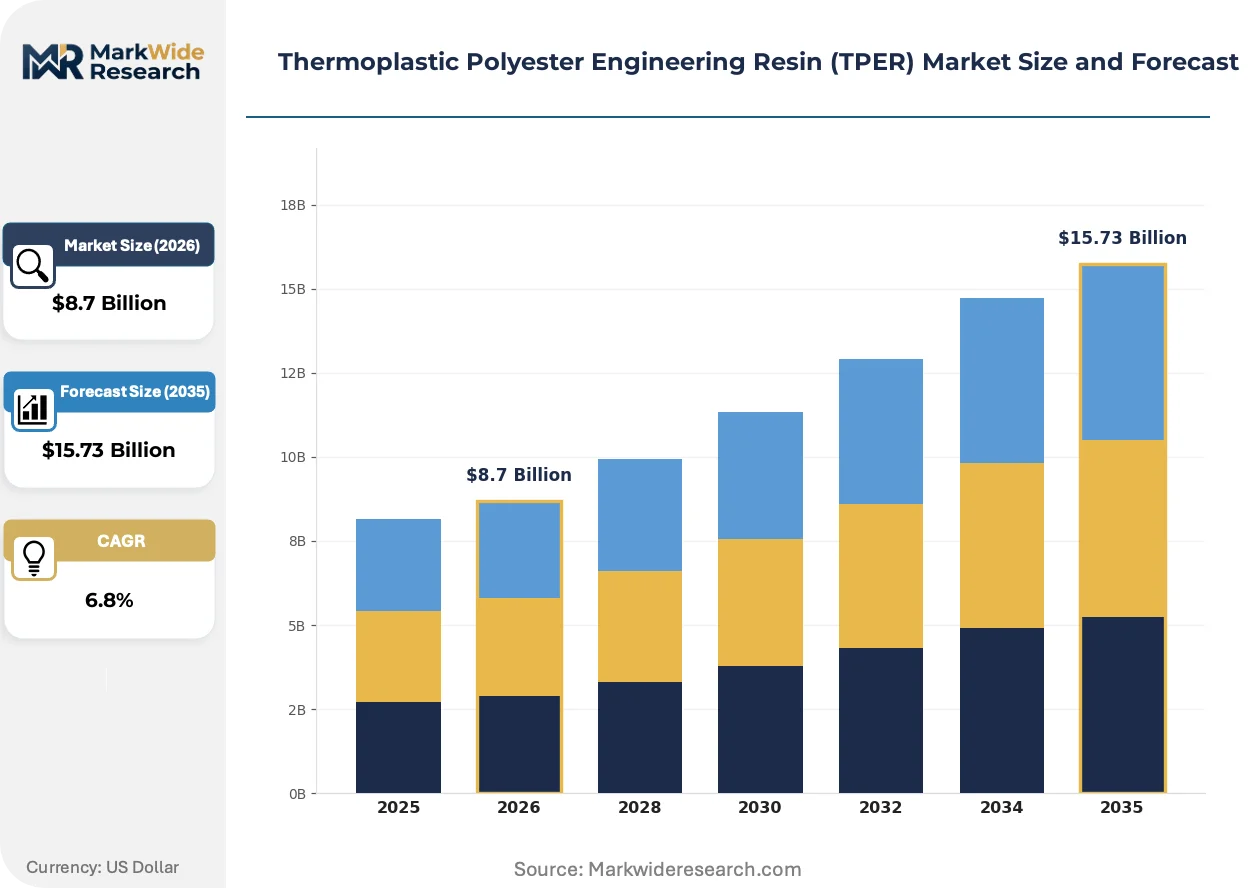
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, Polybutylene Terephthalate, Copolyester, Blends Application: Automotive Components, Consumer Electronics, Industrial Parts, Packaging Materials End User: Automotive, Electronics, Consumer Goods, Industrial Manufacturing Form: Granules, Sheets, Films, Pellets |
| Companies Covered | Celanese Corporation, Mitsubishi Engineering-Plastics Corporation, Lomont Molding LLC, SABIC, BASF SE, JRD POLYMER, Covestro AG, DuPont, SK Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Polyester Engineering Resin (TPER) Market Evolving Landscape
Bio-based feedstock substitution and process intensification are reshaping how polyester engineering resins achieve carbon footprint reduction without sacrificing hydrolysis resistance or dimensional stability.
Laser-direct structuring technology is integrating copper plating onto PBT surfaces for 3D-molded interconnect devices. Automotive sensor module manufacturers in Germany and Japan are adopting this capability to eliminate separate PCB assemblies. The process is integrating antenna and housing functions into single-shot molded components, compressing bill-of-material counts and assembly labor.
REACH Annex XIV authorization requirements for di(2-ethylhexyl) phthalate and related plasticizers are forcing reformulation of flexible copolyester grades used in medical tubing. Compounders must validate alternative chain extenders that maintain Shore hardness and sterilization tolerance. European medical device OEMs are accelerating supplier audits to secure uninterrupted material flows before sunset dates.
Consolidated procurement platforms among Chinese battery OEMs are compressing supplier panels from six qualified resin sources to two preferred partners per specification grade. Long-term offtake agreements now bundle compounding, color concentrate, and technical service into single contracts. This concentration is most visible in Ningbo and Shenzhen, where CATL and BYD procurement teams negotiate multi-year resin supply with indexed pricing mechanisms.
Thermoplastic Polyester Engineering Resin (TPER) Market Segmentation
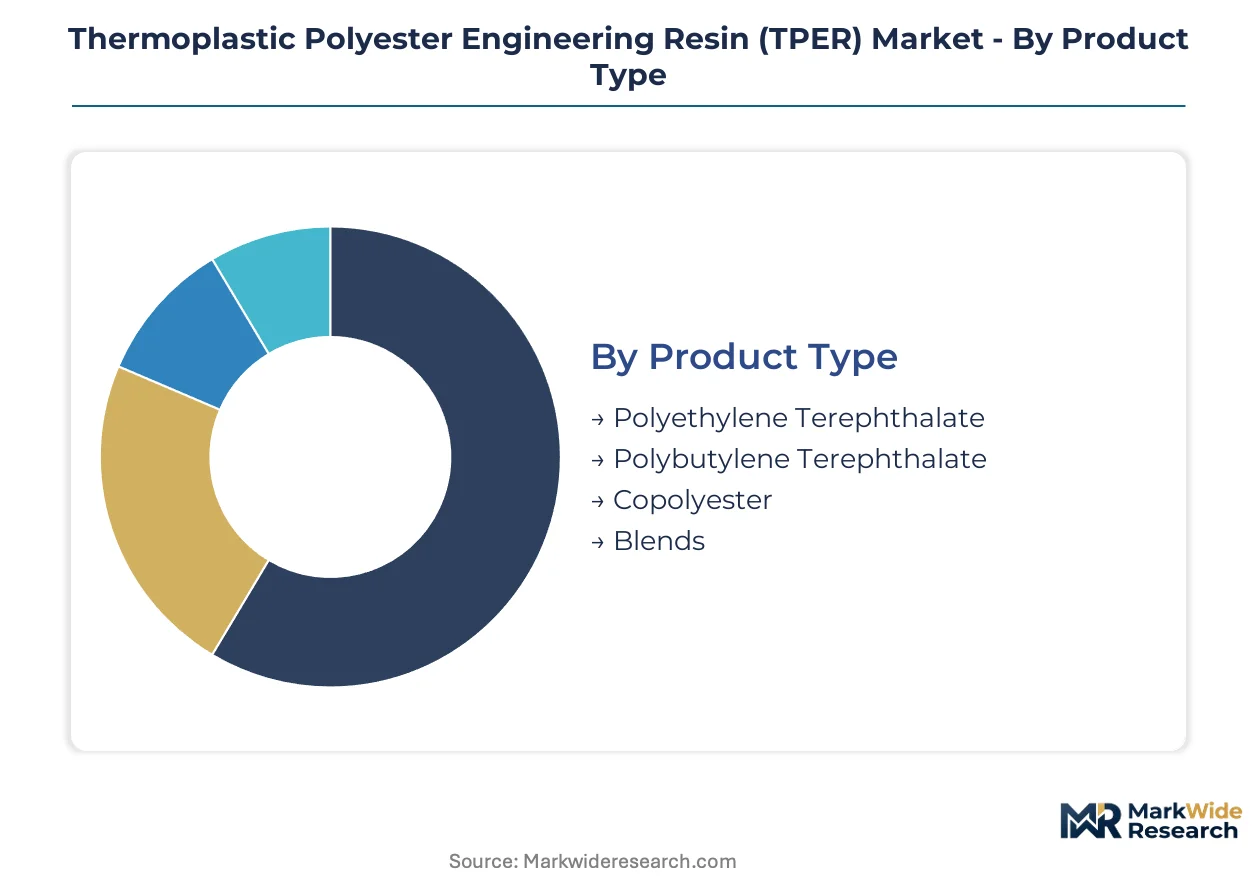
TPER procurement patterns diverge sharply across product chemistry, application thermal requirements, and end-user qualification protocols. Segment boundaries determine margin capture, with hydrolysis-resistant grades commanding premiums in automotive electrification while clarity copolyesters penetrate medical sterilization workflows.
Product Type:
Buyers differentiate primarily by crystallinity targets and moisture absorption tolerances that dictate molding yield and long-term dimensional stability.
- Polyethylene Terephthalate:Semi-crystalline polyester with 250-260°C melting point and excellent chemical resistance. Demand concentrates in German pump housing and valve body manufacturers where cost-performance ratios outweigh premium specifications; REACH substance restrictions on legacy additives force continuous reformulation cycles.
- Polybutylene Terephthalate:Lower melting point (220-230°C) with superior hydrolysis resistance and faster crystallization kinetics. Automotive tier-1 suppliers in Japan and Germany specify glass-filled grades for connector housings exposed to battery pack humidity cycling; 18-month qualification compression favors established compounders with captive BDO supply.
- Copolyester:Amorphous clarity grades combining transparency with autoclave and gamma sterilization tolerance. Medical device OEMs in Switzerland and Massachusetts specify these for instrument trays replacing polycarbonate in cyclic steam exposure.
- Blends:Alloyed formulations with PC or elastomers balancing impact resistance and chemical tolerance. Consumer electronics housing producers in South Korea utilize these for drop-test compliance without secondary overmolding operations.
Polybutylene Terephthalate leads volumes today; Copolyester is gaining share fastest.
Application:
Thermal load severity and regulatory exposure separate application tiers, with electrification programs resetting material specifications faster than industrial replacement cycles.
- Automotive Components:Underhood sensors, high-voltage connectors, and battery module housings requiring hydrolysis resistance across -40°C to 150°C operating windows. China's Ningbo and Shenzhen EV clusters concentrate procurement through consolidated supplier panels; MEE dual carbon enforcement redirects PTA capacity toward qualified resin producers.
- Consumer Electronics:Laptop chassis, smartphone structural frames, and wearable device housings prioritizing thin-wall flow and surface finish. Japanese OEMs specify flame-retardant grades meeting JIS standards for thermal runaway containment.
- Industrial Parts:Pump housings, valve bodies, and conveyor components in chemical processing environments. German industrial equipment manufacturers favor PET-based compounds for abrasion resistance in slurry handling applications.
- Packaging Materials:Food-contact films and medical sterilization pouches requiring amorphous clarity and barrier properties. European packaging converters leverage closed-loop chemical recycling claims to differentiate against virgin resin competitors.
Automotive Components anchor current procurement volumes; Packaging Materials show the steepest expansion trajectory as circular material certification penetrates premium segments.
End User:
Qualification burden and volume predictability distinguish end-user categories, with automotive programs demanding 15-year batch consistency while consumer goods tolerate broader specification bands.
- Automotive:Tier-1 component suppliers managing OEM color-matching protocols across multi-year vehicle platforms. India's PLI scheme localization mandates trigger resin qualification programs at Pune and Chennai compounding clusters.
- Electronics:Contract manufacturers serving brand OEMs with rapid product refresh cycles. Taiwanese and South Korean EMS providers specify halogen-free grades meeting IEC 61249-2-21 for printed circuit substrate applications.
- Consumer Goods:Appliance and personal care product manufacturers prioritizing aesthetic surface quality over thermal performance. Mexican maquiladora operations source standard-grade pellets for cost-sensitive housing applications.
- Industrial Manufacturing:OEMs and maintenance-repair-operations buyers with specification continuity spanning decades. Brazilian petrochemical equipment rebuilders specify glass-reinforced compounds for corrosion-resistant impeller replacement.
Automotive end users dominate qualified volume commitments; Electronics procurement is accelerating most rapidly as 5G infrastructure deployment expands high-frequency connector specifications.
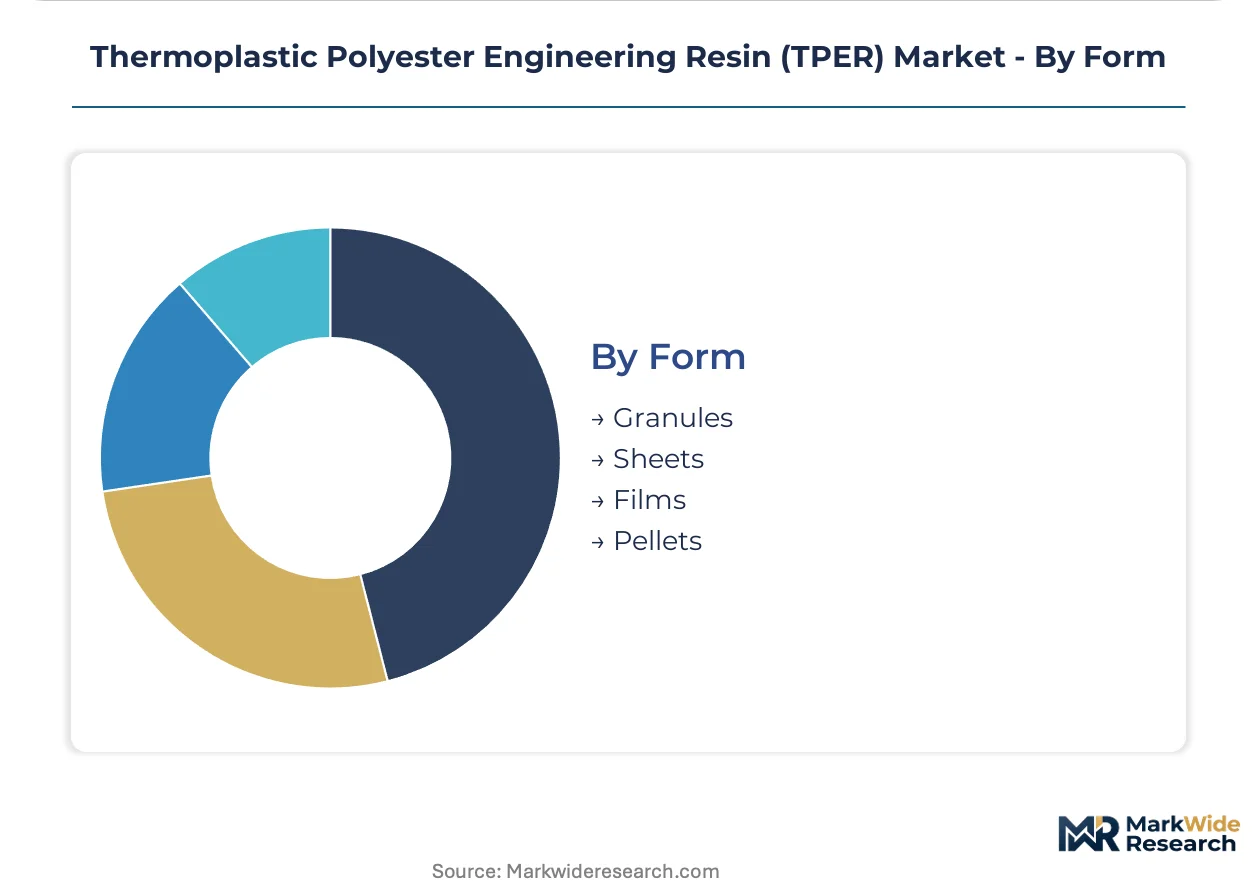
Form:
Processing equipment compatibility and logistics economics shape form selection, with bulk pellet shipments favoring high-volume automotive programs while sheet and film formats serve specialized thermoforming workflows.
- Granules:Standard injection molding feedstock with consistent particle size distribution for twin-screw compounding operations. Chinese battery OEM procurement platforms consolidate granule supply through multi-year offtake agreements bundling technical service.
- Sheets:Extruded flat stock for thermoformed medical trays and industrial equipment housings. German thermoformers specify copolyester sheets for deep-draw sterilization tray applications.
- Films:Biaxially oriented or cast formats for flexible packaging and electronic substrate applications. Japanese film converters supply 5G antenna substrate manufacturers with dielectric-stable PET grades.
- Pellets:Compounded formulations with pre-dispersed additives and color concentrates. US automotive tier-1 suppliers specify pellet formats to minimize in-house blending capital expenditure.
Granules command the largest shipment volumes today; Films are climbing fastest as flexible electronics and advanced packaging applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates engineering resin procurement through battery OEM consolidation, while Germany maintains specification leadership through tier-1 automotive validation protocols. Regulatory divergence between REACH substance restrictions and China's dual carbon enforcement is fragmenting certification requirements across supply chains.
China
Domestic EV production scales are concentrating demand for lightweight connector housings in Ningbo and Shenzhen clusters. MEE enforcement redirects PTA capacity toward lower-carbon process routes for qualified resin producers. CATL and BYD procurement teams negotiate multi-year offtake agreements bundling compounding and technical service.
Germany
Automotive tier-1 suppliers specify glass-filled PBT grades for high-voltage connectors exposed to battery pack humidity cycling. KBA vehicle type approval mandates hydrolysis resistance validation across -40°C to 150°C operating windows. Stuttgart and Munich industrial corridors host laser-direct structuring adoption for 3D-molded interconnect devices.
United States
EPA Clean Air Act Title V permitting governs emissions compliance for resin manufacturing facilities in Texas and Louisiana petrochemical corridors. Automotive OEMs demand 15-year batch-to-batch color consistency for interior components. Detroit-area tier-1 suppliers specify pellet formats to minimize in-house blending capital expenditure.
Japan
METI industrial standards shape JIS-compliant flame-retardant grades for consumer electronics thermal runaway containment. Toyota and Honda tier networks anchor Mitsubishi Engineering-Plastics compounding facility utilization. Nagoya and Osaka industrial zones concentrate medical device OEM audits for copolyester sterilization tray applications.
India
PLI scheme localization mandates trigger resin qualification programs at Pune and Chennai compounding clusters. BIS certification requirements for automotive components extend validation timelines for imported compound formulations. Domestic EV assembly is accelerating procurement of hydrolysis-resistant connector grades from qualified suppliers.
Thermoplastic Polyester Engineering Resin (TPER) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The vendor base organizes around three strategic archetypes: integrated petrochemical majors with captive feedstock, regional compounders serving qualified tier-1 networks, and technology licensors monetizing proprietary catalyst systems. Competitive moves center on backward integration into BDO intermediates and geographic expansion through joint venture compounding facilities.
Among integrated material science conglomerates, Celanese Corporation and BASF SE exemplify archetypes leveraging acetyl chain integration for captive PBT feedstock security. Mitsubishi Engineering-Plastics Corporation anchors Asian supply architecture through dedicated compounding infrastructure. DuPont occupies a position reflecting high-heat polymer expertise inherited from long-cycle industrial specialization.
| Leading Market Players |
|---|
| Celanese Corporation |
| Mitsubishi Engineering-Plastics Corporation |
| Lomont Molding LLC |
| SABIC |
| BASF SE |
| JRD POLYMER |
| Covestro AG |
| DuPont |
| SK Chemicals |
| Others |
Value Network & Pricing Analysis
Specialized twin-screw compounding technicians in southern Germany command wage premiums that propagate through automotive PBT pricing tiers, widening spreads between qualified supplier rates and commodity compounder bids across European connector markets.
Pricing Analysis
Capacity additions in China's eastern seaboard are reshaping price floors for standard-grade PET compounds as new PTA integration comes online. Contract-based long-term offtake agreements dominate procurement between battery OEMs and qualified compounders, with price differentiation driven by hydrolysis-resistance certification tier and volume scale commitments. Pricing pressure stems from BDO spot market volatility that compounders cannot fully pass to downstream automotive tier-1s. Electronics contract manufacturers show highest price sensitivity due to rapid product refresh cycles, while medical device OEMs tolerate premium spreads for autoclave-validated clarity grades.
Supply Chain Analysis
Post-industrial PET scrap flows through depolymerization-to-repolymerization routes are creating circular feedstock channels that bypass virgin resin pricing. Supply concentrates in China, Germany, and Japan, with raw material dependencies on purified terephthalic acid, butanediol, and specialty glass fiber reinforcements. Single-source vulnerability runs through China's eastern seaboard PTA clusters where geopolitical friction threatens just-in-time schedules. Distribution runs through qualified tier-1 compounding facilities serving OEM direct-specification programs rather than merchant resin distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification programs provide durable demand anchoring for compounders with validated hydrolysis-resistant grades, sustaining margin capture across battery platform generations.
For Market Incumbents: Deepen captive BDO supply integration to insulate margin structures from acetylene-based process volatility. Expand compounding capacity in Pune and Chennai to capture India's PLI scheme localization mandates before qualification windows close. Polyamide substitution in non-critical underhood applications threatens PBT volume expansion; defend position through laser-direct structuring technology licensing for 3D-molded interconnect devices. For New Entrants and Emerging Players: Indian domestic EV assemblers represent an underserved buyer archetype with urgent resin qualification needs and limited incumbent relationships. Target medical device sterilization tray specifications where polycarbonate displacement creates specification gaps for autoclave-compatible clarity grades. Pursue joint venture compounding arrangements with established BDO producers to shortcut feedstock security requirements. For Investors and Strategic Acquirers: Specialty chemical conglomerates with acetyl chain assets are the most active acquirer in this space, seeking polyester engineering resin capabilities to complete materials portfolios. Five-to-ten year viability hinges on circular material certification penetration in European packaging and automotive interiors. Monitor REACH Annex XIV authorization timelines for phthalate plasticizer alternatives as inflection signals for medical-grade copolyester reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into BDO Intermediates | Celanese and BASF secure captive feedstock against acetylene price swings affecting PBT margins. |
| Joint Venture Compounding Facilities | Mitsubishi Engineering-Plastics anchors Toyota and Honda tier network utilization across Nagoya industrial zones. |
| Closed-loop Chemical Recycling Certification | European packaging converters differentiate against virgin resin competitors through food-contact validated copolyester claims. |
| Laser-direct Structuring Technology Licensing | German automotive sensor module manufacturers eliminate separate PCB assemblies through copper-plated PBT surfaces. |
| Multi-jurisdiction Certification Parallelization | UL yellow card, VDE, and China CQC approval compression reduces 18-month validation timelines for new grade commercialization. |
Research Methodology
Direct dialogue with automotive tier-1 procurement managers, resin plant operations directors, medical device OEM material scientists, and distribution channel partners grounded qualitative findings. Secondary validation drew from customs trade data, SEC 10-K chemical segment disclosures, ACC and Cefic industry reports, and REACH substance restriction filings. Bottom-up volume modeling across product chemistry, application thermal requirements, and end-user qualification protocols triangulated with top-down petrochemical capacity assessments.
Bottom-up segment modeling aggregated grade-specific volume assumptions across automotive electrification programs, medical sterilization workflows, and consumer electronics refresh cycles. Top-down constraints applied PTA and BDO intermediate capacity forecasts, MEE dual carbon enforcement trajectories, and REACH authorization sunset timelines. CAGRs derived from regression analysis of historical resin demand against EV production and industrial equipment output indices across the projection horizon.
Inputs from automotive OEM specification databases and medical device sterilization protocol registries were available through the study window; gaps in real-time BDO spot market transaction data introduce uncertainty bands around margin compression scenarios. Forecasts reflect assumptions regarding battery pack architecture standardization and regulatory divergence between jurisdictions. Practitioners should monitor CATL and BYD procurement panel consolidation patterns and REACH Annex XIV substance restriction timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Global Styrenic Polymers Market
Polymers & Resins
Saturated Polyester Resin Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Medical Grade Liquid Crystal Polymer Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Europe Engineering Plastics Market