
 PET Foam Market | 2026-2036
PET Foam Market Size, Share, and Industry Trends Forecast 2026-2036
PET Foam Market Intelligence
Consolidation among major wind turbine and automotive OEMs is expanding the base of buyers requiring large-volume, certified PET foam core materials. Diab Group leverages its expertise in sandwich composite technology to serve marine and wind energy clients. Gurit Holding specializes in advanced composite materials for high-performance applications. Armacell differentiates through its broad portfolio of engineered foams for various insulation and structural uses.
PET foam is a closed-cell thermoplastic structural foam produced from polyethylene terephthalate. It provides a high strength-to-weight ratio and excellent fatigue resistance, serving as a core material in composite sandwich structures. Rigid foam variants command the largest share, essential for load-bearing applications like construction panels and transportation parts. Among applications, demand for lightweight automotive components is accelerating, contrasting with the more stable use in packaging materials.
Regulatory frameworks like the EU's REACH and the US EPA's rules on blowing agents govern the chemical composition and manufacturing of PET foam. In parallel, national initiatives such as China's dual carbon goals promote its use in energy-saving applications. These standards directly influence material selection and market access for producers. Key strategic decisions for manufacturers now center on aligning product development with increasing demands for recyclability and lifecycle performance.
Market Dynamics
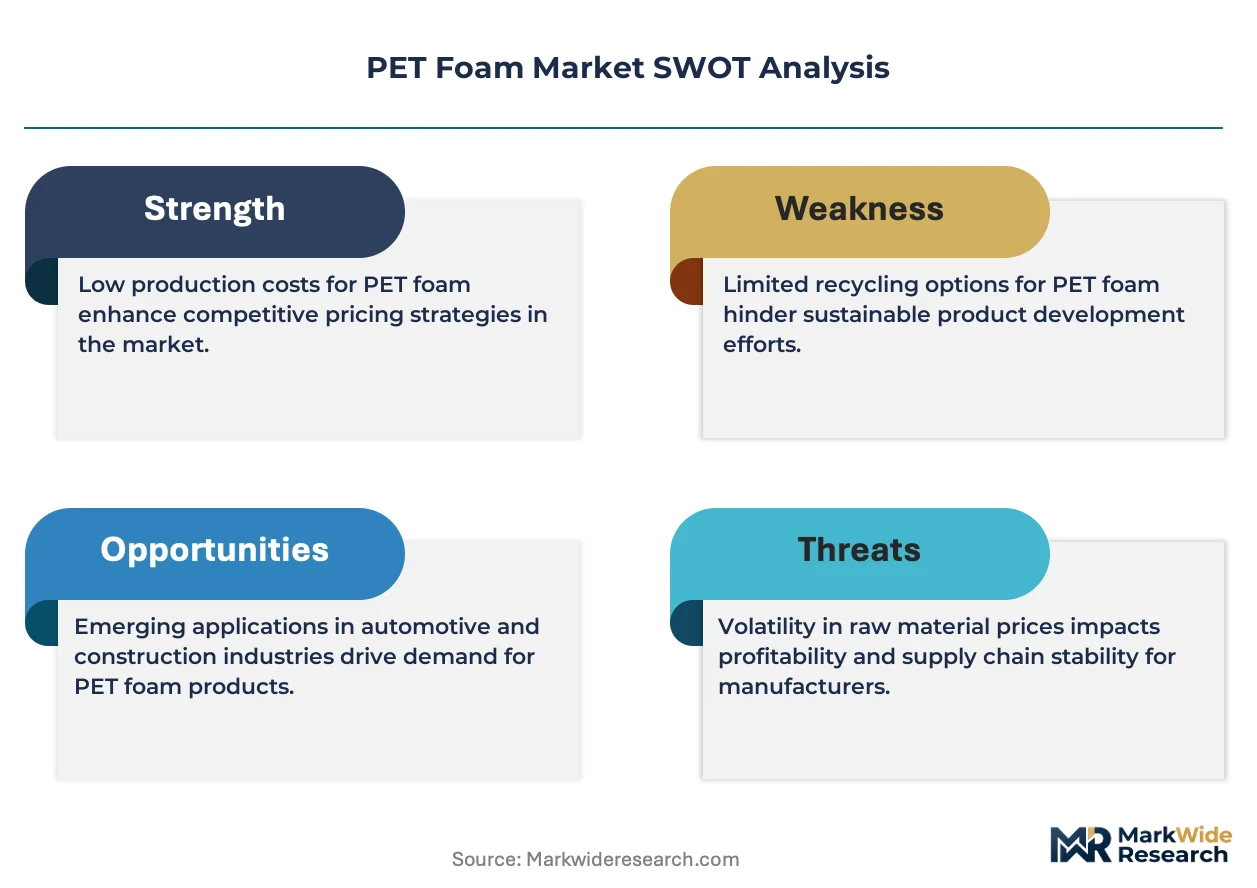
The market's central dynamic is the push for circularity, forcing manufacturers to balance the high-performance structural demands of wind energy and automotive applications with the material inconsistencies inherent in recycled PET feedstock streams.
Growth Catalysts
- EU Green Deal:Mandates for recycled content and circular economy principles favor materials like rPET foam, especially in construction and packaging sectors.
- Wind Energy Expansion:The global build-out of renewable energy infrastructure drives demand for lightweight, fatigue-resistant PET foam cores in large-scale wind turbine blades.
- Recycling Technology:Advances in chemical and mechanical recycling processes are improving the quality and consistency of rPET, enabling its use in higher-specification structural applications.
Market Restraints
- Feedstock Volatility:Price and quality fluctuations in the supply of post-consumer PET bottles create production cost instability for PET foam manufacturers.
- Substitution Threat:In less demanding applications, lower-cost core materials such as balsa wood, PVC, and SAN foams remain competitive alternatives.
- Processing Complexity:Achieving uniform cell structure and density with recycled feedstock requires sophisticated process control, adding to manufacturing costs and complexity.
Strategic Opportunities
- Electric Vehicle Components:Use in lightweight battery enclosures and interior components for EVs offers a new high-volume application driven by range extension goals.
- Indian Market Penetration:India's focus on domestic manufacturing and renewable energy through initiatives like the PLI scheme presents a significant growth market for local production.
- Fire-Retardant Grades:Developing PET foam variants that meet stringent fire safety standards, such as those for public transport and high-rise buildings, opens new architectural markets.
Industry Challenges
- Capital Expenditure:Significant investment is needed to build and qualify large-scale extrusion lines capable of producing wide, thick foam boards required by wind blade manufacturers.
- Certification Timelines:The long and expensive process of obtaining certifications for use in regulated industries like aerospace and rail delays market entry for new products.
- Supply Chain Security:Establishing reliable, long-term contracts for high-quality, pre-sorted rPET flake is a critical operational hurdle for ensuring consistent production output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Foam Market |
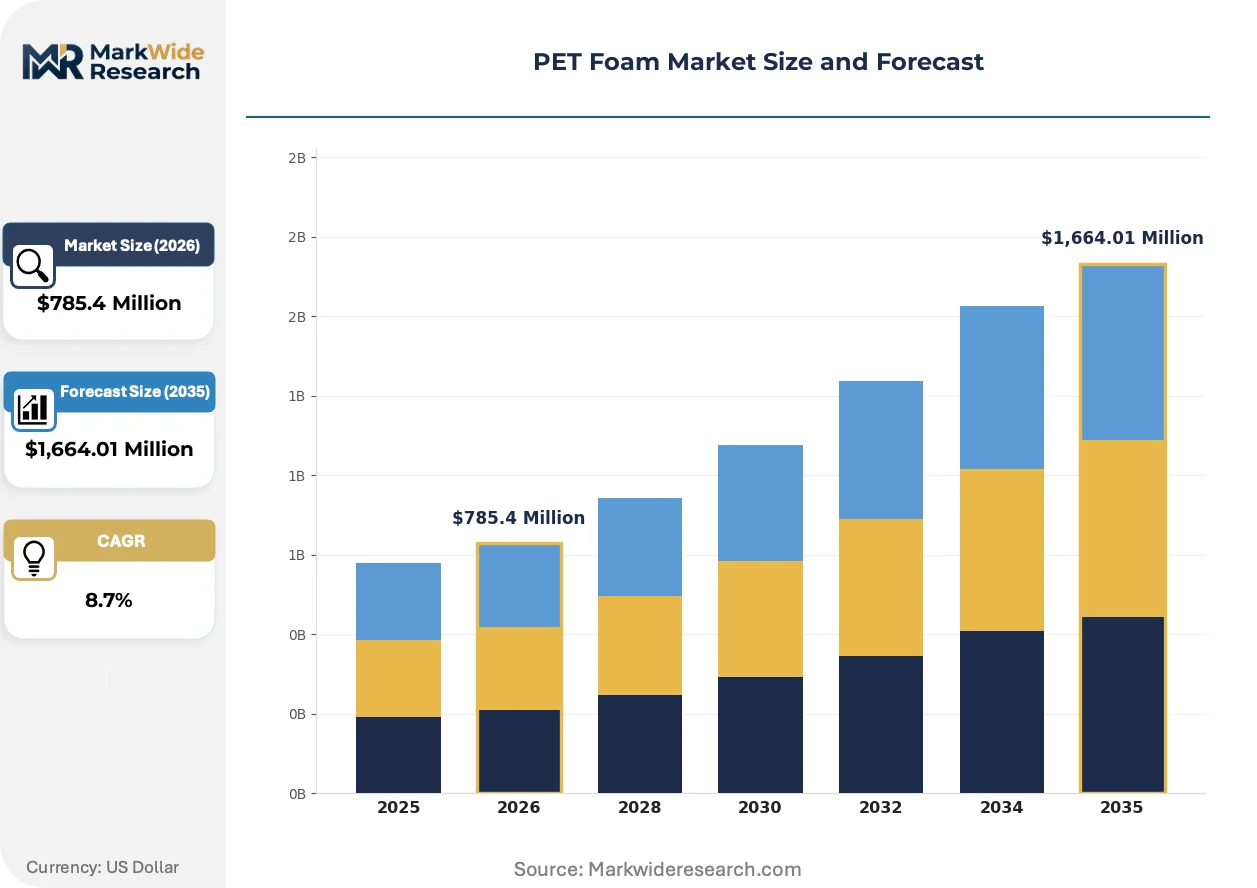
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,664.01 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate Sheets, Expanded PET, Extruded PET, Closed-cell PET, Open-cell PET Application: Packaging Materials, Construction Panels, Automotive Components, Sports Equipment, Consumer Electronics End User Industry: Consumer Goods Manufacturers, Construction Contractors, Vehicle Assemblers, Sports Goods Producers, Electronics Fabricators Form: Rigid Foam, Flexible Foam, Composite Foam, Laminated Foam, Sheet Foam |
| Companies Covered | Armacell, 3A Composites, Diab Group, Gurit Holding, Sekisui Chemical, Huntsman International, Changzhou Tiansheng New Materials, Carbon-Core Corp, CoreLite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Foam Market Strategic Shifts & Innovations
The industrialization of PET foam production is reshaping the supply base. A shift from specialized, smaller-batch manufacturing to high-volume, automated production is underway, driven by OEM requirements for certified, sustainable structural materials at scale.
High-density, closed-cell PET foam formulations provide superior strength-to-weight ratios for demanding structural composites. Wind turbine and automotive OEMs are rapidly adopting these advanced materials for critical load-bearing components. This technology is consolidating the material choice for large composite structures, displacing less durable or heavier alternatives.
EU mandates under the Circular Economy Action Plan, part of the European Green Deal, establish ambitious targets for recycled content in key products. This policy directly incentivizes the substitution of virgin plastics with materials like rPET foam. The building and construction sector is most affected, with producers now developing certified foam core panels to meet new green building codes.
A shift in buyer criteria from simple material cost to total lifecycle performance is evident. This change disrupts the traditional component-based procurement model, favoring suppliers who can validate long-term durability and recyclability. The trend is most pronounced in Germany's automotive supply chain and across wind energy projects in Northern Europe.
PET Foam Market Segmentation
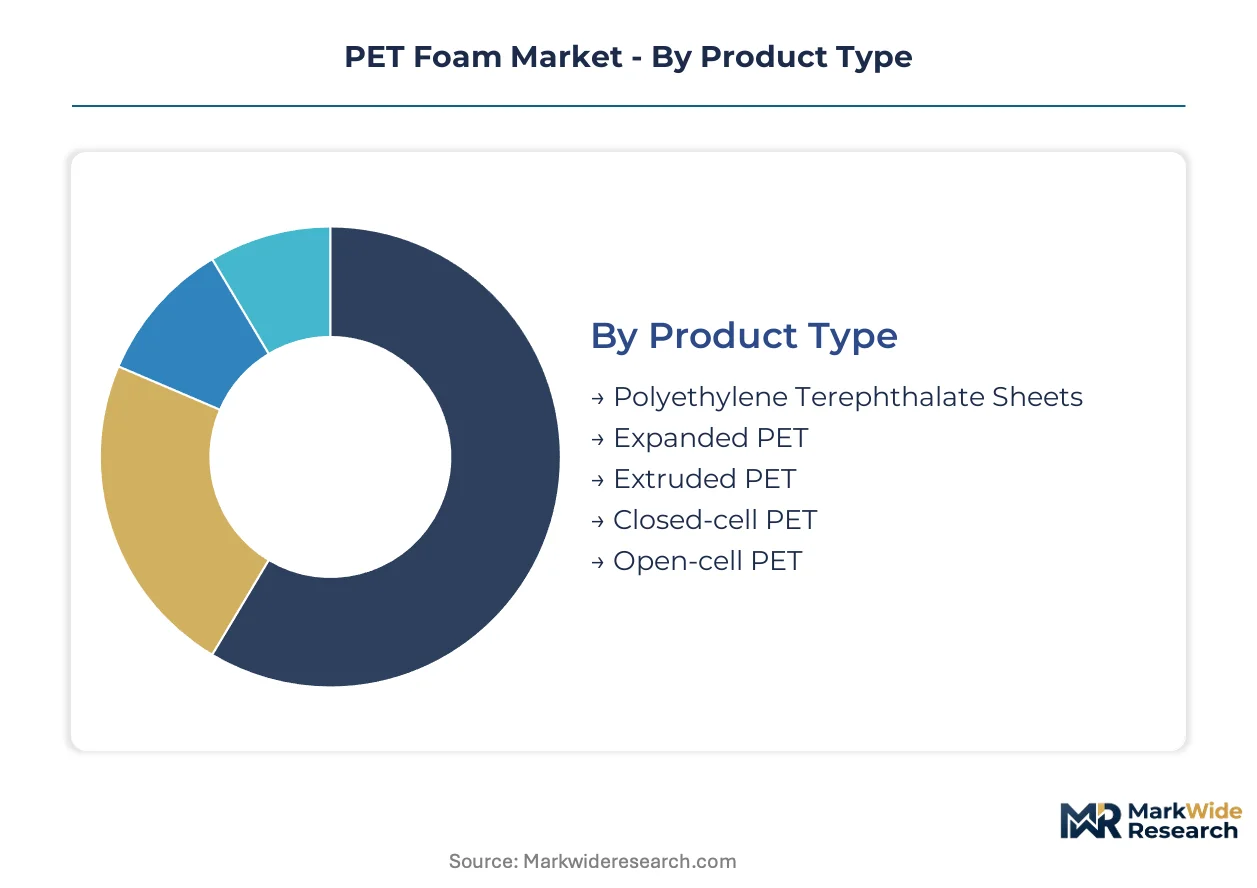
The PET foam market is categorized by distinct product forms, applications, and end-user industries, each presenting unique investment requirements and growth trajectories. Understanding these segments is crucial for manufacturers to align production capabilities with specific demand profiles and for buyers to source materials optimized for their operational needs. Strategic market participation hinges on precise segment targeting.
Product Type:
Capital intensity heavily influences the production of various PET foam product types, with advanced extrusion and expansion technologies requiring significant upfront investment.
- Extruded PET:This process creates continuous sheets or blocks of foam with consistent cell structure and density. Demand concentrates in wind energy, where large-format boards are critical for blade core materials, driven by the need for high fatigue resistance.
- Closed-cell PET:Characterized by isolated cells, this foam offers superior strength-to-weight ratios and minimal water absorption. Its demand is increasing in structural composites for automotive lightweighting, propelled by electric vehicle range extension goals.
- Polyethylene Terephthalate Sheets:These serve as foundational materials for further processing into foam or as thin, rigid panels in less demanding applications. Construction projects in Germany utilize these sheets for insulation and non-load-bearing partitions.
- Expanded PET:Produced through a batch process, expanded PET foam offers a balance of mechanical properties and cost-effectiveness. Packaging solutions for consumer goods in China frequently employ this material for protective inserts.
- Open-cell PET:Featuring interconnected cells, this variant is typically used where breathability or acoustic absorption is desired. Furniture manufacturers in Europe incorporate open-cell PET for cushioning and sound dampening.
Extruded PET absorbs the bulk of installed capacity; Closed-cell PET is expanding most quickly.
Application:
Performance demands vary significantly across applications, guiding material specifications and procurement strategies for PET foam.
- Automotive Components:PET foam is used for lightweighting vehicle structures, battery enclosures, and interior panels. Demand is accelerating due to stringent emissions regulations and the push for electric vehicle efficiency across European OEMs.
- Construction Panels:This application involves using PET foam as a core material in structural insulated panels and facade elements. Green building codes in the EU are driving its adoption for enhanced thermal performance and sustainability.
- Packaging Materials:PET foam provides protective cushioning and insulation for various goods, particularly in temperature-sensitive or fragile product categories. E-commerce logistics in the US increasingly rely on lightweight PET foam for reduced shipping costs.
- Sports Equipment:High strength-to-weight ratio and impact resistance make PET foam suitable for items like skis, surfboards, and protective gear. Manufacturers in Japan utilize PET foam to enhance product durability and user performance.
- Consumer Electronics:PET foam finds use in internal structural supports, housings, and thermal management solutions for electronic devices. South Korean electronics fabricators integrate PET foam for its dielectric properties and lightweight design.
Demand for Automotive Components drives significant material innovation; Construction Panels presents substantial growth potential.
End User Industry:
Different end-user industries exhibit distinct procurement patterns and material requirements, influencing supplier relationships and product development.
- Vehicle Assemblers:Major automotive OEMs require high-volume, certified PET foam components with consistent mechanical properties. German vehicle manufacturers are consolidating suppliers who can meet strict quality and sustainability standards for EV platforms.
- Construction Contractors:These entities procure PET foam for large-scale infrastructure projects and commercial buildings. Projects in Scandinavia emphasize materials with high insulation values and long lifecycle performance.
- Consumer Goods Manufacturers:Companies producing packaged goods utilize PET foam primarily for protective and insulating packaging solutions. Brand owners in North America seek cost-effective and recyclable foam options for their product lines.
- Sports Goods Producers:Specialized manufacturers integrate PET foam into high-performance equipment requiring specific strength and weight characteristics. European sports brands collaborate with foam producers for custom material formulations.
- Electronics Fabricators:Firms assembling electronic devices use PET foam for internal structural support, vibration dampening, and thermal management. Asian electronics companies prioritize foam solutions that offer compact design and electromagnetic compatibility.
Vehicle Assemblers emphasize long-term supply contracts; Construction Contractors are increasingly seeking sustainable material solutions.
Form:
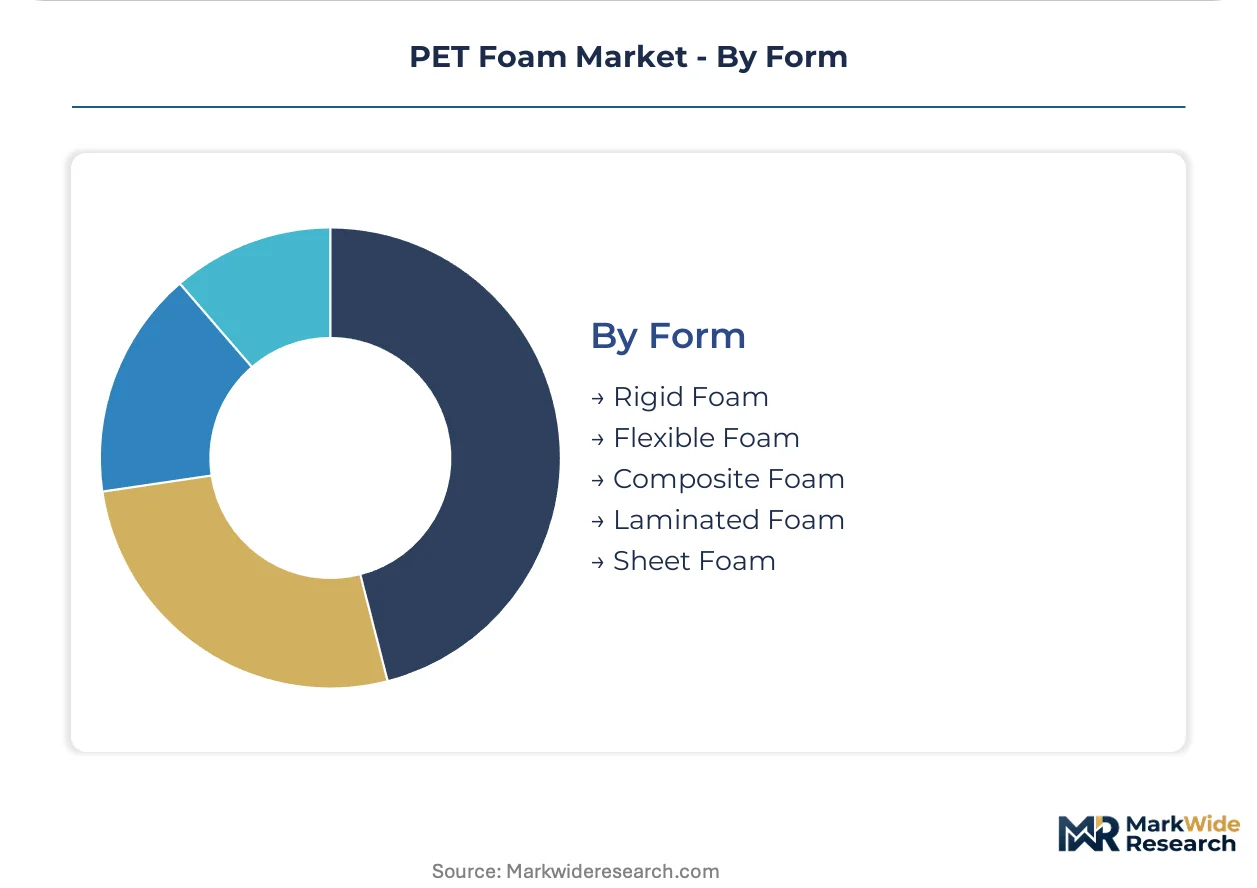
The physical form of PET foam dictates its suitability for various structural and non-structural applications, with rigid forms dominating load-bearing uses.
- Rigid Foam:This predominant form offers high compressive strength and stiffness, making it ideal for load-bearing composite structures. Wind turbine blade manufacturers in Denmark rely on rigid PET foam for its structural integrity.
- Composite Foam:These products combine PET foam with other materials to achieve enhanced multi-functional properties, such as improved fire resistance or bonding characteristics. Aerospace applications in France utilize composite foams for specialized panels.
- Sheet Foam:Supplied in large, flat panels, sheet foam provides a versatile core material for various sandwich constructions. Building material suppliers in the US distribute PET sheet foam for wall and roof insulation.
- Flexible Foam:Offering pliability and cushioning, flexible PET foam is used in applications requiring conformability rather than high structural rigidity. Automotive interiors in Japan incorporate flexible PET foam for comfort and noise reduction.
- Laminated Foam:This form involves PET foam bonded with other layers, such as fabric or film, to add specific surface properties or improve adhesion. Packaging companies in China use laminated PET foam for aesthetic and protective benefits.
Rigid Foam holds the largest market share due to its versatility; Composite Foam is undergoing rapid innovation for specialized uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for PET foam is evident in regions with robust manufacturing and renewable energy sectors. These areas prioritize advanced materials for lightweighting and circular economy initiatives. Global manufacturing clusters drive the need for certified, high-performance structural foam.
Germany
German automotive OEMs and construction projects demand high-performance PET foam for lightweight components and insulated panels. The EU Green Deal and national green building codes incentivize sustainable material choices. Industrial clusters in Bavaria and North Rhine-Westphalia are hubs for advanced materials engineering and production.
China
China's ambitious wind energy expansion and electric vehicle production drive significant PET foam demand for turbine blades and battery enclosures. The country's dual carbon goals promote energy-saving applications and material circularity. Manufacturing centers in the Yangtze River Delta concentrate production capacity for large-format foam boards.
United States
United States e-commerce logistics and infrastructure projects require PET foam for protective packaging and construction applications. EPA regulations on blowing agents influence material formulation and manufacturing processes. The Southeast manufacturing corridor sees increasing investment in advanced materials production for transportation and building sectors.
India
India's growing renewable energy sector and domestic manufacturing initiatives increase demand for PET foam in wind turbine components. The national PLI scheme supports local production of advanced materials for key industries. Gujarat and Tamil Nadu are emerging as manufacturing hubs for composite materials and automotive parts.
PET Foam Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-specification structural applications and sustainable material innovation. The competitive landscape features a tiered structure, including broad portfolio providers and specialized composite material suppliers. Strategic archetypes include diversified foam manufacturers, advanced composite specialists, and circular economy solution providers. Dominant competitive moves involve capacity expansion and strategic partnerships to secure feedstock and market access.
Specialists in advanced composite solutions include Gurit Holding, focusing on high-performance applications across wind and marine sectors. Diab Group leverages its extensive expertise in sandwich composite technology for critical structural components. Armacell, a multinational company, offers a broad portfolio of engineered foams, serving diverse insulation and structural uses globally. These companies exemplify the strategic differentiation within the PET foam market, catering to specific performance requirements and end-user demands.
| Leading Market Players |
|---|
| Armacell |
| 3A Composites |
| Diab Group |
| Gurit Holding |
| Sekisui Chemical |
| Huntsman International |
| Changzhou Tiansheng New Materials |
| Carbon-Core Corp |
| CoreLite |
Cost & Logistics Intelligence
The performance-grade certification ladder represents a key divergence, manifesting in distinct pricing structures for specialized versus commodity PET foam and shaping the supply chain configurations for each. High-performance structural applications demand certified materials, influencing procurement patterns and supplier relationships.
Pricing Analysis
Volume-driven applications like packaging often operate on tighter margins, while high-performance structural applications command premium pricing. The dominant pricing model for large-volume PET foam is contract-based long-term offtake, particularly for wind energy and automotive OEMs. Price differentiation stems from certification levels required by regulated industries and the degree of customization for specific applications. Pricing softness in packaging materials reflects intense competition from alternative core materials. Wind energy and automotive OEMs exhibit lower price sensitivity, prioritizing performance and reliability over cost.
Supply Chain Analysis
Logistics and freight costs significantly influence regional supply chain viability, especially for large-format PET foam boards. Geographic supply concentrates in industrial clusters within China and Germany, which serve global markets. The supply chain for PET foam draws heavily from post-consumer PET bottles, making rPET flake a critical raw material dependency. Feedstock volatility, driven by price and quality fluctuations in recycled PET, presents a structural supply chain risk. Distribution runs through direct sales channels for major OEMs and specialized distributors for smaller construction and packaging clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is poised for consolidation, with high capital expenditure requirements for advanced extrusion lines forcing out less capitalized players.
For Market Incumbents: Hedge against feedstock volatility by securing long-term contracts for high-quality rPET flake and investing in advanced chemical recycling technologies. Expand capacity in strategic industrial clusters like China and Germany to meet escalating demand from wind energy and automotive OEMs. Prioritize certification investment for new high-performance grades to counter substitution threats from lower-cost alternatives in less demanding applications.
For New Entrants and Emerging Players: A price-point gap exists between premium certified structural foams and commodity packaging materials, offering entry opportunities. Target niche applications like fire-retardant grades for architectural markets or specialized lightweight EV components. The Indian market, supported by the PLI scheme, presents a penetrable geography for local production. Focus on a value-based go-to-market angle, emphasizing specific performance benefits and lifecycle advantages.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized composite material suppliers given the increasing demand for sustainable, high-performance structural materials. The long-term viability of PET foam is strong, driven by circular economy mandates and renewable energy infrastructure growth. Target acquisition archetypes include firms with patented recycling technologies or advanced high-volume extrusion capabilities. Successful commercialization of chemical recycling for structural rPET foam is a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meeting growing demand from wind energy and automotive OEMs is critical for market share. |
| Backward Integration | Securing consistent supply of high-quality rPET feedstock stabilizes production costs and quality. |
| Joint Venture | Developing fire-retardant grades opens new architectural and public transport markets. |
| Certification Investment | Obtaining approvals for regulated industries like aerospace accelerates market entry for new products. |
| Green Manufacturing Transition | Aligning production with EU Green Deal mandates enhances market access and brand perception. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a robust foundation for market sizing and trend analysis. The methodology combined extensive primary interviews with industry stakeholders such as wind turbine blade engineers, automotive material procurement leads, rPET feedstock suppliers, and construction panel manufacturers. Secondary data sources included EU Green Deal policy documents, EPA regulations, China's dual carbon goals, and composite materials industry reports, all triangulated with bottom-up and top-down validation.
Granularity-level modeling covered product forms, applications, end-user industries, and regional production clusters, allowing for detailed segment analysis. The analytical framework projected market growth across the analysis window, with CAGRs derived from historical trends, anticipated technology adoption rates, and projected regulatory impacts. Key industry-specific forecast inputs included renewable energy project pipelines and electric vehicle production forecasts, directly influencing demand projections.
Underlying measurement precision varies by segment; established applications like construction panels carry tighter precision than emerging uses such as electric vehicle battery enclosures. Forecasts reflect assumptions on market dynamics, including feedstock availability and evolving regulatory landscapes. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
C5 Resin Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Polymer Seals Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Polymer Binders Market
Polymers & Resins
Global Polyethyleneimine Market