
 Polybutene-1 Market | 2026-2036
Polybutene-1 Market Size, Share, and Industry Trends Forecast 2026-2036
Polybutene-1 Market Analysis
High-purity extrusion-grade specifications are reorganizing competitive dynamics across the Polybutene-1 landscape. LyondellBasell Industries NV leverages its integrated polyolefin platform to secure feedstock advantages in North American specialty grades. Mitsui Chemicals Inc. anchors Asia-Pacific supply through dedicated butene-1 monomer streams and localized compounding operations. Borealis AG differentiates via catalyst technology leadership in high-molecular-weight copolymer variants.
Polybutene-1 is a semi-crystalline thermoplastic polyolefin produced through Ziegler-Natta or metallocene polymerization of butene-1 monomer, exhibiting superior creep resistance, thermal stability, and flexibility compared to conventional polyethylene. Its primary commercial purpose centers on hot-water piping systems, pressure-rated tubing, and flexible packaging films requiring long-term mechanical integrity under thermal stress. Homopolymer formulations command the dominant volume share in potable water infrastructure due to established certification pathways and decades of field performance data. Copolymer and modified grades represent the fastest-expanding margin pools, particularly in automotive under-hood applications and medical packaging where EMA and FDA biocompatibility standards apply. Blends remain a niche but strategically significant category for converters seeking cost-performance optimization in non-critical film and adhesive layers.
REACH registration requirements and the EU F-Gas Regulation shape material qualification timelines for European suppliers, while China's GB standards and NMPA medical device rules govern import access and clinical-grade certification. The US EPA and FDA jointly influence potable water and food-contact applications through NSF/ANSI 61 and 21 CFR 177.1520 compliance frameworks. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as regulatory pressure on fluorinated alternatives creates substitution opportunities for polyolefin barrier systems in high-performance packaging.
Market Dynamics
Construction-grade piping specifications are tightening across emerging economies, forcing converters to qualify higher-purity extrusion grades and reshaping procurement relationships with resin suppliers.
Growth Catalysts
- REACH and EU Green Deal mandates:ECHA registration requirements and carbon-neutral infrastructure targets accelerate substitution from metal piping toward durable thermoplastic alternatives in municipal water systems.
- China's municipal water renewal programs:Provincial infrastructure funds channel investment into pressure-rated polymer distribution networks, creating concentrated demand for certified homopolymer grades.
- Metallocene catalyst advances:Next-generation polymerization technology enables narrower molecular-weight distribution, improving creep resistance for hot-water applications without compounding modifications.
Market Restraints
- Butene-1 monomer supply concentration:Feedstock availability concentrates among integrated petrochemical complexes, exposing compounders to price volatility when cracker maintenance cycles tighten.
- Polyethylene cost-performance parity:Conventional PE-RT and cross-linked polyethylene alternatives capture specification share in residential plumbing where thermal stress margins allow material downgrading.
- GB standard certification timelines:China's SAMR testing protocols for potable water contact extend qualification cycles, delaying market access for new copolymer formulations.
Strategic Opportunities
- Southeast Asian residential construction corridors:Vietnam and Indonesia's urban housing expansion lacks established polymer specification lock-in, opening territory for PB-1 piping system adoption.
- Automotive under-hood fluid management:Thermal stability requirements for electric vehicle battery cooling circuits create specification entry points for high-molecular-weight copolymer grades.
- Medical packaging barrier migration:FDA and EMA pressure on fluorinated polymer alternatives accelerates polyolefin substitution in pharmaceutical blister and pouch applications.
Industry Challenges
- Certification pathway fragmentation:NSF/ANSI 61, KTW, and WRAS potable water approvals require parallel testing investments, straining R&D budgets for mid-scale compounders.
- Skilled polymer processing labor scarcity:Extrusion technicians with PB-1-specific rheology expertise concentrate among legacy European and Japanese equipment operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polybutene-1 Market |
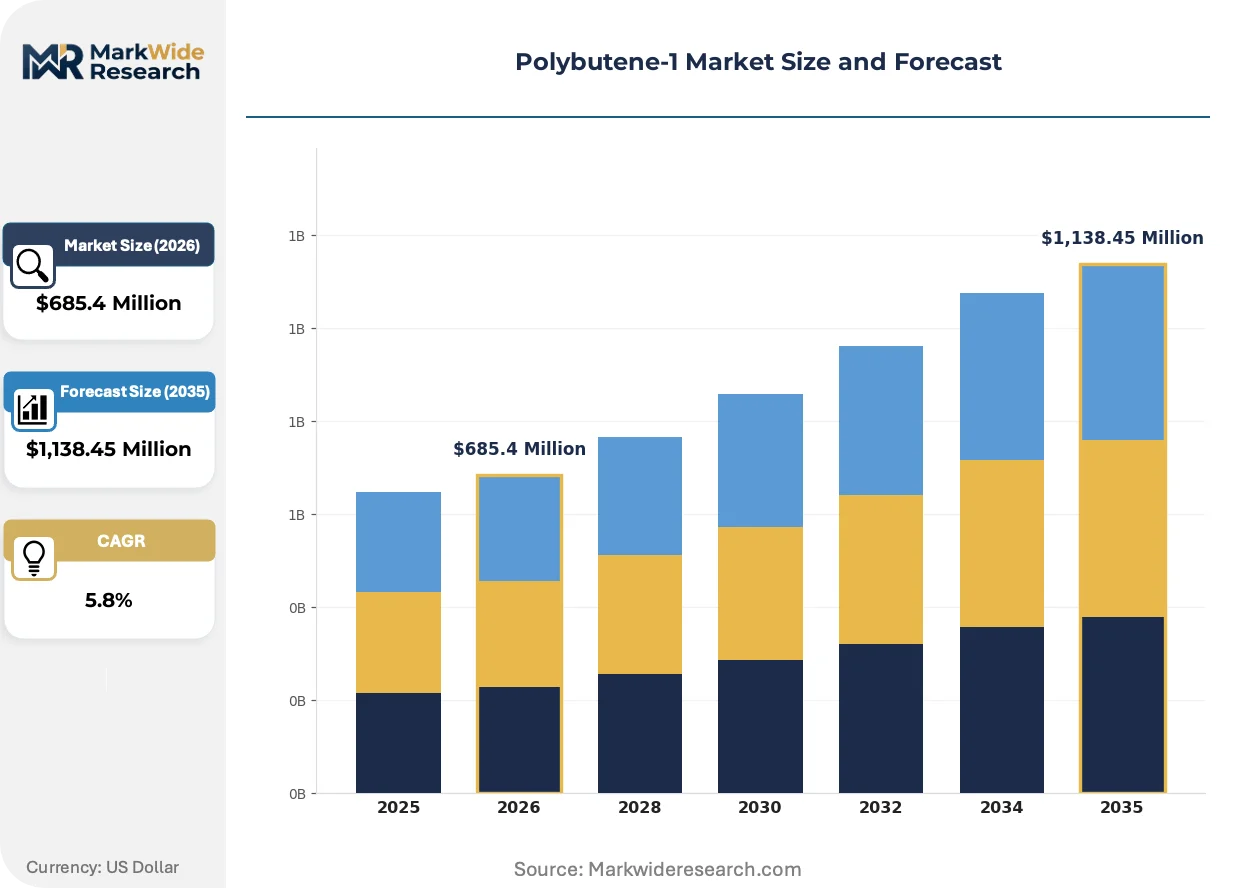
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Blends, Modified Application: Piping Systems, Adhesives, Cables, Films End User: Construction, Automotive, Packaging, Healthcare Distribution Channel: Online Retail, Direct Sales, Distributors, Retail Stores |
| Companies Covered | Mitsui Chemicals Inc., Formosa Plastics Corporation, LyondellBasell Industries NV, Ylem Technology Co. Ltd., Chevron Phillips Chemical Company LLC, BASF SE, Braskem S.A., Shandong Hongye Chemical, Borealis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polybutene-1 Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reposition polyolefin performance grades within specification hierarchies previously dominated by engineering polymers and metal systems.
Metallocene single-site catalyst technology is decomposing the traditional trade-off between processability and mechanical performance in high-purity PB-1 grades. Automotive thermal management suppliers in Germany and Japan are qualifying these materials for battery cooling lines at accelerated cycles. The technology is decomposing incumbent nylon and rubber hose positions in under-hood fluid routing by matching thermal cycling durability at lower system weight.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are compressing availability of high-barrier polymer alternatives for pharmaceutical packaging. EMA guidance documents now explicitly favor non-fluorinated barrier structures in new drug applications. Medical device manufacturers in Switzerland and Ireland are reformulating blister packs around polyolefin coextrusions to preempt regulatory disqualification.
Specification-driven procurement now dominates infrastructure polymer selection in China's tier-one cities. Municipal engineering departments in Shanghai and Shenzhen have centralized material pre-qualification databases, eliminating trial-based supplier entry. This concentration forces compounders to front-load certification investment before volume allocation, privileging established multinationals with existing testing relationships.
Polybutene-1 Market Segmentation
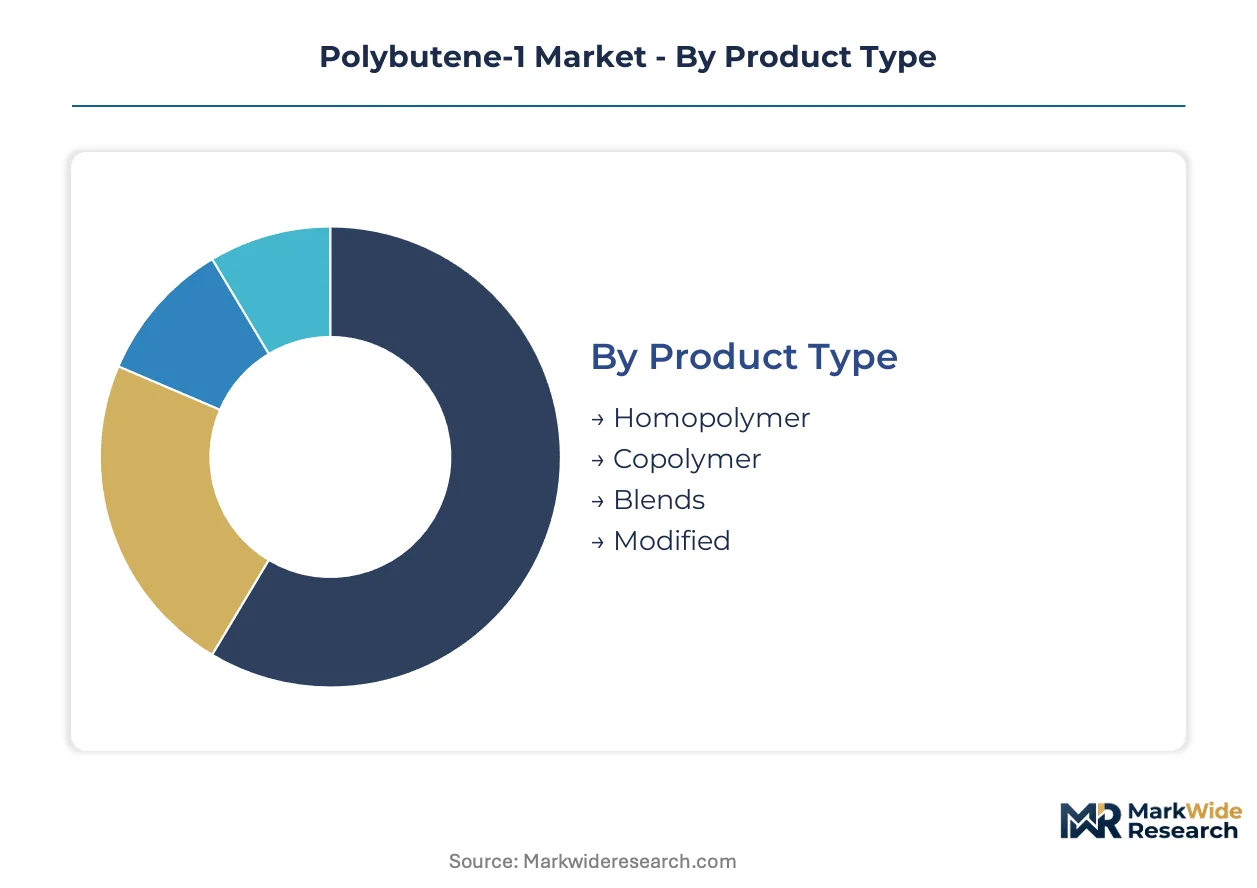
Polybutene-1 procurement patterns diverge sharply across specification tiers, with certified grades commanding qualification premiums while commodity blends compete on converter economics. Segmentation discipline separates infrastructure-grade suppliers from packaging-focused compounders.
Product Type:
REACH registration tiers and NSF/ANSI 61 certification pathways create distinct commercial strata among polymer architectures.
- Homopolymer:Linear isotactic chains deliver maximum crystallinity and creep resistance for pressure-rated piping. China's municipal water renewal programs concentrate procurement of certified homopolymer grades from pre-qualified supplier databases in Shanghai and Shenzhen.
- Copolymer:Random ethylene incorporation reduces crystallization temperature while maintaining thermal stability. Automotive under-hood fluid management in Germany and Japan drives specification of high-molecular-weight copolymers for battery cooling circuits.
- Blends:Cost-performance optimization for non-critical film layers and adhesive formulations.
- Modified:Grafted or compounded variants targeting medical packaging biocompatibility under EMA and FDA frameworks.
Homopolymer handles the majority of throughput; copolymer is the fastest mover on share.
Application:
End-use thermal stress profiles determine margin capture, with continuous-load infrastructure applications outperforming intermittent-use segments.
- Piping Systems:Hot-water distribution networks and pressure-rated tubing dominate volume consumption. Southeast Asian residential construction corridors in Vietnam and Indonesia lack specification lock-in, opening territory for PB-1 system adoption against incumbent materials.
- Films:Flexible packaging requiring long-term mechanical integrity under thermal stress. EU F-Gas Regulation restrictions on fluorinated barriers accelerate polyolefin substitution in pharmaceutical blister applications.
- Adhesives:Tackifier and sealant formulations leveraging PB-1's oxidative stability.
- Cables:Insulation and jacketing for high-temperature electrical applications.
Piping systems absorb the dominant share of resin volume; films are climbing the fastest on specification migration.
End User:
Customer technical capabilities separate specification-driven procurement from price-elastic volume buying.
- Construction:Municipal engineering departments and residential developers with centralized pre-qualification databases. China's SAMR testing protocols for potable water contact extend qualification cycles, delaying access for new formulations.
- Packaging:Medical device manufacturers reformulating around non-fluorinated barrier structures to preempt EMA disqualification.
- Automotive:Thermal management suppliers qualifying materials for electric vehicle battery cooling at accelerated test cycles.
- Healthcare:Sterile barrier systems requiring FDA 21 CFR 177.1520 and biocompatibility certification.
Construction commands the largest installed base; packaging is gaining share fastest on regulatory substitution.
Distribution Channel:
Channel economics reflect lot-size requirements and technical service intensity across customer tiers.
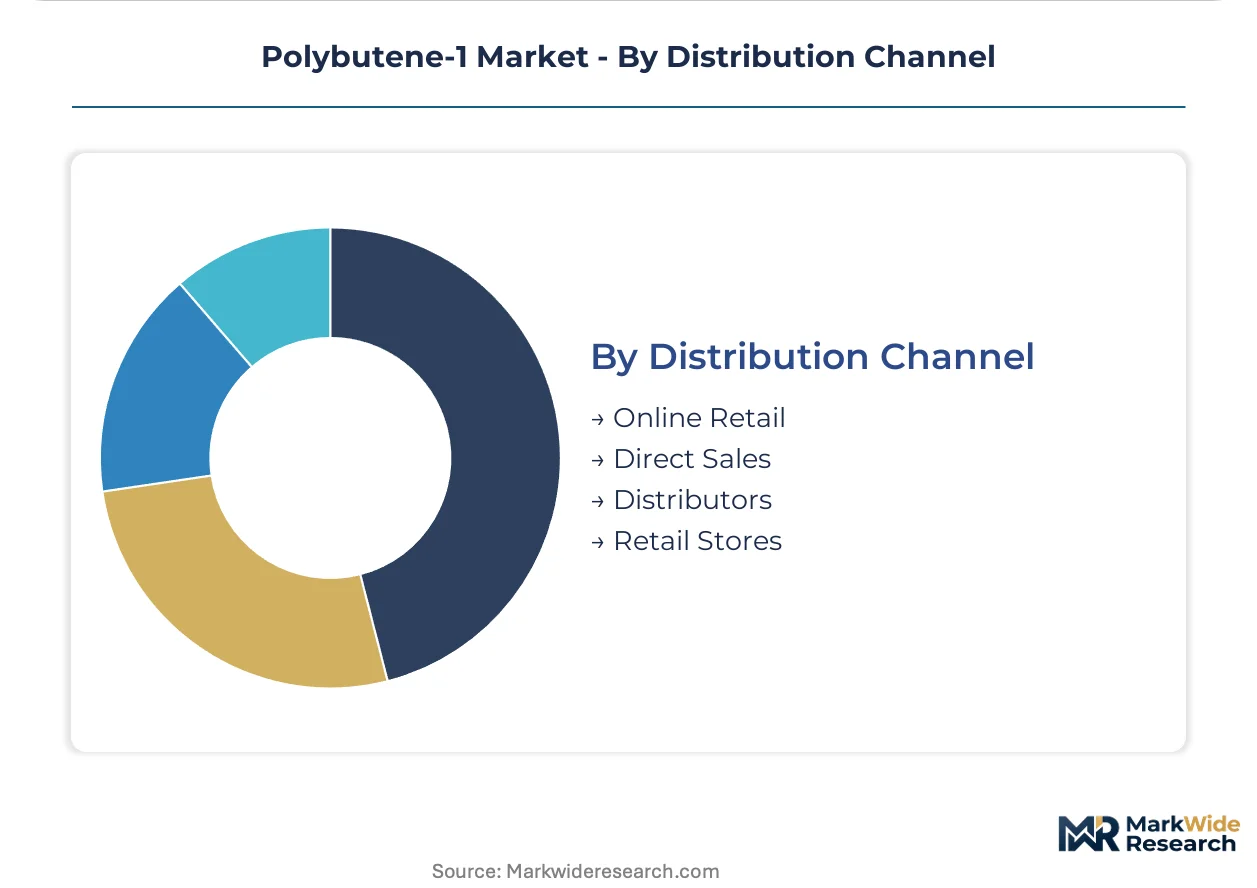
- Direct Sales:Volume accounts with dedicated technical service for extrusion-grade qualification. Integrated petrochemical complexes leverage captive butene-1 monomer streams to secure feedstock-advantaged direct relationships.
- Distributors:Regional stocking for mid-scale compounders lacking warehouse infrastructure.
- Online Retail:Small-lot specialty grades and modified formulations for R&D sampling.
- Retail Stores:Limited penetration given bulk handling requirements and specification complexity.
Direct sales channels move the bulk volume; distributor networks are expanding most quickly on geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feedstock availability concentrates among integrated petrochemical complexes in East Asia and the Middle East, creating supply advantages for producers with captive butene-1 monomer streams. China, Germany, Japan, Saudi Arabia, and the United States anchor regional demand through infrastructure renewal and automotive thermal management programs.
China
Municipal water infrastructure renewal programs in Shanghai and Shenzhen concentrate procurement of certified homopolymer grades through centralized pre-qualification databases. SAMR testing protocols for potable water contact extend qualification cycles under GB standards, delaying market access for new copolymer formulations. Yangtze River Delta compounders supply extrusion-grade resin for provincial pressure-rated distribution networks.
Germany
Automotive thermal management suppliers qualify high-molecular-weight copolymers for electric vehicle battery cooling circuits at accelerated test cycles. REACH registration requirements and the EU F-Gas Regulation shape material qualification timelines for pharmaceutical packaging applications. Bavarian compounders develop metallocene-grade formulations for under-hood fluid routing systems.
Japan
Metallocene catalyst technology advances enable narrower molecular-weight distribution for hot-water piping applications without compounding modifications. METI industrial standards govern pressure-rated tubing certification for residential construction markets. Osaka-based processors supply specialized grades for medical packaging biocompatibility under PMDA frameworks.
Saudi Arabia
Integrated petrochemical complexes leverage captive feedstock streams to secure cost advantages in extrusion-grade resin production. Domestic infrastructure investment programs create specification opportunities for pressure-rated polymer distribution networks. Eastern Province producers export homopolymer grades to Southeast Asian residential construction corridors.
United States
NSF/ANSI 61 compliance frameworks govern potable water applications, while FDA 21 CFR 177.1520 rules shape food-contact and medical packaging specifications. EPA regulations jointly influence material selection for infrastructure polymer systems. Gulf Coast petrochemical clusters supply North American specialty grades through direct technical service relationships.
Polybutene-1 Market Vendor Landscape
Concentration sits with integrated petrochemical multinationals controlling captive butene-1 monomer supply and catalyst technology platforms. The vendor base separates into three tiers: global resin producers with full backward integration into feedstock, regional compounders specializing in certified infrastructure grades, and niche formulators serving medical and automotive qualification pathways. Dominant competitive moves include strategic partnerships for metallocene catalyst licensing and capacity expansion in high-purity extrusion-grade segments.
Within the integrated multinational tier, Mitsui Chemicals Inc., LyondellBasell Industries NV, and Borealis AG exemplify archetypes spanning Asia-Pacific supply anchoring, North American feedstock integration, and European catalyst leadership respectively. These positions reflect geographic concentration of butene-1 production and qualification pathway expertise rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| Mitsui Chemicals Inc. |
| Formosa Plastics Corporation |
| LyondellBasell Industries NV |
| Ylem Technology Co. Ltd. |
| Chevron Phillips Chemical Company LLC |
| BASF SE |
| Braskem S.A. |
| Shandong Hongye Chemical |
| Borealis AG |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between integrated petrochemical producers and municipal infrastructure contractors lock in both butene-1 monomer supply access and multi-year price visibility across China's Yangtze River Delta and Germany's Bavarian compounding clusters. These contract structures insulate qualified suppliers from spot market volatility while forcing compounders to front-load certification investment before volume allocation.
Pricing Analysis
REACH registration tiers dictate the pricing tier structure across European extrusion-grade markets. Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI 61-certified homopolymer from uncertified commodity grades and modified medical formulations. Cost compression in standard-grade piping runs through polyethylene cost-performance parity as PE-RT alternatives capture residential specification share. Municipal engineering departments in China's tier-one cities demonstrate least price sensitivity due to centralized pre-qualification databases, while Southeast Asian residential developers show highest elasticity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes compound feedstock delivery uncertainty for non-integrated compounders sourcing butene-1 monomer. Production gravity centers on Saudi Arabia's Eastern Province, China's Yangtze River Delta, and the US Gulf Coast petrochemical clusters. Raw material dependencies rest on naphtha cracker outputs, metallocene catalyst precursors, and antioxidant stabilizer packages. Single-source vulnerability concentrates around butene-1 monomer supply from integrated complexes. Distribution runs through direct technical service relationships for volume accounts, with regional distributors covering mid-scale compounders lacking warehouse infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polybutene-1 suppliers face a substitution defense against cross-linked polyethylene and PE-RT alternatives in residential plumbing segments where thermal stress margins allow material downgrading. Incumbents must navigate this threat through certification moats and feedstock control.
For Market Incumbents: Secure captive butene-1 monomer streams through backward integration or long-term offtake with naphtha crackers in Saudi Arabia and China. Accelerate metallocene catalyst licensing partnerships to maintain creep resistance advantages against polyethylene substitutes. Certification investment in China's SAMR GB standards and EU REACH tiers builds procurement lock-in that new entrants cannot replicate quickly. For New Entrants and Emerging Players: Lead with uncertified copolymer grades for automotive under-hood battery cooling circuits in Germany and Japan, where specification lock-in remains incomplete and thermal management suppliers seek alternatives to nylon. Target Vietnam and Indonesia's residential construction corridors through distributor partnerships, leveraging absence of established polymer specification hierarchies. Position on metallocene-grade technical service rather than price undercutting. For Investors and Strategic Acquirers: Regional compounders with existing SAMR and WRAS certification pathways present the most defensible acquisition profile for exposure to China's municipal water renewal programs. Long-term viability hinges on feedstock-advantaged positioning within integrated petrochemical complexes rather than standalone compounding assets. Watch for inflection in EMA guidance on fluorinated barrier disqualification, which would accelerate polyolefin substitution timelines in pharmaceutical packaging.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butene-1 Monomer | Captive feedstock supply from Saudi Eastern Province crackers eliminates price volatility exposure. |
| Metallocene Catalyst Licensing Agreement | Narrower molecular-weight distribution from single-site technology displaces nylon in automotive thermal management. |
| Long-term Supply Agreement with Municipal Contractors | Pre-qualified supplier status in Shanghai and Shenzhen databases locks out unqualified competitors. |
| Certification Investment in SAMR GB Standards | Extended testing protocols create regulatory moats against faster polyethylene qualification cycles. |
| Joint Venture for Southeast Asian Distribution | Localized compounding in Vietnam and Indonesia bypasses logistics chokepoints on Asia-Europe lanes. |
Methodological Framework
Operator-level perspectives from extrusion plant managers, municipal procurement engineers, automotive thermal management suppliers, and medical device packaging directors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through customs/trade data, SEC 10-K filings from integrated petrochemical multinationals, and ECHA REACH registration databases. Bottom-up volume modeling across homopolymer, copolymer, and modified grade tiers triangulated against top-down infrastructure spending forecasts from China's provincial funds and EU Green Deal implementation trackers.
Sensitivity analysis tested forecast robustness across butene-1 monomer price volatility scenarios, polyethylene substitution elasticity parameters, and regulatory timeline acceleration under EU F-Gas restrictions. The analytical framework segmented by product architecture, application thermal stress profile, end-user technical capability, and distribution channel intensity across the projection horizon. Modeled inputs included construction-grade piping specification tightening rates, metallocene catalyst adoption curves, and automotive battery cooling content-per-vehicle trajectories.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure investment in China's tier-one cities, continued REACH enforcement stringency, and stable naphtha cracker operating rates would require recalibration. Forecasts reflect documented assumptions regarding certification pathway timelines and feedstock supply concentration. Recalibration cycles align with material shifts in EMA barrier guidance, SAMR testing protocol revisions, and metallocene catalyst technology licensing developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Global Styrenic Polymers Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Mixed-Mode Chromatography Resin Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Polyaryletherketone (PAEK) Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Bio-Sourced Nylon Market
Polymers & Resins
Biobased Thermosetting Polymers Market