
 Polyisobutene Market | 2026-2036
Polyisobutene Market Size, Share, and Industry Trends Forecast 2026-2036
Polyisobutene Market Analytics
Buyer concentration among automotive lubricant blenders is recalibrating procurement volumes across the polyisobutene value chain. BASF SE leverages its integrated C4 chemistry platform to secure backward integration into isobutene feedstock. ExxonMobil Corporation sustains manufacturing scale across its Baytown complex, dominating North American supply for high-viscosity grades. SIBUR competes through captive butene supplies at its Tobolsk site, anchoring cost positions in coating-grade output.
Polyisobutene comprises a class of synthetic hydrocarbon polymers produced via cationic polymerization of isobutene, with molecular weights spanning 500 to 5,000,000 g/mol depending on catalyst selection and reaction temperature. Low-viscosity grades below 1,000 g/mol function as primary base fluids in lubricant formulations and tackifier additives, while high-viscosity variants above 10,000 g/mol serve as permanent tackifiers in sealant and roofing membrane applications. The adhesive-grade segment leads volume consumption through pressure-sensitive tape and hot-melt formulations, though pharmaceutical-grade specifications command the strongest margin pools due to USP and EP compliance burdens. Coating-grade polyisobutene occupies a mature growth trajectory in corrosion-protection tapes, with demand tethered to pipeline infrastructure maintenance cycles.
REACH registration requirements enforced by ECHA govern polymer monomer residuals and impurity thresholds for all grades sold within Europe. EPA fuel and lubricant additive regulations under 40 CFR constrain volatile organic compound content in US-bound automotive formulations. FDA indirect food-contact clearances shape qualification pathways for adhesive grades deployed in food packaging laminates. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as these intersect with polyisobutene substitution strategies in grease and sealant formulations.
Market Dynamics
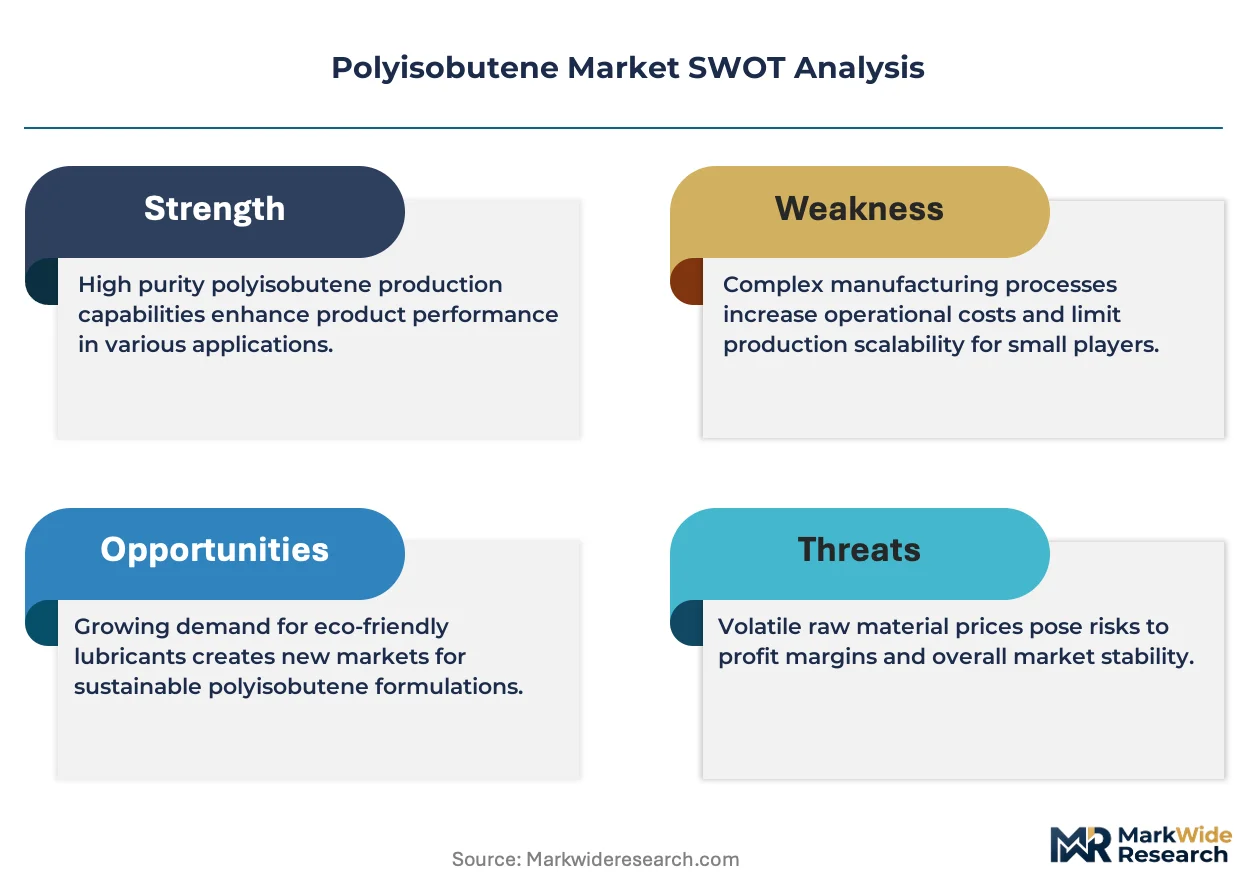
Automotive lubricant formulators are consolidating procurement around high-viscosity polyisobutene grades, compressing supplier margins while REACH and EU Green Deal mandates force purity upgrades across European production clusters.
Growth Catalysts
- REACH registration thresholds:ECHA mandates on monomer residuals are accelerating qualification of pharmaceutical-grade polyisobutene, opening premium margin pools for compliant producers.
- Fuel additive reformulation:EPA 40 CFR constraints on volatile organic compounds are expanding polyisobutene penetration in low-VOC engine oil packages across US refineries.
- Sealant-grade demand concentration:Roofing membrane and corrosion-tape maintenance cycles in pipeline infrastructure are sustaining coating-grade volume baselines.
Market Restraints
- Isobutene feedstock volatility:C4 olefin supply tightness from steam cracker rate cuts is compressing margin structures for non-integrated polymer producers.
- High-molecular-weight production concentration:Specialized high-viscosity capacity clusters in Germany and Texas create geographic supply risk for Asian formulators.
- Polyalphaolefin substitution:Synthetic base fluid alternatives in automotive lubricants are displacing low-viscosity polyisobutene in passenger car motor oil segments.
Strategic Opportunities
- India adhesive packaging growth:BIS certification pathways for food-contact laminates are opening qualification routes for adhesive-grade polyisobutene in flexible packaging.
- EU Green Deal biodegradability mandates:Regulatory pressure on polymer environmental persistence is creating first-mover advantage for producers with bio-attributed isobutene feedstock.
- Hot-melt formulation convergence:Pressure-sensitive tape producers are blending polyisobutene tackifiers with metallocene polyolefins, expanding compatible grade specifications.
Industry Challenges
- Cationic polymerization expertise scarcity:Operating high-viscosity reactor trains requires specialized process engineering talent concentrated at legacy production sites.
- USP and EP compliance timelines:Pharmaceutical-grade certification cycles extend 18-24 months, locking working capital and delaying market entry for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyisobutene Market |
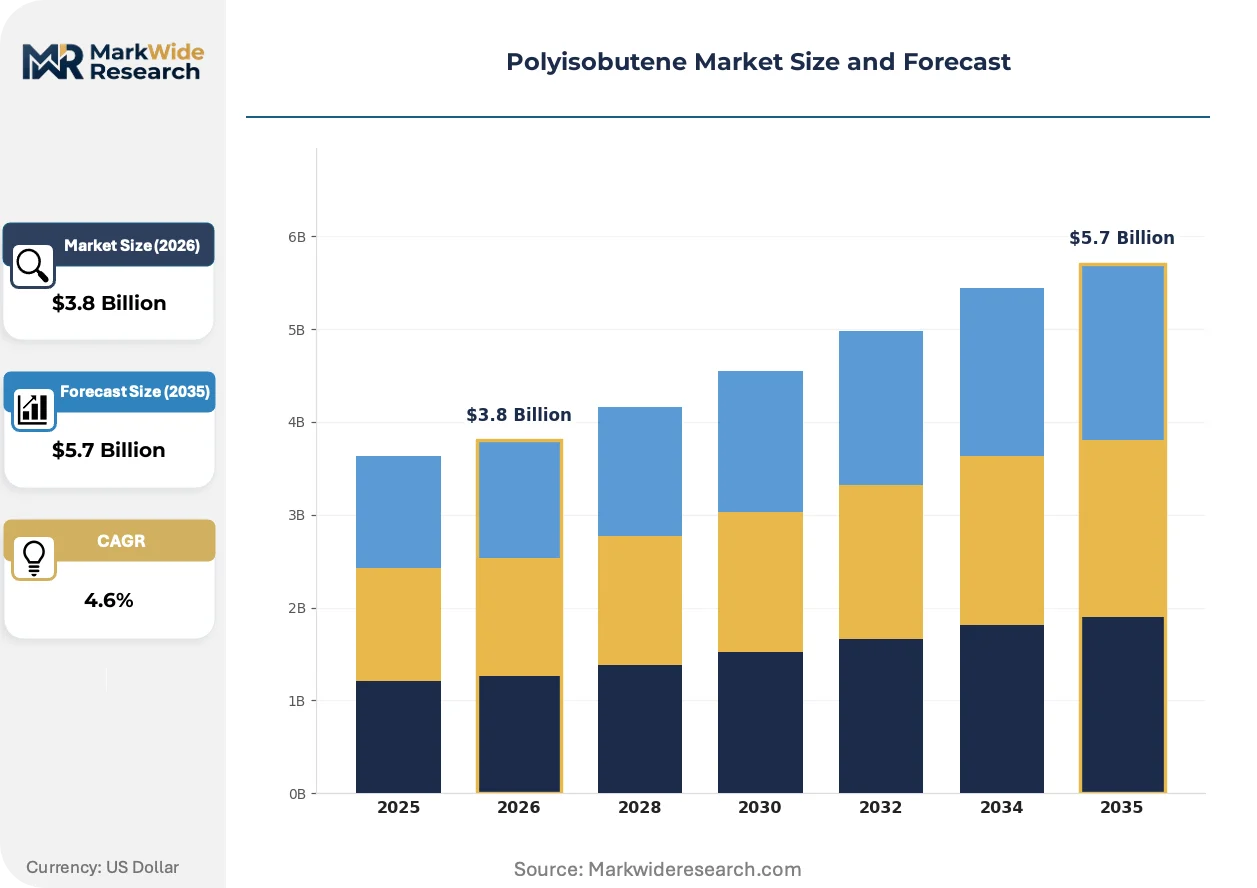
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Viscosity, Low Viscosity, Coating Grade, Adhesive Grade Application: Adhesives, Sealants, Lubricants, Coatings End User: Automotive, Construction, Personal Care, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | BASF SE, Lubrizol Corporation, TPC Group, LANXESS AG, INEOS, ExxonMobil Corporation, Daelim Co., Ltd., Reliance Industries, SIBUR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyisobutene Market Evolving Landscape
Process intensification and regulatory stringency are fragmenting competitive positions across molecular weight grades, with technology modularization and procurement centralization emerging as decisive vectors.
Reactor design advances in cationic polymerization are modularizing production economics for mid-viscosity grades between 1,000 and 10,000 g/mol. Regional compounders in Southeast Asia are adopting skid-mounted units to bypass centralized import dependencies. This modularization is compressing minimum efficient scale thresholds and enabling distributed supply footprints.
EU Green Deal circular economy mandates are forcing disclosure of polymer carbon intensity across the value chain. ECHA is expanding scope for polymer registration reviews, requiring lifecycle data from isobutene extraction through formulation. Adhesive-grade producers serving Continental packaging markets are accelerating mass-balance certification to maintain qualification status.
Automotive lubricant blenders are consolidating annual procurement volumes around fewer qualified suppliers, compressing spot market liquidity. Direct supply agreements with integrated C4 producers are displacing distributor-mediated transactions in North America and Europe. This concentration is most visible among multinational formulators with engine oil approvals from Mercedes-Benz and Volkswagen Group.
Polyisobutene Market Segmentation
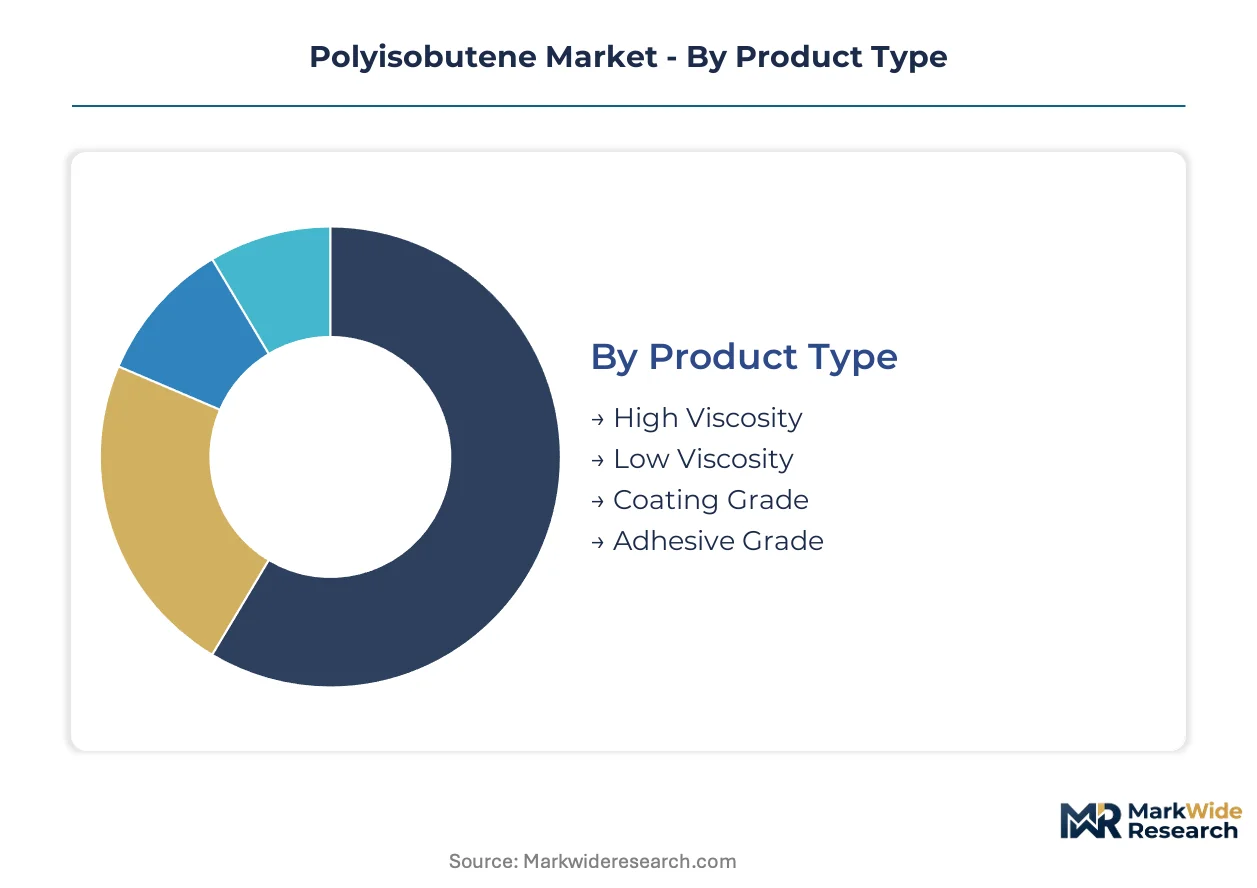
Polyisobutene producers face divergent capital requirements across molecular weight grades, with high-viscosity reactor trains demanding specialized cationic polymerization expertise and extended qualification timelines. Segmentation strategy determines which margin pools remain accessible to non-integrated compounders versus integrated C4 chemistry operators.
Product Type:
Capital intensity escalates steeply with molecular weight, as high-viscosity production requires precision temperature control and extended residence times that low-viscosity skid-mounted units bypass entirely.
- High Viscosity:Molecular weights exceeding 10,000 g/mol demand dedicated reactor infrastructure with cryogenic cooling systems and aluminum chloride catalyst recovery loops. Demand concentrates in Germany and Texas, where BASF SE and ExxonMobil Corporation anchor specialized clusters serving Continental tire manufacturers and roofing membrane formulators. REACH purity mandates are extending certification timelines for new capacity additions.
- Low Viscosity:Grades below 1,000 g/mol function as primary base fluids in lubricant formulations and fuel additive packages. Modular skid-mounted units in Southeast Asia are compressing minimum efficient scale thresholds, though polyalphaolefin substitution in passenger car motor oils is eroding volume growth in US and European automotive channels.
- Coating Grade:Corrosion-protection tape applications in pipeline infrastructure maintenance sustain mature demand baselines.
- Adhesive Grade:Pressure-sensitive tape and hot-melt formulations dominate volume consumption through flexible packaging laminates.
Most installed capacity flows through Adhesive Grade. Expansion is steepest in High Viscosity.
Application:
Application selection determines regulatory exposure, with pharmaceutical and food-contact pathways imposing compliance burdens that general industrial formulations avoid.
- Adhesives:Pressure-sensitive tape producers are blending polyisobutene tackifiers with metallocene polyolefins, expanding compatible grade specifications. FDA indirect food-contact clearances shape qualification pathways for adhesive grades deployed in food packaging laminates, with BIS certification in India opening additional routes.
- Lubricants:Automotive lubricant formulators are consolidating procurement around fewer qualified suppliers, compressing spot market liquidity. EPA 40 CFR constraints on volatile organic compounds are expanding polyisobutene penetration in low-VOC engine oil packages across US refineries.
- Sealants:Roofing membrane and construction-grade applications require permanent tackifier performance.
- Coatings:Pipeline infrastructure maintenance cycles sustain corrosion-tape demand baselines.
Volume concentrates in Adhesives. Value capture is strongest in Lubricants.
End User:
End-user concentration varies sharply by compliance tier, with pharmaceutical and personal care segments commanding premium pricing through USP and EP certification requirements.
- Automotive:Engine oil and fuel additive formulators are the dominant consumption channel, with direct supply agreements displacing distributor-mediated transactions. Mercedes-Benz and Volkswagen Group approvals consolidate procurement around integrated C4 producers with guaranteed isobutene feedstock security.
- Pharmaceuticals:USP and EP compliance burdens lock working capital for 18-24 month certification cycles, creating steep barriers to entry. ECHA REACH registration thresholds on monomer residuals are accelerating qualification of pharmaceutical-grade material, opening premium margin pools for compliant producers.
- Construction:Roofing membrane and sealant applications drive coating-grade consumption.
- Personal Care:Cosmetic-grade specifications require specialized impurity controls.
Procurement scale peaks with Automotive. Margin expansion is most rapid in Pharmaceuticals.
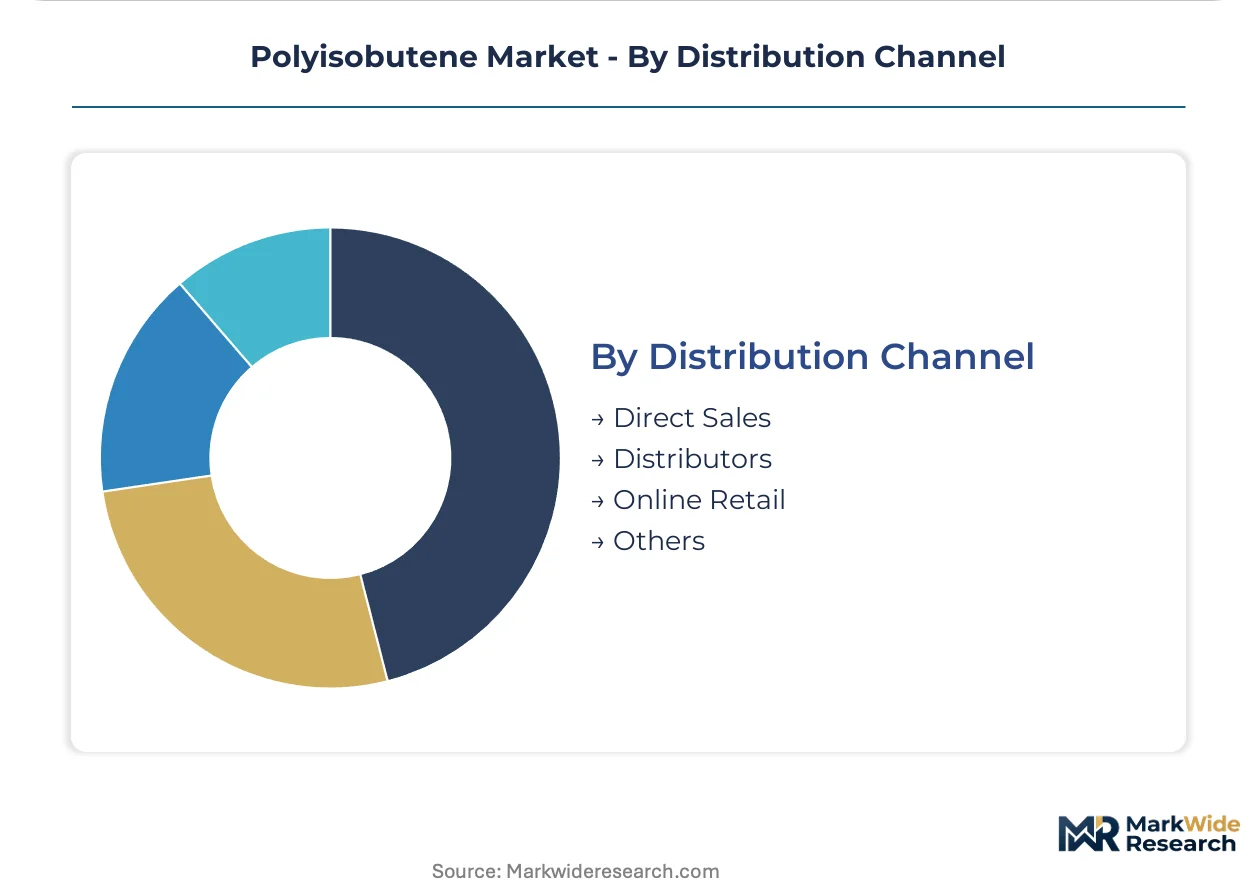
Distribution Channel:
Channel structure reflects buyer consolidation patterns, with multinational formulators bypassing intermediaries while regional compounders remain dependent on distributor networks.
- Direct Sales:Multinational lubricant blenders with engine oil approvals from Mercedes-Benz and Volkswagen Group are consolidating annual procurement volumes around fewer qualified suppliers. This concentration is most visible in North America and Europe, where integrated C4 producers capture preferred supplier status.
- Distributors:Regional compounders in Southeast Asia and emerging markets rely on distributor-mediated transactions for smaller volume procurement and technical service support.
- Online Retail:Specialty chemical platforms serve small-batch adhesive and coating formulators.
- Others:Agent-mediated channels persist in markets with complex import documentation requirements.
Transaction value concentrates in Direct Sales. Channel development is most active in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specialized high-viscosity production clusters while the United States dominates North American supply through integrated petrochemical complexes. China and India are expanding adhesive-grade consumption through packaging sector growth. Japan maintains pharmaceutical-grade specifications with extended certification requirements.
United States
Automotive lubricant blenders concentrate procurement around integrated C4 producers with guaranteed isobutene feedstock security. EPA 40 CFR constraints on volatile organic compounds expand polyisobutene penetration in low-VOC engine oil packages. The Baytown complex in Texas anchors high-viscosity manufacturing scale serving domestic sealant and roofing membrane formulators.
Germany
Continental tire manufacturers and sealant producers drive demand concentration for specialized high-viscosity grades. REACH and EU Green Deal mandates tighten specifications for low-molecular-weight polymer purity and biodegradability. The Rhine-Ruhr industrial corridor hosts production clusters where BASF SE and LANXESS AG anchor specialized capacity serving automotive and construction end-users.
China
Flexible packaging laminates and hot-melt adhesive formulations accelerate adhesive-grade consumption across coastal manufacturing zones. The country's national chemical regulator enforces polymer registration requirements on monomer residuals and impurity thresholds. The Yangtze River Delta industrial belt concentrates compounding operations for pressure-sensitive tape producers blending polyisobutene tackifiers with metallocene polyolefins.
India
Food-contact laminate producers pursue BIS certification pathways for adhesive-grade qualification in flexible packaging expansion. The Bureau of Indian Standards shapes compliance frameworks for indirect food-contact applications. Maharashtra and Gujarat host emerging compounding facilities serving regional packaging converters with distributor-mediated technical service support.
Japan
Cosmetic-grade and pharmaceutical specifications command premium pricing through specialized impurity controls and extended certification cycles. The national pharmaceutical regulator enforces compliance burdens that lock working capital for 18-24 month qualification timelines. The Kanto industrial region around Tokyo maintains formulation expertise for USP and EP-certified material serving personal care multinationals.
Polyisobutene Market Competitive Landscape
German producers anchor one tier of specialized high-viscosity manufacturing; United States-based integrated petrochemical operators hold scale positions in lubricant-grade supply. The vendor base clusters around three strategic archetypes: integrated C4 chemistry platforms with captive isobutene feedstock, specialized polymer producers with modular reactor capabilities, and regional compounders serving adhesive formulation markets. Capacity expansion and strategic partnerships dominate competitive moves, with direct supply agreements displacing distributor channels among multinational lubricant blenders.
Within the integrated chemistry tier, BASF SE and ExxonMobil Corporation exemplify archetypes with backward integration into feedstock security. SIBUR occupies a position among regionally anchored producers leveraging captive butene supplies at specialized production sites. These three entities represent distinct geographic and structural positions: a German-headquartered SE with Rhine-Ruhr cluster concentration, a United States-based Corporation with Gulf Coast manufacturing scale, and a Russian producer with Tobolsk site integration. Each anchors supply relationships with automotive formulators seeking engine oil approval qualifications from Mercedes-Benz and Volkswagen Group.
| Leading Market Players |
|---|
| BASF SE |
| Lubrizol Corporation |
| TPC Group |
| LANXESS AG |
| INEOS |
| ExxonMobil Corporation |
| Daelim Co., Ltd. |
| Reliance Industries |
| SIBUR |
| Others |
Value Network & Pricing Analysis
Modular skid-mounted reactor adoption in Southeast Asia is compressing minimum efficient scale thresholds while fragmenting supply concentration across mid-viscosity grades. This technology shift simultaneously erodes centralized pricing power in legacy production clusters and enables distributed cost economics for regional compounders.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for adhesive-grade material, forcing legacy producers in Germany and Texas to defend premium positioning through REACH certification bundling. Pricing stratifies across pharmaceutical-grade, industrial-grade, and coating-grade tiers, with USP and EP compliance commanding substantial premiums. Cost compression in low-viscosity lubricant grades is intensifying because polyalphaolefin substitution erodes volume leverage. Automotive lubricant blenders show least price sensitivity due to engine oil approval dependencies, while regional adhesive compounders in emerging markets drive hardest bargaining.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns for bulk chemical logistics. Manufacturing concentrates in Germany, the United States, and Russia, with BASF SE, ExxonMobil Corporation, and SIBUR anchoring specialized high-viscosity clusters. Feedstock security draws from captive C4 olefin streams, aluminum chloride catalyst supply chains, and cryogenic cooling infrastructure. Single-source vulnerability runs through German high-viscosity capacity serving Continental tire manufacturers. Distribution runs through direct supply agreements with multinational formulators, displacing distributor channels in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyisobutene has matured into a late-cycle quality story where REACH and USP certification tiers separate viable suppliers from commodity players. Demand is shifting decisively toward pharmaceutical-grade specifications with 18-24 month qualification barriers.
For Market Incumbents: Lock in feedstock security through backward integration into C4 chemistry platforms or long-term isobutene offtake agreements with steam cracker operators. Defend high-viscosity margins by accelerating ECHA registration completion ahead of EU Green Deal biodegradability mandates. Polyalphaolefin substitution in passenger car motor oils threatens volume in low-viscosity tiers; redirect capacity toward adhesive-grade qualification in India and Southeast Asia where BIS and national chemical regulator pathways are opening. For New Entrants and Emerging Players: E-commerce specialty chemical platforms offer the lowest-friction route to bypass entrenched distributor relationships and reach small-batch adhesive formulators directly. Target coating-grade corrosion-tape demand in pipeline maintenance cycles, where qualification barriers are lowest and geographic supply gaps persist in Asia-Pacific. Pursue modular skid-mounted production for mid-viscosity grades between 1,000 and 10,000 g/mol, leveraging technology transfer partnerships with regional engineering firms to bypass centralized import dependencies. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders with adhesive-grade technical service capabilities but lacking pharmaceutical-grade certification infrastructure. The five-to-ten year viability window favors producers with mass-balance bio-attributed isobutene feedstock positions ahead of EU Green Deal circular economy mandates. Watch ECHA registration review scope expansion as the critical inflection signal; producers with incomplete polymer lifecycle disclosure face disqualification risk from Continental packaging supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Feedstock | Captive isobutene supply secures margin structure against steam cracker rate volatility. |
| Pharmaceutical-Grade Certification Investment | USP and EP compliance opens premium margin pools with 18-24 month barrier protection. |
| Modular Reactor Deployment | Skid-mounted units in Southeast Asia bypass import dependencies and compress scale thresholds. |
| Mass-Balance Bio-Attribution Certification | EU Green Deal compliance maintains qualification status for Continental packaging markets. |
| Direct Supply Agreement Consolidation | Mercedes-Benz and Volkswagen Group approvals displace distributor-mediated transactions. |
Research Methodology
Multiple input streams — executive interviews with lubricant formulators and adhesive compounders, technical discussions with cationic polymerization engineers, and procurement lead surveys at packaging converters — were reconciled against customs trade data, SEC 10-K chemical segment disclosures, and ECHA registration databases. Bottom-up volume modeling from individual reactor capacity and utilization rates was triangulated against top-down demand estimates from end-use industry consumption patterns.
Data-stream reconciliation across molecular weight grades, application segments, and regional production clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include viscosity tier, end-use industry, certification level, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized consumption trends, with specific inputs from automotive OEM engine oil approval timelines and pipeline infrastructure maintenance cycle data.
The model assumes a particular technology adoption path for modular skid-mounted reactor deployment; alternative pathways for distributed manufacturing scale-up would alter the outlook for minimum efficient scale and geographic supply concentration. Forecasts reflect assumptions about REACH registration review intensity and EU Green Deal implementation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Co-Polymer Resin Market
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
Europe Super Absorbent Polymers (SAP) Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market
Polymers & Resins
Saturated Polyester Resin Market
Polymers & Resins
Global Acrylic Emulsions Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
Global UV Curable Resins Market