
 Potassium Fluoride Market | 2026-2036
Potassium Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Fluoride Market Outlook
Electronic-grade purity specifications above 99.9% is redrawing competitive boundaries in the Potassium Fluoride Market. Navin Fluorine International anchors its position through captive hydrofluoric acid supply in Gujarat. Solvay differentiates via integrated fluorine chemistry platforms serving European semiconductor fabs. Stella Chemifa Corporation dominates specialty fluoride production for Japanese electronics OEMs.
Potassium fluoride is an inorganic salt with formula KF, typically manufactured through neutralization of hydrofluoric acid with potassium carbonate or hydroxide, yielding a white crystalline solid with melting point 858°C that serves as a fluorinating agent, etchant, and precursor in industrial chemistry. The electronics application leads value generation due to wafer-processing demand for ultra-high-purity material. Powder and granular forms capture divergent margin pools, with powder commanding premiums in pharmaceutical synthesis while granular grades serve agricultural bulk buyers.
China's MEE enforces fluorochemical emission ceilings that constrain domestic production capacity expansion. REACH registration requirements in Europe and EPA reporting obligations in the United States shape cross-border trade flows and product documentation burdens. Stakeholders must monitor feedstock cost volatility and regional purity certification divergence when allocating capital across production footprints.
Market Dynamics
Feedstock hydrofluoric acid availability is tightening across East Asia as China's MEE enforces fluorochemical discharge ceilings, forcing electronics-grade producers to secure alternative supply routes or upgrade purification capabilities.
Growth Catalysts
- Semiconductor etching demand:Wafer-processing fabs in Jiangsu province and the Osaka-Kobe cluster are expanding capacity for advanced node production, pulling ultra-high-purity potassium fluoride volumes upward.
- REACH registration compliance:European fluorochemical documentation requirements are consolidating supplier bases and rewarding pre-registered producers with preferential access to German and Belgian semiconductor facilities.
- Dual carbon policy enforcement:China's MEE emission ceilings are accelerating domestic facility upgrades, creating import substitution windows for qualified foreign suppliers.
Market Restraints
- Hydrofluoric acid price volatility:Feedstock costs fluctuate with fluorspar concentrate availability from Mexican and Mongolian mines, compressing margin predictability for neutralization-route producers.
- East Asian supply concentration:Over sixty percent of electronics-grade capacity sits within five hundred kilometers of Shanghai, exposing buyers to simultaneous disruption risks from typhoon seasons or port congestion.
- Fluorine gas substitution:Direct fluorination technologies are displacing potassium fluoride in select pharmaceutical intermediates, eroding volume in legacy synthesis applications.
Strategic Opportunities
- Indian pharmaceutical expansion:Gujarat and Maharashtra bulk drug manufacturers are upgrading to GMP-certified fluorinating agents, opening premium-grade import channels previously dominated by domestic suppliers.
- Battery electrolyte precursors:Potassium fluoride derivatives are emerging as conductivity enhancers in solid-state electrolyte research programs across South Korean and Japanese materials laboratories.
- EU F-Gas Regulation phase-down:Refrigerant sector fluorochemical constraints are redirecting technical-grade capacity toward industrial etching applications with higher documentation tolerance.
Industry Challenges
- Analytical chemist scarcity:Electronics-grade certification requires ICP-MS trace metal analysis capabilities that few contract laboratories outside Japan and Germany currently maintain.
- Multi-jurisdiction registration timelines:Simultaneous EPA reporting, REACH dossier updates, and China's new chemical substance notification requirements extend product launch cycles by eighteen to thirty months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Fluoride Market |
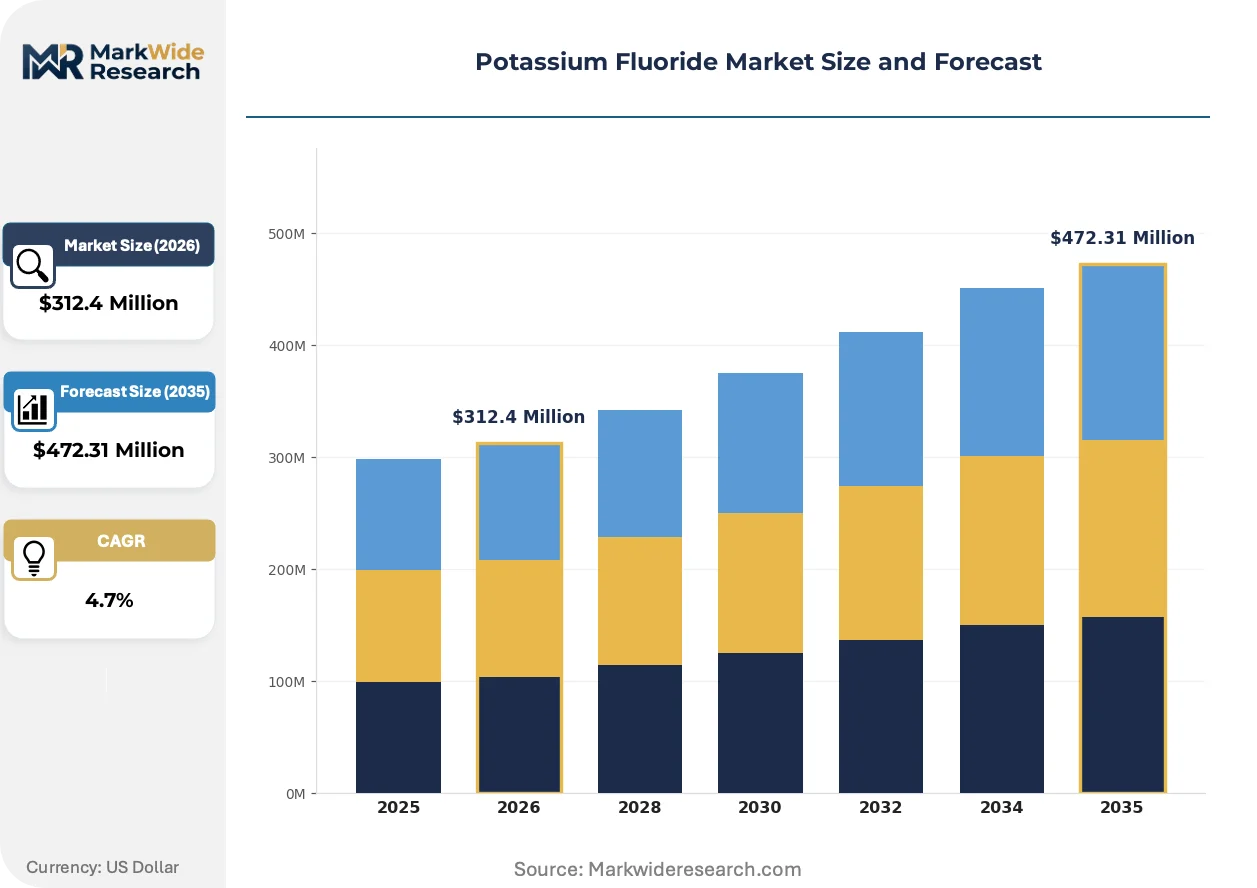
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Electronics, Pharmaceuticals, Agriculture, Chemical Synthesis Form: Granular, Powder, Liquid, Soluble End User: Manufacturers, Research Institutions, Farmers, Laboratories Packaging Type: Bags, Drums, Bottles, Containers |
| Companies Covered | Navin Fluorine International, Stella Chemifa Corporation, Solvay, Aarti Industries, Merck KGaA, DERIVADOS DEL FLUOR, Morita Chemical Industries, Harshil Industries, Tanfac Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Fluoride Market Strategic Shifts
Continuous flow fluorination systems are displacing batch neutralization in high-volume applications, while regulatory pressure on perfluorinated compound emissions is redirecting R&D investment toward closed-loop manufacturing architectures.
Membrane electrolysis for anhydrous potassium fluoride production is decomposing traditional neutralization economics. Japanese electronics chemical specialists are piloting solid-state electrolytic cells at scale. This technology is decomposing the historical feedstock cost advantage of integrated hydrofluoric acid producers by enabling direct fluoride recovery from spent etchant streams.
REACH restriction proposals on per- and polyfluoroalkyl substances are tightening fluorochemical chain-of-custody requirements across European semiconductor supply chains. German chemical distributors are mandating batch-level fluorine origin documentation. Specialty-grade producers with verified non-PFAS feedstock pathways are capturing preferential supply contracts from Dutch and Belgian fab operators.
Consolidated procurement desks at Korean and Taiwanese foundries are compressing supplier qualification cycles from twenty-four months to twelve. Volume commitments now bundle potassium fluoride with complementary fluorochemical portfolios. This concentration is most visible in Samsung and TSMC supplier ecosystems, where single-source contracts for etching chemical suites are displacing discrete material tenders.
Potassium Fluoride Market Segmentation
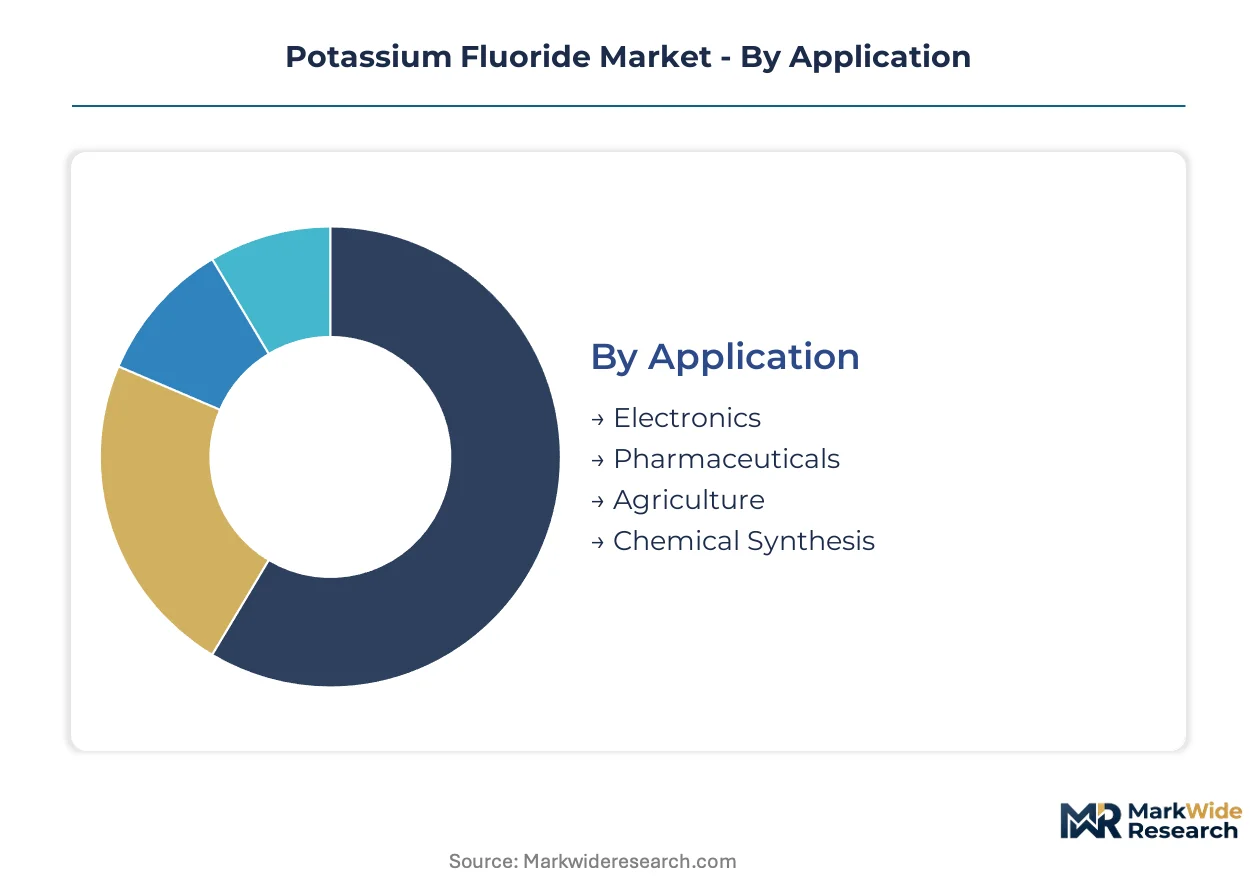
Segmentation in the Potassium Fluoride Market exposes how purity gradients and packaging economics split margin pools across divergent buyer workflows. Electronics-grade specifications command the steepest premiums, while agricultural bulk purchasing compresses unit economics toward feedstock cost floors.
Application:
Electronics applications capture the dominant share of value-added revenue, with pharmaceutical synthesis trailing at a narrower but defensible margin tier.
- Electronics:Ultra-high-purity grades above 99.9% serve wafer etching and surface treatment in Jiangsu province fabs and Osaka-Kobe semiconductor clusters. MEE emission ceilings in China are tightening feedstock availability, forcing qualified suppliers to secure alternative hydrofluoric acid routes or upgrade purification investments.
- Pharmaceuticals:GMP-certified fluorinating agent demand is climbing among Gujarat and Maharashtra bulk drug manufacturers upgrading to international quality standards. REACH registration requirements in Europe are consolidating supplier bases and rewarding pre-registered producers with preferential access to German and Belgian pharmaceutical facilities.
- Agriculture:Technical-grade material serves as a fluoride source in specialized fertilizer formulations and pest control applications across concentrated farming regions.
- Chemical Synthesis:Intermediate applications span organic fluorination reactions and specialty chemical manufacturing, with direct fluorination technologies displacing volumes in select legacy synthesis routes.
Electronics holds installed capacity. Pharmaceuticals is rotating up the share rankings.
Form:
Physical state determines logistics economics and contamination risk exposure, with powder forms absorbing disproportionate quality assurance overhead.
- Powder:Fine particulate grades below 100 microns command premiums in pharmaceutical synthesis where dissolution kinetics and batch consistency determine process yields. ICP-MS trace metal certification requirements restrict qualified supply to Japanese and German analytical laboratories with validated electronics-grade protocols.
- Granular:Crystalline forms with controlled particle size distribution serve agricultural bulk buyers and chemical synthesis operations where dissolution rate tolerances are wider. Bagged granular shipments from integrated hydrofluoric acid producers in East Asia dominate volume flows into price-sensitive procurement channels.
- Liquid:Aqueous solutions reduce handling hazards in laboratory and small-batch manufacturing environments with limited fluorine safety infrastructure.
- Soluble:Rapid-dissolution formulations target automated dosing systems in precision agriculture and continuous-flow chemical processing installations.
Granular dominates tonnage shipments. Powder is expanding most quickly in value terms.
End User:
Procurement sophistication varies sharply across buyer categories, with research institutions tolerating documentation gaps that manufacturers cannot accept.
- Manufacturers:Semiconductor fabs and pharmaceutical producers impose batch-level chain-of-custody requirements, with Korean and Taiwanese foundries compressing supplier qualification cycles from twenty-four months to twelve through consolidated chemical suite tenders.
- Research Institutions:Academic and government laboratories purchase smaller volumes with relaxed purity specifications, though solid-state electrolyte research programs in South Korean and Japanese materials laboratories are pulling experimental-grade volumes upward.
- Farmers:Agricultural cooperatives and individual operators source technical-grade material through regional distributor networks with limited analytical verification capabilities.
- Laboratories:Quality control and analytical chemistry operations consume reference-grade material for method validation and instrument calibration protocols.
Manufacturers anchor volume commitments. Research institutions are climbing the fastest as solid-state battery programs scale.
Packaging Type:
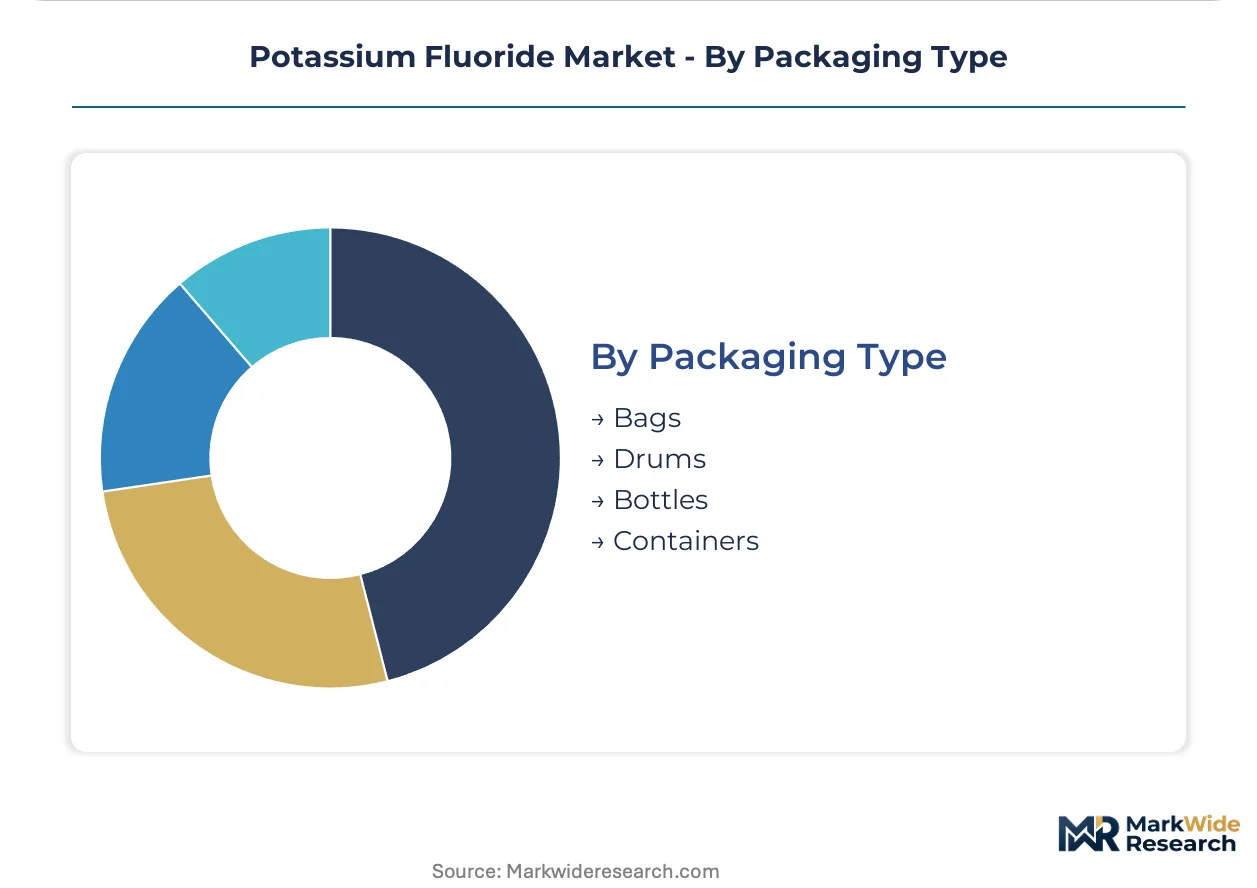
Container specifications align with contamination risk and handling automation requirements, with drum formats capturing intermediate value between bulk bags and precision bottles.
- Bags:Multi-wall paper or woven polypropylene sacks serve agricultural and technical-grade chemical synthesis buyers moving material by palletized truckload, with moisture barrier specifications varying by climatic exposure during distribution.
- Drums:Steel and fiber containers dominate electronics-grade and pharmaceutical-grade shipments where sealed integrity and UN certification for hazardous materials transport are mandatory.
- Bottles:Laboratory-scale packaging in glass or fluoropolymer-lined containers preserves purity for analytical and research applications with extended shelf-life requirements.
- Containers:Intermediate bulk containers and totes serve continuous-flow manufacturing installations with automated material handling systems and bulk storage infrastructure.
Drums hold the broadest cross-segment penetration. Bags retain cost advantage in agricultural channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated hydrofluoric acid capacity clusters within five hundred kilometers of Shanghai, exposing electronics-grade buyers to simultaneous disruption risks from typhoon seasons or port congestion. Chinese, Japanese, and South Korean fabs anchor procurement volumes, while European REACH compliance and Indian pharmaceutical upgrades reshape trade flows.
China
Jiangsu province fabs drive ultra-high-purity potassium fluoride consumption for advanced node wafer processing. MEE emission ceilings constrain domestic hydrofluoric acid availability, forcing qualified suppliers to secure alternative feedstock routes or upgrade purification investments. The Yangtze River Delta chemical corridor concentrates electronics-grade production alongside captive fluorine chemistry platforms.
Japan
Osaka-Kobe semiconductor clusters pull specialty fluoride volumes for Japanese electronics OEMs with batch-level chain-of-custody requirements. METI industrial policy supports closed-loop manufacturing architectures in fluorochemical processing. Stella Chemifa Corporation and Morita Chemical Industries anchor domestic supply through integrated fluorine chemistry expertise serving precision etching applications.
South Korea
Samsung and SK Hynix foundries compress supplier qualification cycles from twenty-four months to twelve through consolidated chemical suite tenders. MFDS pharmaceutical regulations shape GMP-certified fluorinating agent demand among Busan-Ulsan bulk drug manufacturers. Seoul Capital Area materials laboratories pull experimental-grade volumes for solid-state electrolyte research programs.
India
Gujarat and Maharashtra bulk drug manufacturers upgrade to GMP-certified fluorinating agents, opening premium-grade import channels previously dominated by domestic suppliers. CDSCO quality standards and PLI scheme incentives accelerate pharmaceutical-grade certification timelines. Navin Fluorine International leverages captive hydrofluoric acid supply in Gujarat to serve regional electronics and pharmaceutical demand.
Germany
Bavarian and North Rhine-Westphalia semiconductor fabs impose REACH registration requirements that consolidate supplier bases and reward pre-registered producers with preferential access. ECHA restriction proposals on per- and polyfluoroalkyl substances tighten fluorochemical chain-of-custody documentation. German chemical distributors mandate batch-level fluorine origin verification for Dutch and Belgian fab operators.
Potassium Fluoride Market Competitive Environment
Concentration sits with integrated fluorine chemistry specialists and captive hydrofluoric acid producers who control feedstock cost structures. The vendor base stratifies across three tiers: multinational chemical conglomerates with diversified fluorochemical portfolios, mid-cap specialists with regional purity certification dominance, and commodity-grade neutralization-route producers exposed to fluorspar price volatility. Strategic moves center on backward integration into hydrofluoric acid supply and purification capability upgrades to meet electronics-grade specifications.
Among integrated specialists, Solvay represents the multinational archetype with European semiconductor fab relationships, while Navin Fluorine International anchors the captive feedstock model through Gujarat-based hydrofluoric acid production. Stella Chemifa Corporation exemplifies the precision-grade specialist serving Japanese electronics OEMs with batch-level certification protocols.
| Leading Market Players |
|---|
| Navin Fluorine International |
| Stella Chemifa Corporation |
| Solvay |
| Aarti Industries |
| Merck KGaA |
| DERIVADOS DEL FLUOR |
| Morita Chemical Industries |
| Harshil Industries |
| Tanfac Industries |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory buffers among Jiangsu province semiconductor fabs signal supply-chain fragility and amplify pricing leverage for qualified electronics-grade suppliers. This lead-time compression concentrates procurement power with integrated fluorine chemistry specialists who control captive hydrofluoric acid routes.
Pricing Analysis
REACH registration dictates the pricing tier structure across European semiconductor supply chains. Three-tier pricing structure across premium, standard, and economy levels separates ICP-MS certified electronics-grade from GMP-certified pharmaceutical material and technical-grade agricultural supply. Price differentiation rests on purity certification and batch-level chain-of-custody documentation. Cost compression in technical-grade channels is intensifying because fluorspar concentrate availability fluctuates from Mexican and Mongolian mines. Agricultural cooperatives exhibit highest price sensitivity, while German and Belgian fabs tolerate substantial premiums for verified non-PFAS feedstock pathways.
Supply Chain Analysis
Just-in-time inventory strategies dominate electronics-grade procurement, though strategic stockpiling is emerging among Korean foundries hedging against typhoon season disruptions. Supply concentrates in China, Japan, and South Korea, with over sixty percent of electronics-grade capacity clustered within five hundred kilometers of Shanghai. Raw material flows draw from fluorspar mining operations in Mexico, Mongolia, and South Africa, plus hydrofluoric acid production in Gujarat and the Yangtze River Delta. Single-source vulnerability pervades the sector, as MEE emission ceilings constrain domestic Chinese feedstock availability. Distribution runs through integrated chemical distributors serving semiconductor clusters with bundled fluorochemical portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICP-MS trace metal analysis capabilities anchor competitive scarcity, with qualified contract laboratories concentrated in Japan and Germany creating bottlenecks for electronics-grade certification. This analytical infrastructure gap determines which suppliers capture premium supply contracts from Korean and Taiwanese foundries.
For Market Incumbents: Fortify purification capabilities to meet advancing node requirements at Samsung and TSMC facilities. Backward integration into hydrofluoric acid supply insulates margin structures from fluorspar price volatility. Invest in closed-loop manufacturing architectures ahead of METI industrial policy mandates. Defensive positioning against membrane electrolysis pilots requires accelerating direct fluoride recovery from spent etchant streams.
For New Entrants and Emerging Players: Differentiate on non-PFAS feedstock verification to capture Dutch and Belgian fab procurement windows opening under ECHA restriction proposals. Target Indian pharmaceutical upgrading in Gujarat and Maharashtra, where CDSCO quality standards and PLI scheme incentives compress certification timelines. Establish analytical partnerships with German or Japanese ICP-MS laboratories to bypass eighteen-to-thirty-month multi-jurisdiction registration barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized fluorine chemistry assets and dormant REACH registrations. Long-term viability hinges on purification technology ownership and regional purity certification dominance. Watch for inflection when membrane electrolysis achieves scale economics, decomposing traditional neutralization-route feedstock advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrofluoric Acid | Captive supply from Gujarat or Yangtze River Delta facilities insulates margin structures from fluorspar volatility. |
| ICP-MS Certification Investment | Analytical capability partnerships with German or Japanese laboratories unlock electronics-grade supply contracts. |
| Closed-Loop Manufacturing Transition | METI policy support and ECHA restriction proposals reward direct fluoride recovery from spent etchant streams. |
| Non-PFAS Feedstock Verification | German chemical distributor mandates for batch-level fluorine origin documentation create preferential supply windows. |
| Joint Venture with Korean Foundry | Consolidated procurement desks at Samsung and SK Hynix compress qualification cycles through bundled chemical suite tenders. |
Study Parameters
A standing panel of plant managers at fluorochemical facilities, procurement leads at Jiangsu province fabs, distribution channel partners serving Osaka-Kobe clusters, and technical R&D directors at Japanese electronics chemical specialists provided ongoing calibration across the research cycle. Primary interview findings were cross-referenced with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and MEE emission ceiling documentation. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile volume estimates.
Consistency checks against external benchmarks validated output robustness across the projection horizon. The analytical framework modeled grade tier segmentation, end-use industry splits across electronics and pharmaceuticals, packaging format economics, and regional production hub capacity. CAGRs were derived from installed base expansion rates, node transition timelines at major foundries, and pharmaceutical upgrading trajectories in India. Forecast inputs incorporated fluorspar concentrate trade flows, REACH registration status by supplier, and solid-state electrolyte research program scaling.
Material uncertainties — MEE enforcement intensity, fluorspar supply disruptions, membrane electrolysis scale economics — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding foundry capacity expansion and pharmaceutical certification timelines. Revision becomes warranted when membrane electrolysis cost parity crosses thresholds that trigger accelerated displacement of neutralization-route production.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
P-Ethylphenol Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Tin Chemicals Market
Chemicals
Asia-Pacific Construction Chemicals Market
Chemicals
Dicaprylyl Carbonate Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Africa Sodium Cyanide Market
Chemicals
Europe Hydrazine Market
Chemicals
Carcinogenic Chemical Alternatives Market
Chemicals
Acrylic Acids and Esters Market
Chemicals
CHPTAC Market
Chemicals
Laboratory Chemicals Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market