
 Human Biobanking Ownership Market | 2026-2036
Human Biobanking Ownership Market Size, Share, and Industry Trends Forecast 2026-2036
Human Biobanking Ownership Market Foresight
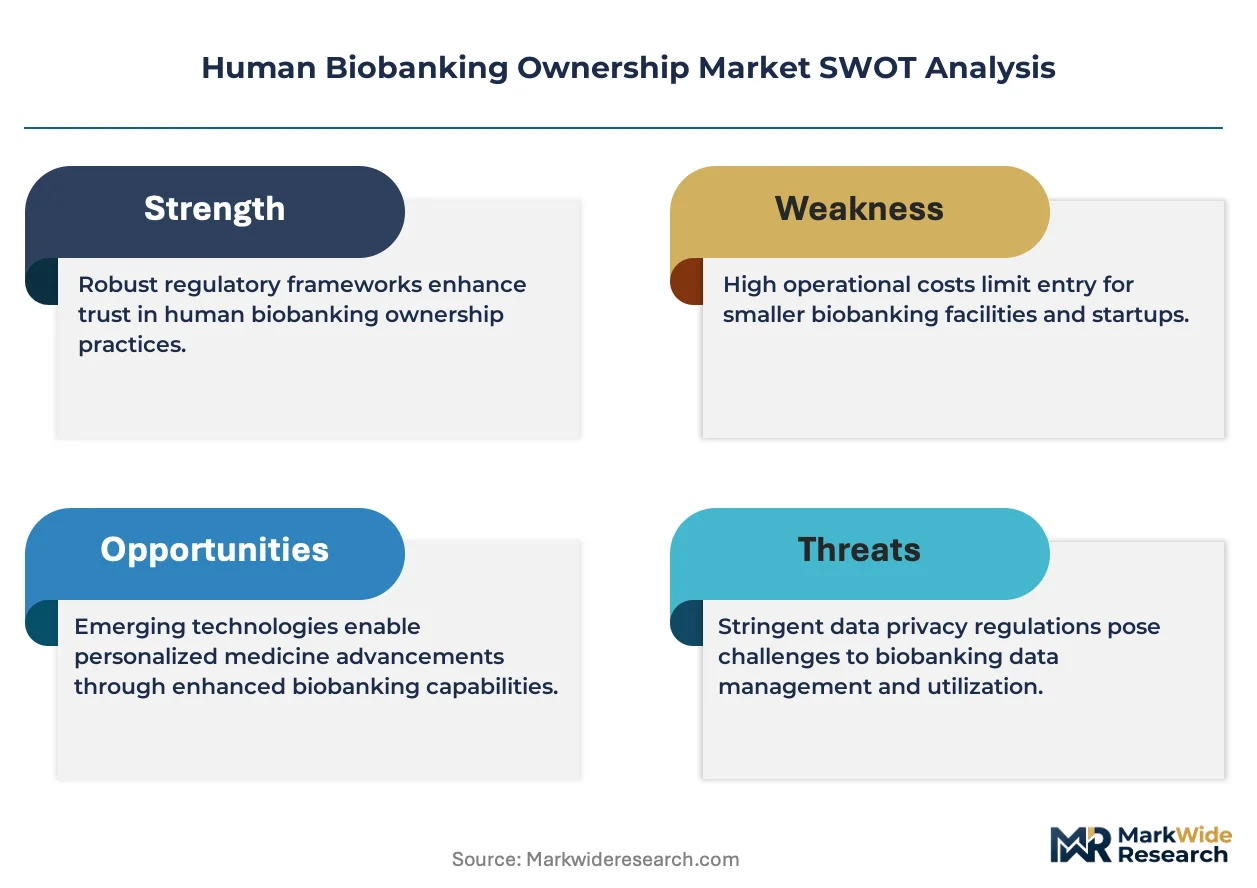
Buyer concentration among pharmaceutical sponsors is decoupling from traditional fragmented hospital-based procurement. Thermo Fisher Scientific leverages its end-to-end cold chain infrastructure to anchor large-scale ownership contracts. Qiagen competes through nucleic acid stabilization expertise that sustains sample value across ownership transfers. Danaher Corporation controls integrated quality systems that dominate regulatory-heavy custody environments.
Human biobanking ownership encompasses the legal and operational frameworks governing custodial rights over biological specimens maintained at temperatures between minus 196°C and minus 80°C for longitudinal research utility. Academic ownership structures retain the largest volume of legacy collections though private ownership models generate superior margins through commercial licensing terms. Blood-derived sample types occupy the highest throughput tier while tissue specimens command premium ownership valuations due to processing complexity and IRB governance burdens. Centralized storage modes are displacing on-site alternatives as biorepositories consolidate under regional hub architectures.
FDA 21 CFR Part 11, HIPAA privacy safeguards, and ISO 20387 biobanking standards collectively determine market access thresholds for ownership service providers. The FDA mandates complete chain-of-custody documentation that shapes platform investments across all ownership tiers. Stakeholders must monitor evolving state-level biobank privacy legislation that fragments compliance requirements beyond federal baselines.
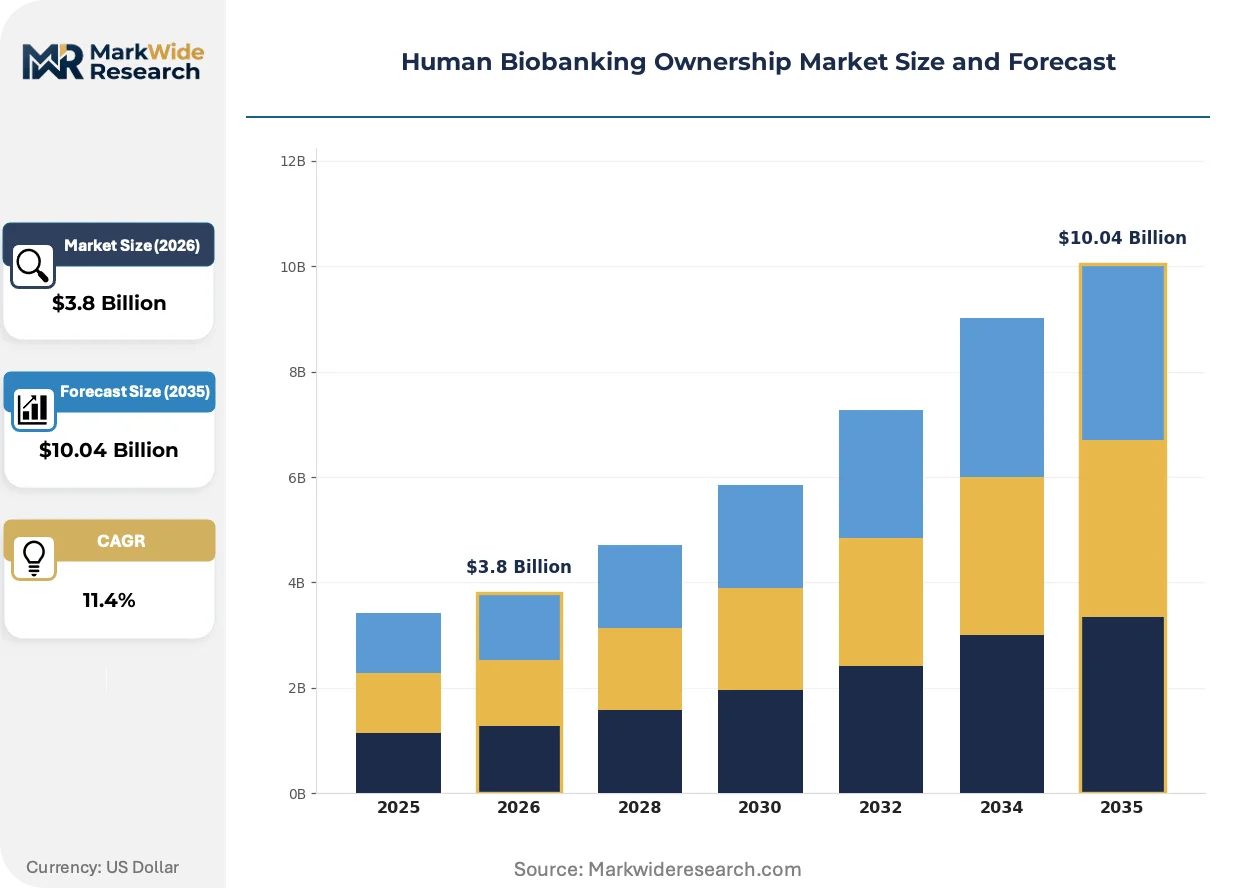
Market Dynamics
Pharmaceutical sponsors are consolidating biobank procurement under centralized vendor contracts, decoupling from fragmented hospital-based sourcing and reshaping custody economics across the ownership ecosystem.
Growth Catalysts
- FDA 21 CFR Part 11 mandates:Digital integrity requirements for chain-of-custody documentation are forcing platform upgrades that favor qualified ownership service providers with compliant infrastructure.
- Academic medical center conversion:Legacy specimen collections in the United States are being transformed into governed assets through structured ownership frameworks that enable commercial licensing.
- Regional hub architectures:Centralized storage modes are displacing on-site alternatives as biorepositories consolidate under temperature-controlled regional facilities.
Market Restraints
- IRB governance burdens:Tissue specimens face prolonged approval timelines that compress ownership valuation premiums and deter speculative collection investments.
- State-level privacy fragmentation:Biobank-specific legislation beyond HIPAA creates compliance multiplication costs for multi-jurisdictional ownership transfers.
- Liquid nitrogen supply concentration:Cryogenic infrastructure depends on concentrated industrial gas suppliers vulnerable to regional production disruptions.
Strategic Opportunities
- ISO 20387 certification gaps:Biobanks lacking standardized quality management systems present acquisition targets for ownership consolidators seeking regulatory-ready assets.
- Nucleic acid stabilization convergence:Integration of automated extraction platforms with long-term storage systems creates value-added service tiers beyond basic custody.
- Commercial licensing expansion:Private ownership models in pharmaceutical R&D verticals generate superior margins through tiered access agreements.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized technicians capable of maintaining minus 196°C to minus 80°C environments command premium compensation that strains operational budgets.
- Legacy collection data remediation:Decades-old specimens lack digital provenance records required for FDA-qualified ownership transfers, forcing expensive retrospective documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Biobanking Ownership Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ownership Type: Public, Private, Academic, Non-profit Sample Type: Blood, Tissue, DNA, Plasma Application Area: Research, Clinical Trials, Diagnostics, Drug Development Storage Mode: On-site, Off-site, Mobile, Centralized |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Qiagen, Becton Dickinson, Hamilton Company, Danaher Corporation, Tecan Group, Lonza Group, Stemcell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Biobanking Ownership Market Shifts & Advancements
Digital custody platforms and automated cold chain monitoring are compressing qualification timelines while regulatory digitization mandates reshape platform architecture investments across ownership tiers.
Blockchain-enabled specimen provenance tracking is expanding into pharmaceutical sponsor audit requirements, with large-scale biobank operators adopting distributed ledger systems to satisfy FDA chain-of-custody demands. Thermo Fisher Scientific and Qiagen are embedding these capabilities into their custody platforms to anchor enterprise contracts. The technology is expanding into secondary markets by enabling fractional ownership verification for research consortium arrangements.
EMA's MDR traceability requirements are extending into biobanking ancillary services, compelling European custody providers to implement unique device identification for processing equipment. This regulatory pressure is compressing vendor qualification cycles and favoring integrated quality system providers. Tissue processors in Germany and France are responding by consolidating under Danaher Corporation's regulatory-heavy custody environments.
Buyer concentration among pharmaceutical sponsors is fragmenting traditional hospital-based procurement relationships, with centralized vendor management offices displacing site-specific contracting. Academic medical centers in the United States are losing pricing leverage as sponsors mandate preferred provider networks. This behavioral shift is most visible in oncology specimen sourcing, where sponsors now require pre-qualified biobank partnerships for trial eligibility.
Human Biobanking Ownership Market Segmentation
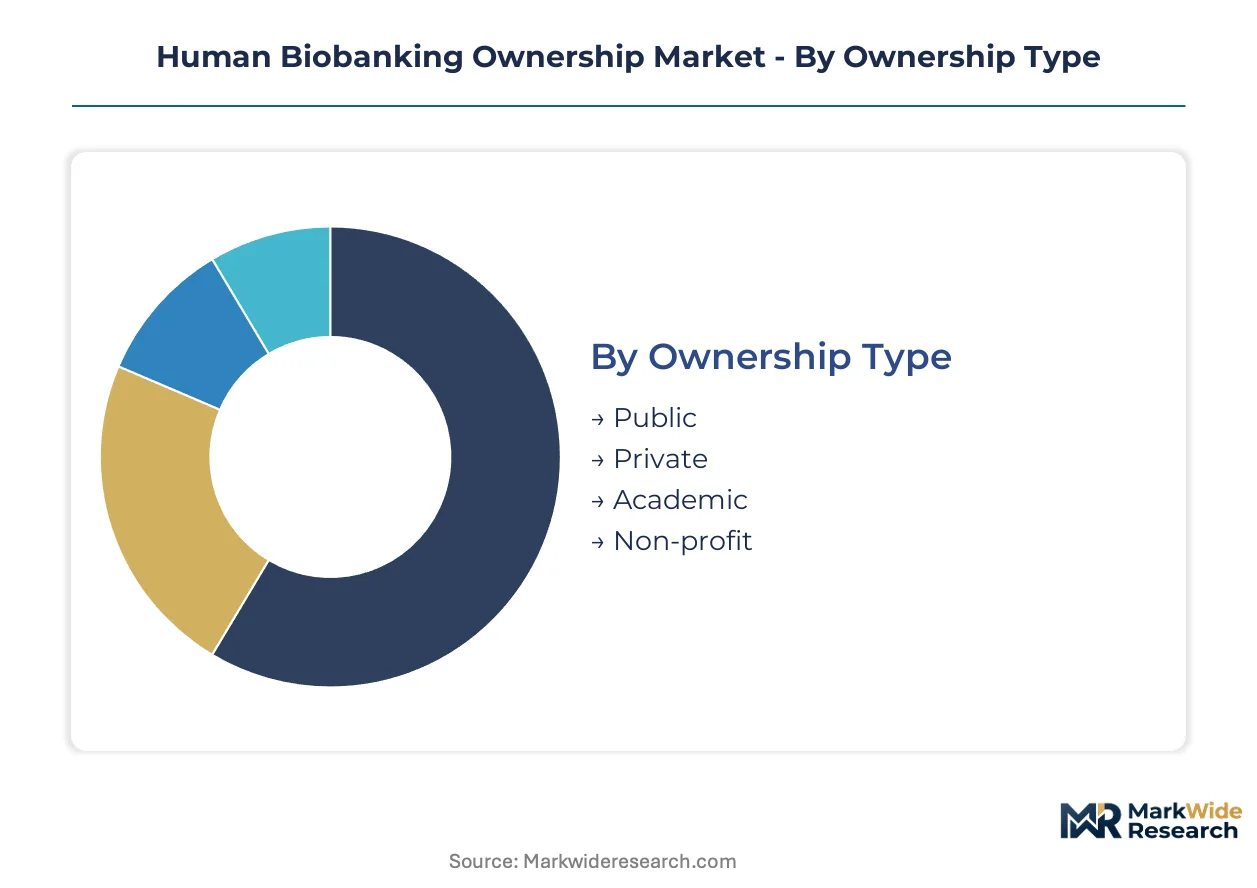
Ownership structures determine margin profiles and regulatory exposure across the biobanking ecosystem. Sample type and storage configuration further stratify operational complexity and capital requirements for custody providers.
Ownership Type:
Volume concentrates in academic repositories while premium economics favor commercial frameworks with licensing flexibility.
- Public:Government-funded collections serve population health mandates with standardized access protocols. Demand clusters in national health initiatives across Germany and France where centralized biobanks support longitudinal epidemiology studies under EMA data governance.
- Private:Commercial entities command superior margins through tiered licensing agreements and exclusive access arrangements. Pharmaceutical sponsors in the United States increasingly mandate private ownership structures for oncology specimen sourcing to ensure chain-of-custody integrity under FDA 21 CFR Part 11.
- Academic:University medical centers retain the largest legacy specimen volumes though conversion to governed assets requires expensive data remediation. IRB governance burdens compress valuation premiums for tissue-heavy collections.
- Non-profit:Disease foundation repositories aggregate patient-donated specimens with restricted commercial use clauses. Operational sustainability depends on grant funding cycles that limit infrastructure investment.
Today's leader: Private ownership. Tomorrow's challenger: Academic conversion frameworks.
Sample Type:
Processing complexity separates high-throughput commodities from premium specimens with specialized handling requirements.
- Blood:Serum and whole blood specimens dominate throughput metrics due to standardized collection protocols and automated processing compatibility. United States academic medical centers are converting legacy blood collections into governed assets to enable commercial licensing.
- Tissue:Solid tumor and normal tissue specimens command ownership premiums reflecting histopathology validation requirements and cryogenic sectioning expertise. IRB approval timelines for tissue use compress speculative collection investments.
- DNA:Extracted nucleic acids require stabilization platforms that sustain integrity across ownership transfers. Qiagen's expertise in this category anchors custody contracts with molecular diagnostic sponsors.
- Plasma:Cell-free plasma fractions support proteomics and circulating biomarker research with intermediate processing complexity. Demand concentrates in cardiovascular and metabolic disease verticals.
Blood generates volume scale. Tissue captures margin expansion.
Application Area:
Regulatory stringency escalates from exploratory research through regulated drug development environments.
- Research:Academic and government-funded investigations utilize broad consent frameworks with lower documentation thresholds. Specimen provenance requirements remain flexible compared to regulated applications.
- Clinical Trials:FDA-mandated chain-of-custody documentation forces platform upgrades that favor qualified ownership service providers. Sponsor consolidation under centralized vendor contracts reshapes procurement economics.
- Diagnostics:Companion diagnostic development requires specimen collections with documented clinical outcomes. LDT and IVD regulatory pathways impose distinct quality management burdens.
- Drug Development:Pharmaceutical R&D verticals generate the steepest expansion trajectory through tiered access agreements and longitudinal specimen requirements. Private ownership models dominate this segment.
Drug development commands investment focus. Diagnostics offers standardization leverage.
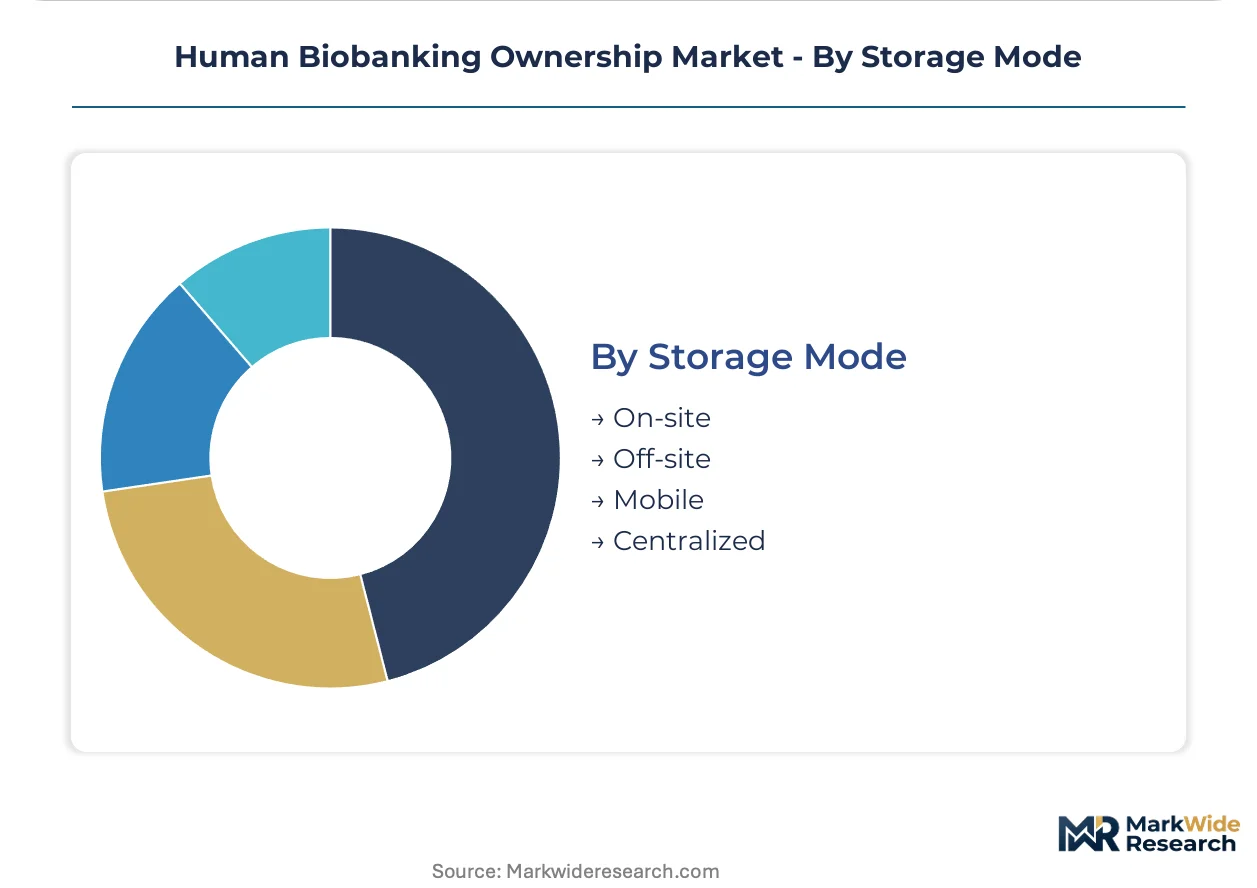
Storage Mode:
Capital intensity and operational control trade off across distributed versus centralized architectures.
- On-site:Hospital-based repositories maintain immediate specimen accessibility for clinical service operations. Consolidation pressures are displacing this mode as sponsors mandate pre-qualified biobank partnerships.
- Off-site:Third-party custody providers achieve economies of scale through regional hub architectures with automated cold chain monitoring. Thermo Fisher Scientific leverages end-to-end infrastructure to anchor enterprise contracts.
- Mobile:Deployable cryogenic units serve decentralized collection networks and emergency response scenarios. Niche deployment limits commercial scale.
- Centralized:Temperature-controlled regional facilities consolidate legacy collections under unified quality systems. Danaher Corporation's integrated platforms dominate regulatory-heavy custody environments.
Centralized storage gains share. Off-site retains flexibility premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates pharmaceutical sponsor demand while Germany anchors European regulatory-grade custody infrastructure, creating divergent investment patterns across major biobanking ownership markets.
United States
Academic medical centers in Boston and the Research Triangle are converting legacy specimen collections into governed assets with commercial licensing frameworks. FDA 21 CFR Part 11 mandates are forcing platform upgrades that favor qualified ownership service providers with compliant digital infrastructure. The National Cancer Institute's biorepository network in Bethesda anchors federal specimen governance standards.
Germany
EMA MDR traceability requirements are compelling custody providers to implement unique device identification for processing equipment across Bavarian and North Rhine-Westphalian biobank clusters. The country's national pharmaceutical regulator enforces chain-of-custody documentation that exceeds baseline EU requirements. Heidelberg and Munich academic medical centers are consolidating tissue processing under regional hub architectures.
France
ANSM oversight of biobank ancillary services is compressing vendor qualification cycles for Parisian and Lyon-based custody providers. The country's national data protection authority imposes supplementary consent documentation beyond GDPR baselines for specimen transfers. Île-de-France biorepositories are adopting ISO 20387 certification to qualify for pharmaceutical sponsor contracts.
United Kingdom
UK Biobank's longitudinal collection in Manchester and Oxford is setting governance templates for commercial licensing arrangements with pharmaceutical sponsors. The Medicines and Healthcare products Regulatory Agency mandates complete provenance documentation for specimens used in regulated drug development. London academic medical centers are losing pricing leverage as sponsors mandate pre-qualified biobank partnerships.
Japan
PMDA quality management requirements for clinical trial specimens are driving consolidation among Tokyo and Osaka-based biorepositories. METI funding for precision medicine initiatives is expanding governed specimen collection infrastructure. Kansai region biobanks are integrating automated cold chain monitoring to satisfy pharmaceutical sponsor audit requirements.
Human Biobanking Ownership Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across custody infrastructure, reagent systems, and quality management verticals. Market structure tilts toward consolidation as pharmaceutical sponsors mandate centralized vendor contracts that displace fragmented hospital-based procurement. Three archetypes dominate: integrated life sciences conglomerates with end-to-end cold chain infrastructure, nucleic acid stabilization specialists with automated extraction platforms, and regulatory-heavy quality system providers. Dominant competitive moves include strategic partnerships for regional hub architectures and technology licensing for blockchain-enabled provenance tracking.
Among integrated conglomerates, Thermo Fisher Scientific and Danaher Corporation anchor enterprise ownership contracts through captive infrastructure and quality system integration. Qiagen occupies a specialist position exemplifying nucleic acid stabilization expertise that sustains sample value across custody transfers. These three entities represent the competitive poles—scale-driven integration, regulatory-heavy compliance, and technical specialization—that define strategic positioning in pharmaceutical sponsor procurement.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Qiagen |
| Becton Dickinson |
| Hamilton Company |
| Danaher Corporation |
| Tecan Group |
| Lonza Group |
| Stemcell Technologies |
| Others |
Supply & Pricing Matrix
Liquid nitrogen supply costs cascade through ownership pricing tiers, with cryogenic infrastructure investments anchoring premium custody rates in United States and German markets while compressed margins pressure regional hub operators.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for regulatory-grade custody services. Three-tier pricing structure across premium, standard, and economy levels separates ISO 20387-certified facilities from basic storage providers. Pricing pressure stems from pharmaceutical sponsor consolidation under centralized vendor contracts. Academic medical centers exhibit highest price sensitivity due to grant-dependent budgets, while commercial drug developers accept premium rates for FDA 21 CFR Part 11 compliance.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for cryogenic equipment and industrial gas supply. Manufacturing concentrates in the United States, Germany, and Japan for ultra-low temperature storage systems. Supply chains draw from concentrated liquid nitrogen production, specialized compressor units, and automated monitoring sensors. Single-source vulnerability in industrial gas supply creates systemic risk for regional hub architectures. Distribution runs through qualified third-party logistics providers with temperature-validated transport certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Human Biobanking Ownership Market functions as a stable compounder, with longitudinal specimen retention requirements and regulatory digitization mandates generating recurring infrastructure investment cycles.
For Market Incumbents: Extend quality system integration into nucleic acid stabilization workflows to defend against Qiagen's technical specialization. Anchor enterprise contracts through captive cold chain infrastructure investments in Boston and Research Triangle clusters. Consolidate regional hub architectures before pharmaceutical sponsor vendor management offices finalize preferred provider networks. For New Entrants and Emerging Players: Disease foundation repositories represent an underserved buyer archetype with grant-funded infrastructure gaps and restricted commercial use clauses. Target non-profit ownership structures with hybrid governance-to-licensing service packages. Pursue ISO 20387 certification gaps in French and Japanese academic medical centers as the most penetrable entry vector. For Investors and Strategic Acquirers: Consolidation pressure builds where legacy collections lack digital provenance records required for FDA-qualified ownership transfers. Frame long-term viability around biobank acquisition targets with retrospective data remediation needs and commercial licensing conversion potential. Watch pharmaceutical sponsor audit requirement expansion as the inflection signal for blockchain-enabled provenance tracking adoption.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20387 Certification Investment | Qualifies biobanks for pharmaceutical sponsor contracts under EMA and FDA governance frameworks. |
| Blockchain Provenance Integration | Satisfies chain-of-custody documentation mandates from Thermo Fisher and Qiagen enterprise clients. |
| Regional Hub Consolidation | Captures economies of scale in temperature-controlled storage across United States and German markets. |
| Nucleic Acid Stabilization Platform | Creates value-added service tiers beyond basic custody for molecular diagnostic sponsors. |
| Academic Licensing Framework Conversion | Transforms legacy collections into governed assets with commercial revenue streams. |
Research Methodology
Coverage spans the United States, Germany, France, the United Kingdom, and Japan, with primary inputs from each market cluster. The analysis combines structured interviews with biobank operations directors, pharmaceutical sponsor procurement leads, regulatory affairs specialists, and academic medical center technology transfer officers. Secondary validation draws from FDA 21 CFR Part 11 guidance documents, EMA MDR traceability requirements, ISO 20387 certification registries, and hospital procurement database extracts. Bottom-up specimen volume estimates and top-down ownership contract value analysis undergo triangulation.
Rate-of-change decomposition separates volume expansion from pricing trajectory shifts across the projection horizon. Segmentation dimensions include ownership type, sample category, application area, and storage mode, with regulatory compliance tier as an additional industry-specific dimension. CAGRs derive from fitted trend analysis applied to historical contract value data and sponsor procurement survey responses. Forecast inputs incorporate liquid nitrogen supply cost trajectories and pharmaceutical R&D pipeline specimen demand indicators.
Underlying measurement precision varies by segment; private ownership and drug development applications carry tighter precision than public collections and exploratory research. Forecasts reflect documented assumptions regarding regulatory digitization timelines and sponsor consolidation velocity. Deviation in FDA enforcement intensity for chain-of-custody violations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
PD L1 Biomarker Testing Market
Biomedical Technology
Global Glycomics/Glycobiology Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
Human Reproductive Technologies Market
Biomedical Technology
Global Glycobiology Market
Biomedical Technology
Ubiquitin Proteasome Market
Biomedical Technology
Global Oncology Based in-Vivo CRO Market
Biomedical Technology
Cell Separation Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Oligonucleotide Synthesis Market
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Live Cell RNA Detection Market
Biomedical Technology
Global Biomarker Technologies Market