
 Human Reproductive Technologies Market | 2026-2036
Human Reproductive Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Human Reproductive Technologies Market Outlook
A capital-intensity divergence between integrated pharmaceutical suppliers and specialized device manufacturers is reorganizing competitive boundaries in human reproductive technologies. Merck KGaA leverages its vertically integrated fertility drug portfolio to dominate gonadotropin supply chains. Thermo Fisher Scientific anchors its position through controlled access to genetic testing platforms and laboratory infrastructure. Vitrolife AB specializes in time-lapse embryo imaging systems that command premium positioning in high-throughput clinics.
Human reproductive technologies encompass clinical procedures, laboratory equipment, and pharmaceutical interventions designed to achieve conception outside or with assisted natural processes, including temperature-controlled incubation at 37 degrees Celsius with 5-6% carbon dioxide and pH 7.2-7.4 for embryo culture. These technologies serve infertile couples, single parents, and LGBTQ+ couples seeking biological parenthood through medically supervised pathways. In Vitro Fertilization occupies the largest value pool due to its multi-cycle drug and device requirements, while Genetic Testing captures expanding margins as preimplantation screening becomes standard practice. Fertility Clinics represent the dominant application channel, consolidating procedure volume through centralized laboratory investments and specialized embryology staffing.
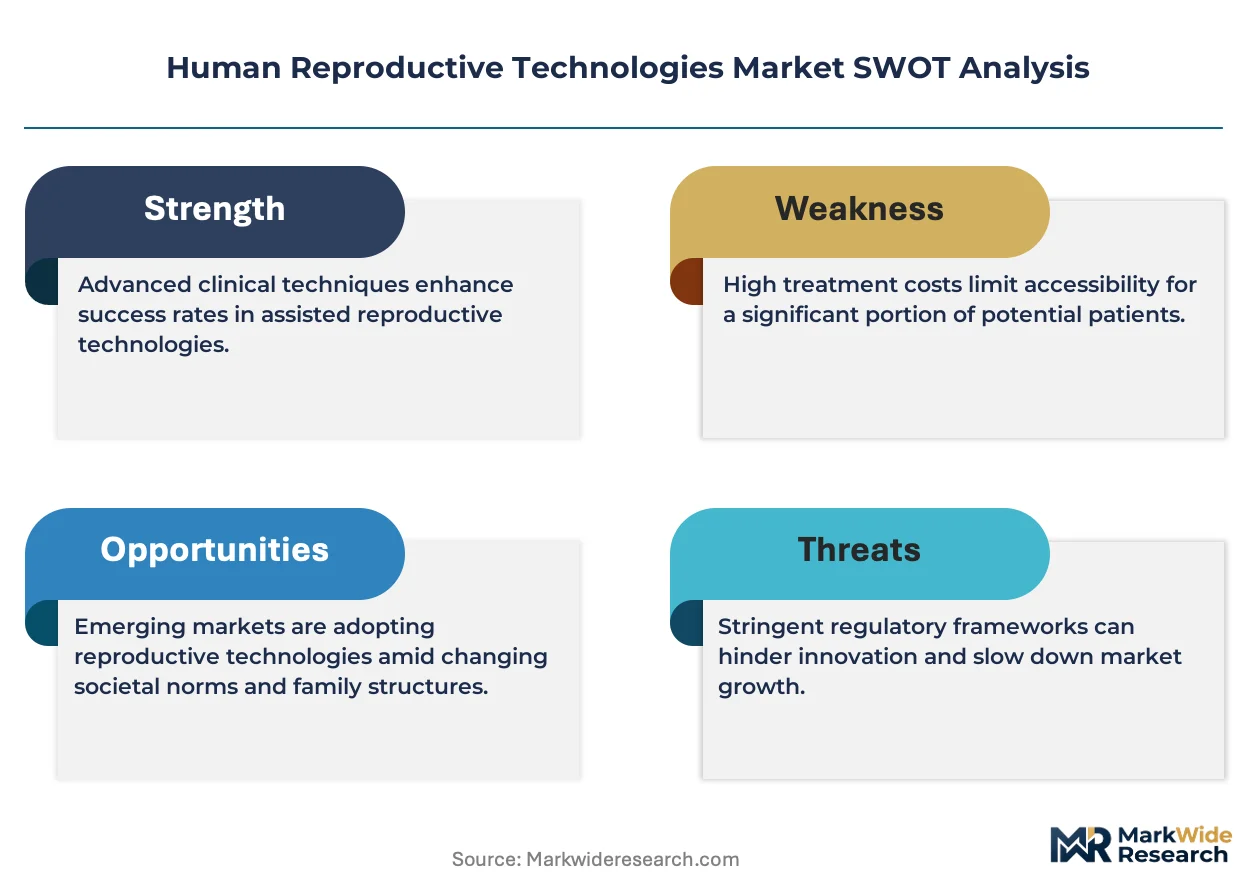
FDA oversight of human cells, tissues, and cellular and tissue-based products shapes device and media approval pathways in the United States, while EMA and national competent authorities enforce the EU Tissues and Cells Directive across European member states. These frameworks elevate compliance costs but simultaneously protect incumbent positions by creating barriers for unvalidated entrants. Stakeholders must monitor evolving preimplantation genetic testing reimbursement decisions and emerging AI-based embryo selection regulatory classifications to anticipate shifts in competitive advantage and capital allocation priorities.
Market Dynamics
Preimplantation genetic testing reimbursement decisions are compressing profit margins across fertility clinic networks while simultaneously accelerating consolidation among high-throughput embryology laboratories.
Growth Catalysts
- EU Tissues and Cells Directive harmonization:Standardized quality benchmarks across European member states reduce cross-border regulatory friction for media and device suppliers. Fertility clinics in Germany and Spain leverage mutual recognition to streamline procurement.
- Time-lapse embryo imaging:Automated morphokinetic analysis reduces manual embryologist hours per cycle. High-throughput clinics in the United States deploy these systems to scale patient throughput without proportional staffing increases.
- LGBTQ+ family formation demand:Legal recognition of same-sex marriage and single-parent rights in Canada, Australia, and parts of Latin America expands addressable patient populations beyond traditional infertility diagnoses.
Market Restraints
- Gonadotropin supply concentration:Three manufacturers control recombinant FSH production, exposing clinics to price volatility and allocation risk during manufacturing disruptions.
- FDA 510(k) pathway complexity:Novel embryo culture media formulations face extended review timelines for substantial equivalence determinations, delaying market entry for improved formulations.
- Oocyte cryopreservation technical ceiling:Post-thaw survival rates plateau below 90% for women over 38, limiting elective fertility preservation adoption among older demographics.
Strategic Opportunities
- India's underserved metro corridors:Mumbai, Delhi, and Bangalore host fewer than 300 accredited IVF centers for a population exceeding 400 million reproductive-age adults. Partnerships with local hospital chains unlock volume.
- AI-based embryo classification:Machine learning algorithms analyzing time-lapse image sequences reduce subjective grading variation. Regulatory clarity from the FDA on software-as-medical-device classification determines commercialization pace.
- Direct-to-consumer genetic screening integration:At-home carrier testing platforms create pre-qualified patient pipelines. Fertility clinics in California and Texas pilot referral partnerships with DTC laboratories.
Industry Challenges
- Embryologist training pipeline constriction:Certification programs require 2-3 years of supervised practice. Clinic expansion outpaces accredited training positions in the United Kingdom and Australia.
- Cleanroom infrastructure capex intensity:ISO 14644 Class 7 laboratory suites demand $3-5 million per facility. Independent clinics defer upgrades, ceding volume to capital-rich networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Reproductive Technologies Market |
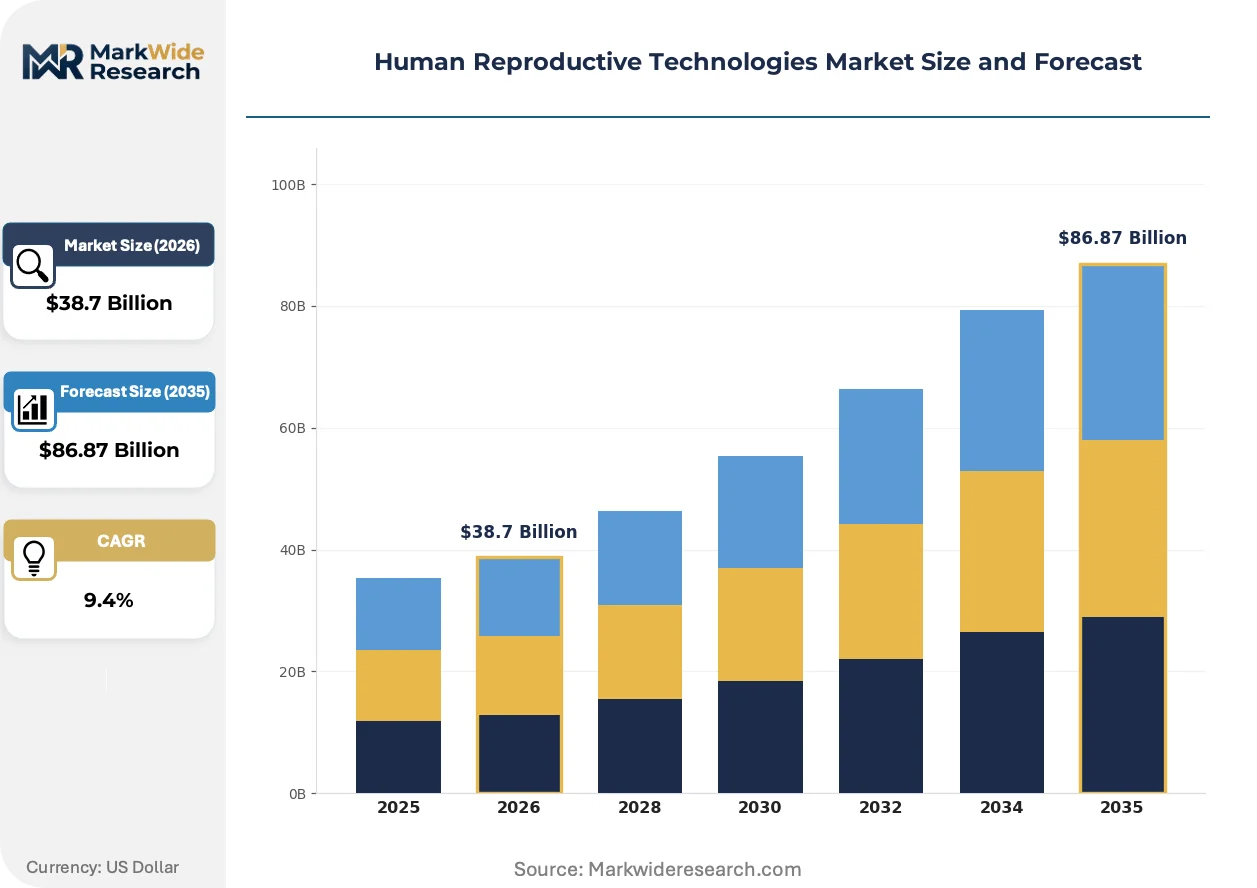
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: In Vitro Fertilization, Artificial Insemination, Genetic Testing, Egg Freezing Application: Fertility Clinics, Hospitals, Research Institutes, Home Use End User: Infertile Couples, Single Parents, LGBTQ+ Couples, Donor Recipients Service Type: Consultation, Screening, Treatment, Support Services |
| Companies Covered | Merck KGaA, Ferring Pharmaceuticals, CooperSurgical, Thermo Fisher Scientific, Vitrolife AB, Cook Medical, Bayer AG, Teva Pharmaceutical Industries, Genea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Reproductive Technologies Market Strategic Shifts
Automation is penetrating embryology workflows at the precise moment regulatory scrutiny intensifies on algorithmic decision-support tools. Three developments merit close monitoring.
Time-lapse incubation systems equipped with integrated AI scoring modules are decomposing the traditional embryologist's role in manual morphology assessment. Fertility networks with annual cycle volumes exceeding 2,000 procedures deploy these platforms to standardize embryo selection protocols. The structural consequence is compressing headcount requirements per laboratory while elevating capital intensity barriers for independent competitors.
REACH chemical registration requirements are extending disclosure obligations to embryo culture media constituents. Manufacturers reformulating synthetic protein substitutes face expanded toxicology documentation demands. European suppliers with pre-registered base chemical portfolios gain compliance speed advantages over entrants lacking grandfathered substance dossiers.
Patients are initiating treatment journeys through employer-sponsored fertility benefits rather than direct specialist referrals. Large self-insured employers in the United States contract with managed fertility networks that steer members toward preferred high-volume clinics. This channel shift concentrates procedure volume within accredited network participants and marginalizes independent practices lacking payer contracts.
Human Reproductive Technologies Market Segmentation
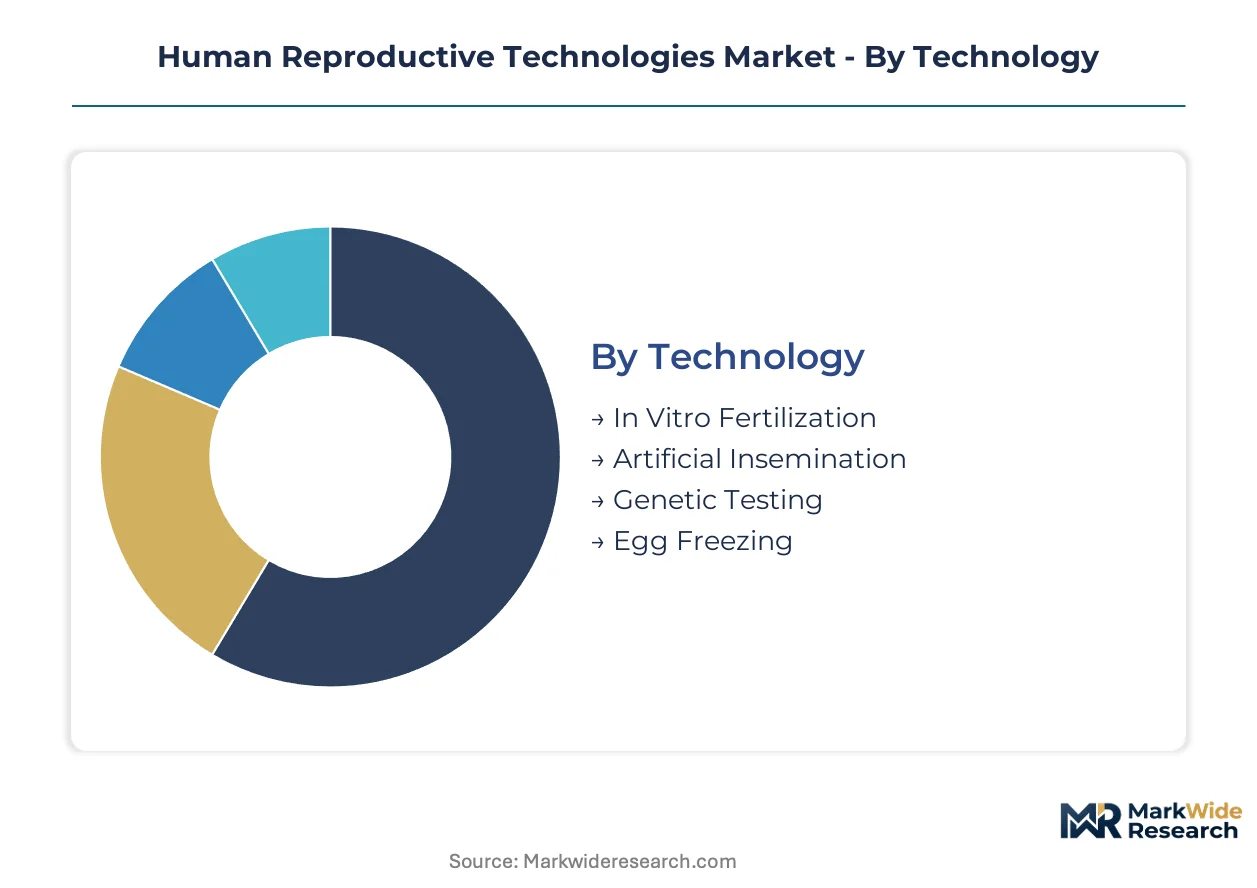
Human reproductive technologies fragment across clinical, pharmaceutical, and service dimensions that determine procurement patterns and capital allocation priorities. Each segmentation axis reveals distinct margin profiles and regulatory exposure for suppliers and providers.
Technology:
Fertility clinics route high-complexity procedures through centralized embryology laboratories while simpler interventions flow to satellite offices or hospital partnerships.
- In Vitro Fertilization:Multi-cycle protocols combine controlled ovarian stimulation, oocyte retrieval, and embryo transfer with sustained gonadotropin consumption. United States clinic networks concentrate demand where employer-sponsored benefits subsidize treatment costs.
- Genetic Testing:Preimplantation screening and carrier analysis require specialized NGS platforms and bioinformatics pipelines. European laboratories under EMA oversight lead standardization of PGT-A clinical utility evidence.
- Artificial Insemination:Lower-complexity intrauterine procedures dominate initial fertility consultations in India and Latin America where cost sensitivity shapes first-line intervention selection.
- Egg Freezing:Elective oocyte cryopreservation serves career-delayed family planning in corporate benefit programs across Australia and Canada.
In Vitro Fertilization dominates installed base. Genetic Testing is where expansion concentrates.
Application:
Capital intensity and regulatory accreditation requirements stratify delivery settings across reimbursement tiers and patient volume thresholds.
- Fertility Clinics:Standalone specialized facilities aggregate embryology talent and ISO 14644 cleanroom infrastructure. Germany and Spain host high-throughput networks exploiting EU Tissues and Cells Directive mutual recognition.
- Hospitals:Academic medical centers integrate reproductive endocrinology with maternal-fetal medicine and genetics departments. United States health systems leverage 340B drug pricing for fertility pharmaceutical procurement.
- Research Institutes:Stem cell and early embryo research programs drive demand for research-grade culture media and time-lapse systems without clinical quality management overhead.
- Home Use:Ovulation tracking hardware and sperm collection kits expand through direct-to-consumer channels in deregulated jurisdictions.
Fertility Clinics capture procedure volume concentration. Research Institutes are climbing the fastest for equipment refresh cycles.
End User:
Legal recognition of family formation rights and insurance benefit design reshape patient demographic composition across markets.
- Infertile Couples:Medically diagnosed infertility remains the core reimbursed indication in most national health systems and private payer contracts.
- LGBTQ+ Couples:Same-sex family formation demand expands in Canada, Australia, and select US states with mandated fertility benefit parity.
- Single Parents:Elective single parenthood by choice drives donor sperm and oocyte utilization where regulatory frameworks permit.
- Donor Recipients:Third-party reproduction coordination requires specialized counseling and genetic matching services.
Infertile Couples anchor reimbursement frameworks. LGBTQ+ Couples are gaining share fastest where legal protections mature.
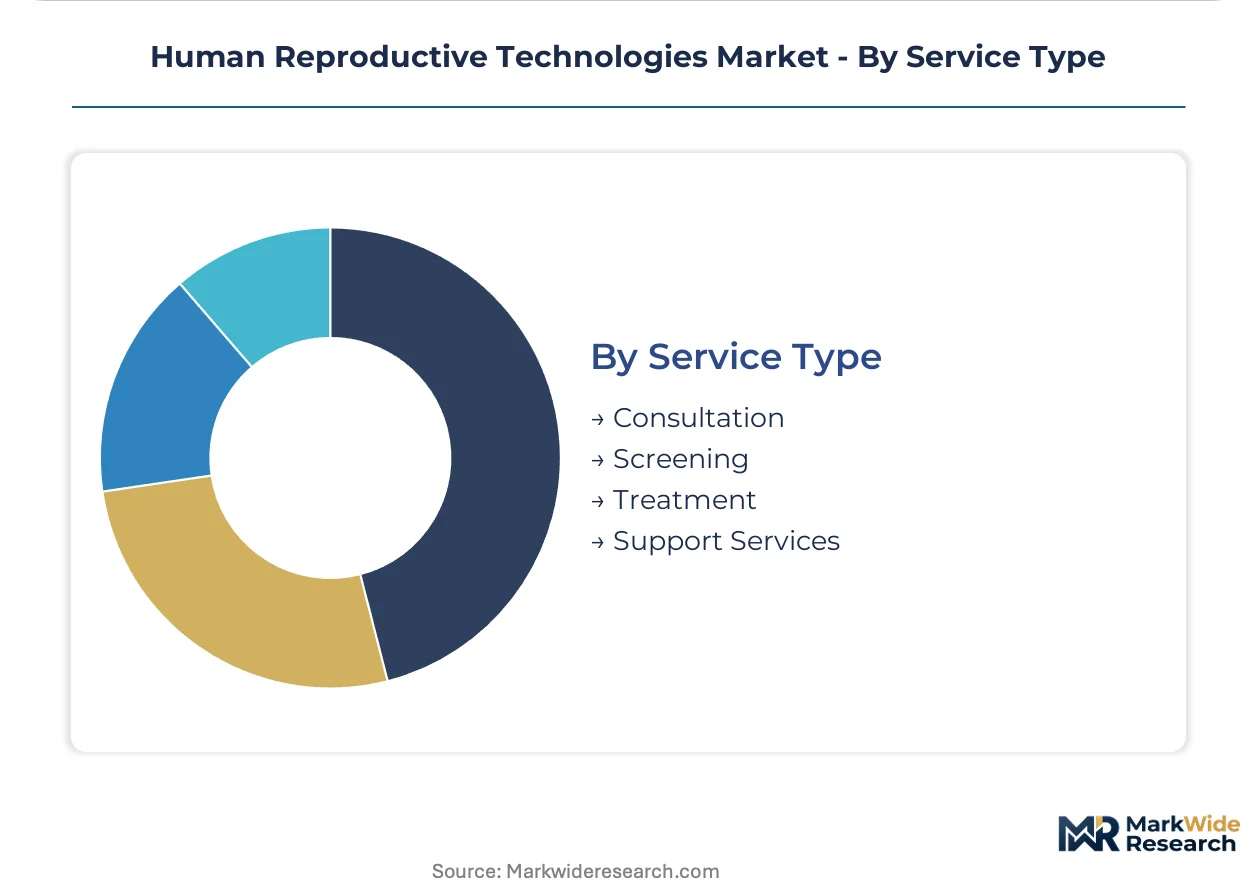
Service Type:
Service bundling and unbundling strategies respond to payer pressure for outcome transparency and episode-based pricing.
- Treatment:Procedure execution including ovarian stimulation, retrieval, and embryo transfer commands the largest fee-for-service revenue pool.
- Screening:Diagnostic workup and genetic assessment create pre-qualified patient pipelines and risk stratification inputs.
- Consultation:Initial reproductive endocrinology evaluation and treatment planning face compression under managed fertility network steerage.
- Support Services:Counseling, nutrition, and acupuncture differentiate premium clinic positioning in competitive metropolitan markets.
Treatment absorbs capital and labor intensity. Screening is where margin expansion concentrates through test menu expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across reproductive healthcare markets. Employer-sponsored benefits in the United States insulate patients from price sensitivity, while out-of-pocket payment structures in India and Latin America compress clinic margins and shape intervention selection.
United States
Large self-insured employers drive volume concentration through managed fertility networks that steer members toward accredited high-throughput clinics. FDA oversight of human cells and tissues shapes device approval pathways, extending review timelines for novel embryo culture media. California and Texas fertility networks pilot direct-to-consumer genetic screening referral partnerships.
Germany
Statutory health insurance reimbursement for medically diagnosed infertility sustains steady procedure demand across academic medical centers and specialized clinics. The EU Tissues and Cells Directive harmonizes quality benchmarks, enabling German laboratories to leverage mutual recognition for streamlined cross-border procurement. Berlin and Munich host high-throughput networks exploiting this regulatory efficiency.
India
Cost sensitivity shapes first-line intervention selection toward lower-complexity intrauterine procedures, with IVF adoption concentrated among affluent urban populations. The country's national pharmaceutical regulator enforces quality standards for gonadotropin imports, though enforcement capacity varies across states. Mumbai, Delhi, and Bangalore host fewer than 300 accredited IVF centers serving a reproductive-age population exceeding 400 million.
Australia
Legal recognition of same-sex marriage and mandated fertility benefit parity expands addressable patient populations beyond traditional infertility diagnoses. The Therapeutic Goods Administration regulates embryo culture media and genetic testing platforms under medical device frameworks. Sydney and Melbourne clinic networks consolidate volume through employer-sponsored elective egg freezing programs.
Spain
Liberal donor anonymity laws and competitive pricing attract cross-border reproductive tourism from elsewhere in Europe and Latin America. The EU Tissues and Cells Directive enables Spanish laboratories to participate in mutual recognition agreements for streamlined media and device procurement. Barcelona and Madrid fertility networks exploit this regulatory positioning to capture international patient flows.
Human Reproductive Technologies Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in human reproductive technologies. Pharmaceutical conglomerates with captive gonadotropin production control upstream supply chains, while specialized device manufacturers concentrate on embryology laboratory infrastructure. Two strategic archetypes dominate: vertically integrated drug-device combinations and pure-play laboratory equipment specialists. Competitive moves center on portfolio diversification into adjacent genetic testing services and geographic expansion through distributor partnerships in underserved Asian markets.
Within the integrated pharmaceutical tier, Merck KGaA and Ferring Pharmaceuticals anchor supply-side concentration through recombinant FSH production capabilities. Thermo Fisher Scientific exemplifies the laboratory infrastructure archetype, controlling access to genetic testing platforms and analytical instrumentation. These three entities represent distinct competitive vectors—upstream hormone supply, downstream laboratory equipment, and integrated platform ecosystems—each shaping procurement patterns for fertility clinic networks.
| Leading Market Players |
|---|
| Merck KGaA |
| Ferring Pharmaceuticals |
| CooperSurgical |
| Thermo Fisher Scientific |
| Vitrolife AB |
| Cook Medical |
| Bayer AG |
| Teva Pharmaceutical Industries |
| Genea |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance requirements for embryo culture media and time-lapse imaging systems gate both supplier qualification and price differentiation simultaneously. Clinics in the United States pay premiums for validated devices while European competitors exploit CE marking speed advantages to undercut on entry-level equipment.
Pricing Analysis
Consumables and extended service contracts generate lifetime value exceeding initial device sales by significant multiples. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14644 Class 7 cleanroom-certified laboratories from satellite facilities and research-grade installations. Price differentiation rests on embryologist training bundling and real-time remote monitoring capabilities. Cost compression in standard-tier media formulations is intensifying because synthetic protein substitute suppliers face REACH disclosure expansion. Employer-sponsored benefit patients show lowest price sensitivity; out-of-pocket markets in India and Latin America demand economy-tier sourcing.
Supply Chain Analysis
Recombinant FSH fermentation capacity concentrates in Switzerland, Denmark, and Germany, creating pharmaceutical chokepoints for gonadotropin-dependent protocols. Media manufacturing draws from pharmaceutical-grade water systems, synthetic serum substitutes, and time-lapse imaging sensors. Single-source vulnerability runs through the three-manufacturer concentration of recombinant hormone production. Distribution runs through fertility clinic networks, hospital procurement consortia, and research institute direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as employer-sponsored fertility benefits create network-tier niches distinct from independent clinic positioning. LGBTQ+ family formation demand and elective egg freezing expand addressable segments beyond traditional infertility reimbursement frameworks.
For Market Incumbents: Compound laboratory automation investments to compress embryologist headcount per cycle while elevating capital barriers for independent competitors. Secure gonadotropin supply allocation agreements before manufacturing disruptions expose volume-dependent networks. Backward integration into AI-based embryo scoring modules protects margin pools threatened by software-as-medical-device entrants. For New Entrants and Emerging Players: CE marking fast-track pathways under EU Tissues and Cells Directive mutual recognition unlock European laboratory procurement before FDA 510(k) timelines conclude. India's accredited IVF center shortage across Mumbai, Delhi, and Bangalore corridors offers the most penetrable geography. Partner with local hospital chains for infrastructure sharing rather than greenfield cleanroom construction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-throughput embryology laboratories as AI-integrated time-lapse systems displace manual grading workflows. Long-term viability favors platform ecosystems combining pharmaceutical supply, device infrastructure, and genetic testing services. Acquisition target archetype: regional clinic networks with employer benefit contracts but deferred automation upgrades. Watch FDA software-as-medical-device classification clarity as inflection indicator for AI embryo scoring valuations.| Strategic Initiative | Industry Significance |
|---|---|
| AI Embryo Scoring Regulatory Submission | FDA software-as-medical-device classification determines commercialization pace for automated morphokinetic analysis platforms. |
| Employer Benefit Network Contracting | Managed fertility network participation concentrates patient volume within accredited high-throughput laboratories. |
| CE Marking Fast-Track Utilization | EU Tissues and Cells Directive mutual recognition accelerates European market entry before United States clearance. |
| Cleanroom Infrastructure Partnership | Shared ISO 14644 Class 7 facilities reduce capital barriers for clinic expansion in underserved metro corridors. |
| Direct-to-Consumer Genetic Screening Integration | At-home carrier testing platforms create pre-qualified patient pipelines for fertility clinic referral networks. |
Study Parameters
Cross-validation between primary interviews with reproductive endocrinologists, embryology laboratory directors, fertility clinic procurement managers, and payer benefit specialists anchors the qualitative findings. Secondary validation incorporates FDA 510(k) filings, EMA device registrations, hospital GPO contract databases, and employer fertility benefit plan documents. Bottom-up cycle volume estimates from accredited clinic networks triangulate against top-down pharmaceutical consumption data for gonadotropin dosing protocols.
Sensitivity analysis on reimbursement rate assumptions and AI regulatory classification timelines frames the projection range. Segmentation dimensions span technology type, application setting, end-user demographic, and service bundling configuration across the modeling period. CAGRs derive from fitted growth curves calibrated to historical procedure volume expansion and pharmaceutical consumption trajectories. Forecast inputs incorporate embryologist training pipeline constraints and cleanroom infrastructure capex intensity thresholds specific to high-throughput laboratory economics.
Decision-makers should treat outputs as directional under sustained employer benefit expansion and stable FDA review timelines; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as preimplantation genetic testing reimbursement decisions and AI-based embryo selection regulatory classifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Global Biosimulation Market
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Biomarker Detection Systems Market
Biomedical Technology
Reverse Transcriptase Enzymes Market
Biomedical Technology
Antibody Library Technology Market
Biomedical Technology
Global Laser Capture Microdissection Market
Biomedical Technology
Global Cell Counting Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
Subcutaneous Biologics Market