
 Multiplex Biomarker Imaging Market | 2026-2036
Multiplex Biomarker Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Multiplex Biomarker Imaging Market Outlook
The multiplex biomarker imaging market is decoupling into two distinct tiers: high-parameter spatial proteomics systems commanding premium pricing versus commoditized immunohistochemistry workflows facing reimbursement compression. Thermo Fisher Scientific anchors the upper tier through its integrated mass cytometry-imaging platforms and captive antibody supply chains. Akoya Biosciences specializes in codified, FDA-cleared imaging panels that streamline clinical translation for pharmaceutical partners.
Multiplex biomarker imaging refers to techniques that simultaneously detect and localize multiple protein, RNA, or DNA targets within intact tissue sections, typically resolving 40 to 100-plus analytes per slide using metal-isotope reporters or spectrally unmixed fluorophores. Its primary purpose is to map cellular heterogeneity and immune infiltration patterns for therapeutic development and diagnostic stratification. Immunohistochemistry retains the largest installed base but imaging mass cytometry captures the fastest expansion as pharma sponsors demand whole-slide spatial profiling for immuno-oncology trials. Fluorescence-based multiplexing occupies the broadest academic access point, though margin pools concentrate in the proteomics segment where reagent pull-through economics dominate.
FDA 510(k) and premarket approval pathways shape instrument validation requirements, while the Clinical Laboratory Improvement Amendments govern assay deployment in diagnostic settings. ISO 13485 certification and the EU In Vitro Diagnostic Regulation create parallel compliance burdens for vendors serving dual markets. Stakeholders must monitor how CMS coverage determinations for tissue-based companion diagnostics reshape the addressable clinical volume versus the research-funded installed base.
Market Dynamics
The multiplex biomarker imaging market is bifurcating around a single structural force: pharmaceutical sponsors now mandate whole-slide spatial profiling data packages for immuno-oncology trial submissions, compressing validation timelines and privileging vendors with integrated hardware-software-reagent stacks.
Growth Catalysts
- FDA accelerated approval pathways:The FDA's expanded access programs for companion diagnostics compress clinical validation timelines from years to months, forcing CROs to pre-qualify imaging vendors with 510(k)-cleared platforms.
- Metal-isotope reporter technology:Imaging mass cytometry using lanthanide-tagged antibodies now resolves 40-plus protein targets per tissue section, replacing iterative immunohistochemistry workflows in pharma translational research.
- Boston-San Francisco corridor concentration:Academic medical centers clustered around these biotech hubs account for disproportionate instrument procurement volume, creating localized demand pull-through for high-parameter spatial proteomics systems.
Market Restraints
- Helium supply volatility:Imaging mass cytometry relies on helium-cooled detectors; price spikes in this noble gas input directly compress instrument margins and extend lead times for new installations.
- Antibody supply concentration:Validated metal-conjugated antibody clones are captive to a narrow supplier base, creating single-source risk for panel standardization across multi-site clinical trials.
- CLIA complexity for LDT deployment:The Clinical Laboratory Improvement Amendments impose proficiency testing burdens on laboratories developing laboratory-developed tests, slowing clinical translation of research-grade multiplex panels.
Strategic Opportunities
- EU IVDR harmonization:The In Vitro Diagnostic Regulation creates a unified 27-country certification pathway for CE-marked imaging assays, reducing fragmentation for vendors seeking European clinical market entry.
- AI-integrated image analysis:Machine learning algorithms for automated cell phenotyping are converging with multiplex imaging hardware, enabling software-as-a-service revenue models that decouple from instrument placement cycles.
- Research Triangle Park expansion:North Carolina's biopharma cluster is emerging as a third demand pole alongside Boston and San Francisco, with new translational medicine institutes creating greenfield instrument procurement opportunities.
Industry Challenges
- Computational pathology talent scarcity:Multiplex image analysis requires hybrid expertise in tissue biology and machine learning; this skill intersection commands premium compensation and extends hiring timelines.
- ISO 13485 certification burden:Dual certification for FDA and EU markets demands parallel quality management systems, diverting engineering resources from product development cycles.
- Legacy LIS integration friction:Hospital laboratory information systems use non-standardized data formats, forcing custom middleware development for multiplex imaging workflow integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiplex Biomarker Imaging Market |
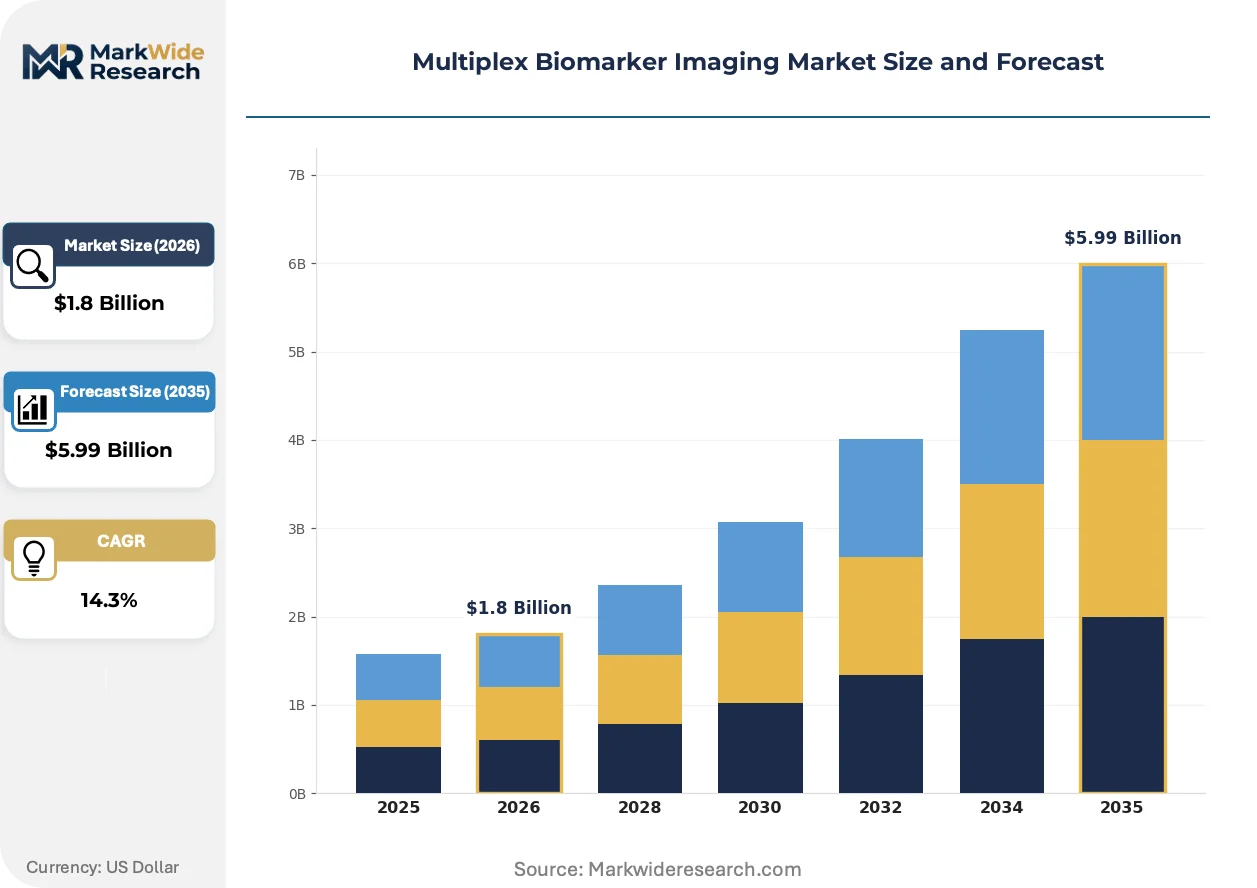
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunohistochemistry, In Situ Hybridization, Proteomics, Multiplex Assays Technology: Fluorescence, Mass Cytometry, RNA Sequencing, Imaging Mass Cytometry End User: Pharmaceutical Companies, Academic Research Institutions, Clinical Laboratories, Diagnostics Providers Application: Oncology Research, Neurological Studies, Infectious Disease Studies, Drug Development |
| Companies Covered | Merck KGaA, Illumina, Inc., Thermo Fisher Scientific Inc., Leica Biosystems Nussloch GmbH, Akoya Biosciences, Inc., PerkinElmer Inc., Abcam plc, Bio-Techne Corporation, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiplex Biomarker Imaging Market Strategic Shifts
Spatial biology instrumentation is undergoing platform consolidation as sponsors demand end-to-end solutions spanning sample preparation through regulatory-grade data packages, collapsing the historical separation between research and clinical-grade systems.
Fluorescence-based cyclic immunofluorescence is decentralizing tissue analysis by enabling 100-plus plex imaging on standard epifluorescence microscopes without specialized mass cytometry infrastructure. Academic pathology departments and regional hospital systems are adopting these workflows at three-year replacement cycles for conventional immunohistochemistry instruments. This diffusion is compressing the addressable market for premium-priced imaging mass cytometry systems in settings below pharma-scale throughput.
The EU In Vitro Diagnostic Regulation's 2022 implementation timeline is reshaping vendor commercialization sequencing by prioritizing CE-marked assay panels over research-use-only reagents. Manufacturers are redirecting R&D budgets toward clinical validation studies and notified body engagement. Mid-sized European diagnostic laboratories are deferring instrument purchases pending clarity on IVDR-compliant panel availability, creating a temporary demand trough in Germany and France.
Pharmaceutical procurement teams are unbundling after-sales service contracts from instrument leases, negotiating direct antibody supply agreements and cloud-based analysis subscriptions separately. This disintermediation of the traditional bundled pricing model is most visible in United States-based biopharma headquarters, where procurement functions have centralized under chief financial officer oversight. Vendors now face margin compression on service attach rates while competing for recurring reagent revenue on open-platform instruments.
Multiplex Biomarker Imaging Market Segmentation
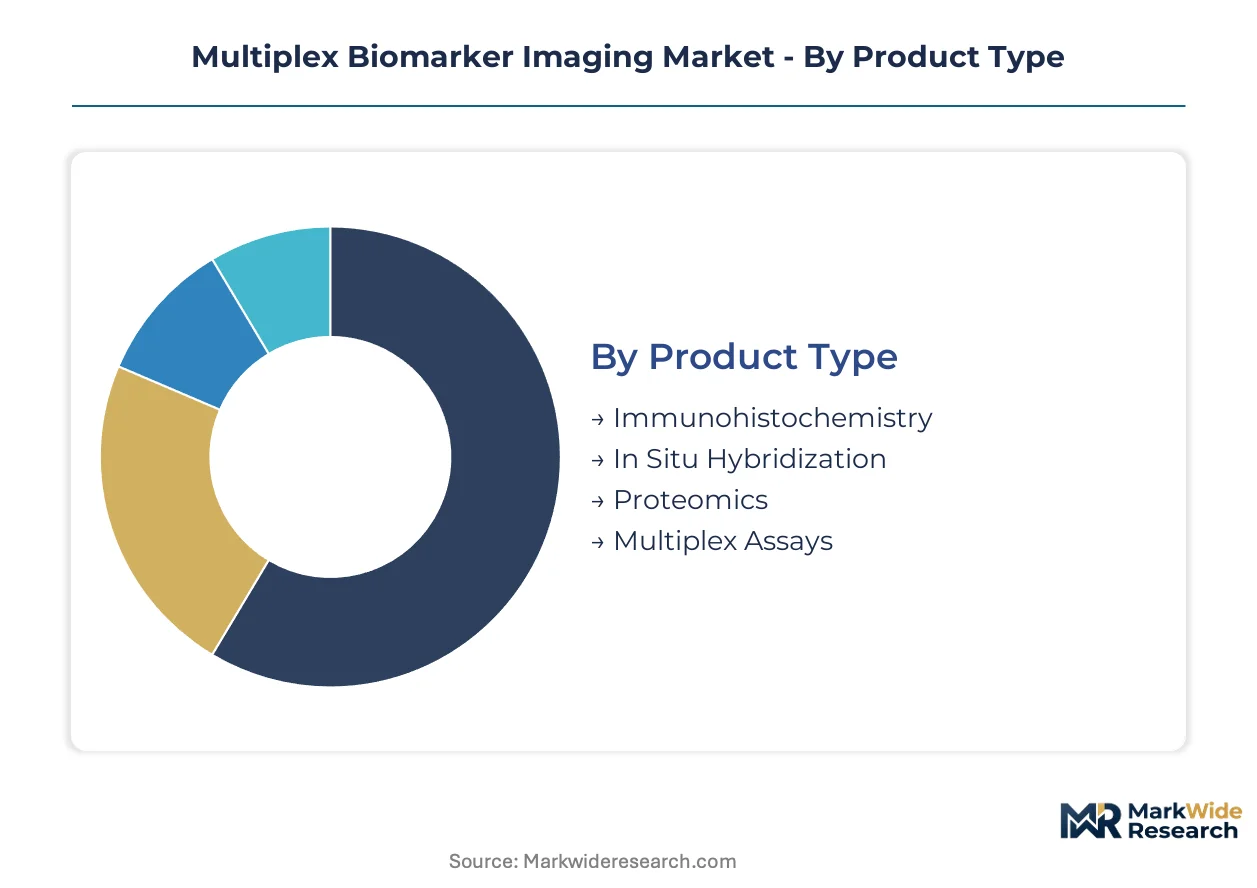
Multiplex biomarker imaging segments diverge sharply between standardized clinical workflows and configurable research platforms. Procurement patterns in pharmaceutical settings favor integrated systems with locked reagent menus, while academic buyers prioritize modular architectures that accommodate experimental antibody panels.
Product Type:
Customization intensity varies from rigid FDA-cleared assay kits to open-architecture proteomics workstations that accept user-conjugated metal tags.
- Immunohistochemistry:Chromogenic detection of single protein targets using enzyme-conjugated secondary antibodies remains the clinical reference standard. Hospital pathology departments in the United States deploy these workflows under CLIA proficiency requirements, though reimbursement compression is forcing consolidation toward higher-plex alternatives.
- Proteomics:High-parameter spatial analysis resolves 40-plus protein targets per tissue section through metal-isotope reporters or spectral unmixing. Pharmaceutical sponsors in Boston and San Francisco now mandate whole-slide proteomics data packages for immuno-oncology trial submissions, displacing iterative single-stain workflows.
- In Situ Hybridization:DNA and RNA target detection within intact tissue architecture using labeled nucleic acid probes.
- Multiplex Assays:Pre-validated antibody cocktails optimized for specific disease indications or therapeutic mechanisms.
Leading the category by volume: Immunohistochemistry. Expanding most quickly: Proteomics.
Technology:
Capital intensity separates fluorescence-based methods deployable on existing microscopes from mass cytometry platforms requiring specialized helium-cooled detectors and dedicated facilities.
- Imaging Mass Cytometry:Laser ablation of metal-tagged tissue sections coupled to time-of-flight mass spectrometry achieves single-cell resolution without spectral overlap. Helium supply volatility directly constrains instrument margins and installation lead times for vendors serving United States biopharma clusters.
- Fluorescence:Cyclic immunofluorescence using spectrally unmixed organic dyes enables 100-plus plex imaging on standard epifluorescence microscopes. Academic medical centers adopt these workflows at three-year replacement cycles, decentralizing tissue analysis without mass cytometry infrastructure investments.
- Mass Cytometry:Suspension-based single-cell proteomics adapted for imaging applications through tissue ablation interfaces.
- RNA Sequencing:Spatial transcriptomics mapping gene expression patterns across tissue sections using capture arrays or in situ sequencing.
Highest installed base: Fluorescence. Steepest expansion trajectory: Imaging Mass Cytometry.
End User:
Procurement centralization under chief financial officer oversight at pharmaceutical headquarters is fragmenting traditional bundled service contracts.
- Pharmaceutical Companies:Translational medicine groups sponsor multi-site clinical trials requiring standardized panel deployment across contract research organizations. These buyers unbundle instrument leases from antibody supply agreements and cloud-based analysis subscriptions, compressing vendor service attach rates.
- Academic Research Institutions:Principal investigators prioritize experimental flexibility over regulatory clearance, driving demand for open-platform instruments compatible with investigator-conjugated antibody panels. Research Triangle Park institutes are emerging as concentrated procurement poles alongside established Boston and San Francisco corridors.
- Clinical Laboratories:Hospital-based pathology services constrained by CLIA proficiency testing and laboratory information system integration requirements.
- Diagnostics Providers:Commercial reference laboratories developing laboratory-developed tests under FDA enforcement discretion policies.
Dominant revenue concentration: Pharmaceutical Companies. Gaining share fastest: Academic Research Institutions.
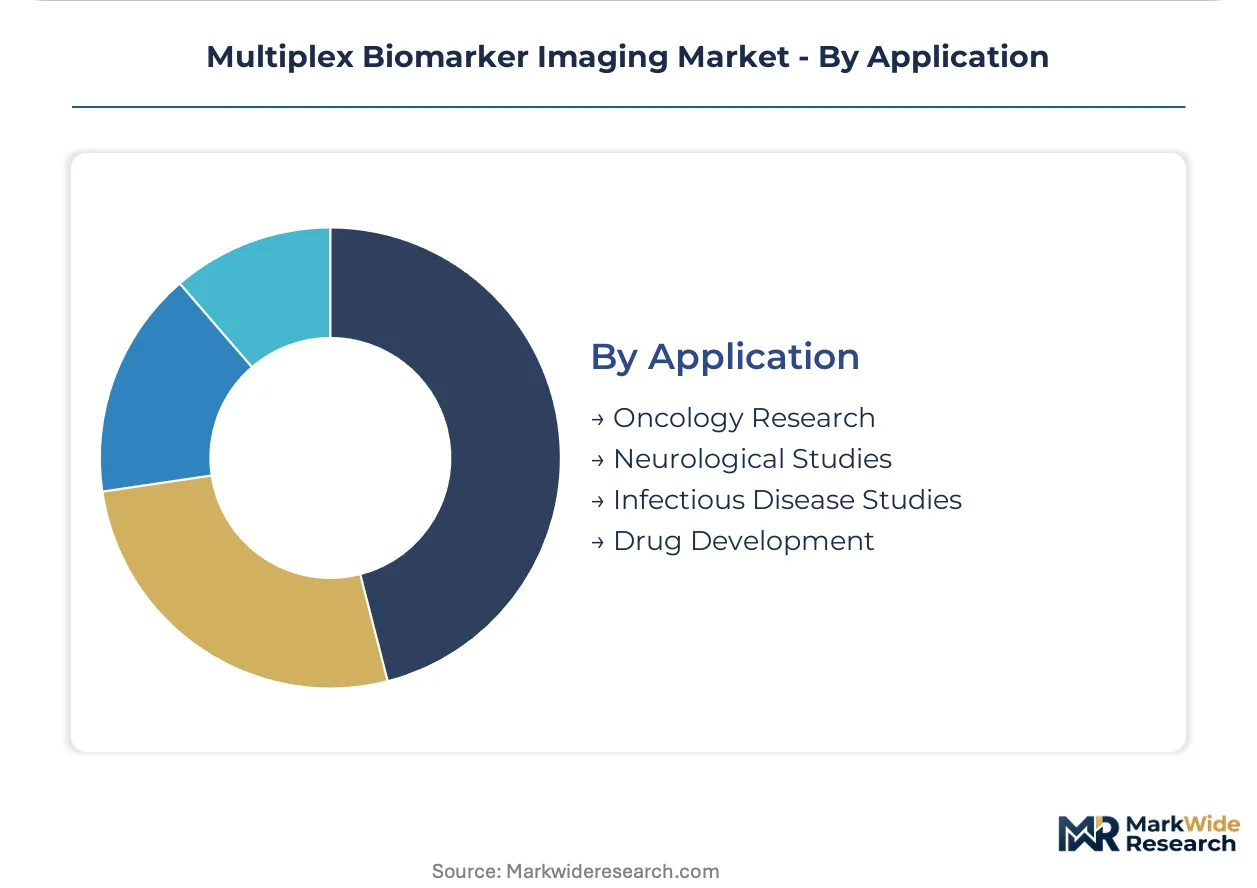
Application:
Therapeutic area maturity determines whether multiplex imaging serves exploratory biomarker discovery or locked companion diagnostic validation.
- Oncology Research:Immune infiltration profiling and tumor microenvironment mapping for checkpoint inhibitor development commands the largest reagent pull-through volumes. FDA accelerated approval pathways for tissue-based companion diagnostics compress validation timelines from years to months, privileging vendors with 510(k)-cleared platforms.
- Drug Development:Pharmacodynamic biomarker readouts across preclinical and clinical phases require harmonized assay transfer from research to regulated settings. ISO 13485 certification and EU IVDR compliance create parallel quality burdens for vendors serving dual United States and European markets.
- Neurological Studies:Neuroinflammatory marker mapping and protein aggregation analysis in neurodegenerative disease models.
- Infectious Disease Studies:Host-pathogen interaction visualization and immune response characterization in tissue reservoirs.
Largest addressable volume: Oncology Research. Climbing the fastest: Drug Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston, San Francisco, and Research Triangle Park concentrate the highest instrument procurement volumes for multiplex biomarker imaging systems. Academic medical centers and biopharma headquarters cluster around these three metropolitan areas. FDA accelerated approval pathways for companion diagnostics compress validation timelines from years to months.
United States
Pharmaceutical sponsors in Boston and San Francisco now mandate whole-slide spatial profiling data packages for immuno-oncology trial submissions. FDA 510(k) clearance requirements privilege vendors with integrated hardware-software-reagent stacks. Research Triangle Park institutes in North Carolina are emerging as a third concentrated demand pole alongside the two coastal corridors.
Germany
Mid-sized European diagnostic laboratories are deferring instrument purchases pending clarity on IVDR-compliant panel availability. The EU In Vitro Diagnostic Regulation creates a unified 27-country certification pathway for CE-marked imaging assays. Berlin-Brandenburg and Munich-Stuttgart clusters house notified body engagement teams redirecting R&D budgets toward clinical validation studies.
United Kingdom
London-based translational medicine institutes drive demand for open-platform instruments compatible with investigator-conjugated antibody panels. MHRA alignment with EU IVDR timelines shapes vendor commercialization sequencing for the British market. The Oxford-Cambridge-London golden triangle concentrates academic pathology departments adopting cyclic immunofluorescence workflows.
China
NMPA regulatory harmonization with international standards is reshaping import qualification requirements for imaging mass cytometry platforms. Shanghai and Beijing biotech parks are incubating domestic spatial proteomics ventures. Yangtze River Delta medical centers are deploying fluorescence-based multiplexing at three-year replacement cycles for conventional immunohistochemistry instruments.
Japan
PMDA consultation procedures for companion diagnostics are compressing pre-submission timelines for tissue-based assay developers. Tokyo and Osaka academic medical centers prioritize experimental flexibility over regulatory clearance in procurement decisions. Kansai region pathology departments represent concentrated installed bases for chromogenic detection workflows facing reimbursement compression toward higher-plex alternatives.
Multiplex Biomarker Imaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across the certification-grade divide, with FDA-cleared and CE-marked platforms commanding pricing multiples over research-use-only configurations. The vendor base stratifies into three archetypes: diversified life science conglomerates with captive antibody supply chains, specialized spatial biology platform developers with codified clinical panels, and reagent-focused suppliers providing metal-conjugated antibody clones. Dominant competitive moves include unbundling of after-sales service contracts from instrument leases and direct negotiation of antibody supply agreements separate from hardware procurement.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Merck KGaA exemplify players with integrated mass cytometry-imaging platforms and vertical control over critical input supply. Among specialized platform developers, Akoya Biosciences, Inc. occupies a position defined by FDA-cleared imaging panels that streamline clinical translation. Illumina, Inc. represents the sequencing-anchored archetype extending into spatial transcriptomics applications. These three named entities collectively illustrate how certification status and supply chain configuration determine margin tier placement in sponsor procurement evaluations.
| Leading Market Players |
|---|
| Merck KGaA |
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| Leica Biosystems Nussloch GmbH |
| Akoya Biosciences, Inc. |
| PerkinElmer Inc. |
| Abcam plc |
| Bio-Techne Corporation |
| Bio-Rad Laboratories, Inc. |
| Others |
Value Chain & Pricing Dynamics
EU IVDR sustainability mandates for clinical-grade reagent traceability gate qualified supply access and premium-tier pricing eligibility for vendors serving dual United States and European markets. Helium-cooled detector maintenance costs and metal-conjugated antibody validation burdens concentrate pricing power among integrated platform developers with captive supply chains.
Pricing Analysis
Value-based pricing anchored to trial submission throughput and regulatory clearance speed dominates pharmaceutical procurement evaluations. Three-tier pricing structure across FDA-cleared, CE-marked, and research-use-only configurations separates premium proteomics platforms from commoditized immunohistochemistry workflows. Pricing pressure stems from procurement centralization under chief financial officer oversight at biopharma headquarters unbundling service contracts. Academic research institutions exhibit highest price sensitivity due to grant-funded capital constraints, while pharmaceutical sponsors prioritize validation speed over unit cost.
Supply Chain Analysis
Warehouse-distribution layer concentration around Boston, San Francisco, and Research Triangle Park creates hub-and-spoke patterns for instrument deployment and reagent replenishment. Metal-isotope reporter production draws from United States and German specialty chemical suppliers, while helium for detector cooling sources from Qatar and United States extraction facilities. Single-source vulnerability for validated metal-conjugated antibody clones threatens multi-site clinical trial standardization. Distribution runs through direct vendor-to-laboratory contracts for high-parameter systems and regional distributors for fluorescence-based platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multiplex biomarker imaging market functions as a vertical-integration race where control over metal-conjugated antibody supply chains and cloud-based analysis software determines margin capture. Players are pursuing backward integration into reagent manufacturing to lock in panel standardization advantages.
For Market Incumbents: Lock in antibody supply exclusivity through long-term clone licensing agreements with hybridoma developers to neutralize emerging open-platform competitors. Invest in ISO 13485 dual-certification infrastructure to preempt EU IVDR compliance gaps that would disqualify rivals from European clinical procurement. Defend service attach rates by embedding AI-integrated image analysis subscriptions into instrument lease structures before procurement functions complete their unbundling transition.
For New Entrants and Emerging Players: Capture cyclic immunofluorescence replacement cycles at academic medical centers in Research Triangle Park and Midwestern hospital systems underserved by mass cytometry field service networks. Target regional pathology departments with three-year immunohistochemistry instrument refresh timelines by offering 100-plus plex capability without helium infrastructure requirements. Deploy software-as-a-service revenue models for automated cell phenotyping to decouple from capital-intensive instrument placement competition.
For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for tissue-based companion diagnostics is the leading indicator that regulatory-grade platform developers will command acquisition premiums over research-use-only instrument vendors. Position holdings around five-to-ten year windows where spatial proteomics transitions from exploratory biomarker discovery to locked companion diagnostic validation. Monitor helium supply contract renegotiations as signals of margin compression vulnerability among imaging mass cytometry incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Antibody Supply Chain Integration | Captive metal-conjugated clone production secures panel standardization for multi-site pharma trials. |
| AI-Integrated Image Analysis Launch | Machine learning cell phenotyping enables recurring SaaS revenue independent of instrument sales cycles. |
| EU IVDR Certification Pathway | CE-marked assay panels unlock 27-country clinical market access ahead of research-use-only competitors. |
| Helium Detector Alternative Development | Cooling technology substitution mitigates noble gas supply volatility compressing instrument margins. |
| Research Triangle Park Expansion | North Carolina translational medicine institutes represent greenfield demand for spatial proteomics systems. |
Study Parameters
Independent corroboration across translational medicine executives, regulatory affairs leads at imaging platform vendors, hospital pathology department heads, and contract research organization procurement managers underwrites the qualitative findings. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA IVDR submission databases, ClinicalTrials.gov protocol specifications, and hospital GPO contract records establish demand-side ground truth. Bottom-up instrument placement tracking and top-down reagent revenue estimates triangulate market sizing across the analysis window.
Comparable-period anchoring to historical pharma translational research spending patterns and academic medical center capital equipment cycles informs the projection horizon. Segmentation dimensions span product type, technology platform, end-user archetype, and therapeutic application area, with regional regulatory cluster differentiation for United States and European market modeling. CAGRs derive from reagent pull-through economics and replacement cycle timing rather than instrument placement velocity alone. Forecast inputs incorporate helium supply contract pricing trends and FDA accelerated approval pathway utilization rates.
The model holds under sustained pharmaceutical R&D prioritization of immuno-oncology and stable CLIA proficiency testing requirements; deviation in CMS reimbursement policy for tissue-based companion diagnostics or EU IVDR enforcement discretion would shift addressable clinical volume assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
Global Oncology Based in-Vivo CRO Market
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Imaging Biomarkers Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Bacteriophage Market
Biomedical Technology
Biochips Market
Biomedical Technology
Inhalable Biologics Market
Biomedical Technology
ST2 Biomarker Market
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
Ubiquitin Proteasome Market
Biomedical Technology
Bioprocess Technology Market