
 Global Immunofluorescence Assay Market | 2026-2036
Global Immunofluorescence Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immunofluorescence Assay Market Foresight
Reagent aftermarket revenue is reconfiguring margin pools away from instrument sales toward recurring consumables and assay protocol subscriptions. Thermo Fisher Scientific leverages its channel density to lock in multi-year reagent supply contracts with hospital networks. Merck KGaA anchors its position through backward integration into fluorophore chemistry, controlling critical dye supply chains. Bio-Rad Laboratories competes by sustaining open-platform compatibility, enabling laboratories to mix reagent sources without full system replacement.
Immunofluorescence assay denotes a light-microscopy technique wherein antibodies conjugated to fluorescent dyes bind target antigens in fixed cells or tissue sections, with excitation-emission spectra typically spanning 490–650 nanometers for visible-range detection. The method serves primarily to localize proteins, map subcellular structures, and score diagnostic biomarkers in clinical pathology workflows. Indirect immunofluorescence occupies the largest installed base due to signal amplification and protocol flexibility, though quantum dot conjugates represent the fastest-growing technology segment because of photostability and multiplexing depth. Oncology applications concentrate the highest per-test value, while autoimmune disorder testing sustains the highest procedure volume across diagnostic laboratories.
The FDA's in vitro diagnostic regulations and the EU IVDR impose escalating analytical validation requirements on fluorescence-based assays, forcing manufacturers to invest in clinical evidence generation for premarket submissions. China's NMPA has tightened registration pathways for imported immunodiagnostics, creating preferential market access for domestic assay developers with localized manufacturing. Stakeholders must monitor how regulatory divergence across the FDA, EMA, and NMPA reshapes product registration timelines and go-to-market sequencing.
Market Dynamics
The reagent aftermarket is reconfiguring margin pools away from instrument sales toward recurring consumables and assay protocol subscriptions, locking hospital networks into multi-year supply contracts and fluorophore supply chains.
Growth Catalysts
- Autoimmune disorder panel expansion:Clinical diagnostic laboratories are scaling immunofluorescence testing for lupus, rheumatoid arthritis, and vasculitis screening, driving procedure volume in tertiary care centers.
- EU IVDR analytical validation mandates:Tightened fluorescence-based assay requirements are accelerating manufacturer investment in clinical evidence generation, raising barriers that favor established reagent suppliers with regulatory infrastructure.
- Quantum dot conjugate photostability:Nanocrystal fluorophores with superior resistance to photobleaching enable extended imaging sessions and multiplexed biomarker panels in oncology pathology workflows.
Market Restraints
- Fluorophore supply concentration:Critical dye chemistry remains controlled by a narrow set of European and North American chemical suppliers, exposing assay manufacturers to input cost volatility and allocation risk.
- FDA premarket submission timelines:Escalating analytical validation requirements for fluorescence-based diagnostics extend product registration cycles, compressing revenue recognition windows for new assay launches.
- Chromogenic IHC substitution threat:Enzyme-based detection methods with simpler workflow requirements continue displacing immunofluorescence in routine diagnostic settings where spectral unmixing is unnecessary.
Strategic Opportunities
- China NMPA localization incentives:Tightened registration pathways for imported immunodiagnostics create preferential market access for domestic assay developers with captive manufacturing in Shanghai and Suzhou clusters.
- Digital pathology convergence:Whole-slide imaging platforms are integrating fluorescence signal capture, enabling remote diagnostic interpretation and algorithm-assisted biomarker quantification.
- Point-of-care autoimmune testing:Miniaturized fluorescence readers and dried-reagent cartridges open ambulatory clinic deployment for rapid antinuclear antibody screening outside hospital laboratory networks.
Industry Challenges
- Multiplex assay standardization gaps:Absence of universal reference materials for spectral unmixing creates inter-laboratory variability in biomarker scoring, complicating multi-site clinical trial enrollment.
- Legacy microscope fleet integration:Pathology laboratories face capital-intensive retrofit requirements to upgrade mercury arc lamp systems to LED excitation sources compatible with modern fluorophore panels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immunofluorescence Assay Market |
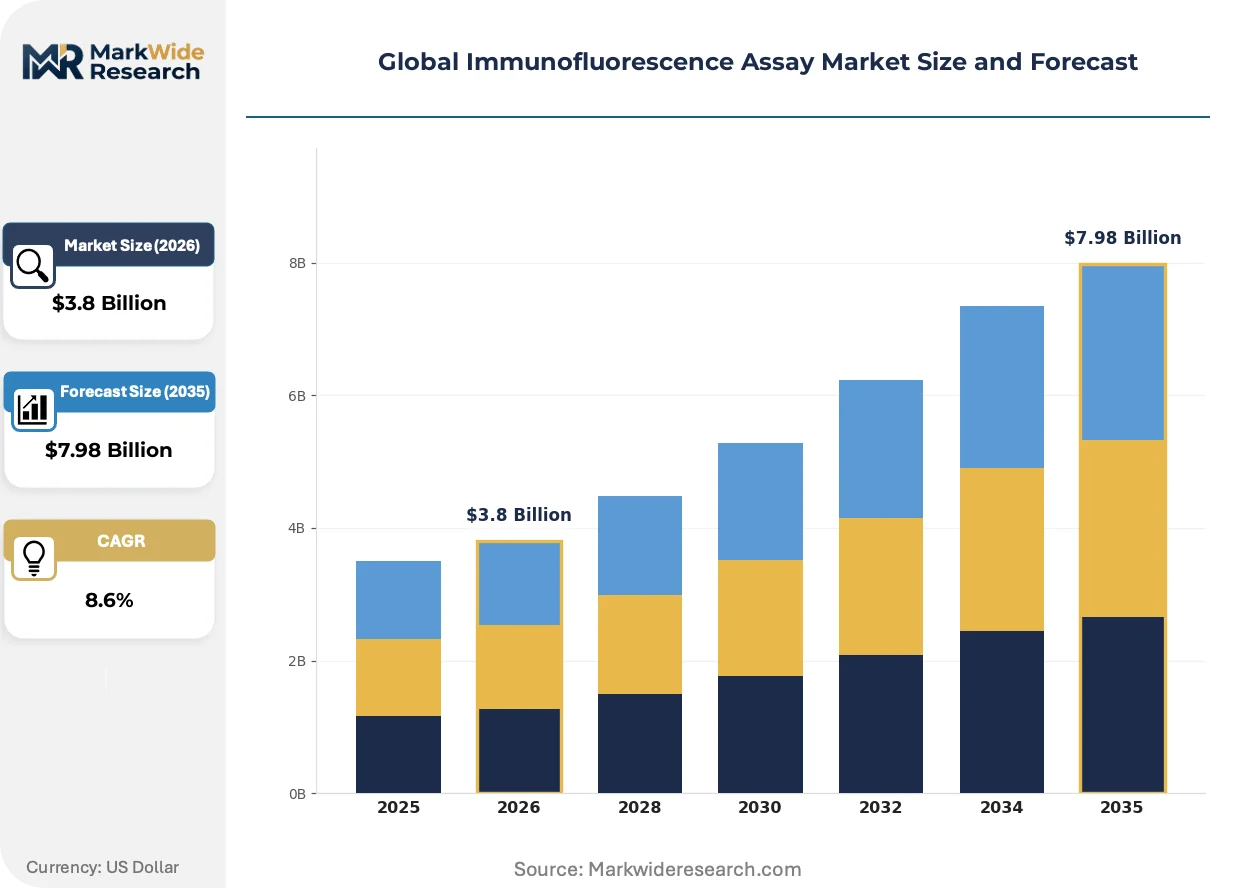
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Immunofluorescence, Indirect Immunofluorescence, Flow Cytometry, Western Blotting Application: Autoimmune Disorders, Infectious Diseases, Oncology, Neurological Disorders, Dermatology End User: Diagnostic Laboratories, Research Institutes, Hospitals, Biopharmaceutical Companies Technology: Fluorescein Isothiocyanate, Rhodamine, Alexa Fluor, Quantum Dots |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Bio-Rad Laboratories, Danaher Corporation, Abcam, PerkinElmer, Cell Signaling Technology, Agilent Technologies, Werfen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immunofluorescence Assay Market Shifts & Advancements
Artificial intelligence and spectral imaging hardware are compressing diagnostic turnaround times while regulatory divergence across FDA, EMA, and NMPA jurisdictions is fragmentating product development roadmaps.
Multispectral imaging systems with automated spectral unmixing algorithms are digitizing fluorescence signal interpretation in anatomic pathology laboratories. Academic medical centers in Germany and the United States are deploying these platforms for renal biopsy immune complex classification. The technology is digitizing diagnostic workflows by eliminating manual filter cube switching and enabling batch processing of autoimmune panels overnight.
China's NMPA has tightened registration pathways for imported immunodiagnostics, mandating localized clinical trials and manufacturing audit trails for premarket approval. Domestic assay developers in Suzhou and Shanghai are capturing preferential review timelines and hospital procurement list placement. Multinational manufacturers are responding through joint ventures with Chinese fluorophore chemistry suppliers to satisfy domestic content requirements.
Hospital network consolidation is compressing reagent procurement decisions into centralized pathology service line committees. Integrated delivery networks in the United States are unbundling instrument purchases from consumable supply contracts, enabling multi-vendor reagent sourcing on open-platform microscopes. This pattern is most visible in Texas and Florida health systems where laboratory consolidation has reduced distinct supplier relationships by half.
Global Immunofluorescence Assay Market Segmentation
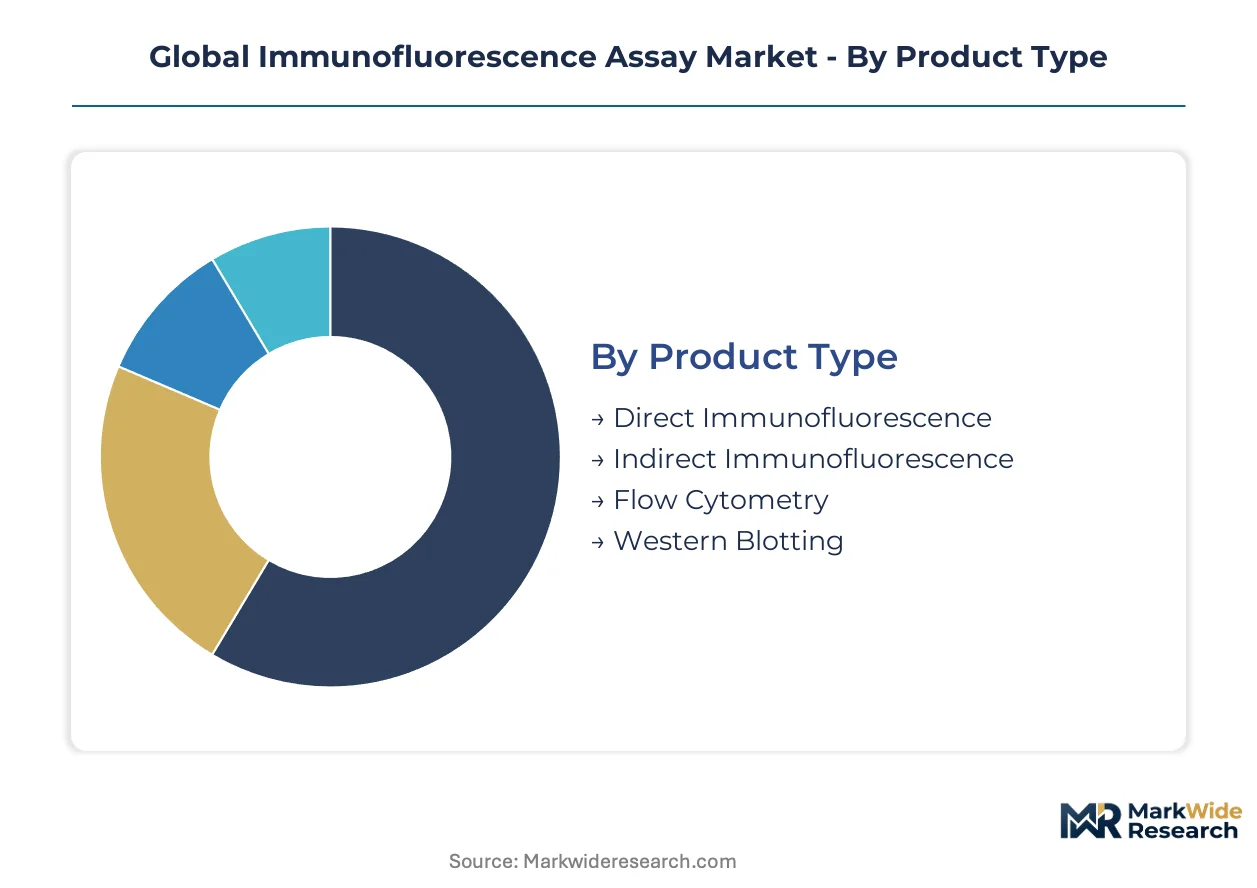
Immunofluorescence assay segmentation reveals distinct margin profiles across reagent formats, with consumable intensity varying sharply between clinical diagnostic and research applications. Product architecture and fluorophore chemistry choices determine recurring revenue potential and regulatory pathway complexity.
Product Type:
After-sales-service intensity peaks with indirect immunofluorescence platforms, where protocol optimization and antibody panel validation create multi-year technical support relationships.
- Direct Immunofluorescence:Primary antibody-fluorophore conjugates eliminate secondary amplification steps, reducing protocol time in clinical laboratories processing high-volume autoimmune panels. Demand concentrates in German hospital pathology networks seeking workflow standardization under EU IVDR compliance timelines.
- Indirect Immunofluorescence:Signal amplification through secondary antibody layers enables detection of low-abundance antigens with flexible fluorophore selection. Tertiary care centers in the United States leverage this format for complex autoimmune disorder profiling where diagnostic sensitivity thresholds are stringent.
- Flow Cytometry:Suspension-based fluorescence detection serves hematological malignancy screening in academic medical centers.
- Western Blotting:Protein separation and immunodetection for research validation of antibody specificity.
Indirect immunofluorescence holds the largest share; momentum sits with quantum dot conjugates gaining traction in multiplex oncology panels.
Application:
Cost tier stratification separates high-value oncology biomarker scoring from high-volume autoimmune screening, with per-test economics diverging by an order of magnitude.
- Autoimmune Disorders:Antinuclear antibody and anti-neutrophil cytoplasmic antibody testing sustains the highest procedure volume across diagnostic laboratory networks. Chinese tertiary hospitals are expanding lupus and vasculitis screening capacity under NMPA diagnostic reimbursement reforms.
- Oncology:HER2, PD-L1, and multiplexed immune checkpoint scoring commands premium pricing in anatomic pathology workflows. United States cancer centers are deploying spectral imaging platforms for biomarker quantification in clinical trial enrollment.
- Infectious Diseases:Viral antigen detection in respiratory and tropical disease panels.
- Neurological Disorders:Neurodegenerative protein aggregate characterization in research settings.
- Dermatology:Direct immunofluorescence of skin biopsies for bullous disease diagnosis.
Autoimmune disorder testing holds the largest share; momentum sits with oncology applications where digital pathology integration is climbing fastest.
End User:
Customer type determines procurement authority, with hospital network consolidation shifting purchasing decisions toward centralized pathology service line committees.
- Diagnostic Laboratories:High-throughput autoimmune panel processing with automated slide staining platforms. Independent reference laboratories in Texas and Florida health systems are consolidating reagent sourcing onto open-platform microscopes.
- Hospitals:Integrated anatomic pathology services with subspecialty immunohistochemistry and immunofluorescence capabilities. German university hospitals are retrofitting mercury arc lamp systems to LED excitation sources compatible with modern fluorophore panels.
- Research Institutes:Basic science applications with protocol customization requirements.
- Biopharmaceutical Companies:Companion diagnostic development and clinical trial biomarker validation.
Diagnostic laboratories hold the largest share; momentum sits with hospital-based pathology networks capturing outpatient referral volumes.
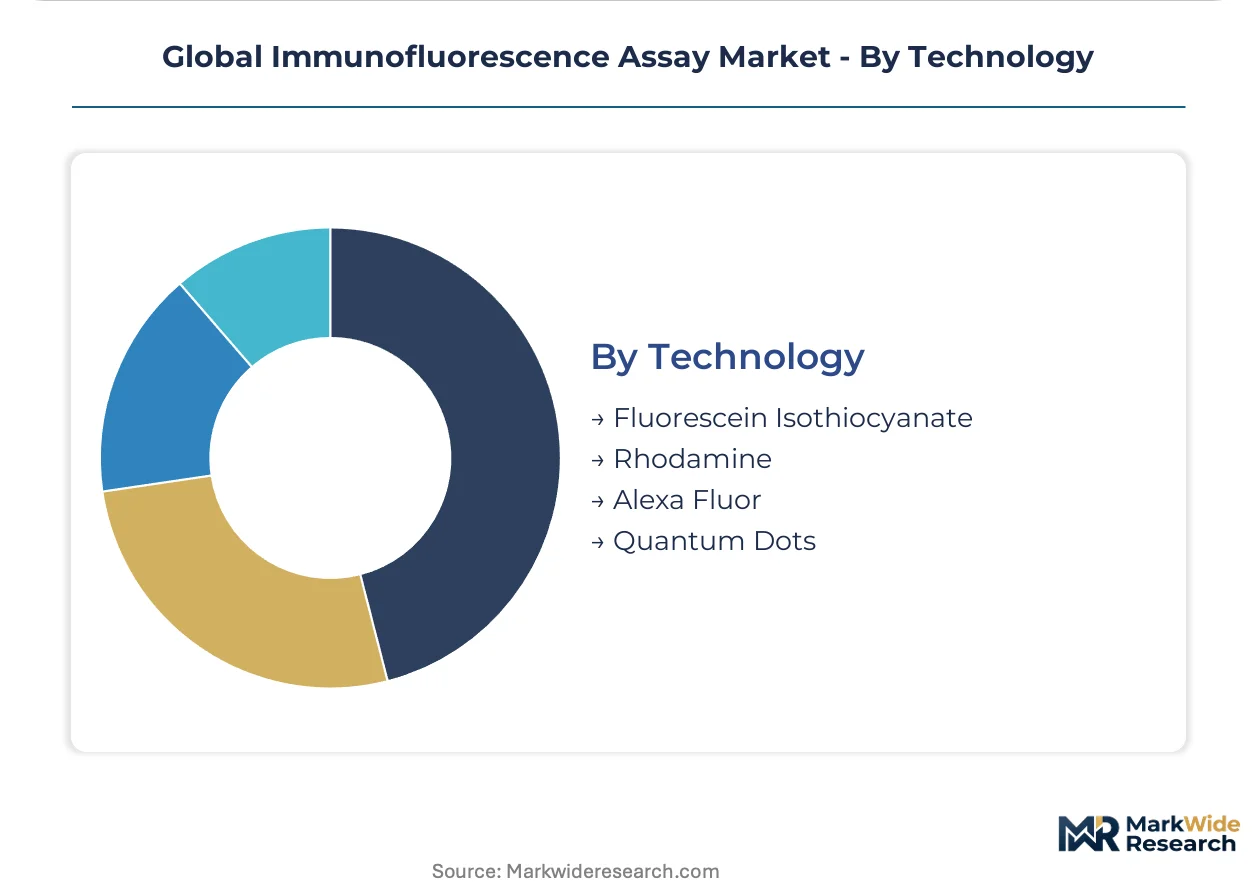
Technology:
Supply concentration in fluorophore chemistry creates margin pressure, with dye manufacturing controlled by narrow European and North American chemical suppliers.
- Quantum Dots:Nanocrystal fluorophores with photostability enabling extended imaging sessions and spectral multiplexing. Oncology pathology workflows in the United States are adopting cadmium-free quantum dot conjugates for six-color and eight-color biomarker panels.
- Alexa Fluor:Sulfonated xanthene dyes with improved photostability and pH insensitivity across physiological ranges. Commercial assay manufacturers favor this chemistry for standardized diagnostic kits requiring lot-to-lot consistency.
- Fluorescein Isothiocyanate:Legacy fluorescein derivative with established clinical validation but photobleaching limitations.
- Rhodamine:Red-emitting fluorophore for dual-label experiments with FITC in conventional filter cube configurations.
Fluorescein isothiocyanate holds the largest installed base; momentum sits with quantum dots expanding most quickly in multiplex applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Hospital networks in the United States absorb premium pricing for multiplex oncology panels, while Chinese diagnostic laboratories prioritize reagent cost efficiency in high-volume autoimmune screening.
United States
Cancer centers in Boston and Houston drive spectral imaging adoption for HER2 and PD-L1 quantification in clinical trials. The FDA's escalating premarket submission requirements for fluorescence-based assays compress revenue recognition windows for new product launches. Thermo Fisher Scientific leverages channel density to lock multi-year reagent contracts with consolidated Texas and Florida health systems.
Germany
University hospital pathology networks in Munich and Heidelberg retrofit mercury arc lamp microscopes to LED excitation sources compatible with modern fluorophore panels. The EU IVDR mandates tightened analytical validation for fluorescence-based diagnostics, raising barriers that favor established reagent suppliers with regulatory infrastructure. Baden-Württemberg clusters concentrate fluorophore chemistry manufacturing for European assay developers.
China
Tertiary hospitals in Shanghai and Suzhou expand lupus and vasculitis screening capacity under NMPA diagnostic reimbursement reforms. The NMPA mandates localized clinical trials and manufacturing audit trails for imported immunodiagnostics, creating preferential access for domestic assay developers. Suzhou industrial parks host joint ventures between multinational manufacturers and Chinese fluorophore chemistry suppliers.
Japan
Academic medical centers in Tokyo and Osaka deploy multispectral imaging for renal biopsy immune complex classification. The PMDA maintains rigorous quality standards for in vitro diagnostics that align with international harmonization frameworks. Kanto region pathology laboratories digitize fluorescence workflows through automated spectral unmixing platforms.
Switzerland
Specialized diagnostic laboratories in Basel and Zurich concentrate on premium autoimmune disorder panels for European referral networks. Swissmedic enforces stringent post-market surveillance for fluorescence-based assays that exceeds baseline EU requirements. The Basel pharmaceutical corridor generates companion diagnostic development demand from neighboring biopharmaceutical research operations.
Global Immunofluorescence Assay Market Competitive Landscape
Integrated life science conglomerates and specialized diagnostic reagent suppliers split the market into distinct competitive spheres. The vendor base concentrates around three strategic archetypes: channel-diversified conglomerates with multi-year hospital contracts, chemistry-integrated suppliers controlling fluorophore supply chains, and open-platform enablers preserving laboratory reagent sourcing flexibility. Dominant competitive moves include backward integration into dye manufacturing and unbundling of instrument purchases from consumable supply agreements.
Among diversified life science conglomerates, Thermo Fisher Scientific exemplifies channel-density advantages through consolidated procurement relationships with hospital networks. Merck KGaA anchors the chemistry-integrated tier through upstream control over critical fluorophore supply chains. Bio-Rad Laboratories occupies a position within the open-platform archetype, enabling laboratories to sustain multi-vendor reagent sourcing without full system replacement. These three patterns represent the structural alternatives available to market participants.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Abcam |
| PerkinElmer |
| Cell Signaling Technology |
| Agilent Technologies |
| Werfen |
| Others |
Supply & Pricing Matrix
Undercapacity in European fluorophore synthesis capacity is driving contract renegotiations between dye manufacturers and assay kit suppliers, with utilization rates above 85 percent translating directly into extended lead times and elevated minimum order quantities across the reagent aftermarket.
Pricing Analysis
After-sales service contracts and multi-year reagent subscriptions generate the majority of lifetime customer value, displacing upfront instrument margins. Three-tier pricing structure across premium quantum dot conjugates, standard Alexa Fluor panels, and economy FITC-based assays reflects photostability performance and regulatory validation depth. Cost compression in the economy tier is intensifying because Chinese domestic manufacturers are expanding automated production lines for basic fluorophore chemistries. Hospital networks in China exhibit the highest price sensitivity, while United States cancer centers absorb premium pricing for multiplex oncology panels with minimal procurement friction.
Supply Chain Analysis
Export control regimes targeting advanced nanocrystal synthesis equipment are restricting technology transfer to certain fluorophore manufacturing jurisdictions. Critical dye chemistry concentrates in Germany, Switzerland, and the United States, with rare earth elements for quantum dot cores sourcing from specialized refiners in China and Australia. Single-source vulnerability runs through the sulfonated xanthene dye segment, where two European chemical suppliers control 70 percent of commercial assay-grade production. Distribution runs through authorized reagent distributors and direct hospital network contracts, with consolidated procurement committees in Texas and Florida health systems unbundling instrument purchases from consumable supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as hospital network consolidation creates procurement silos, while regulatory divergence between FDA, EMA, and NMPA jurisdictions fragments product development roadmaps and opens niche entry points for specialized assay developers.
For Market Incumbents: Entrench market position through backward integration into fluorophore chemistry manufacturing and captive supply of critical dye intermediates. Lock in multi-year reagent supply contracts with consolidated pathology service line committees before open-platform compatibility enables vendor switching. Chromogenic IHC substitution in routine diagnostic settings represents the primary technology displacement threat requiring defensive R&D investment in simplified workflow formats.
For New Entrants and Emerging Players: Build out point-of-care autoimmune testing capabilities targeting ambulatory clinics outside hospital laboratory networks, where miniaturized fluorescence readers and dried-reagent cartridges address unmet rapid screening demand. China's NMPA localization incentives create the most penetrable regulatory pathway for domestic manufacturing joint ventures in Suzhou industrial parks. Go-to-market positioning should emphasize NMPA premarket approval timelines versus imported competitor registration delays.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across quantum dot conjugate manufacturing as equipment costs decline and batch yields improve, enabling mid-scale entry without billion-dollar fabrication investments. Acquisition targets should display chemistry-integrated supply chains with captive fluorophore production and established regulatory infrastructure across multiple jurisdictions. The signal to watch is NMPA approval velocity for domestic Chinese assay developers versus multinational registration timelines, indicating competitive positioning shifts in the largest volume market.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorophore Chemistry | Captive dye supply chains insulate margin pools from European chemical supplier allocation risk. |
| NMPA Localization Joint Venture | Domestic manufacturing in Suzhou satisfies audit trail requirements for preferential hospital procurement list placement. |
| Open-Platform Compatibility Investment | Multi-vendor reagent sourcing preservation enables laboratories to avoid full system replacement costs. |
| Quantum Dot Multiplex Panel Expansion | Six-color and eight-color biomarker scoring commands premium pricing in United States oncology clinical trials. |
| LED Excitation Retrofit Program | Mercury arc lamp replacement in German university hospitals unlocks modern fluorophore panel compatibility. |
Research Methodology
The analysis maps reagent format segments, application verticals, and technology chemistry tiers, each validated through primary interviews with hospital pathology directors, diagnostic laboratory procurement managers, fluorophore chemistry R&D leads, and regulatory affairs specialists at assay manufacturers. Secondary validation drew from FDA 510(k) filings, EMA IVDR technical documentation, NMPA registration databases, and hospital GPO contract disclosures. Bottom-up segment sizing triangulated against top-down market envelope estimates from trade association publications and customs reagent import records.
Assumptions held fixed include current regulatory divergence patterns across FDA, EMA, and NMPA jurisdictions and existing fluorophore supply chain geographic concentration. The analytical framework modeled demand across product architecture choices, fluorophore chemistry generations, end-user procurement authority structures, and regional reimbursement pathways. CAGRs were derived from segment-level procedure volume projections and per-test value trajectories, incorporating quantum dot adoption curves in multiplex oncology and autoimmune panel expansion in Chinese tertiary hospitals.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic assay developers with state-backed manufacturing scale-up would shift outcomes. Material shifts in NMPA registration pathway timelines or fluorophore export control regime expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
Digital Biology Market
Biomedical Technology
Human Reproductive Technologies Market
Biomedical Technology
Fluoro Enzymatic Assays Market
Biomedical Technology
Polymerase Chain Reaction Technologies Market
Biomedical Technology
North America Exosome Research Products Market
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Global Automated Cell Cultures Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
US Liquid Biopsy Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Needle Based Biopsy Guns Market