
 Global Nucleic Acid Labeling Market | 2026-2036
Global Nucleic Acid Labeling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nucleic Acid Labeling Market Intelligence
The divergence in R&D investment and manufacturing scale is reorganizing competitive dynamics in the nucleic acid labeling sector. Thermo Fisher Scientific leverages its vast portfolio and global sales channels to serve large-scale diagnostic and pharmaceutical clients. In contrast, New England Biolabs specializes in high-purity enzymatic labeling solutions for academic research. F. Hoffmann-La Roche dominates the clinical diagnostics space with its integrated instrument and reagent systems, creating a closed ecosystem for its assays.
Nucleic acid labeling is the process of attaching a detectable molecule, such as a fluorescent dye or biotin, to a DNA or RNA strand. This modification enables the visualization, quantification, and tracking of specific nucleic acid sequences in biological samples. Fluorescent dyes remain the principal product type, essential for widespread techniques like quantitative PCR. Gene expression analysis and mutation detection constitute the largest application segments, driven by oncology research and personalized medicine initiatives.
Regulatory frameworks, including the US FDA's oversight of in vitro diagnostics and the EU's Medical Device Regulation (MDR), govern the use of labeling products in clinical settings. These rules mandate rigorous performance validation and quality control for market access in major healthcare systems. Consequently, reagent selection for clinical applications increasingly hinges on navigating complex compliance pathways versus purely technical performance.
Market Dynamics
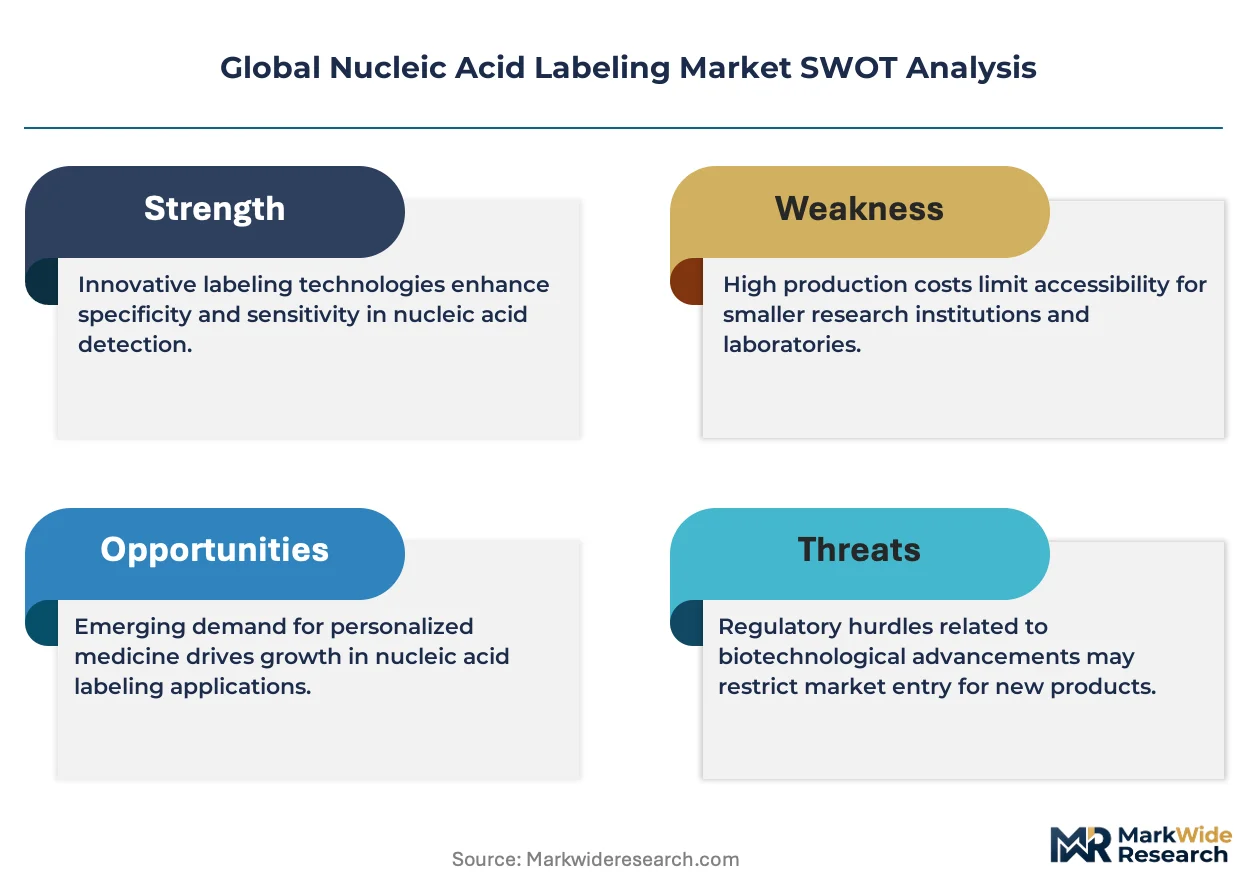
The imperative for clinical validation is the central force governing the nucleic acid labeling market. Expanding use in diagnostics, governed by frameworks like the EU's Medical Device Regulation, creates a structural tension between the rapid pace of research innovation and the rigorous, slower-moving demands of regulatory compliance for clinical applications.
Growth Catalysts
- Personalized Medicine Initiatives:Government-backed research programs in the United States and Germany are accelerating the use of nucleic acid labeling in genomics and oncology to develop targeted therapies and companion diagnostics.
- Advancements in Multiplexing:The development of novel fluorescent dyes with distinct spectral properties enables the simultaneous detection of multiple targets, driving adoption in complex gene expression panels and infectious disease testing.
- Expansion of Molecular Diagnostics:The growing infrastructure for molecular testing in clinical laboratories for applications like viral load monitoring and genetic screening is a primary demand driver for validated labeling reagents.
Market Restraints
- High Cost of Novel Reagents:The proprietary nature and complex manufacturing processes for high-performance fluorescent dyes and specialized labeling enzymes result in high input costs, limiting adoption in cost-sensitive research settings.
- Technical Limitations of Fluorophores:Photobleaching and spectral overlap remain inherent technical challenges with fluorescent labels, potentially compromising the accuracy and reproducibility of quantitative and long-term imaging experiments.
- Stringent Regulatory Hurdles:The EU's MDR and similar regulations in other jurisdictions mandate extensive performance validation for labeling reagents used in clinical assays, increasing development costs and time-to-market.
Strategic Opportunities
- Emerging Applications in Agri-Genomics:Nucleic acid labeling techniques present an opportunity for use in plant and animal breeding, enabling high-throughput screening for desirable genetic traits and rapid detection of agricultural pathogens. -
- Diagnostic Market Penetration in Brazil:Expanding healthcare access and investment in laboratory infrastructure in Brazil and other Latin American countries create new growth avenues for suppliers of clinical-grade labeling products. -
- Adoption of Click Chemistry:This class of bioconjugation reactions offers a more stable, efficient, and specific alternative to traditional enzymatic or chemical labeling methods, representing a white space for new product development.
Industry Challenges
- Reproducibility and Standardization:Variability in labeling efficiency between different reagent lots and laboratory protocols poses a significant challenge to achieving consistent and comparable results, particularly in large-scale multi-center studies.
- Bioinformatics Skill Gap:The massive datasets generated by high-throughput labeling applications, such as next-generation sequencing, require specialized bioinformatics expertise for analysis and interpretation, a skill set that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nucleic Acid Labeling Market |
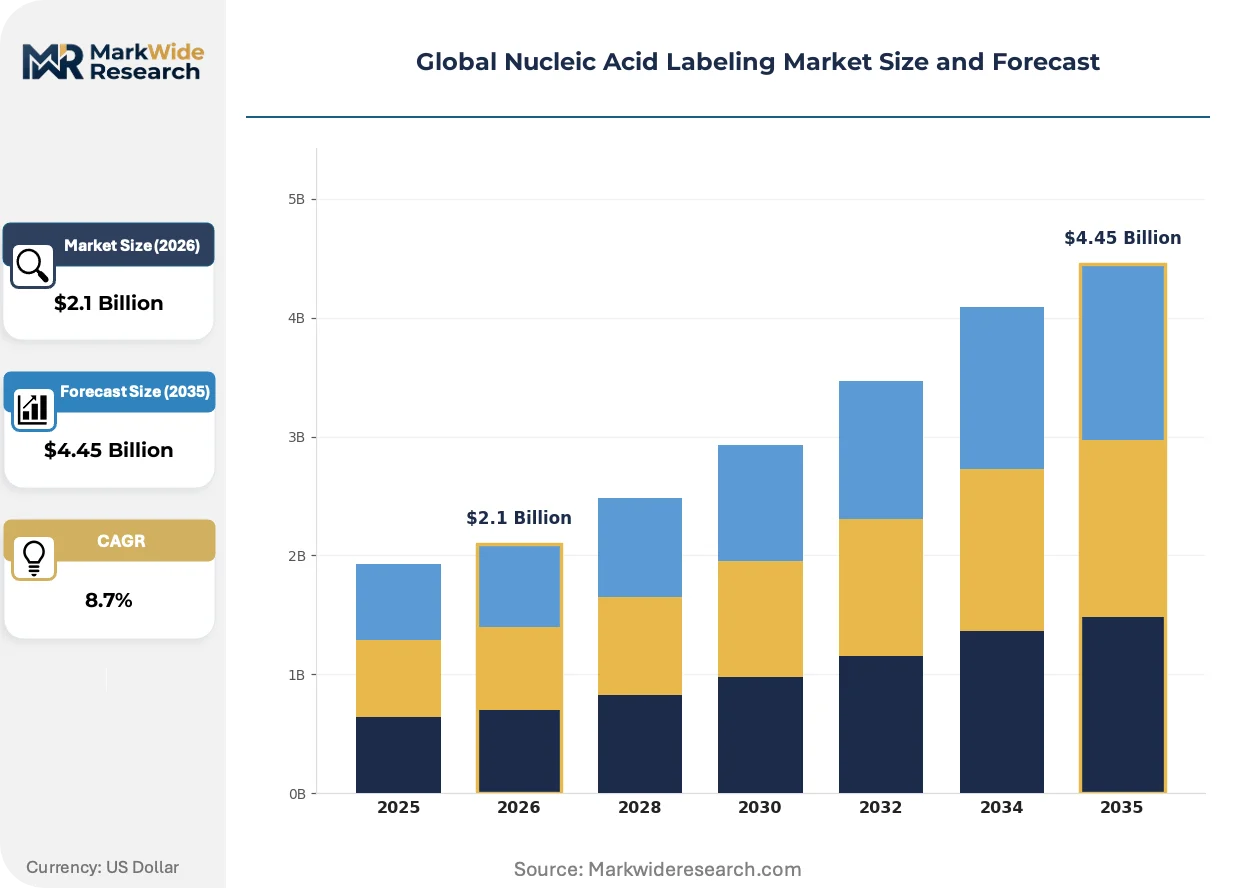
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescent Dyes, Radioisotopes, Biotin Labels, Enzyme Labels, Chemiluminescent Tags Application: Gene Expression Analysis, Mutation Detection, DNA Microarray, In Situ Hybridization, Quantitative PCR Technology: Direct Labeling, Indirect Labeling, Click Chemistry, Enzymatic Labeling, Photochemical Labeling End User: Academic Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Diagnostic Laboratories, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific, PerkinElmer, F. Hoffmann-La Roche, Merck KGaA, GE Healthcare, Agilent Technologies, Promega Corporation, New England Biolabs, Enzo Biochem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nucleic Acid Labeling Market Strategic Shifts & Innovations
A fundamental shift is underway as the market moves from supplying discrete research components to providing integrated, clinically validated solutions. This evolution is driven by technological convergence, tightening regulatory oversight, and changing purchasing behaviors in the core diagnostic end-market.
Spatial transcriptomics combines nucleic acid labeling with high-resolution microscopy to visualize gene expression patterns directly within the context of tissue architecture. Pharmaceutical R&D groups and academic medical centers are adopting this for deeper insights into disease pathology and drug response. This powerful technology is decomposing the traditional boundary between molecular biology and histology, creating a unified analysis of tissue function.
The US FDA's proposed framework to regulate Laboratory Developed Tests (LDTs) as medical devices represents a significant policy evolution. This action will likely impose stricter premarket review and quality system requirements on clinical laboratories that have historically developed their own assays using individual components. Consequently, diagnostic laboratories are most affected, increasing their demand for labeling reagents that come with comprehensive validation documentation suitable for regulatory submissions.
Preference for integrated instrument-reagent systems is altering procurement patterns within high-volume clinical laboratories. These customers are increasingly moving away from open-platform assays, which require sourcing and validating individual components, toward closed-box systems from a single vendor. This trend, most visible in the US and German hospital networks, streamlines workflows and simplifies the path to regulatory compliance for new tests.
Global Nucleic Acid Labeling Market Segmentation
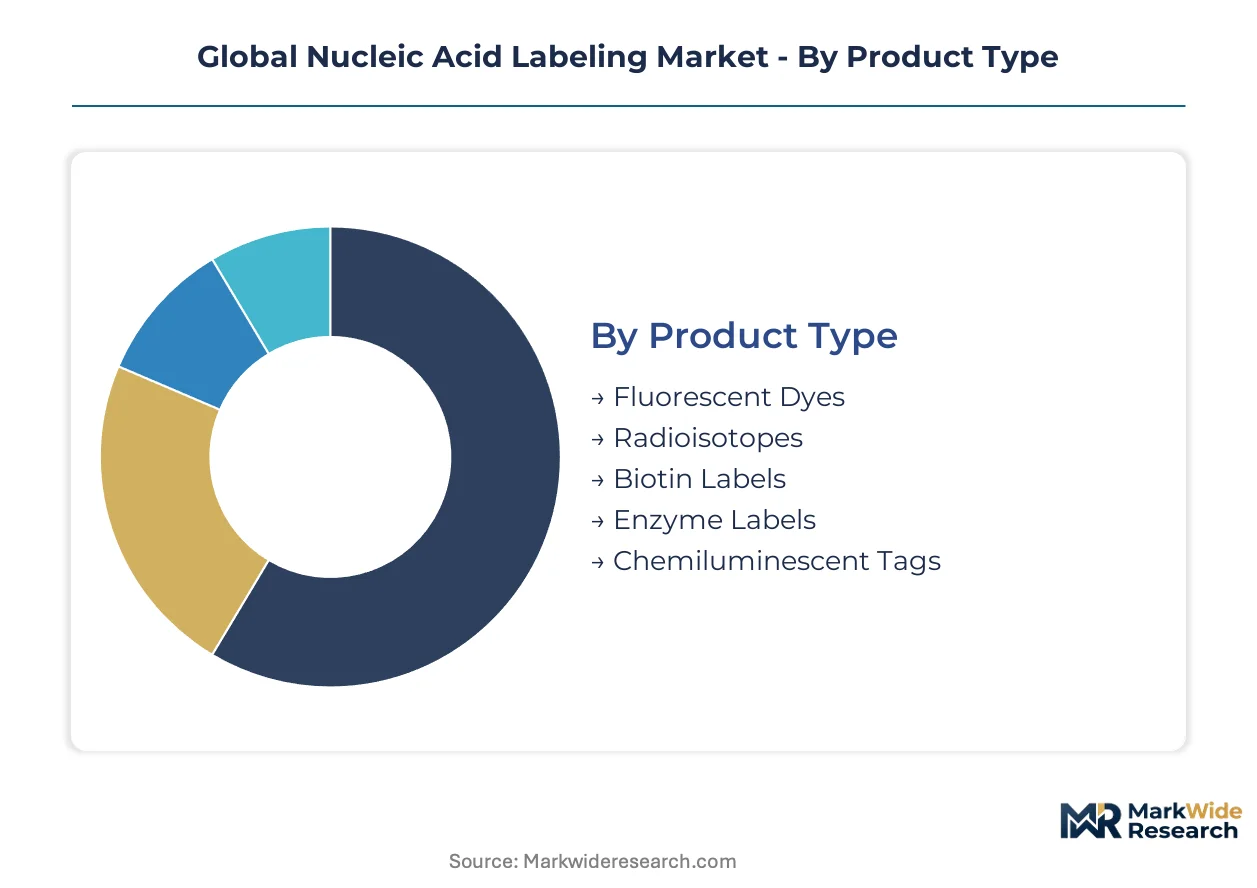
The nucleic acid labeling market is delineated by specific product types, applications, technologies, and end-user segments. This segmentation reflects diverse requirements of research and clinical domains, highlighting varied demands for sensitivity, throughput, and regulatory compliance.
Product Type:
Regulatory oversight significantly influences demand for different nucleic acid labeling product types, particularly in clinical settings.
- Fluorescent Dyes:These molecules emit light upon excitation, enabling visualization and quantification of nucleic acids in quantitative PCR. Widespread use in diagnostic laboratories drives consistent demand.
- Enzyme Labels:Enzymes like horseradish peroxidase generate detectable signals through enzymatic reactions, offering high sensitivity for academic research. New England Biolabs utilizes these solutions.
- Radioisotopes:Radioactive isotopes are used for highly sensitive detection in specific research, despite safety challenges.
- Biotin Labels:Biotin-labeled nucleic acids bind strongly to avidin, providing versatile detection and purification methods.
- Chemiluminescent Tags:These tags produce light via chemical reaction without external excitation, used in Western blotting and diagnostics.
Established volume favors Fluorescent Dyes; emerging adoption favors Biotin Labels for versatile applications.
Application:
Application focus determines required sensitivity, throughput, and validation levels for labeling products.
- Gene Expression Analysis:This application measures gene activity by quantifying RNA levels, critical for oncology research and personalized medicine. US and German programs accelerate its use.
- Mutation Detection:Labeling reagents identify specific genetic alterations, supporting clinical diagnostics for inherited diseases and cancer. This segment drives validated reagent demand.
- DNA Microarray:This high-throughput method uses labeled DNA to analyze thousands of genes simultaneously for gene profiling.
- In Situ Hybridization:Labeled probes detect specific nucleic acid sequences within cells or tissues, providing spatial information.
- Quantitative PCR:Labeled probes enable real-time quantification of DNA or RNA, a cornerstone for viral load monitoring.
The market prioritizes Gene Expression Analysis for clinical utility, with Quantitative PCR supporting high-throughput research.
Technology:
The mechanistic approach to attaching detectable molecules defines efficiency, stability, and specificity of labeling methods.
- Click Chemistry:This class of bioconjugation reactions offers stable, efficient, and specific nucleic acid labeling. It represents a strategic opportunity for new product development.
- Enzymatic Labeling:Enzymes incorporate labeled nucleotides directly into nucleic acid strands. This method is crucial for high-purity academic research, exemplified by New England Biolabs.
- Direct Labeling:This method covalently attaches labels directly to nucleic acids, offering simplicity but sometimes compromising integrity.
- Indirect Labeling:A two-step process incorporates a hapten, then detects it with a labeled affinity molecule, enhancing signal.
- Photochemical Labeling:UV light initiates covalent attachment of photoreactive labels to nucleic acids, useful for specific research.
Efficiency and specificity are paramount for Click Chemistry, while established methods like Enzymatic Labeling maintain broad utility.
End User:
End-user requirements dictate the scale, quality, and regulatory documentation needed for labeling products.
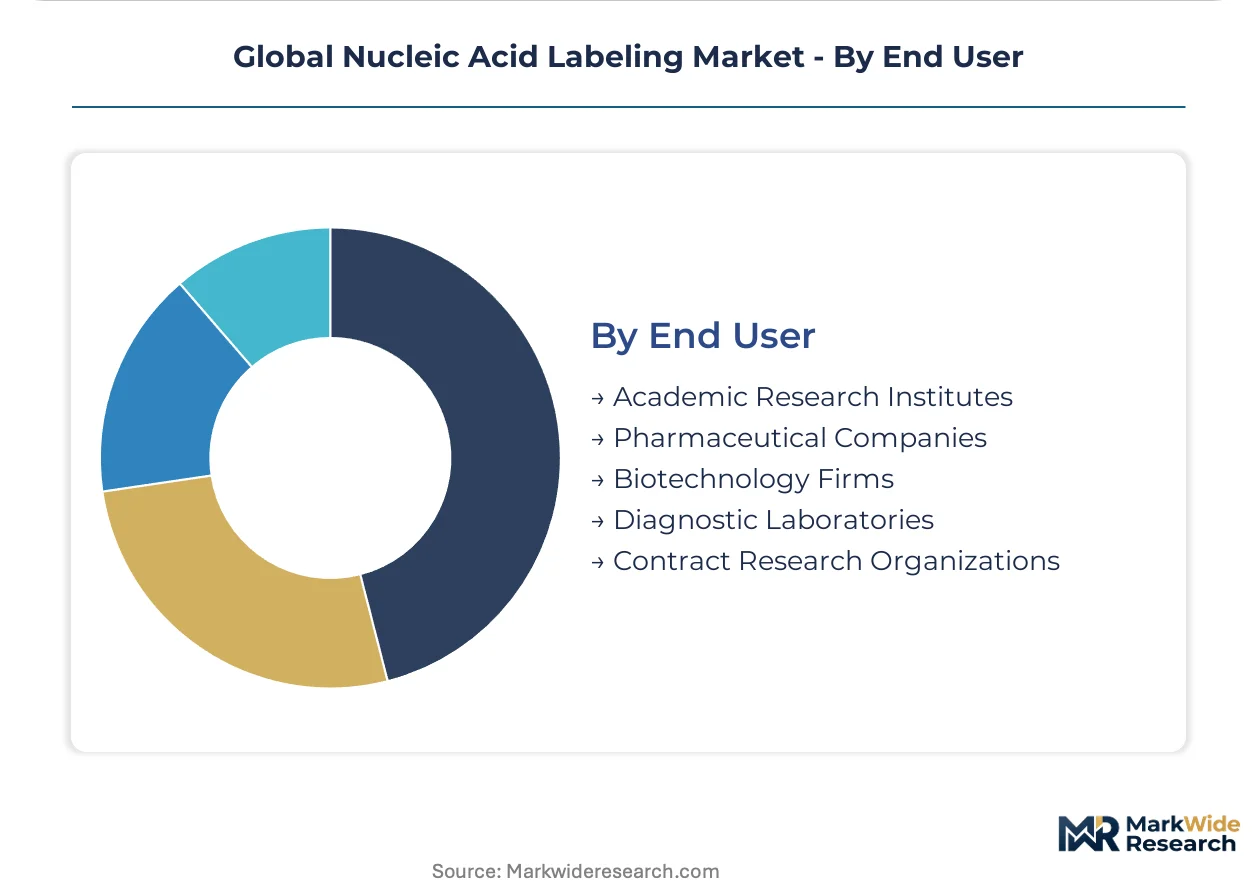
- Diagnostic Laboratories:These entities require highly validated, standardized labeling reagents for molecular testing like viral load monitoring. EU MDR directly impacts their procurement.
- Pharmaceutical Companies:These firms utilize nucleic acid labeling in drug discovery, target validation, and companion diagnostics. High-throughput solutions are needed for R&D groups.
- Academic Research Institutes:University and government labs employ labeling reagents for fundamental biological studies, valuing innovation and performance.
- Biotechnology Firms:These companies develop novel assays and therapeutics, using labeling for product development and quality control.
- Contract Research Organizations:CROs provide outsourced research services, requiring reliable and scalable labeling solutions for various protocols.
Large-scale clinical demand concentrates in Diagnostic Laboratories, whereas innovation originates from Academic Research Institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption-mix for nucleic acid labeling products varies significantly across major global markets. While established economies prioritize high-value clinical diagnostics and advanced research, emerging markets focus on expanding molecular testing infrastructure. This differentiation drives distinct demand patterns for validated reagents and integrated solutions worldwide.
United States
Demand for nucleic acid labeling reagents in the United States stems from personalized medicine initiatives and oncology research. The US FDA's oversight of in vitro diagnostics mandates rigorous validation for clinical applications. The Boston-Cambridge biotech hub and the San Francisco Bay Area concentrate significant R&D activities and diagnostic development.
Germany
Germany's market for nucleic acid labeling products centers on advanced clinical diagnostics and pharmaceutical R&D. The EU's Medical Device Regulation (MDR) imposes strict compliance requirements for labeling reagents used in medical assays. Major biotech clusters in Munich and Heidelberg drive innovation in gene expression analysis.
Brazil
Brazil represents a significant growth avenue for nucleic acid labeling, driven by expanding molecular diagnostics infrastructure. ANVISA, the country's health surveillance agency, regulates the approval of clinical-grade labeling products. São Paulo and Rio de Janeiro serve as key centers for medical research and laboratory expansion.
Japan
Japan's market exhibits strong demand for high-purity labeling solutions in academic research and pharmaceutical development. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures stringent quality control for reagents used in clinical settings. Tokyo and Osaka host numerous research universities and biotechnology companies.
China
China's market for nucleic acid labeling is expanding rapidly due to increased investment in genomics and clinical testing. The National Medical Products Administration (NMPA) governs the use of diagnostic reagents within the country. Major research institutions in Shanghai and Beijing are accelerating high-throughput sequencing applications.
Global Nucleic Acid Labeling Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the nucleic acid labeling market. This structure exhibits consolidation at the top with a fragmented base of niche providers. Two strategic archetypes emerge: large diversified life science conglomerates and specialized reagent developers. Dominant competitive moves include portfolio diversification to capture integrated system demand and strategic partnerships for technology co-development.
Integrated leaders like Thermo Fisher Scientific exemplify the strategy of leveraging extensive portfolios and global sales channels to serve diverse clients. F. Hoffmann-La Roche, a Swiss-based company, occupies a strong position in clinical diagnostics, particularly through its integrated instrument and reagent systems. New England Biolabs, a US-based corporation, represents the specialist tier, focusing on high-purity enzymatic labeling solutions tailored for academic research. These distinct approaches highlight the market's tiered structure, where different entities cater to specific segments from high-volume clinical applications to specialized laboratory needs.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| PerkinElmer |
| F. Hoffmann-La Roche |
| Merck KGaA |
| GE Healthcare |
| Agilent Technologies |
| Promega Corporation |
| New England Biolabs |
| Enzo Biochem |
| Others |
Cost & Logistics Intelligence
The European Union's Medical Device Regulation (MDR) gates both supply qualification and price differentiation simultaneously for nucleic acid labeling reagents. This regulatory framework necessitates extensive validation for clinical applications, directly influencing product costs and market access across major healthcare systems.
Pricing Analysis
Long-term contract-based offtake agreements characterize pricing for validated clinical-grade nucleic acid labeling reagents, particularly for high-volume diagnostic laboratories. Price differentiation stems from the specific certification level, such as EU MDR compliance, and the brand premium associated with integrated system providers. Pricing pressure stems from the high input costs of novel reagents and the extensive validation required for clinical use. Academic research institutes are generally more price-sensitive, valuing cost-effectiveness for experimental applications, while clinical diagnostic laboratories prioritize validated performance and regulatory adherence.
Supply Chain Analysis
Specialized manufacturing processes for high-purity enzymes and novel fluorescent dyes represent a critical chokepoint in the nucleic acid labeling supply chain. Geographic supply concentration for these proprietary inputs centers on established R&D hubs within the United States and Germany. Raw material dependencies include highly purified nucleotides, specialized fluorophores, and recombinant enzymes. Single-source vulnerability for these complex components poses a significant supply chain risk. Distribution runs through a dual model, with direct sales channels for integrated instrument-reagent systems and specialized distributors serving academic and smaller research laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spatial transcriptomics represents a high-growth disruption in the nucleic acid labeling market, fundamentally altering how molecular biology and histology converge. This technological inflection drives new demand for specialized labeling solutions.
For Market Incumbents: Compound existing portfolio strengths by investing in integrated instrument-reagent systems tailored for spatial transcriptomics applications. Consolidate market share in clinical diagnostics by accelerating regulatory submissions under frameworks like the US FDA's LDT oversight. Diversify R&D efforts into novel multiplexing technologies to counter emerging specialized reagent developers. Leverage global sales channels to secure long-term supply contracts with large diagnostic and pharmaceutical clients.
For New Entrants and Emerging Players: Streamlined regulatory compliance pathways for research-use-only products create a viable entry point into the nucleic acid labeling market. Target emerging applications like agri-genomics and specific geographies such as Brazil, where molecular diagnostics infrastructure is expanding. Focus on niche specialization in click chemistry solutions, which offer superior stability and efficiency. Develop strategic partnerships with academic research institutes to co-develop high-purity enzymatic labeling solutions with lower validation hurdles.
For Investors and Strategic Acquirers: The US FDA's proposed framework to regulate Laboratory Developed Tests reshapes the acquisition landscape, favoring companies with robust validation capabilities. Long-term viability rests on the continued expansion of personalized medicine and molecular diagnostics, supporting sustained demand for labeling reagents. Target specialized reagent developers with strong intellectual property in novel labeling chemistries or integrated system providers with established clinical validation. A key signal to watch is the adoption rate of spatial transcriptomics platforms within pharmaceutical R&D and academic medical centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Integrated Systems | Streamlines workflows and simplifies regulatory compliance for high-volume clinical laboratories. |
| Expand Multiplexing Capabilities | Enables simultaneous detection of multiple targets, crucial for complex gene expression panels. |
| Target Agri-Genomics Applications | Unlocks new market segments for high-throughput screening in plant and animal breeding. |
| Develop Click Chemistry Solutions | Offers stable and efficient labeling methods, addressing technical limitations of current fluorophores. |
| Strengthen Regulatory Compliance | Ensures market access in major healthcare systems governed by regulations like EU MDR. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary insights were gathered from R&D leads, laboratory directors, regulatory affairs specialists, and procurement managers across pharmaceutical companies and diagnostic laboratories. Secondary data was extracted from FDA filings, EU MDR guidelines, scientific publications, and company financial reports to corroborate primary findings. This approach facilitated a comprehensive understanding of market dynamics through bottom-up and top-down triangulation.
The forecasting framework utilized an analytical model to project market growth across the analysis window. Segmentation dimensions modeled included product type, application, technology, end-user, and regional regulatory compliance levels. Compound annual growth rates were derived from historical trends and projected market drivers, including personalized medicine investment and molecular diagnostics expansion. These inputs provided a robust basis for quantitative projections throughout the forecast period.
The analysis sits within stated boundaries; outcomes outside unforeseen regulatory shifts or rapid technological obsolescence would require recalibration. Forecasts reflect assumptions regarding market evolution and stakeholder behavior. Practitioners should keep alternative scenarios live as regulatory landscapes and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
North America Whole Exome Sequencing Market
Genomics
Asia Pacific Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Global Nutrigenomics Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Genetic Testing Panels Market
Genomics
Glycan Sequencing Market
Genomics
Europe Epigenetics Market
Genomics
Antisense Oligonucleotides Market
Genomics
Alagille Syndrome Market
Genomics
Global Genotyping Assay Market
Genomics
Global Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Gene Sequencing Market
Genomics
Plant Genomics Market
Genomics
Global Single-Cell Genome Sequencing Market
Genomics
Latin America Next Generation Sequencing Market