
 Proteomics Market | 2026-2036
Proteomics Market Size, Share, and Industry Trends Forecast 2026-2036
Proteomics Market Intelligence
Asset-light contract research platforms and instrument-leasing programs are reshaping how mid-size biotech firms access high-resolution mass spectrometry. Thermo Fisher Scientific leverages its installed base of Orbitrap systems to sustain recurring revenue through service contracts and consumables. Bruker differentiates through specialized timsTOF platforms that dominate high-throughput proteogenomics workflows.
Proteomics encompasses the large-scale study of protein structures, functions, and interactions through analytical techniques such as liquid chromatography-mass spectrometry with resolution thresholds below 5 ppm. Its primary commercial purpose is enabling biomarker validation and therapeutic target deconvolution across drug development pipelines. Mass spectrometry systems command the largest installed base and generate the steadiest consumable pull-through, while protein microarrays represent a faster-growing segment for multiplexed affinity screening. Academic research institutes constitute the deepest end-user pool, though pharmaceutical companies yield higher per-site spending on premium instrumentation.
The FDA's biomarker qualification framework and the EPA's analytical method validation requirements jointly shape instrument specifications and software compliance burdens for vendors entering regulated environments. ISO 17025 accreditation and CLIA standards for clinical laboratories further constrain which proteomics platforms achieve routine diagnostic deployment. Stakeholders must monitor how harmonization between FDA guidance and European Medicines Agency pathways for protein-based companion diagnostics alters competitive access to transatlantic markets.
Market Dynamics
Asset-light research models are compressing capital barriers for mid-size biotech firms seeking high-resolution mass spectrometry access, forcing vendors to pivot from instrument sales toward recurring service architectures and consumable pull-through revenue.
Growth Catalysts
- FDA Biomarker Qualification Framework:Streamlined pathways for protein-based companion diagnostics accelerate clinical translation timelines for biopharmaceutical sponsors.
- Orbitrap installed base expansion:Thermo Fisher Scientific's recurring revenue engine through service contracts and consumables sustains platform lock-in across academic and pharmaceutical sites.
- Boston-San Diego research cluster concentration:Geographic density of biopharmaceutical R&D creates localized demand spikes for high-throughput proteogenomics infrastructure.
Market Restraints
- Helium supply volatility:Mass spectrometry systems depend on constrained noble gas supply chains, with price spikes disrupting operational budgets for core facilities.
- ISO 17025 accreditation burden:Clinical laboratories face multi-year compliance timelines that delay routine diagnostic deployment of proteomics platforms.
- Antibody microarray substitution:Lower-cost affinity screening methods capture share in biomarker discovery workflows where resolution thresholds exceed 5 ppm requirements.
Strategic Opportunities
- India CDSCO pathway alignment:Harmonization with FDA biomarker frameworks opens companion diagnostic market access for Western proteomics vendors.
- Single-cell proteomics convergence:Integration of microfluidics with mass spectrometry creates white space in immuno-oncology target deconvolution.
- Instrument-leasing channel innovation:CRO platforms offering pay-per-sample models reduce capital barriers for emerging biotech entrants.
Industry Challenges
- Bioinformatics talent scarcity:Shortage of computational biologists proficient in mass spectrometry data pipelines constrains analytical throughput at core facilities.
- CLIA certification complexity:Multi-site standardization requirements fragment operational scale for clinical proteomics service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proteomics Market |
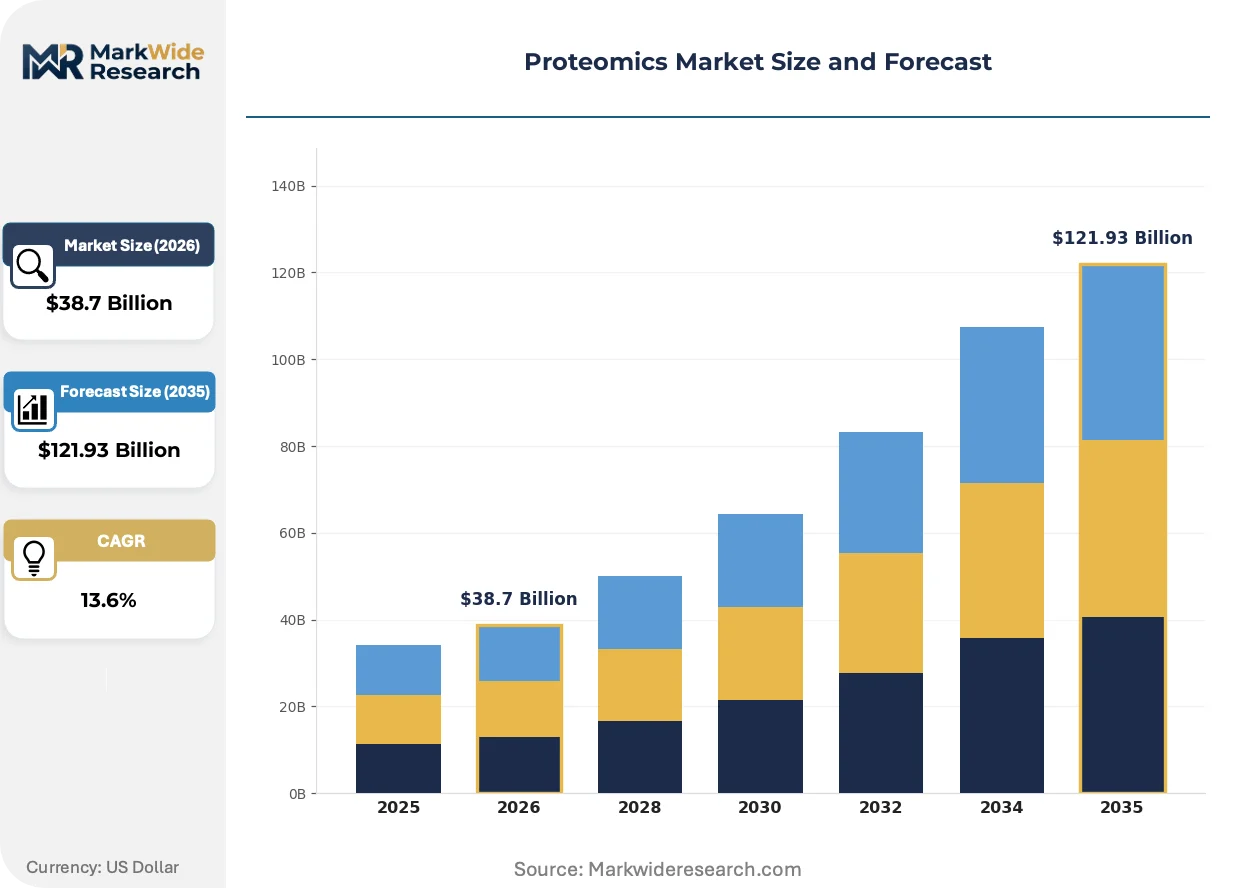
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $121.93 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Microarrays, Mass Spectrometry Systems, Chromatography Systems, Protein Extraction Kits, Protein Labeling Reagents, Others Technology: Gel Electrophoresis, X-ray Crystallography, Nuclear Magnetic Resonance, Surface Plasmon Resonance, Isotope Labeling, Fluorescence Resonance Energy Transfer Application: Biomarker Discovery, Drug Target Identification, Protein Interaction Mapping, Disease Mechanism Elucidation, Personalized Medicine, Toxicology Studies End User: Pharmaceutical Companies, Academic Research Institutes, Clinical Laboratories, Contract Research Organizations, Biotech Firms, Government Research Centers |
| Companies Covered | Bio-Rad Laboratories, Waters Corporation, Thermo Fisher Scientific, SomaLogic Operating, Merck KGaA, Agilent Technologies, Danaher, Biognosys, Bruker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proteomics Market Strategic Shifts & Innovations
Computational architectures are displacing hardware-centric competitive moats, with cloud-native data pipelines and AI-assisted spectral interpretation compressing the value capture traditionally held by instrument manufacturers.
Deep learning-based spectral library matching is digitizing protein identification workflows, enabling pharmaceutical companies to process tenfold more samples per instrument day. Biopharmaceutical sponsors in the United States and Germany now prioritize platforms with embedded neural search capabilities over raw resolution specifications. This capability compression threatens premium pricing for hardware vendors while elevating software and bioinformatics service margins.
EMA's evolving guidance on protein-based companion diagnostics is creating transatlantic regulatory friction, forcing vendors to maintain dual compliance tracks for FDA and European Medicines Agency submission pathways. Instrument manufacturers must now validate software algorithms under MDR technical documentation requirements, extending product launch timelines by 12-18 months. European academic hospitals are responding by consolidating procurement around vendors with established CE-marked proteomics workflows.
After-sales service unbundling is fragmenting vendor-customer relationships, with large pharmaceutical buyers negotiating direct consumable sourcing and third-party maintenance contracts. Thermo Fisher Scientific's installed base in Massachusetts faces pressure from independent service organizations offering 40% reduced annual maintenance costs. This disintermediation is most visible in the United States, where procurement teams now separate instrument capital from operational expenditure line items.
Proteomics Market Segmentation
Proteomics segmentation reveals divergent margin architectures across hardware, consumables, and services. Vendors optimize revenue mix differently depending on which segments anchor their installed base and recurring revenue streams.
Product Type:
After-sales service intensity varies dramatically across hardware versus consumable segments, reshaping vendor-customer contract structures and lifetime value calculations.
- Mass Spectrometry Systems:High-resolution Orbitrap and timsTOF platforms command premium capital outlays with 10-15 year operational lifespans. Pharmaceutical companies in Massachusetts and California drive replacement cycles through obsolescence pressure rather than mechanical failure.
- Protein Microarrays:Multiplexed affinity chips enable parallel screening of thousands of protein interactions with minimal sample volume. Academic institutes in Germany and the United States favor these for biomarker discovery where mass spec resolution exceeds experimental requirements.
- Chromatography Systems:Liquid chromatography front-ends integrate with mass detection for separation workflows.
- Protein Extraction Kits:Standardized reagent sets reduce protocol variability across multi-site studies.
- Protein Labeling Reagents:Isotopic and fluorescent tags for quantitative comparison experiments.
- Others:Sample preparation automation and quality control consumables.
Mass spectrometry systems hold the largest share; momentum sits with protein microarrays.
Technology:
Technology selection follows resolution requirements and throughput constraints rather than cost optimization alone, with regulatory validation pathways favoring established methods over emerging alternatives.
- Gel Electrophoresis:SDS-PAGE and 2D gel methods persist in quality control workflows despite lower throughput. Clinical laboratories in India and Brazil retain these for protein purity verification where regulatory familiarity accelerates assay validation.
- X-ray Crystallography:Structural determination at atomic resolution enables structure-based drug design for challenging targets. Biopharmaceutical sponsors in Switzerland and the United Kingdom maintain dedicated facilities for therapeutic protein characterization.
- Nuclear Magnetic Resonance:Solution-state dynamics analysis for intrinsically disordered proteins.
- Surface Plasmon Resonance:Real-time binding kinetics without labeling requirements.
- Isotope Labeling:SILAC and TMT methods for multiplexed quantitative proteomics.
- Fluorescence Resonance Energy Transfer:Protein interaction visualization in living cells.
Gel electrophoresis retains dominant installed base; surface plasmon resonance is gaining share fastest in biologics development.
Application:
Application prioritization shifts with biopharmaceutical pipeline composition, with oncology and immunology targets commanding disproportionate analytical investment.
- Biomarker Discovery:Large-scale protein profiling identifies diagnostic signatures and patient stratification markers. FDA qualification pathway alignment drives sponsor investment in cardiovascular and oncology protein panels.
- Drug Target Identification:Proteome-wide screening reveals mechanistic entry points for therapeutic intervention. CRISPR-proteomics integration in Boston and Cambridge accelerates target deconvolution timelines.
- Protein Interaction Mapping:Interactome characterization for pathway analysis.
- Disease Mechanism Elucidation:Differential expression studies for therapeutic hypothesis generation.
- Personalized Medicine:Patient-specific protein signatures for treatment selection.
- Toxicology Studies:Off-target effect characterization in safety assessment.
Biomarker discovery commands the deepest funding; personalized medicine shows the steepest expansion trajectory.
End User:
End-user procurement sophistication varies with capital access and regulatory exposure, fragmenting vendor sales motion between enterprise and transactional segments.
- Academic Research Institutes:Core facilities serve dispersed investigator bases with shared high-resolution instrumentation. NIH and Wellcome Trust funding concentration in Boston, San Diego, and Heidelberg sustains premium platform demand despite budget volatility.
- Pharmaceutical Companies:Internal proteomics capabilities support pipeline decision-making with strict data integrity requirements. EMA and FDA submission pressures in Germany and the United States drive investment in validated software workflows.
- Clinical Laboratories:Diagnostic service providers facing CLIA and ISO 17025 compliance burdens.
- Contract Research Organizations:Asset-light access models for emerging biotech sponsors.
- Biotech Firms:Venture-backed companies prioritizing speed over internal capability building.
- Government Research Centers:National laboratory systems with mission-driven analytical requirements.
Academic research institutes represent the broadest installed base; contract research organizations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA biomarker qualification frameworks and EMA companion diagnostic pathways are redirecting proteomics infrastructure investment toward jurisdictions with harmonized regulatory recognition. National funding concentration in established biopharmaceutical clusters sustains premium instrument demand despite capital constraints elsewhere.
United States
NIH funding concentration and venture capital availability sustain the deepest installed base of high-resolution mass spectrometry. FDA biomarker qualification guidance accelerates clinical translation timelines for protein-based diagnostics. Boston and San Diego research clusters drive localized demand spikes for proteogenomics infrastructure serving biopharmaceutical sponsors.
Germany
Wellcome Trust and national research council funding sustain core facility investment across academic institutes. EMA protein-based companion diagnostic requirements extend product launch timelines, favoring vendors with established CE-marked workflows. Heidelberg and Munich academic hospitals consolidate procurement around validated proteomics platforms.
China
NMPA regulatory alignment with international biomarker frameworks expands market access for Western instrument vendors. National biotechnology development programs prioritize domestic mass spectrometry capability building. Shanghai and Beijing research institutes balance imported platform acquisition with local supplier qualification.
Switzerland
Swissmedic requirements for therapeutic protein characterization sustain dedicated structural biology facilities. Federal research funding and pharmaceutical headquarters concentration support premium instrumentation investment. Basel and Zurich biopharmaceutical sponsors maintain in-house proteomics capabilities for pipeline decision-making.
India
CDSCO pathway alignment with FDA biomarker frameworks opens companion diagnostic market access for Western vendors. Central Drugs Standard Control Organization streamlines clinical trial approval for protein-based diagnostics. Hyderabad and Bangalore contract research organizations expand proteomics service capacity for international biopharmaceutical sponsors.
Proteomics Market Key Industry Players
On the supply side, the industry is consolidating around integrated platform vendors with recurring revenue architectures and specialized instrument manufacturers with differentiated technology positions. Thermo Fisher Scientific and Danaher exemplify the full-stack archetype combining hardware, consumables, and services. Bruker and Biognosys occupy the precision-specialist tier with targeted technology platforms. Competitive dynamics center on installed base expansion through leasing programs and software algorithm validation for regulatory submission pathways.
Within the precision-specialist tier, Bruker anchors German mass spectrometry expertise through timsTOF platforms, while Biognosys represents the Swiss proteomics services archetype with mass spectrometry-based contract research capabilities. Thermo Fisher Scientific occupies the integrated platform position with Orbitrap system deployment across academic and pharmaceutical sites. These three entities exemplify the strategic segmentation between hardware-centric recurring revenue models and service-based analytical partnerships.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Waters Corporation |
| Thermo Fisher Scientific |
| SomaLogic Operating |
| Merck KGaA |
| Agilent Technologies |
| Danaher |
| Biognosys |
| Bruker |
| Others |
Cost & Logistics Intelligence
Helium supply volatility between the United States and Qatar determines both pricing tier spreads and supply chain shape for mass spectrometry-dependent proteomics infrastructure. Procurement teams now separate instrument capital from operational expenditure line items to hedge against noble gas price spikes that compress margins in high-resolution workflows.
Pricing Analysis
Certification level creates the primary spread between CLIA-validated clinical platforms and research-grade instrumentation. Three-tier pricing structure across FDA-qualified, CE-marked, and non-certified systems segments buyer budgets, with pharmaceutical sponsors in Massachusetts showing lowest price sensitivity for validated software workflows. Cost compression in the mid-tier research segment is intensifying because after-sales service unbundling allows third-party maintenance contracts at reduced annual rates. Academic core facilities represent the most price-sensitive buyer archetype, prioritizing instrument-leasing programs over capital purchase.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for chromatography consumables and electronic detection components. Manufacturing concentrates in Germany, the United States, and Singapore for precision ion optics and vacuum systems that feed from specialized metalworking clusters. Single-source vulnerability persists for superconducting magnet wire used in NMR platforms and noble gas refining capacity for mass spectrometer operation. Distribution runs through authorized dealer networks for capital equipment and direct e-commerce channels for standardized reagent kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The proteomics market sits in a cyclical recovery phase driven by FDA biomarker qualification framework maturation that restarts capital expenditure cycles frozen during regulatory uncertainty.
For Market Incumbents: Build installed base moats through embedded AI-assisted spectral interpretation that locks pharmaceutical sponsors into recurring software subscription architectures. Deepen consumable pull-through by securing exclusive reagent supply contracts with Boston and San Diego research clusters. Counter third-party service disintermediation by unbundling maintenance tiers to capture price-sensitive academic segments. For New Entrants and Emerging Players: Build out single-cell proteomics convergence capabilities as the most penetrable white space, targeting immuno-oncology target deconvolution workflows in venture-backed biotech firms. Establish pay-per-sample instrument-leasing partnerships with contract research organizations to bypass capital barriers that exclude mid-size entrants. Lead with cloud-native data pipelines as the primary go-to-market angle against hardware-centric incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-specialist platforms with differentiated timsTOF or spatial proteomics capabilities over full-stack generalists. Long-term viability hinges on software algorithm validation for dual FDA-EMA submission pathways that extend competitive moats. Target acquisition profiles center on bioinformatics service providers with mass spectrometry data pipeline expertise. Monitor harmonization progress between CDSCO and FDA biomarker frameworks as the inflection signal for emerging market expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Algorithm Validation | FDA and EMA software qualification extends product launch timelines by 12-18 months for instrument vendors. |
| Instrument-Leasing Channel Innovation | Pay-per-sample models reduce capital barriers for emerging biotech entrants in Boston and San Diego clusters. |
| Single-Cell Proteomics Integration | Microfluidics-mass spectrometry convergence creates white space in immuno-oncology target deconvolution workflows. |
| After-Sales Service Unbundling | Third-party maintenance contracts at 40% reduced costs fragment vendor-customer relationships in the United States. |
| Dual Compliance Track Investment | CE-marked workflow validation captures European academic hospital procurement consolidation around established vendors. |
Research Approach
Initial hypotheses were tested against primary input from proteomics core facility directors, biopharmaceutical R&D executives, regulatory affairs specialists, and clinical laboratory compliance officers and refined through secondary validation against FDA biomarker qualification guidance documents, EMA companion diagnostic pathway submissions, NIH funding allocation databases, and instrument vendor SEC filings. Bottom-up demand modeling across academic, pharmaceutical, and clinical end-user segments was triangulated with top-down market sizing from trade flow and customs data.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, technology platform, application workflow, and end-user procurement sophistication. CAGRs were derived from instrument replacement cycle analysis and consumable pull-through rates calibrated to installed base expansion trajectories. Forecast inputs incorporated CLIA certification timeline assumptions and helium supply chain volatility scenarios.
Practitioners should monitor CDSCO-FDA harmonization progress, EMA protein-based companion diagnostic guidance evolution, and bioinformatics talent pipeline constraints for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Middle East and Africa Exosome Research Products Market
Biomedical Technology
Oligonucleotide Synthesis Market
Biomedical Technology
Global Automated Cell Cultures Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Europe Proteomics Market
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market
Biomedical Technology
Bioprocess Technology Market
Biomedical Technology
Global Glycomics/Glycobiology Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
Global Cell Based Assays Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
US Liquid Biopsy Market
Biomedical Technology
Global Oncology Based in-Vivo CRO Market