
 Global Organoids Market | 2026-2036
Global Organoids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organoids Market Foresight
North American biomanufacturing expansion is reshaping competitive dynamics in organoid supply chains. Thermo Fisher Scientific leverages its cell culture media portfolio to dominate reagent distribution across academic and commercial labs. Merck KGaA anchors European production through its MilliporeSigma bioscience division, while HUB Organoids BV specializes in patient-derived tumor models for oncology applications.
Organoids are self-organizing, three-dimensional tissue cultures derived from stem cells or progenitor cells that recapitulate organ-specific architecture and function in vitro, typically grown within extracellular matrix hydrogels such as Matrigel or synthetic alternatives at 37°C with defined growth factor cocktails. Their primary commercial purpose is to provide physiologically relevant human tissue models for preclinical drug efficacy and safety assessment, replacing animal models in certain applications. Intestinal organoids lead product type revenue due to their established use in cystic fibrosis drug validation and inflammatory bowel disease research. CRISPR gene editing integration with organoid platforms represents the fastest-expanding technology segment, enabling isogenic disease model generation that commands premium pricing from pharmaceutical sponsors.
The FDA's Modernization Act 2.0 provisions and EMA's qualification opinion pathway for complex in vitro methods are converging to reduce regulatory friction for organoid-based submissions in the United States and Europe. ISO 20391 standards for 3D cell culture characterization are emerging as technical benchmarks that shape supplier credibility and procurement criteria across contract research organizations. Stakeholders must monitor harmonization gaps between regional qualification frameworks to anticipate where validation investments will unlock market access.
Market Dynamics
Pharmaceutical sponsors are systematically replacing flat monolayer assays with 3D organoid protocols, compressing validation timelines and redrawing procurement criteria across contract research organizations.
Growth Catalysts
- FDA Modernization Act 2.0:The United States regulatory pathway now explicitly qualifies complex in vitro models for drug submissions, eliminating prior animal-study mandates that delayed organoid adoption.
- CRISPR-isogenic integration:Gene editing convergence with patient-derived tumor models enables pharmaceutical sponsors to generate disease-specific screening panels at scale.
- German biopharma clustering:Heidelberg and Munich host dense contract research infrastructure that concentrates demand for intestinal and hepatic organoid formats.
Market Restraints
- Matrigel supply concentration:Natural extracellular matrix hydrogels derive from Engelbreth-Holm-Swarm mouse sarcomas, creating single-source dependency on Corning Life Sciences for GMP-grade material.
- ISO 20391 validation gaps:Incomplete harmonization between the 3D cell culture characterization standard and national pharmacopeias forces redundant qualification studies.
- Perfusion bioreactor capex thresholds:Advanced organoid expansion requires stirred-tank or microfluidic systems priced beyond academic laboratory budgets.
Strategic Opportunities
- Japan's PMDA qualification pathway:The Japanese pharmaceutical regulator is accelerating approval timelines for organoid-based pharmacokinetic studies, opening access to the world's third-largest drug market.
- Immuno-oncology co-culture models:Tumor organoid-immune cell pairing addresses the failure rate of checkpoint inhibitors in solid tumors.
- Synthetic hydrogel substitution:Peptide-based alternatives to animal-derived matrices unlock vegan certification and reduce batch-to-batch variability.
Industry Challenges
- Bioprocess engineer scarcity:Organoid manufacturing requires hybrid expertise in stem cell biology and scalable suspension culture that existing biotechnology curricula rarely produce.
- Cross-platform data portability:Proprietary image analysis pipelines from Thermo Fisher, Molecular Devices, and Olympus create vendor lock-in that complicates multi-site clinical trials.
- Intellectual property fragmentation:CRISPR licensing from Broad Institute, organoid derivation patents from Hubrecht Institute, and matrix compositions from multiple holders generate royalty stacking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organoids Market |
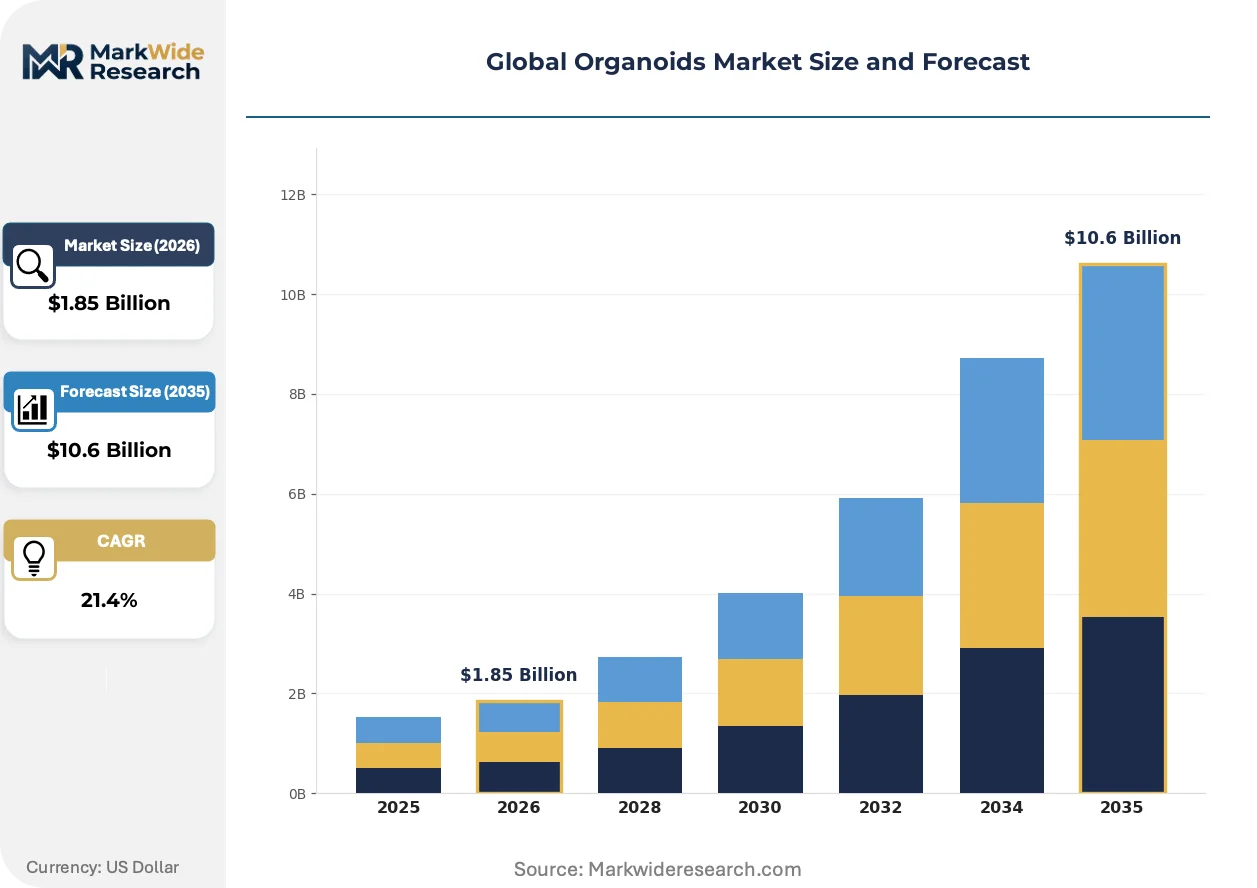
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brain Organoids, Liver Organoids, Kidney Organoids, Intestinal Organoids, Pancreatic Organoids Application: Drug Discovery, Disease Modeling, Personalized Medicine, Toxicology Testing, Developmental Biology End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutes, Contract Research Organizations, Diagnostic Laboratories Technology: 3D Cell Culture, Microfluidics, Bioprinting, CRISPR Gene Editing, High-Content Imaging |
| Companies Covered | Thermo Fisher Scientific Inc., Corning Incorporated, Merck KGaA, STEMCELL Technologies Inc., HUB Organoids BV, Sartorius AG, InSphero, BioIVT, DefiniGEN Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organoids Market Shifts & Advancements
Artificial intelligence and high-content imaging are converging to automate organoid phenotyping, compressing analysis timelines from weeks to days and enabling screening volumes that manual microscopy cannot sustain.
High-content imaging platforms equipped with machine-learning segmentation algorithms are digitizing morphometric readouts from intestinal and cerebral organoid models. Pharmaceutical toxicology departments at Roche and Novartis are deploying these systems for hepatotoxicity prediction. The technology is digitizing histopathological assessment, displacing subjective manual scoring with quantitative feature extraction that feeds directly into regulatory submission packages.
The European Medicines Agency's qualification opinion pathway for complex in vitro methods entered operational phase in 2024, creating explicit precedents for organoid-based efficacy claims. Dutch and Danish sponsors have secured scientific advice meetings referencing tumoroid drug response data. Oncology applications in colorectal and pancreatic cancer are responding fastest, with EMA feedback letters now citing organoid-derived biomarker rationale.
Biopharma procurement departments are unbundling organoid sourcing from full-service contract research, establishing direct supplier relationships with Hubrecht Organoid Technology and specialized academic biobanks. This disintermediation bypasses traditional CRO markups on pass-through reagent costs. The shift is most visible in Boston and San Francisco, where venture-backed oncology startups maintain in-house organoid facilities rather than outsourcing to Charles River or Covance.
Global Organoids Market Segmentation
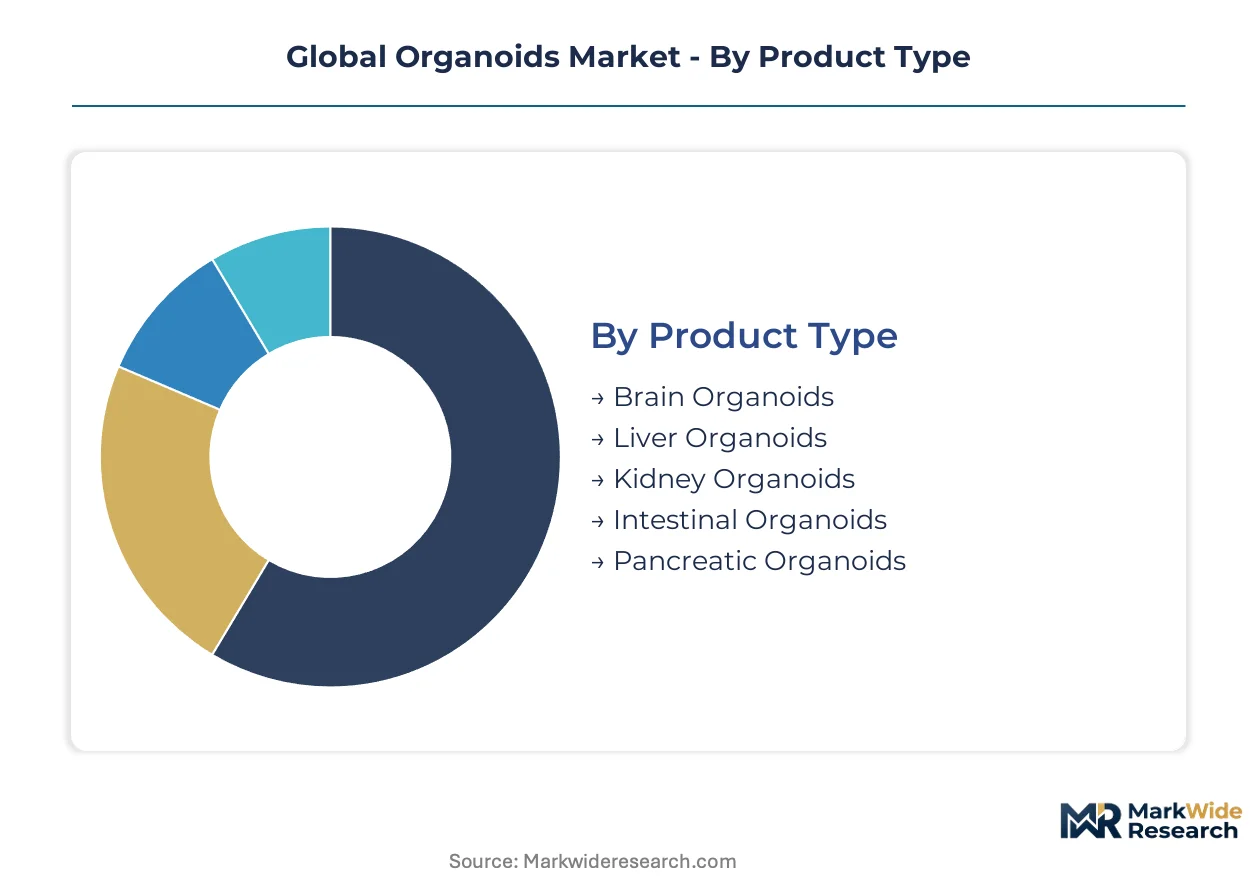
Segmentation in the organoids market determines procurement patterns across biopharma R&D budgets. Each dimension—product format, application purpose, end-user sophistication, and enabling technology—shapes pricing tiers and supplier relationships differently.
Product Type:
After-sales service intensity varies sharply by organoid complexity, with cerebral and hepatic formats demanding sustained technical support for media optimization and quality control troubleshooting.
- Intestinal Organoids:Derived from Lgr5+ stem cells embedded in Matrigel with Wnt3a, R-spondin, and Noggin supplementation. Cystic fibrosis drug validation at Vertex Pharmaceuticals and inflammatory bowel disease programs at Takeda concentrate procurement in Boston and Osaka. These formats benefit from the most mature commercial protocols.
- Liver Organoids:Hepatocyte-biliary lineage co-cultures requiring HGF and EGF gradients for metabolic maturation. Roche and Novartis toxicology departments in Basel drive demand for hepatotoxicity prediction ahead of IND filings. Supply constraints include donor tissue variability and CYP450 enzyme stability.
- Brain Organoids:Forebrain-patterned spheroids using dual-SMAD inhibition and Wnt modulation for cortical layer formation.
- Kidney Organoids:Nephron progenitor-derived structures with glomerular and tubular segmentation.
- Pancreatic Organoids:Ductal and acinar lineage models for diabetes and pancreatic cancer applications.
Intestinal organoids hold the largest share; momentum sits with liver organoids as hepatotoxicity failures drive regulatory substitution mandates.
Application:
Cost tier stratification separates validation-heavy pharmaceutical submissions from exploratory academic research, with pricing spreads of 3-5x between GMP-grade and research-use-only formats.
- Drug Discovery:High-throughput screening of compound libraries against patient-derived tumor panels. Pfizer and AstraZeneca oncology units in Cambridge, Massachusetts and Gothenburg have replaced 30-50% of 2D assays with organoid protocols. CRISPR-edited isogenic lines command premium pricing for target validation.
- Disease Modeling:Patient-specific organoids recapitulating genetic disorders for mechanistic study and therapeutic target identification. Academic medical centers in Heidelberg and Stanford lead biobanking initiatives.
- Personalized Medicine:Tumoroid drug response profiling to guide chemotherapy selection.
- Toxicology Testing:Regulatory-compliant safety assessment replacing animal studies.
- Developmental Biology:Fundamental research into organogenesis and stem cell biology.
Drug discovery absorbs the majority of commercial expenditure; personalized medicine is expanding most quickly as reimbursement frameworks mature.
End User:
Customer type dictates contract structure, with pharmaceutical sponsors preferring multi-year supply agreements while academic institutes purchase through distributor consortia.
- Pharmaceutical Companies:Internal organoid facilities at Merck KGaA, Roche, and Johnson & Johnson bypass CRO markups. Direct sourcing from Hubrecht Organoid Technology and Cellesce concentrates in New Jersey, Basel, and Tokyo.
- Biotechnology Firms:Venture-backed oncology startups in South San Francisco and Cambridge maintain captive organoid capabilities for investor due diligence.
- Academic Research Institutes:NIH and EU Horizon-funded laboratories with limited bioprocess engineering capacity.
- Contract Research Organizations:Charles River and Evotec integrating organoid services into toxicology portfolios.
- Diagnostic Laboratories:Clinical reference labs exploring tumoroid testing for precision oncology.
Pharmaceutical companies dominate procurement volume; biotechnology firms are gaining share fastest as venture funding flows into immuno-oncology.
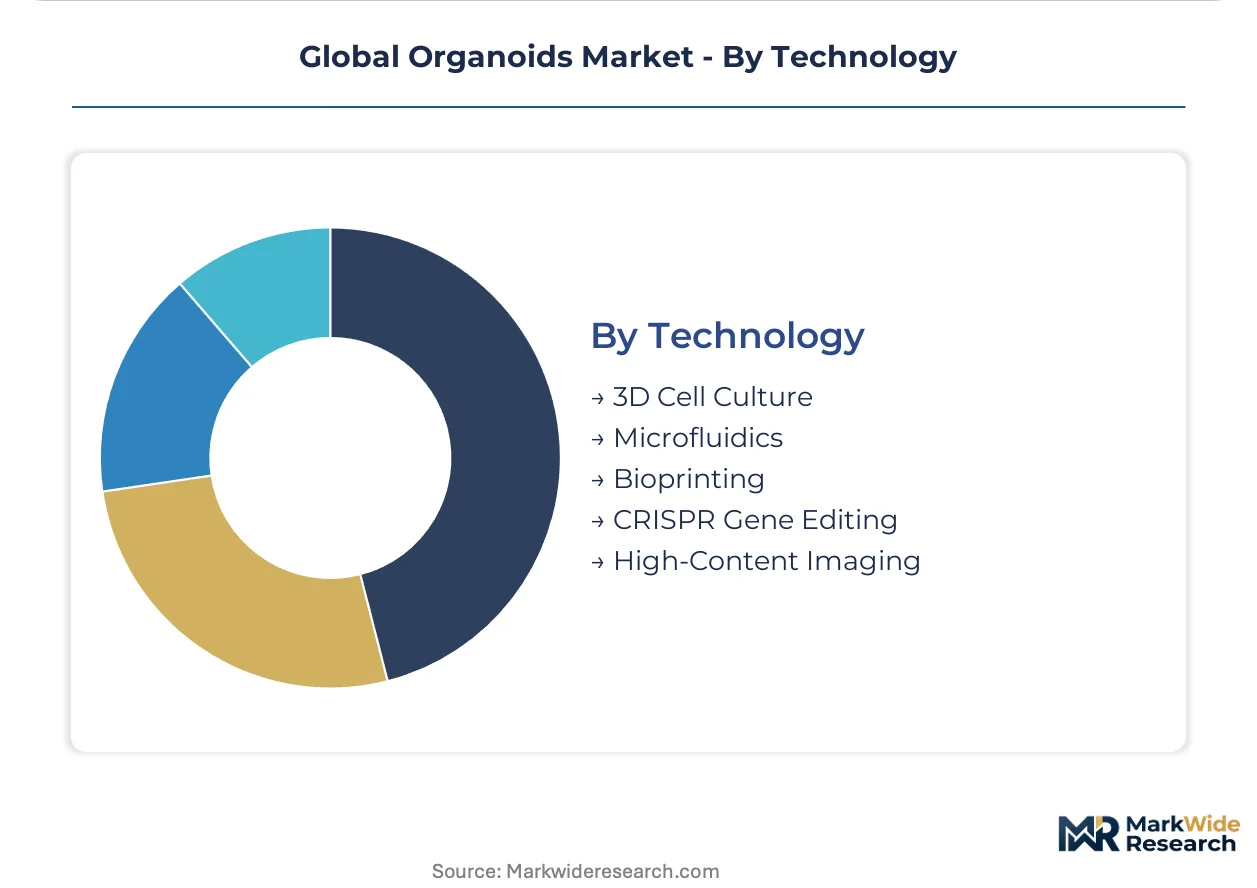
Technology:
Supply concentration in enabling platforms creates vendor lock-in, with proprietary image analysis pipelines complicating multi-site trial data portability.
- CRISPR Gene Editing:Isogenic disease model generation through homology-directed repair in intestinal and hepatic progenitors. Broad Institute licensing and Synthego synthetic gRNA supply anchor the ecosystem. Premium pricing reflects IP stacking from multiple holders.
- 3D Cell Culture:Matrigel and synthetic hydrogel embedding with defined growth factor cocktails. Corning Life Sciences controls GMP-grade natural matrix supply.
- Microfluidics:Perfusion-based organoid maturation and vascularization.
- Bioprinting:Extrusion and light-based patterning for multi-cellular tissue assembly.
- High-Content Imaging:Machine-learning phenotyping automation for morphometric analysis.
3D cell culture underpins the installed base; CRISPR integration shows the steepest expansion trajectory as pharmaceutical sponsors scale disease-specific screening panels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organoid supply chains concentrate where biopharma R&D infrastructure clusters most densely, with reagent manufacturing anchoring in industrial corridors while application development localizes near academic medical centers and regulatory agencies.
United States
FDA Modernization Act 2.0 provisions explicitly qualify complex in vitro models for drug submissions, eliminating prior animal-study mandates. The agency's qualification pathway for complex in vitro models entered operational phase in 2024, accelerating regulatory acceptance. Boston and San Francisco Bay Area clusters host venture-backed oncology startups maintaining captive organoid facilities for investor due diligence.
Germany
Heidelberg and Munich host dense contract research infrastructure concentrating demand for intestinal and hepatic organoid formats. EMA's qualification opinion pathway for complex in vitro methods creates explicit precedents for organoid-based efficacy claims. Merck KGaA anchors European production through its MilliporeSigma bioscience division in Darmstadt.
Japan
PMDA is accelerating approval timelines for organoid-based pharmacokinetic studies, opening access to the world's third-largest drug market. METI funding programs support domestic biomanufacturing capacity expansion. Tokyo and Osaka pharmaceutical corridors drive procurement of patient-derived tumor models for oncology applications.
Netherlands
Hubrecht Institute-derived intellectual property anchors the country's organoid technology ecosystem. Dutch sponsors have secured EMA scientific advice meetings referencing tumoroid drug response data. Utrecht and Amsterdam clusters specialize in patient-derived tumor models for colorectal and pancreatic cancer applications.
United Kingdom
Cambridge and Oxford academic medical centers lead biobanking initiatives for disease-specific organoid generation. MHRA alignment with EMA qualification pathways reduces redundant validation studies for cross-border submissions. London pharmaceutical headquarters drive demand for toxicology testing services replacing animal studies.
Global Organoids Market Competitive Landscape
Life science conglomerates and specialized organoid technology developers split the market between scale-driven reagent supply and proprietary disease model portfolios. Three strategic archetypes dominate: diversified laboratory suppliers controlling distribution infrastructure, dedicated organoid platform companies holding derivation patents, and contract research organizations integrating organoid services into toxicology portfolios. Competitive dynamics center on backward integration into matrix manufacturing and exclusive licensing of CRISPR-edited disease model libraries.
Within the diversified supplier tier, Thermo Fisher Scientific leverages its cell culture media portfolio to dominate reagent distribution, while Corning Incorporated controls GMP-grade Matrigel supply. HUB Organoids BV occupies a specialist position in patient-derived tumor models. These three entities exemplify how market position derives from control over distinct value chain segments rather than direct competition.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Corning Incorporated |
| Merck KGaA |
| STEMCELL Technologies Inc. |
| HUB Organoids BV |
| Sartorius AG |
| InSphero |
| BioIVT |
| DefiniGEN Limited |
| Others |
Supply & Pricing Matrix
Corning Life Sciences' monopoly on GMP-grade Matrigel production from Engelbreth-Holm-Swarm mouse sarcomas funnels margin pools toward matrix suppliers, forcing downstream organoid developers to absorb cost volatility or invest in synthetic alternatives.
Pricing Analysis
FDA Modernization Act 2.0 provisions dictate the pricing tier structure across the organoid market, separating GMP-grade validation-ready formats from research-use-only materials. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with CRISPR-edited isogenic lines commanding the highest premiums. Cost compression in synthetic hydrogel tiers is intensifying because peptide-based alternatives reduce batch-to-batch variability. Academic research institutes exhibit the highest price sensitivity, while pharmaceutical sponsors prioritize regulatory compliance over unit cost.
Supply Chain Analysis
Extended payment terms from large pharmaceutical sponsors strain working capital for specialized organoid technology developers, compressing cash conversion cycles. Raw material sourcing draws from the United States for GMP-grade Matrigel, Germany for MilliporeSigma reagents, and the Netherlands for Hubrecht-derived intellectual property. Critical dependencies include growth factor cocktails, extracellular matrix hydrogels, and patient-derived tissue biopsies. Single-source vulnerability around Corning's animal-derived matrix supply creates structural risk. Distribution runs through direct supplier relationships with biopharma R&D facilities, bypassing traditional CRO markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organoid market sits in early-cycle expansion, with FDA and EMA qualification pathways for complex in vitro models accelerating substitution of animal studies and widening addressable demand.
For Market Incumbents: Harden supply chain resilience by securing captive synthetic hydrogel production or exclusive licensing agreements with peptide-matrix developers, insulating against Corning concentration risk. Deepen regulatory affairs capabilities to navigate ISO 20391 harmonization gaps, converting compliance investment into procurement preference from risk-averse pharmaceutical sponsors. For New Entrants and Emerging Players: Japan's underpenetrated PMDA qualification pathway offers the most penetrable geographic entry point, with METI funding programs de-risking domestic biomanufacturing capacity buildout. Target immuno-oncology co-culture models as the fastest-expanding application white space, leveraging academic partnerships for tumoroid-immune cell pairing protocols rather than building de novo derivation capabilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed oncology startups in Boston and San Francisco that have built captive organoid facilities but face Series C financing pressure. Five-to-ten-year viability hinges on regulatory substitution mandates deepening across toxicology and pharmacokinetic applications. Watch EMA qualification opinion letters citing organoid-derived biomarker rationale as the inflection signal for reimbursement framework maturation in personalized medicine.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Hydrogel Scale-Up | Peptide-based matrix manufacturing unlocks vegan certification and reduces Corning dependency for GMP-grade supply. |
| CRISPR-Isogenic Library Expansion | Broad Institute licensing agreements enable pharmaceutical sponsors to generate disease-specific screening panels at scale. |
| Regulatory Qualification Pathway Investment | FDA and EMA complex in vitro model submissions accelerate organoid-based efficacy claims for IND filings. |
| Perfusion Bioreactor Deployment | Microfluidic organoid maturation systems address hepatocyte CYP450 stability constraints in liver toxicology applications. |
| Academic Biobank Partnership | Direct sourcing from Stanford and Heidelberg biobanking initiatives bypasses CRO markups on patient-derived tumor models. |
Research Methodology
Cross-validation between primary interviews with biopharma executives and secondary validation from regulatory filings anchors the qualitative findings. Drug development executives, regulatory affairs leads at FDA and EMA, hospital procurement managers, and organoid platform engineers provided operational perspective. FDA qualification pathway documentation, EMA scientific advice meeting records, ISO 20391 standard drafts, and ClinicalTrials.gov organoid protocol registrations supplied secondary validation. Bottom-up segment sizing and top-down market triangulation reconciled volume and value estimates across the analysis window.
Calibration against historical adoption curves for prior complex in vitro model categories shaped the analytical framework. Segmentation dimensions modeled include organoid product type, application purpose, end-user sophistication, and enabling technology platform, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs derived from fitted growth curves incorporating pharmaceutical R&D budget trajectories and regulatory substitution elasticity. CRISPR integration penetration rates and synthetic hydrogel substitution timelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by diversified laboratory suppliers would shift outcomes. Macroeconomic contraction in biopharma venture funding, regulatory harmonization failures between FDA and EMA pathways, or breakthrough advances in animal model alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Global Bifida Ferment Lysate Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
Global Molecular Biosensors Market
Biomedical Technology
Live Cell RNA Detection Market
Biomedical Technology
Polymerase Chain Reaction Technologies Market
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Protein Expression Technology Market
Biomedical Technology
Nano-Silicon Drug Delivery Platform Market
Biomedical Technology
Digital Biology Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Oligonucleotide Synthesis Market