
 Biologics Outsourcing Market | 2026-2036
Biologics Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Biologics Outsourcing Market Analysis
Cell and gene therapy-grade manufacturing standards are reorganizing competitive priorities across the biologics outsourcing landscape. Lonza Group anchors its position through integrated cell-and-gene therapy platforms spanning viral vector production. Samsung Biologics dominates large-scale mammalian cell culture capacity with purpose-built facilities in Songdo. WuXi Biologics extends its geographic footprint through multi-modal biologics capabilities across discovery, development, and commercial manufacturing.
Biologics outsourcing encompasses the delegation of development, manufacturing, and analytical services for complex protein-based therapeutics, viral vectors, and nucleic acid products to specialized third-party organizations, typically requiring mammalian or microbial cell culture systems, aseptic processing, and multi-step purification trains achieving purity thresholds above 99%. Contract manufacturing captures the dominant value pool as sponsors prioritize asset-light operating models, while cell and gene therapies represent the fastest-expanding product category driven by escalating clinical pipelines and limited in-house viral vector capacity. Monoclonal antibodies remain the mature volume anchor, though margin compression in this segment pushes CDMOs toward higher-complexity modalities.
FDA's Quality by Design mandates and EMA's ATMP certification requirements are elevating barrier-to-entry for new contract manufacturers while accelerating qualification timelines for established players with prior regulatory approvals. China's NMPA and South Korea's MFDS are implementing convergent biosimilar and novel biologics guidelines that shape local outsourcing demand and cross-border supply strategies. Stakeholders must monitor regulatory divergence between major agencies and assess manufacturing network redundancy as geopolitical risk intersects with biologics supply security imperatives.
Market Dynamics
Viral vector manufacturing capacity constraints are forcing oncology developers into long-term exclusive partnerships with CDMOs possessing validated gene therapy suites, restructuring competitive access and pricing power across the biologics outsourcing landscape.
Growth Catalysts
- FDA Quality by Design mandates:Sponsors lacking in-house process analytical technology capabilities must outsource to CDMOs with validated QbD platforms, accelerating qualification timelines for established contract manufacturers.
- Cell therapy clinical pipeline expansion:CAR-T and gene editing trials require specialized aseptic processing and viral vector production that biopharma developers rarely maintain internally.
- South Korea's Songdo biocluster:Concentrated government investment in mammalian cell culture infrastructure attracts multinational sponsors seeking large-scale GMP capacity with MFDS-aligned regulatory pathways.
Market Restraints
- Plasmid DNA supply concentration:Limited qualified suppliers of GMP-grade plasmid for viral vector production create input bottlenecks and price volatility for gene therapy CDMOs.
- EMA ATMP certification complexity:Novel cell and gene therapy manufacturers face extended regulatory timelines and facility qualification costs that deter new contract manufacturing entrants.
- Stainless steel bioreactor displacement:Single-use systems reduce cross-contamination risk but introduce polymer supply dependencies and higher per-batch consumables costs at commercial scale.
Strategic Opportunities
- China's NMPA biosimilar pathway convergence:Streamlined approval frameworks for novel biologics and biosimilars attract foreign sponsors seeking local manufacturing partnerships for domestic market access.
- Continuous bioprocessing integration:Perfusion cell culture coupled with continuous chromatography enables smaller facility footprints and real-time quality release, appealing to mid-cap biotechs with limited capital.
- Microbial expression system revival:Biosimilar developers and vaccine manufacturers are reactivating E. coli and yeast platforms for non-glycosylated proteins, opening capacity at CDMOs previously dedicated to mammalian systems.
Industry Challenges
- Viral vector analytical method transfer:Potency assay development and reference standard qualification create 12-18 month program delays that compress development timelines and strain sponsor-CDMO relationships.
- Multi-product facility changeover protocols:Campaign-to-campaign cleaning validation and segregation requirements for cytotoxic antibody-drug conjugates consume non-productive capacity and complicate scheduling.
- Gene therapy workforce scarcity:Qualified professionals with combined viral vector production and regulatory submission experience command premium compensation, inflating CDMO operating costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biologics Outsourcing Market |
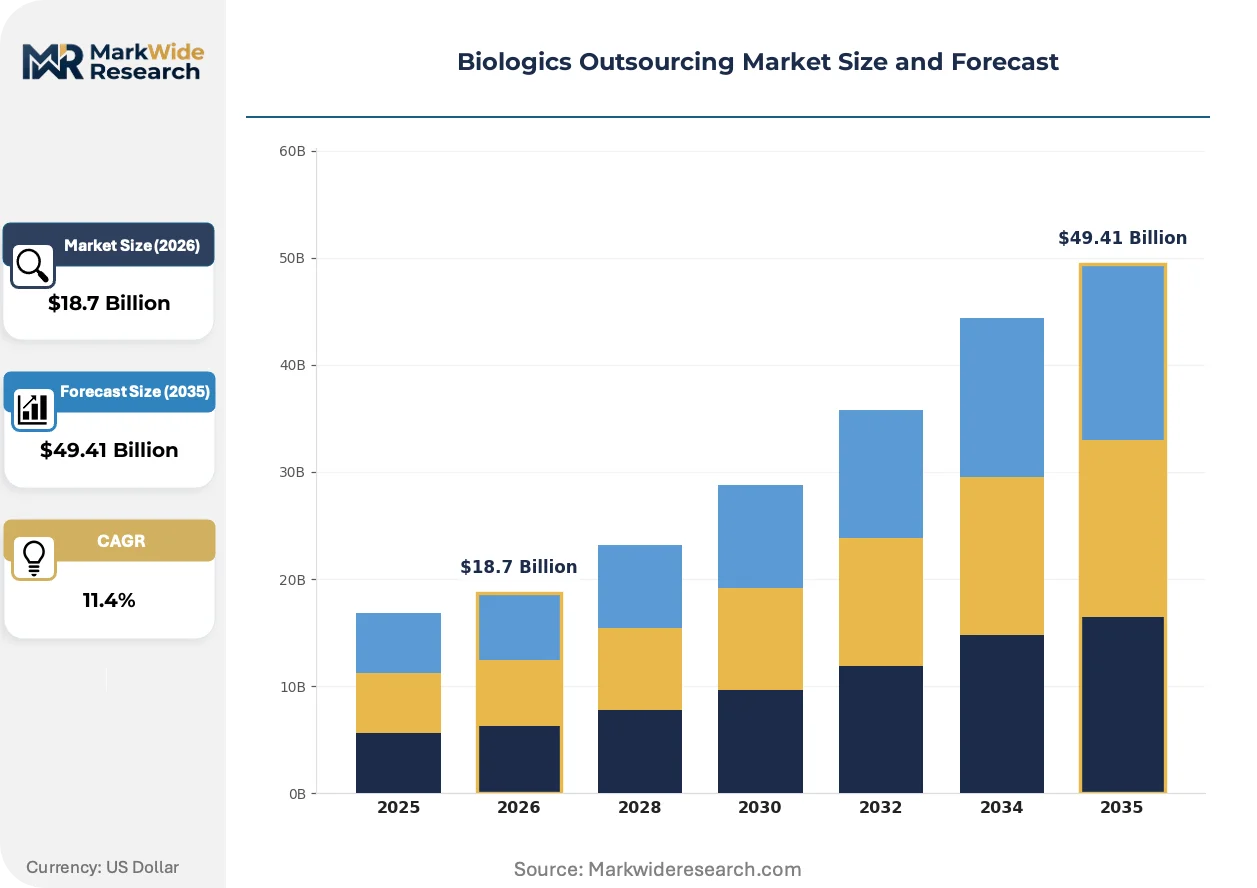
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Contract Manufacturing, Contract Research, Fill-Finish Services, Quality Control Product Type: Monoclonal Antibodies, Vaccines, Therapeutic Proteins, Cell and Gene Therapies End User: Pharmaceutical Companies, Biotech Firms, Academic Institutions, Research Organizations Technology: Recombinant DNA Technology, Monoclonal Antibody Production, Cell Culture Techniques, Purification Methods |
| Companies Covered | Lonza Group, WuXi Biologics, Samsung Biologics, Catalent, Boehringer Ingelheim, Thermo Fisher Scientific, Fujifilm Diosynth Biotechnologies, AGC Biologics, Eurofins Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biologics Outsourcing Market Emerging Trajectories
Process intensification technologies and modular facility designs are compressing biologics development timelines while regulatory convergence efforts reshape qualification requirements across major pharmaceutical markets.
Continuous manufacturing platforms employing perfusion bioreactors and integrated continuous downstream processing are supplanting traditional fed-batch operations in new facility designs. Mid-cap biotech sponsors with accelerated clinical timelines now specify continuous capabilities in CDMO selection criteria, pressuring established contract manufacturers to retrofit legacy batch infrastructure or cede competitive position in speed-sensitive programs.
EMA's revised ATMP GMP guidelines and FDA's emerging standards for gene therapy CMC are elevating documentation and facility segregation requirements for viral vector production. CDMOs with prior agency inspections and approved product licenses capture disproportionate sponsor interest, while new entrants face extended qualification periods and limited audit access from risk-averse biopharma developers.
Biopharma procurement teams now segment manufacturing partnerships by modality risk tier rather than geographic convenience, concentrating gene therapy programs with CDMOs possessing dedicated viral vector suites regardless of location. This pattern is most visible among US-based oncology developers who previously favored domestic manufacturing but now qualify Asian facilities with validated AAV and lentiviral platforms for commercial supply.
Biologics Outsourcing Market Segmentation
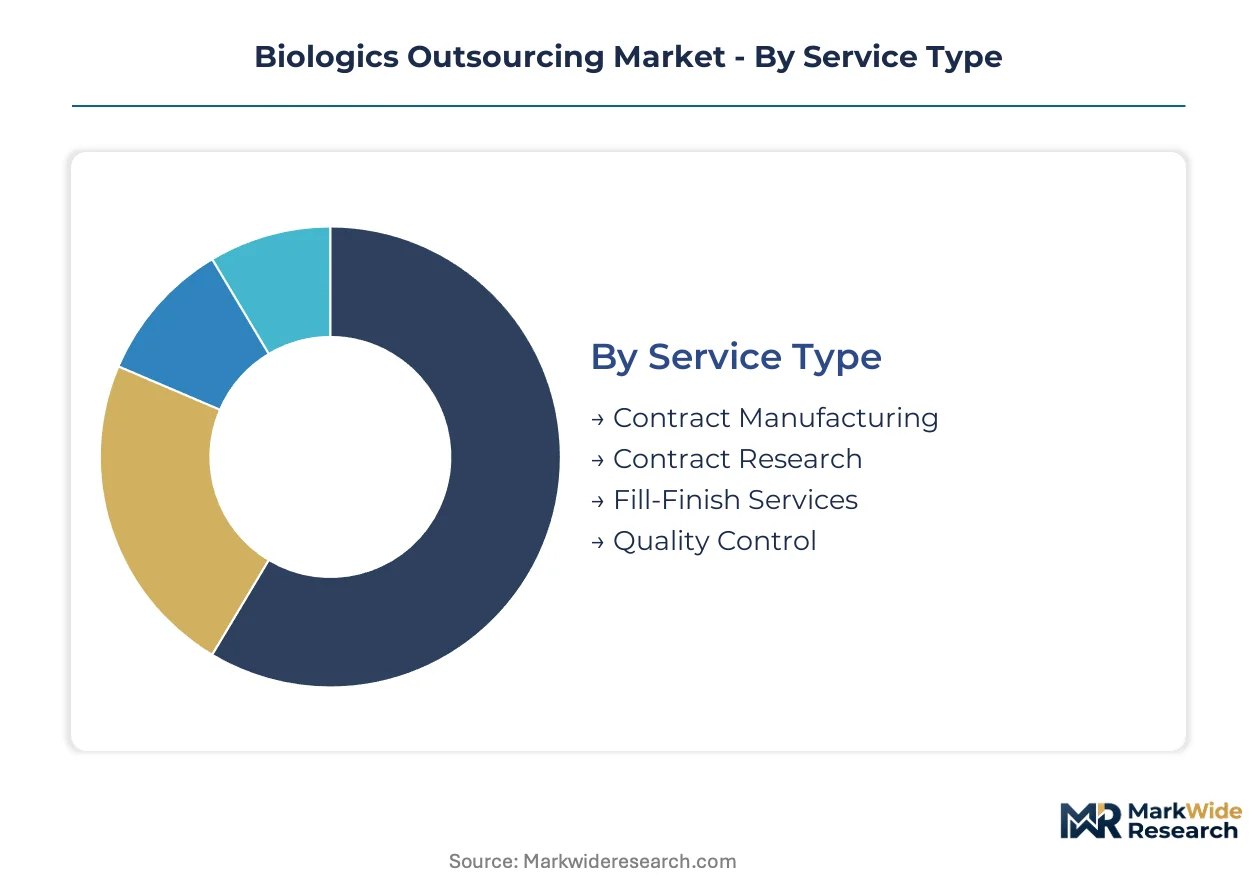
Segmentation in biologics outsourcing reveals how service capabilities align with modality complexity and regulatory requirements across different sponsor types. Each dimension exposes distinct capacity constraints and partnership patterns that shape CDMO selection criteria.
Service Type:
Contract manufacturing services concentrate in the United States, China, and South Korea where dedicated biologics clusters serve export markets, while quality control and analytical services remain more geographically dispersed near sponsor R&D centers.
- Contract Manufacturing:Mammalian cell culture operations in stainless steel and single-use bioreactors constitute the core revenue pool for established CDMOs. Samsung Biologics in Songdo and WuXi Biologics in Wuxi anchor large-scale capacity serving multinational sponsors seeking MFDS-aligned and NMPA-aligned regulatory pathways for Asian market access.
- Contract Research:Cell line development, process characterization, and analytical method development services cluster near Boston, San Francisco, and Basel where sponsor R&D density supports iterative collaboration. These engagements typically precede manufacturing partnerships and lock in long-term CDMO relationships.
- Fill-Finish Services:Aseptic vial and syringe filling for injectable biologics requires isolator technology and specialized lyophilization capacity.
- Quality Control:Release testing, stability studies, and regulatory documentation support spans multiple geographies with lower capital barriers.
Contract Manufacturing holds the largest share; momentum sits with Contract Research as early-stage partnerships expand.
Product Type:
Product categories stratify by manufacturing maturity, with established modalities commanding volume and novel therapies driving capacity investment and capability acquisition.
- Monoclonal Antibodies:Fed-batch and perfusion-based mammalian cell culture yields standardized IgG therapeutics at multi-tonne annual scale. Chinese CDMOs leverage NMPA biosimilar pathway convergence to capture foreign sponsor demand for domestic market entry, while margin compression in this segment pushes providers toward higher-value modalities.
- Cell and Gene Therapies:Viral vector production and aseptic cell processing require dedicated facility suites with segregated air handling. Lonza Group and specialized gene therapy CDMOs command premium pricing due to validated AAV and lentiviral platforms, with US oncology developers now qualifying Asian facilities regardless of prior geographic preferences.
- Vaccines:Microbial expression systems and egg-based production retain relevance for pandemic preparedness and seasonal manufacturing.
- Therapeutic Proteins:Cytokines, growth factors, and enzyme replacement therapies span mammalian and microbial production platforms.
Monoclonal Antibodies retains dominant volume share; Cell and Gene Therapies are climbing the fastest as clinical pipeline expansion outstrips in-house capacity.
End User:
Customer type determines contract structure, with large pharmaceutical sponsors favoring multi-year capacity reservations and emerging biotechs seeking flexible milestone-based engagements.
- Pharmaceutical Companies:Multinational sponsors including Roche, Novartis, and Pfizer pursue asset-light operating models through strategic manufacturing partnerships. These relationships emphasize regulatory track record, geographic redundancy, and multi-modality capability across mammalian, microbial, and viral vector platforms.
- Biotech Firms:Venture-backed developers with single-asset portfolios prioritize speed and risk-sharing over scale, driving demand for integrated CDMOs offering cell line development through commercial manufacturing. FDA Quality by Design mandates accelerate their reliance on established contract manufacturers with validated process analytical technology capabilities.
- Academic Institutions:University-based translational programs require small-scale GMP batches for early-phase investigator-initiated trials.
- Research Organizations:Non-profit and government research entities seek fee-for-service manufacturing for prototype biologics and reference standards.
Pharmaceutical Companies anchor contract value; Biotech Firms are gaining share fastest as capital constraints deepen outsourcing penetration.
Technology:
Technology platforms differentiate CDMO competitive positioning, with continuous processing and advanced analytics reshaping facility investment priorities.
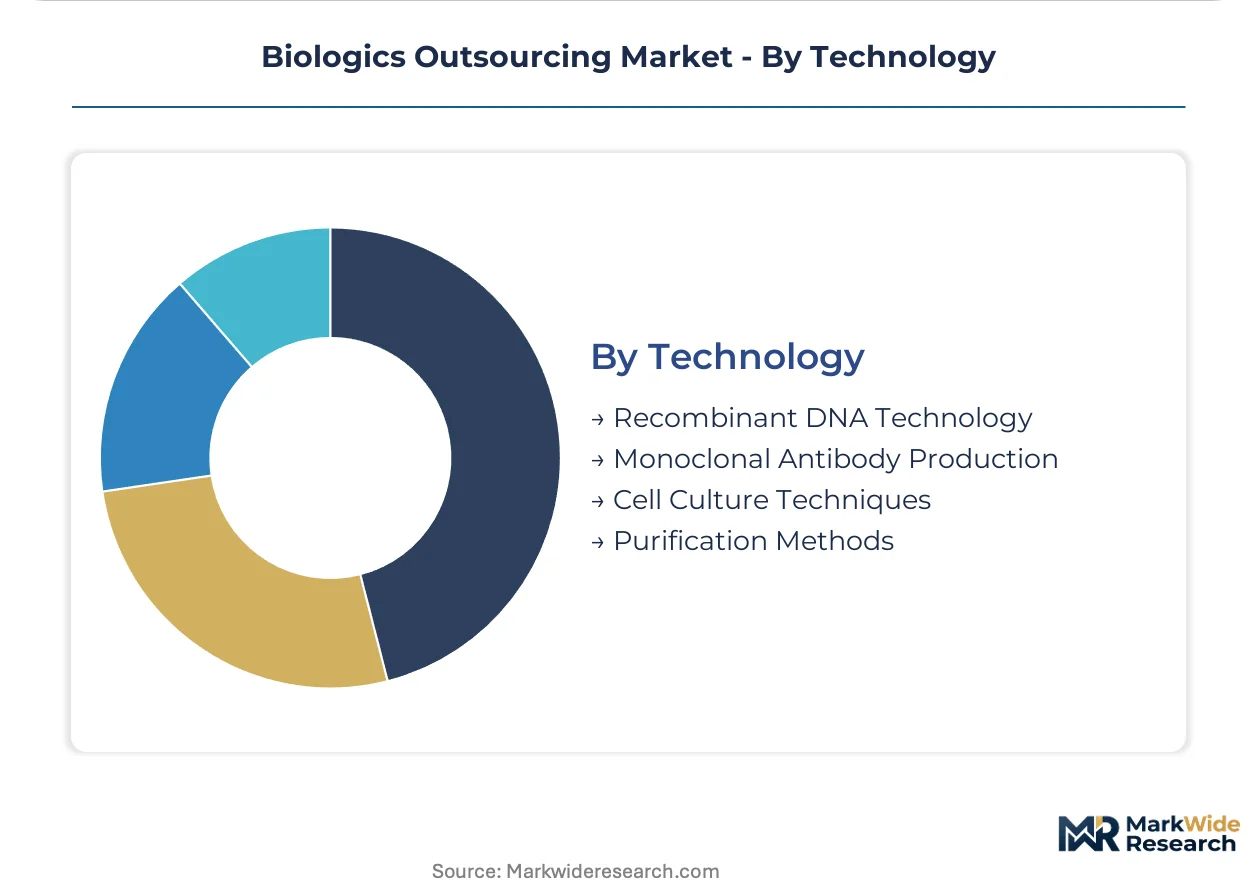
- Recombinant DNA Technology:Gene insertion and expression vector engineering underpin all modern biologics production. This foundational capability concentrates at CDMOs with proprietary host cell line platforms and intellectual property positions in high-yielding Chinese hamster ovary and human cell expression systems.
- Monoclonal Antibody Production:Hybridoma and transgenic technologies for therapeutic antibody generation remain essential despite industry shift toward recombinant approaches. Established CDMOs leverage decades of regulatory filings and reference standard libraries to maintain sponsor relationships in this mature segment.
- Cell Culture Techniques:Perfusion and intensified fed-batch operations enable higher cell densities and improved volumetric productivity.
- Purification Methods:Protein A affinity chromatography and multi-step polishing trains achieve purity thresholds exceeding 99% for clinical and commercial release.
Recombinant DNA Technology commands foundational importance across all segments; Cell Culture Techniques are expanding most quickly as continuous processing retrofits accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing capacity clusters in three national hubs where government-backed infrastructure investments and regulatory alignment attract multinational sponsor demand. The United States, China, and South Korea anchor supply-side concentration through purpose-built bioclusters and convergent quality standards.
United States
Oncology developers in Boston and San Francisco drive demand for viral vector and cell therapy manufacturing partnerships. FDA's Quality by Design framework mandates process analytical technology capabilities that accelerate sponsor reliance on established contract manufacturers with prior agency approvals. The Greater Boston corridor concentrates gene therapy CDMOs serving venture-backed biotechs with accelerated clinical timelines.
China
Multinational sponsors seeking domestic market access leverage local manufacturing partnerships under NMPA's convergent biosimilar and novel biologics guidelines. WuXi Biologics anchors multi-modal capabilities across discovery through commercial manufacturing in the Yangtze River Delta. Government investment in dedicated biologics infrastructure supports export-oriented capacity serving global pharmaceutical companies.
South Korea
Songdo's purpose-built mammalian cell culture facilities attract sponsors requiring MFDS-aligned regulatory pathways for Asian market entry. Samsung Biologics dominates large-scale GMP capacity with stainless steel and single-use bioreactor trains. Government-backed biocluster development concentrates specialized aseptic processing and fill-finish capabilities for injectable biologics.
Switzerland
Swissmedic's alignment with EMA standards positions Basel-region CDMOs as gateways for European commercial supply. Lonza Group anchors integrated cell-and-gene therapy platforms spanning viral vector production for global oncology developers. The country's pharmaceutical manufacturing heritage supports specialized analytical method development and regulatory documentation services.
Germany
Boehringer Ingelheim leverages decades of mammalian cell culture expertise to serve multinational sponsors with multi-tonne antibody manufacturing requirements. German CDMOs benefit from EMA's evolving ATMP guidelines and established GMP inspection track records. The country's industrial bioprocessing equipment base supports continuous manufacturing retrofits and perfusion technology integration.
Biologics Outsourcing Market Vendor Landscape
Concentration sits with integrated platform providers possessing validated regulatory track records across mammalian, microbial, and viral vector modalities. The vendor base stratifies into three tiers: global-scale mammalian specialists, gene therapy-dedicated platforms, and regional fill-finish operators. Dominant competitive moves include capacity expansion in Asian bioclusters and strategic partnerships locking in long-term sponsor commitments for cell therapy programs.
Within the integrated platform tier, Lonza Group exemplifies end-to-end cell-and-gene therapy capabilities spanning viral vector suites through commercial release. Samsung Biologics anchors the scale-driven segment with purpose-built mammalian facilities in Songdo. WuXi Biologics occupies a position spanning discovery services through multi-regional commercial manufacturing under convergent NMPA and FDA pathways.
| Leading Market Players |
|---|
| Lonza Group |
| WuXi Biologics |
| Samsung Biologics |
| Catalent |
| Boehringer Ingelheim |
| Thermo Fisher Scientific |
| Fujifilm Diosynth Biotechnologies |
| AGC Biologics |
| Eurofins Scientific |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-month viral vector analytical method transfer timelines concentrate pricing power with CDMOs possessing validated potency assays and reference standard libraries, while sponsors absorb schedule compression costs through premium project fees. FDA Quality by Design mandates and EMA ATMP certification requirements stratify contract values across regulatory track record tiers, rewarding established manufacturers with prior agency approvals.
Pricing Analysis
FDA Quality by Design mandates dictate the pricing tier structure across the biologics outsourcing landscape. Three-tier pricing structure across premium, standard, and economy levels separates gene therapy CDMOs with dedicated viral vector suites from mammalian specialists and commodity fill-finish operators. Cost compression in monoclonal antibody manufacturing intensifies because Chinese CDMOs leverage NMPA biosimilar pathway convergence to capture foreign sponsor volume. Venture-backed biotech firms exhibit highest price sensitivity due to single-asset capital constraints, while multinational pharmaceutical sponsors prioritize regulatory track record over unit economics.
Supply Chain Analysis
Plasmid DNA inventory cycles stretching six to nine months expose gene therapy CDMOs to input bottlenecks and price volatility from limited GMP-grade suppliers. Manufacturing capacity concentrates in the United States, China, and South Korea where purpose-built bioclusters anchor mammalian cell culture and viral vector production. Supply chains draw from specialized single-use bioreactor consumables, protein A affinity chromatography resins, and aseptic isolator components. Single-source vulnerability in polymer supply for disposable systems creates campaign interruption risk. Distribution runs through long-term exclusive partnerships rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated viral vector production expertise and combined regulatory submission experience represent acute capability gaps that constrain CDMO expansion and concentrate sponsor relationships with incumbent platform providers.
For Market Incumbents: Consolidate gene therapy manufacturing partnerships through capacity reservations in Songdo and Wuxi bioclusters, securing multi-year sponsor commitments before emerging microbial expression competitors capture biosimilar volume. Defend margin position by investing in continuous bioprocessing retrofits that reduce per-batch consumables costs and compress development timelines for speed-sensitive biotech sponsors. For New Entrants and Emerging Players: Anchor in microbial expression system revival for non-glycosylated therapeutic proteins, capturing capacity at CDMOs previously dedicated to mammalian systems as biosimilar developers reactivate E. coli and yeast platforms. Target South Korea's government-backed biocluster infrastructure for fill-finish and aseptic processing specialization, leveraging MFDS-aligned regulatory pathways to serve Asian market entry strategies for Western sponsors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because EMA ATMP certification complexity and FDA prior-approval advantages create durable competitive barriers for established CDMOs with inspection track records. Acquisition candidates should demonstrate validated viral vector suites and existing commercial product licenses rather than greenfield capacity. The signal to watch is sponsor procurement team segmentation by modality risk tier rather than geographic convenience.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Samsung Biologics and WuXi Biologics expand Songdo and Wuxi capacity to capture multinational sponsor volume. |
| Regulatory Approval Pathway | EMA ATMP certification and FDA Quality by Design alignment accelerate qualification timelines for established CDMOs. |
| Backward Integration | Gene therapy CDMOs acquire plasmid DNA manufacturing capabilities to reduce input bottlenecks and price volatility. |
| Strategic Partnership | Oncology developers lock in long-term exclusive viral vector partnerships as capacity constraints intensify. |
| Technology Licensing | Continuous bioprocessing platform providers license perfusion and integrated chromatography to mid-cap biotech sponsors. |
Methodological Framework
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and CDMO capacity announcements preceded structured interviews with drug development executives, regulatory affairs leads, contract manufacturing procurement managers, and viral vector production specialists. Secondary validation drew from SEC 10-K disclosures, MFDS inspection reports, and NMPA biosimilar pathway documentation. Bottom-up service segment sizing and top-down market reconciliation provided cross-checks across the analysis window.
Variance decomposition across service type, product modality, end-user segment, and geographic regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included clinical pipeline expansion rates, viral vector manufacturing capacity utilization, and sponsor outsourcing penetration by company size tier.
Material uncertainties — regulatory divergence between FDA and EMA, geopolitical disruption of cross-border supply strategies, and plasmid DNA supplier consolidation — sit outside the modeled envelope. Forecasts reflect documented assumptions about sponsor asset-light operating model persistence and cell therapy clinical advancement rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Molecular Biosensors Market
Biomedical Technology
Global Optogenetics Market
Biomedical Technology
Global Cell Signaling Market
Biomedical Technology
Global Exosome Research Products Market
Biomedical Technology
Global Stem Cell Assay Market
Biomedical Technology
Exosomes Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Global Oncology Based in-Vivo CRO Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Europe Proteomics Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Liquid Biopsy Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Global Cell Sorting Market