
 Biomarker Detection Systems Market | 2026-2036
Biomarker Detection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Biomarker Detection Systems Market Analytics
A shortage of certified clinical laboratory scientists is unwinding throughput capacity at diagnostic laboratories running high-complexity biomarker assays. Thermo Fisher Scientific leverages its fluorescence detection portfolio to sustain installed-base loyalty across academic medical centers. QIAGEN anchors molecular testing workflows with sample-to-answer automation that reduces hands-on time. Abbott competes on point-of-care portability, extending its lateral flow architecture into decentralized oncology settings.
Biomarker detection systems comprise integrated hardware-software platforms that quantify protein, nucleic acid, or metabolite signatures in clinical specimens, typically achieving picogram-per-milliliter sensitivity through chemiluminescent or electrochemiluminescent readout. Their primary commercial purpose is to enable disease screening, patient stratification, and therapy monitoring in precision medicine workflows. Mass spectrometry segments command premium pricing due to capital intensity and specialized operator requirements, while PCR-based technologies lead volume deployment in infectious disease panels. Nanotechnology approaches represent the fastest-growing technology category as quantum dot and plasmonic enhancement methods mature.
FDA 510(k) and PMA pathways shape instrument development timelines, while EMA IVDR transition demands expanded clinical evidence for companion diagnostic claims. ISO 13485 quality management and CLIA laboratory certification constrain market access for non-compliant manufacturers. Stakeholders must monitor evolving payer coverage policies for liquid biopsy and multi-cancer early detection tests to anticipate reimbursement-driven demand shifts.
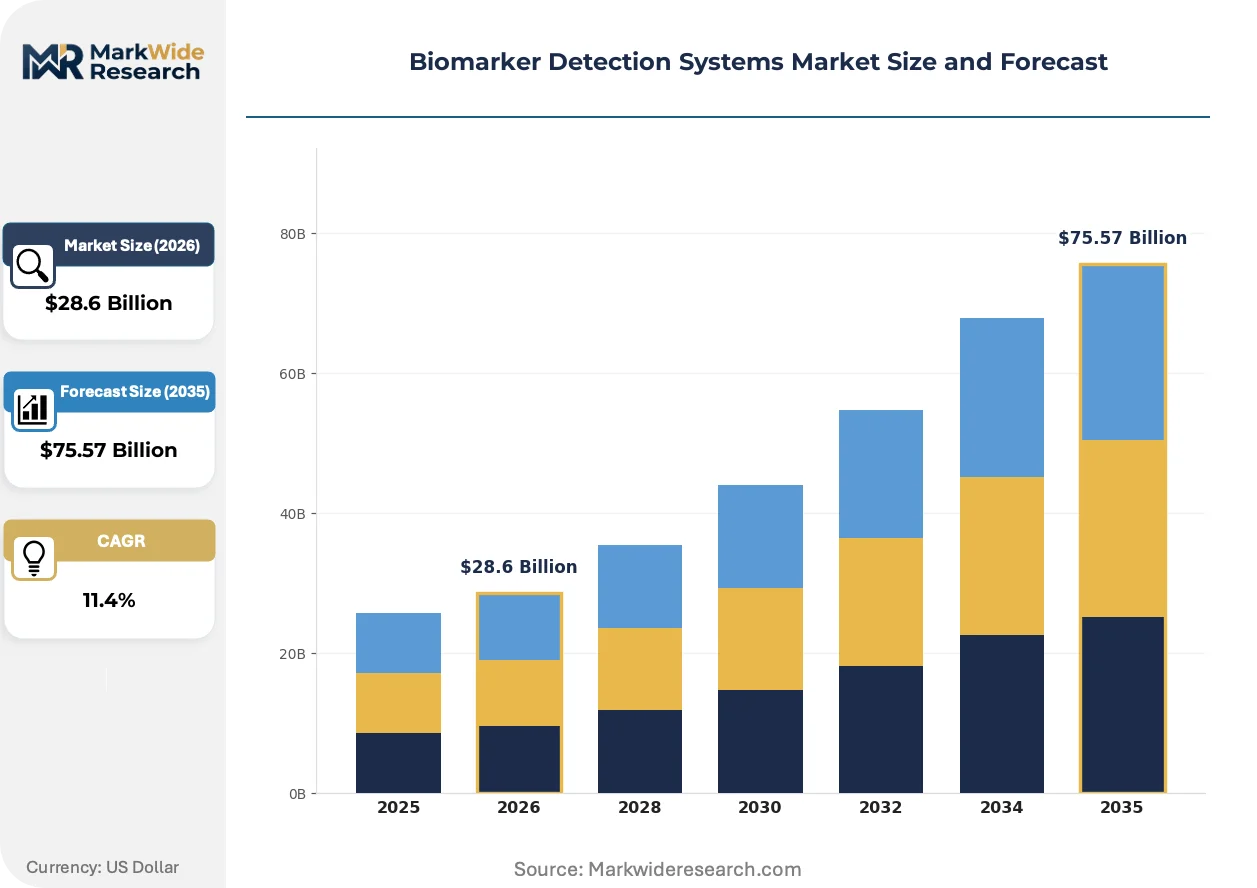
Market Dynamics
Companion diagnostic mandates from FDA and EMA are compressing instrument development timelines while simultaneously expanding the addressable market for qualified biomarker detection platforms across precision medicine workflows.
Growth Catalysts
- EMA IVDR Transition:Expanded clinical evidence requirements for companion diagnostic claims are forcing pharmaceutical sponsors to pre-qualify detection platforms earlier in drug development pipelines, locking in multi-year instrument procurement contracts.
- Liquid Biopsy Standardization:Payer coverage policies for circulating tumor DNA assays in the United States are creating dedicated reimbursement codes that reduce adoption friction for high-sensitivity detection systems in oncology clinics.
- Quantum Dot Enhancement:Plasmonic signal amplification methods are achieving femtomolar detection limits previously requiring mass spectrometry, opening mid-tier laboratory budgets to nanotechnology-enabled platforms.
Market Restraints
- Helium Supply Concentration:Mass spectrometry segments face input cost volatility as Qatar and the United States control over 75% of global helium refining capacity essential for cryogenic detector cooling systems.
- CLIA Personnel Shortage:The United States Bureau of Labor Statistics projects insufficient certified clinical laboratory scientists to operate high-complexity biomarker assays at projected diagnostic laboratory expansion rates.
- ISO 13485 Certification Burden:Small and mid-size manufacturers face 18-24 month quality management system implementation timelines that delay market entry in regulated jurisdictions.
Strategic Opportunities
- Decentralized Oncology Settings:Point-of-care portability requirements in Germany's regional hospital networks are creating demand for cartridge-based detection systems that bypass centralized laboratory logistics.
- Multi-Cancer Early Detection:Medicare Advantage plans in the United States are piloting coverage for methylation-based screening panels that require multiplexed protein and nucleic acid detection architectures.
- AI-Assisted Image Analysis:Convergence of automated liquid handling with machine learning classification algorithms is reducing false-positive rates in immunohistochemistry workflows, enabling laboratory staff reallocation to complex case review.
Industry Challenges
- LIMS Integration Complexity:Biomarker detection platforms must interface with legacy laboratory information management systems that lack standardized data exchange protocols, extending deployment timelines by 4-6 months.
- Cross-Reactivity Validation:Antibody-based detection systems require extensive specificity testing against heterophile antibodies and rheumatoid factor interference that consumes 30-40% of assay development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomarker Detection Systems Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Lateral Flow Assays, Microarrays, Mass Spectrometry Technology: Fluorescence, Electrochemistry, PCR, Nanotechnology Application: Oncology, Neurology, Cardiology, Infectious Diseases End User: Diagnostic Laboratories, Research Institutions, Hospitals, Pharmaceutical Companies |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., QIAGEN, Abbott, Merck KGaA, Bio-Rad Laboratories, Inc., Siemens Healthineers AG, PerkinElmer Incorporated, Illumina, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomarker Detection Systems Market Evolving Landscape
Detection platform architectures are fragmenting between centralized high-throughput installations and distributed point-of-care nodes, with software-defined workflow automation emerging as the critical differentiator across both deployment models.
Digital PCR technology is bifurcating the quantitative nucleic acid detection landscape. Absolute copy number enumeration without reference standards is displacing relative quantification methods in minimal residual disease monitoring. Academic medical centers in the United States and Germany are adopting dual-platform strategies that preserve real-time PCR for infectious disease panels while deploying digital PCR for oncology companion diagnostic validation.
EMA's In Vitro Diagnostic Regulation transition is compressing the competitive set for companion diagnostic claims. Manufacturers must now generate prospective clinical evidence rather than analytical bridging studies to support therapy-guiding indications. This regulatory friction is accelerating consolidation among instrument vendors capable of funding multi-site clinical trials across France, Germany, and Italy.
Hospital procurement committees are unbundling instrument hardware from reagent supply agreements that previously locked laboratories into single-vendor ecosystems. China's tertiary hospital procurement centers are piloting open-architecture tenders that separate capital equipment acquisition from consumable sourcing, forcing detection system manufacturers to compete on standalone platform performance metrics rather than bundled pricing leverage.
Biomarker Detection Systems Market Segmentation
Biomarker detection systems fragment across four distinct classification schemes, each revealing different competitive dynamics. Product type segmentation exposes capital intensity gradients, while technology categories illuminate sensitivity-performance tradeoffs that shape procurement decisions.
Product Type:
Substitution pressure intensifies as nanotechnology-enabled platforms encroach on mass spectrometry's historical dominance in ultra-low detection applications.
- ELISA Kits:Enzyme-linked immunosorbent assays leverage antibody-antigen binding with colorimetric or chemiluminescent readout for protein quantification. Diagnostic laboratories in the United States deploy these for high-throughput infectious disease screening where regulatory familiarity reduces validation burdens.
- Mass Spectrometry:These systems separate ionized analytes by mass-to-charge ratio, achieving parts-per-billion sensitivity for metabolite and protein identification. Germany's academic medical centers concentrate demand for clinical-grade installations, though helium supply volatility constrains expansion timelines.
- Lateral Flow Assays:Paper-based chromatographic devices deliver qualitative results in under 20 minutes without instrumentation.
- Microarrays:High-density spotted substrates enable simultaneous measurement of thousands of biomolecules.
ELISA kits retain volume leadership; mass spectrometry holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium fluorescence systems from emerging electrochemical alternatives in decentralized settings.
- PCR:Polymerase chain reaction amplifies nucleic acid targets through thermal cycling, with quantitative variants enabling viral load monitoring. China's tertiary hospitals drive volume deployment for respiratory pathogen panels as infectious disease surveillance infrastructure expands.
- Nanotechnology:Quantum dot and plasmonic enhancement methods achieve femtomolar detection limits through signal amplification architectures. Research institutions in the United States and Germany pilot these platforms for multi-cancer early detection assays requiring single-molecule sensitivity.
- Fluorescence:Excitation-emission detection pairs with confocal optics for cellular imaging and bead-based assays.
- Electrochemistry:Amperometric and potentiometric sensors enable label-free detection with minimal power requirements.
PCR dominates current installed base; nanotechnology is expanding most quickly.
Application:
Customer type concentration varies sharply, with pharmaceutical sponsors driving precision medicine segments while public health systems anchor infectious disease demand.
- Oncology:Companion diagnostic validation and minimal residual disease monitoring require multiplexed protein and nucleic acid detection. FDA and EMA mandates for therapy-guiding assays lock pharmaceutical companies into multi-year platform procurement contracts.
- Infectious Diseases:Syndromic panels for respiratory, bloodstream, and sexually transmitted pathogens demand rapid turnaround. Diagnostic laboratories in the United States prioritize these assays for CLIA high-complexity certification maintenance.
- Neurology:Cerebrospinal fluid biomarkers for neurodegenerative disease progression tracking face reimbursement uncertainty.
- Cardiology:Troponin and natriuretic peptide quantification supports acute coronary syndrome triage.
Oncology commands premium pricing; infectious diseases retain procedure volume leadership.
End User:
Geography shapes procurement authority, with centralized laboratory networks in Germany contrasting hospital-based purchasing in the United States.
- Diagnostic Laboratories:CLIA-certified facilities operate high-complexity biomarker assays under stringent personnel and quality requirements. The United States Bureau of Labor Statistics projects insufficient certified clinical laboratory scientists to match projected expansion rates.
- Pharmaceutical Companies:Drug developers integrate biomarker detection into clinical trial workflows for patient stratification and efficacy monitoring. EMA IVDR transition demands expanded clinical evidence generation, favoring vendors with multi-site trial capabilities across France, Germany, and Italy.
- Research Institutions:Academic medical centers pilot novel detection modalities before clinical translation.
- Hospitals:Point-of-care deployment in emergency and oncology departments prioritizes turnaround time over sensitivity.
Diagnostic laboratories anchor installed base; pharmaceutical companies drive fastest-growing procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mass spectrometry systems command 40% pricing premiums in Germany over comparable installations in China, reflecting divergent regulatory qualification burdens and helium supply security. This asymmetry concentrates profit pool capture among vendors with multi-site service infrastructure across high-margin jurisdictions.
United States
FDA companion diagnostic mandates and Medicare Advantage pilot programs for liquid biopsy coverage drive procurement of high-sensitivity detection platforms. CLIA laboratory certification requirements constrain market entry to vendors with established quality management systems. The Boston-Cambridge corridor anchors pharmaceutical-sponsored clinical trial demand, while Texas Medical Center laboratories expand infectious disease panel throughput.
Germany
EMA IVDR transition demands prospective clinical evidence generation for therapy-guiding assay claims, favoring instrument vendors with multi-site trial capabilities. Regional hospital networks in Bavaria and North Rhine-Westphalia pilot decentralized oncology point-of-care deployments. Heidelberg and Munich academic medical centers concentrate mass spectrometry demand for metabolite identification workflows.
China
NMPA regulatory harmonization with international standards accelerates import substitution for molecular diagnostic platforms. Tertiary hospital procurement centers in Shanghai and Beijing pilot open-architecture tenders separating capital equipment from consumable sourcing. The Yangtze River Delta region drives volume deployment for respiratory pathogen syndromic panels.
Japan
PMDA streamlined approval pathways for companion diagnostics reduce instrument qualification timelines for pharmaceutical co-development partnerships. METI funding for precision medicine infrastructure expands academic medical center detection platform installations. The Kansai region around Osaka concentrates diagnostic manufacturer headquarters and regional service operations.
United Kingdom
NHS England coverage determinations for multi-cancer early detection tests shape demand for multiplexed protein and nucleic acid detection architectures. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment requirements for EU-exporting manufacturers. The Cambridge-London corridor sustains research institution pilot adoption of quantum dot enhancement platforms.
Biomarker Detection Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium positioning depends on regulatory qualification depth rather than manufacturing scale alone. The market consolidates around three strategic archetypes: diversified life science conglomerates with full workflow integration, specialized molecular diagnostics pure-plays, and emerging nanotechnology platform developers. Competitive dynamics center on multi-year pharmaceutical procurement contract capture and geographic expansion of service infrastructure.
Among diversified instrument manufacturers, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific Inc. occupy positions spanning reagent supply through automated detection platforms. QIAGEN exemplifies the specialized archetype with concentrated focus on sample-to-answer molecular workflows. These three entities anchor the competitive set referenced in this analysis, representing distinct strategic approaches to biomarker detection market participation without implying specific comparative performance claims.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| Abbott |
| Merck KGaA |
| Bio-Rad Laboratories, Inc. |
| Siemens Healthineers AG |
| PerkinElmer Incorporated |
| Illumina, Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day instrument qualification timelines at FDA and EMA concentrate procurement authority among vendors with pre-validated manufacturing footprints, compressing price competition for configured-to-order mass spectrometry platforms while expanding margin capture for standardized PCR-based systems. This lead-time asymmetry binds pricing power to helium supply security and multi-site service infrastructure, rewarding incumbents with backward integration into cryogenic cooling components.
Pricing Analysis
Configured-to-order mass spectrometry platforms command 35-50% premiums over standardized PCR instruments, with price differentiation resting on ISO 13485 certification tier and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels segments the installed base: academic medical centers absorb premium positioning for metabolite identification workflows, while diagnostic laboratories in the United States prioritize economy-tier infectious disease panels to maintain CLIA compliance margins. Cost compression in mid-tier fluorescence systems is intensifying because nanotechnology-enabled platforms achieve comparable sensitivity at reduced capital intensity. Pharmaceutical companies exhibit lowest price sensitivity due to multi-year companion diagnostic procurement mandates, whereas China's tertiary hospital procurement centers drive hardest bargain through open-architecture tenders separating capital equipment from consumable sourcing.
Supply Chain Analysis
Strategic helium stockpiling dominates inventory strategy for mass spectrometry segments, with Qatar and the United States anchoring 75% of global refining capacity essential for cryogenic detector cooling systems. Manufacturing concentration spans Germany for precision optical components, China for PCR thermal cycling hardware, and the United States for fluorescence detection modules. Raw material dependencies include rare earth elements for quantum dot synthesis, specialized optical glass for confocal systems, and high-purity solvents for sample preparation. Single-source vulnerability concentrates in cryogenic cooling supply, where geopolitical disruption would cascade through clinical-grade instrument availability. Distribution runs through authorized service organizations with regional calibration capabilities, extending deployment timelines by 4-6 months for customized installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among China's tertiary hospital procurement centers and Germany's regional hospital networks, with open-architecture tenders fragmenting vendor lock-in and compressing bundled pricing leverage across the installed base.
For Market Incumbents: Shield installed-base loyalty through backward integration into helium recovery systems and captive supply of cryogenic cooling components, neutralizing Qatar supply concentration risk that threatens mass spectrometry margins. Deepen ISO 13485 certification depth across multi-site manufacturing to preempt EMA IVDR clinical evidence requirements that favor vendors with prospective trial capabilities in France, Germany, and Italy.
For New Entrants and Emerging Players: Anchor in Germany's decentralized oncology point-of-care deployments, where cartridge-based detection systems bypass centralized laboratory logistics and regional hospital networks prioritize turnaround time over brand heritage. Target AI-assisted image analysis convergence with automated liquid handling, where machine learning classification algorithms reduce false-positive rates in immunohistochemistry workflows and enable laboratory staff reallocation to complex case review.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-qualification moat play because EMA IVDR transition and FDA companion diagnostic mandates are compressing the competitive set for therapy-guiding assay claims, favoring instrument vendors capable of funding multi-site clinical trials. Target acquisition candidates with nanotechnology platform development capabilities and existing pharmaceutical co-development partnerships. Monitor Medicare Advantage liquid biopsy coverage determinations as inflection indicator for high-sensitivity detection system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Site Clinical Trial Capability | EMA IVDR mandates prospective evidence generation across France, Germany, and Italy for companion diagnostic claims. |
| Helium Supply Security Investment | Cryogenic cooling dependencies in Qatar and the United States create input cost volatility for mass spectrometry segments. |
| AI-Assisted Workflow Integration | Machine learning classification algorithms reduce false-positive rates in immunohistochemistry workflows at academic medical centers. |
| Open-Architecture Platform Development | China's tertiary hospital procurement centers separate capital equipment from consumable sourcing in tender structures. |
| Point-of-Care Cartridge Miniaturization | Germany's regional hospital networks prioritize decentralized oncology deployments bypassing centralized laboratory logistics. |
Research Methodology
A spread of perspectives from clinical laboratory directors, pharmaceutical regulatory affairs leads, hospital procurement committee members, and companion diagnostic platform engineers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) and PMA filing databases, EMA IVDR submission records, ClinicalTrials.gov protocol registrations, and CMS Medicare coverage determination documents. Bottom-up triangulation across instrument shipment data and top-down reconciliation with pharmaceutical R&D expenditure patterns anchored volume and value estimates.
Segmentation dimensions modeled include product type, technology category, application area, and end-user archetype across the projection horizon. CAGRs were derived from growth driver elasticity analysis applied to baseline installed base penetration rates. Industry-specific forecast inputs incorporate CLIA personnel shortage projections from the United States Bureau of Labor Statistics and helium supply concentration metrics from Qatar and United States refining capacity disclosures.
Underlying assumptions cover regulatory pathway stability at FDA and EMA, with deviation risk concentrated in payer coverage policy reversals for liquid biopsy and multi-cancer early detection tests. Revision becomes warranted when Medicare Advantage pilot program enrollment crosses thresholds that trigger national coverage determination proceedings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
Antibody Library Technology Market
Biomedical Technology
Global Bifida Ferment Lysate Market
Biomedical Technology
Global Cell Sorting Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market
Biomedical Technology
Drug Delivery Technology Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
Global Glycomics/Glycobiology Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Polymerase Chain Reaction Technologies Market
Biomedical Technology
E2 Antibody Market