
 Global Oncology Based in-Vivo CRO Market | 2026-2036
Global Oncology Based in-Vivo CRO Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oncology Based in-Vivo CRO Market Foresight
Market Context with Strategic Players
Biotech firms are consolidating their preclinical outsourcing budgets toward full-service in-vivo oncology CROs capable of running GLP toxicology and pharmacokinetics under one contract. Charles River Laboratories dominates North American capacity for patient-derived xenograft studies through its Wilmington, Massachusetts operations. WuXi AppTec leverages its Suzhou campus to anchor Asia-Pacific demand for genetically engineered mouse models. Eurofins Scientific differentiates its portfolio with integrated biomarker evaluation services spanning histopathology and flow cytometry.
Technical Definition and Structural Segments
Oncology based in-vivo CRO denotes contract research organizations that conduct live-animal studies using immunocompromised rodents, syngeneic models, or humanized mice to evaluate anti-cancer compound efficacy, toxicity, and pharmacokinetic profiles prior to human trials. Tumor xenograft models occupy the largest revenue share within service type segmentation due to their established reproducibility in immuno-oncology screening. CRISPR gene editing represents the fastest-expanding technology segment as sponsors demand precisely modified oncogene knock-in models for targeted therapy validation. Pharmacokinetics studies command premium pricing relative to standard efficacy assessments because they require specialized bioanalytical infrastructure and regulatory-grade documentation.
Regulatory Frame and Forward-Looking Close
FDA's GLP regulations and EMA's MDR-aligned preclinical data standards enforce rigorous documentation of in-vivo study protocols, directly shaping CRO investment in quality management systems and audit trails. China's NMPA now mandates domestic replication of pivotal xenograft data for novel oncology IND submissions, redirecting sponsor spending toward China-based GLP facilities. Stakeholders must monitor how evolving FDA guidance on humanized mouse model qualification reshapes competitive positioning between established Western CROs and emerging Asia-Pacific operators.
Market Dynamics
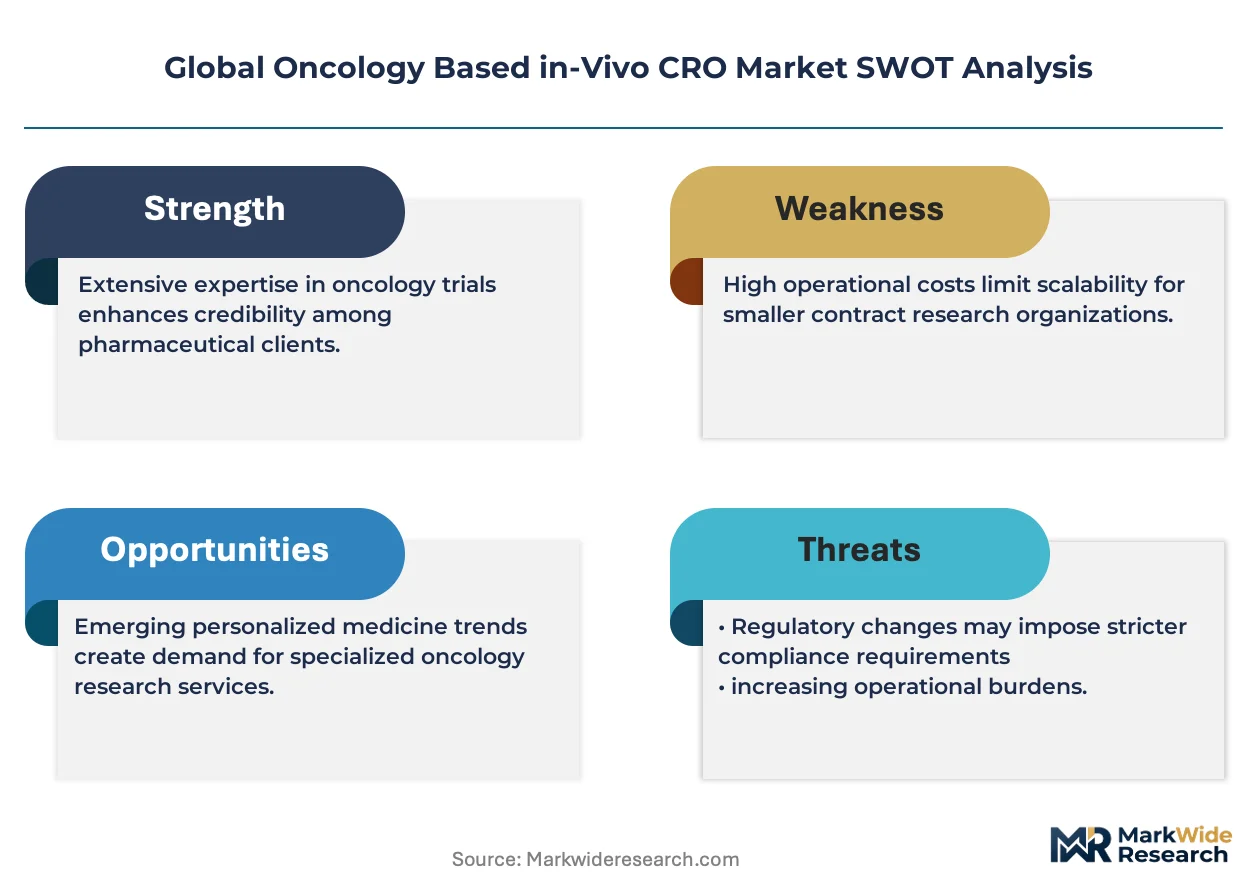
CRISPR gene editing is compressing study timelines by enabling precise oncogene knock-in models, forcing CROs to restructure their technical capabilities and pricing models around genetically engineered mouse production.
Growth Catalysts
- FDA Animal Rule Pathway:Biodefense and oncology sponsors leverage this regulatory route to advance novel therapeutics without traditional human efficacy trials, expanding demand for GLP-compliant primate and rodent oncology studies.
- Immuno-oncology pipeline expansion:Biotech firms require humanized mouse models for checkpoint inhibitor validation, pulling capacity investments toward specialized immune system engraftment facilities.
- China NMPA domestic replication mandate:Novel oncology IND submissions must now include China-generated xenograft data, redirecting sponsor budgets toward Suzhou and Shanghai GLP campuses.
Market Restraints
- Transgenic mouse supply concentration:Foundational genetically engineered models originate from concentrated US and European academic repositories, creating licensing bottlenecks and royalty stacking for CROs.
- GLP facility capex intensity:Specialized barrier housing, HVAC redundancy, and audit trail systems require capital deployment that excludes mid-tier operators from premium pharmacokinetics contracts.
- EMA MDR-aligned documentation standards:Enhanced traceability requirements for in-vivo study protocols extend validation timelines and compress project margins for non-integrated CROs.
Strategic Opportunities
- Germany GLP campus expansion:Underpenetrated central European demand for patient-derived xenograft services creates white space for facilities offering integrated histopathology and flow cytometry.
- Organoid-xenograft hybrid models:Convergence of 3D tumor organoid culture with in-vivo implantation protocols enables higher-throughput immuno-oncology screening at reduced animal usage.
- Digital pathology integration:AI-augmented histopathological readout platforms allow CROs to unbundle biomarker evaluation services and capture recurring revenue from biotech sponsors.
Industry Challenges
- CRISPR specialist talent scarcity:Gene editing model development requires PhD-level expertise in embryonic stem cell manipulation that outpaces academic training pipeline output.
- Multi-site GLP audit coordination:Sponsors running parallel US, China, and Germany studies face fragmented quality management system reconciliation across divergent national inspectorate expectations.
- Humanized mouse engraftment variability:Immune cell donor heterogeneity introduces data reproducibility risks that complicate regulatory submission packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oncology Based in-Vivo CRO Market |
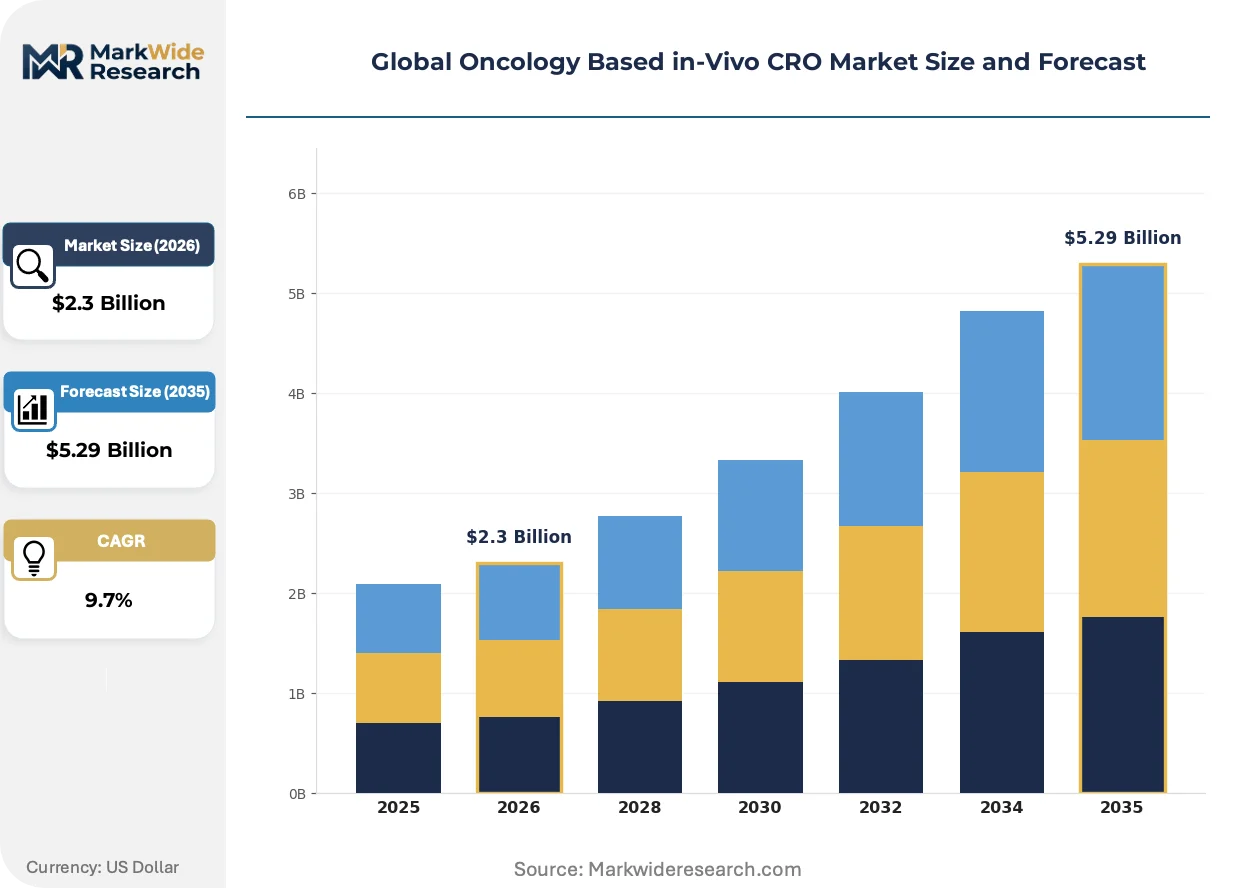
| Market Size in 2026 | $2.3 Billion |
| Market Size in 2035 | $5.29 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Tumor Xenograft Models, Genetically Engineered Models, Pharmacokinetics Studies, Toxicology Analysis, Biomarker Evaluation Therapy Area: Breast Cancer, Lung Carcinoma, Leukemia, Melanoma, Colorectal Adenocarcinoma End User: Pharmaceutical Companies, Biotech Firms, Academic Institutions, Research Organizations, Contract Research Organizations Technology: 3D Cell Culture, CRISPR Gene Editing, Imaging Technologies, Flow Cytometry, Histopathology |
| Companies Covered | Charles River Laboratories, Crown Bioscience, ICON plc, Taconic Biosciences, Eurofins Scientific, Thermo Fisher Scientific, WuXi AppTec, Evotec SE, The Jackson Laboratory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oncology Based in-Vivo CRO Market Shifts & Advancements
Live-animal oncology research is pivoting from standardized cell line xenografts toward patient-derived and genetically complex models, compressing traditional service boundaries between efficacy, toxicology, and biomarker evaluation.
CRISPR-Cas9 precision editing is overtaking conventional transgenic breeding for oncogene model generation. Biotech sponsors now demand knock-in timelines measured in months rather than years. This velocity is compressing competitive differentiation around speed-to-study initiation rather than historical model portfolio breadth.
EMA's MDR-aligned preclinical data standards now mandate enhanced chain-of-custody documentation for in-vivo specimens. CROs must deploy specimen tracking systems that interface with sponsor quality management databases. European oncology sponsors are responding by consolidating contracts with full-service providers possessing integrated informatics platforms.
Biotech procurement teams are unbundling histopathology and bioanalytical services from core efficacy study contracts. Specialized regional laboratories now capture peripheral pharmacokinetics and biomarker work that CROs previously retained. This fragmentation is most visible among mid-cap US sponsors seeking cost transparency through competitive bidding of study components.
Global Oncology Based in-Vivo CRO Market Segmentation
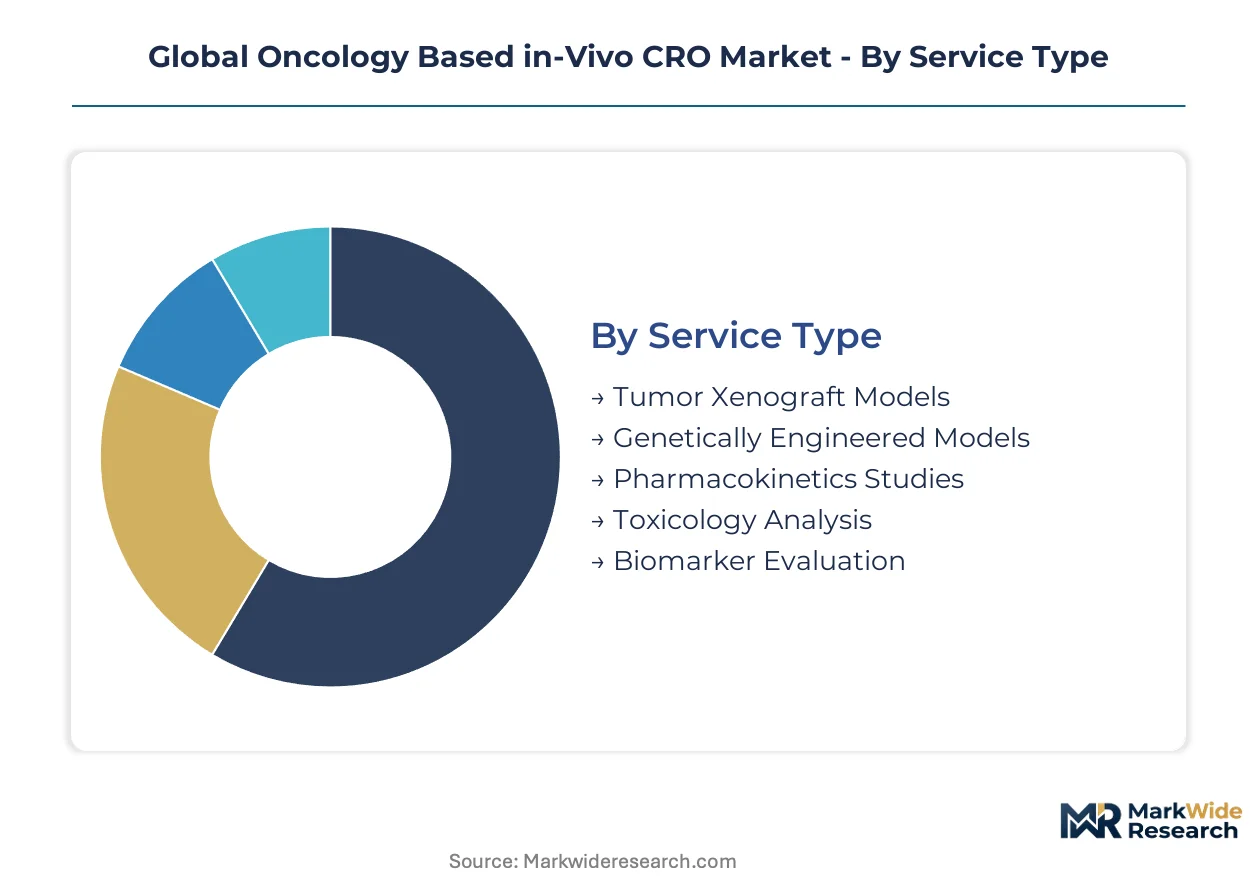
Preclinical outsourcing decisions in oncology CRO services hinge on matching model complexity with regulatory submission requirements. Sponsors segment their procurement across service capabilities, therapeutic targets, and technical platforms to optimize study validity and timeline compression.
Service Type:
Procurement teams prioritize service bundles that consolidate efficacy, toxicology, and pharmacokinetics under unified quality management systems.
- Tumor Xenograft Models:Immunocompromised rodent implantation with human cancer cell lines remains the workhorse for immuno-oncology screening. Demand clusters in the United States and China where GLP-certified barrier facilities support FDA and NMPA submission packages. Charles River Laboratories and WuXi AppTec anchor capacity in these geographies.
- Genetically Engineered Models:CRISPR-edited oncogene knock-in mice enable precise target validation for personalized therapeutics. Sponsors in Germany and Massachusetts drive specification requirements as their pipelines concentrate on rare oncogenic drivers. Licensing constraints from concentrated academic repositories create supply bottlenecks.
- Pharmacokinetics Studies:Specialized bioanalytical infrastructure with LC-MS/MS capabilities commands premium contract values.
- Toxicology Analysis:GLP-compliant rodent and primate safety assessment supports FDA Animal Rule pathway submissions.
- Biomarker Evaluation:Integrated histopathology and flow cytometry services capture recurring revenue from longitudinal study designs.
Tumor xenograft models lead on scale; genetically engineered models lead on momentum.
Therapy Area:
Pipeline concentration in specific malignancies redirects CRO capacity investments toward disease-relevant model repositories.
- Breast Cancer:Patient-derived xenograft banks with hormone receptor stratification support endocrine therapy development. Sponsors in Massachusetts and California dominate protocol submissions.
- Lung Carcinoma:Genetically defined subtypes with EGFR, ALK, and KRAS mutations require specialized knock-in model production. Demand from Shanghai and Suzhou biotech clusters is climbing the fastest.
- Leukemia:Humanized mouse engraftment with patient hematopoietic cells enables chimeric antigen receptor validation.
- Melanoma:Syngeneic models with intact immune systems support checkpoint inhibitor combination studies.
- Colorectal Adenocarcinoma:Microsatellite instability stratification drives mismatch repair deficient model procurement.
Lung carcinoma commands the steepest expansion trajectory; breast cancer maintains the deepest installed base.
End User:
Customer scale determines contract structure, with large pharma seeking integrated partnerships and emerging biotech favoring modular procurement.
- Pharmaceutical Companies:Multi-year master service agreements with dedicated capacity allocations dominate big pharma procurement. These sponsors in New Jersey, Basel, and Tokyo prioritize audit-ready documentation systems.
- Biotech Firms:Milestone-driven contracts with flexible scope modification support venture-backed development timelines. Cambridge, Massachusetts and South San Francisco clusters generate the densest request-for-proposal activity.
- Academic Institutions:Grant-funded exploratory studies with publication requirements drive demand for novel model characterization.
- Research Organizations:Non-profit consortia coordinate multi-site validation of preclinical biomarkers.
- Contract Research Organizations:Subcontracting relationships for specialized capabilities extend service portfolios without capital deployment.
Pharmaceutical companies anchor contract value; biotech firms drive volume growth.
Technology:
Platform selection determines study throughput, data granularity, and regulatory defensibility across the preclinical workflow.
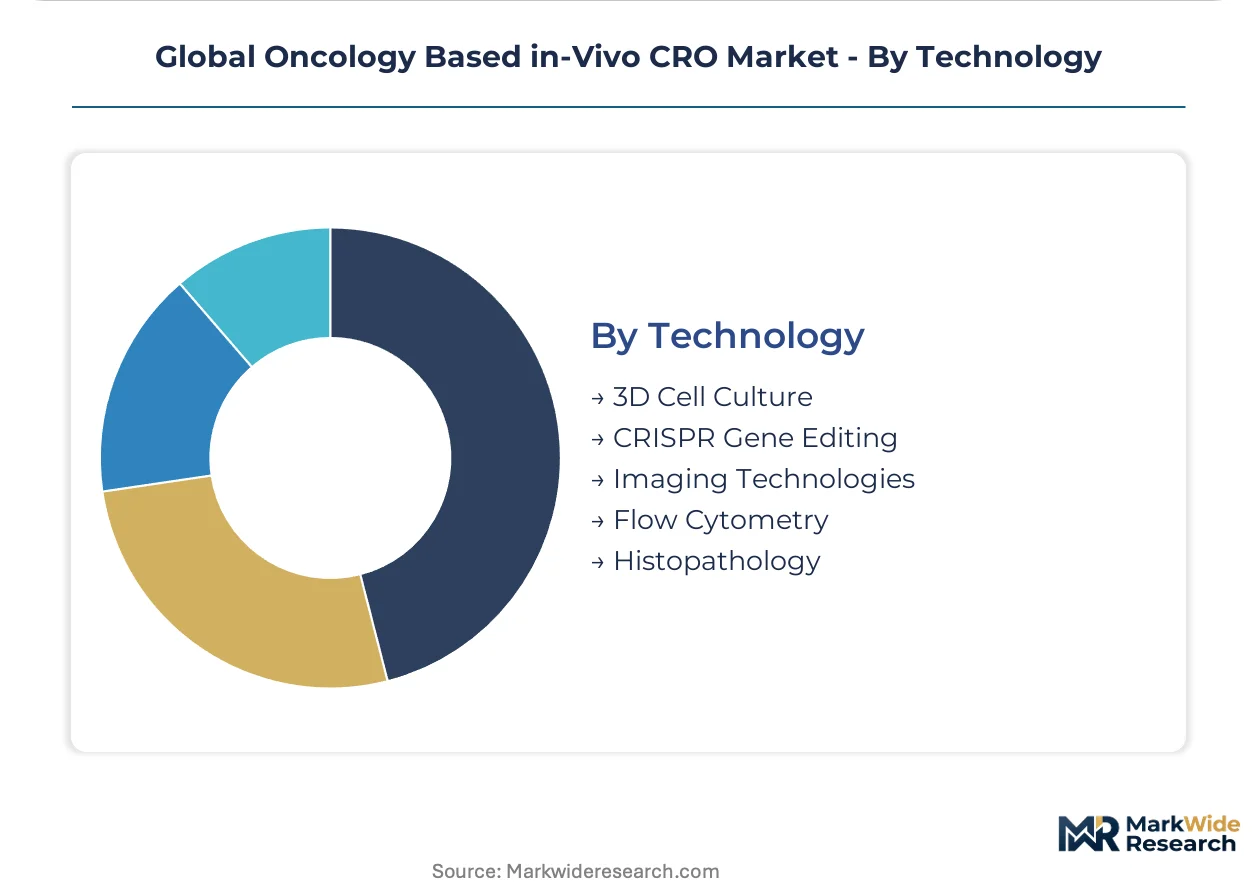
- CRISPR Gene Editing:Precision oncogene modification compresses model development from years to months. Talent scarcity in embryonic stem cell manipulation constrains capacity expansion in Boston and San Diego hubs.
- Imaging Technologies:Bioluminescence and MRI modalities enable longitudinal tumor monitoring without terminal sacrifice. Integration demand from German sponsors is gaining share fastest.
- 3D Cell Culture:Organoid-xenograft hybrid protocols reduce animal usage while preserving microenvironment complexity.
- Flow Cytometry:Multi-parameter immune profiling supports humanized mouse model qualification.
- Histopathology:Digital pathology platforms with AI-augmented readout enable unbundled biomarker service delivery.
CRISPR gene editing leads on technical disruption; imaging technologies lead on adoption velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting sponsor budgets toward jurisdictions where GLP compliance costs diverge most sharply from study throughput potential. CROs now optimize facility placement across the cost-of-compliance gradient separating established Western markets from rapidly certifying Asia-Pacific hubs.
United States
FDA's Animal Rule pathway and IND-enabling study demand concentrate preclinical investment in Massachusetts and California biotech corridors. Charles River Laboratories anchors North American patient-derived xenograft capacity through its Wilmington operations. The agency's humanized mouse model qualification guidance is reshaping facility investment priorities across the Boston-Cambridge cluster.
China
NMPA's domestic replication mandate for novel oncology IND submissions is redirecting multinational sponsor spending toward Suzhou and Shanghai GLP campuses. WuXi AppTec leverages its Suzhou infrastructure to capture this regulatory-driven demand shift. Government funding for biomedical research parks in the Yangtze River Delta is accelerating certification timelines for new barrier facilities.
Germany
EMA's MDR-aligned preclinical documentation standards and underpenetrated central European demand for integrated histopathology services create expansion white space. Eurofins Scientific positions its portfolio around biomarker evaluation capabilities spanning flow cytometry and digital pathology. The Munich and Heidelberg life science clusters are driving specification requirements for rare oncogenic driver models.
United Kingdom
Post-Brexit divergence from EU GLP mutual recognition agreements is forcing sponsors to duplicate study documentation for parallel EMA and MHRA submissions. London and Cambridge research consortia maintain dense request-for-proposal activity despite regulatory friction. Academic repository licensing for transgenic models remains concentrated in Oxford and Edinburgh institutional networks.
Japan
PMDA's streamlined oncology IND review track and aging research infrastructure are pulling sponsor studies toward newer Asia-Pacific facilities. Tokyo and Osaka pharmaceutical headquarters maintain multi-year master service agreements with integrated global CROs. Government initiatives for regenerative medicine and cell therapy are expanding demand for humanized immune system models.
Global Oncology Based in-Vivo CRO Market Competitive Landscape
Capacity expansion dominates the current landscape as established operators defend positioning through GLP-certified facility buildouts. The vendor base stratifies across three tiers: full-service global networks with integrated toxicology and pharmacokinetics, regional specialists concentrating on genetically engineered model production, and niche biomarker evaluation laboratories. Strategic archetypes include the portfolio consolidator bundling efficacy and safety services, the technology licensor monetizing proprietary CRISPR editing platforms, and the geography-focused operator capturing regulatory-mandated domestic replication contracts. M&A activity and strategic partnerships represent the dominant competitive vectors as mid-tier operators seek scale to qualify for premium pharmacokinetics contracts.
Within the full-service network tier, Charles River Laboratories, WuXi AppTec, and Eurofins Scientific exemplify divergent geographic anchoring strategies. Charles River Laboratories represents the North American incumbent leveraging decades of GLP infrastructure investment. WuXi AppTec occupies a position as the Asia-Pacific gateway for regulatory-mandated China study replication. Eurofins Scientific anchors European demand through integrated biomarker capabilities that unbundle into recurring revenue streams.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Crown Bioscience |
| ICON plc |
| Taconic Biosciences |
| Eurofins Scientific |
| Thermo Fisher Scientific |
| WuXi AppTec |
| Evotec SE |
| The Jackson Laboratory |
| Others |
Supply & Pricing Matrix
Big pharma procurement teams in New Jersey, Basel, and Tokyo concentrate contract value through multi-year master service agreements, anchoring a project-based pricing model where pharmacokinetics studies command premium contract values relative to standard efficacy assessments. This buyer concentration compresses margin flexibility for mid-tier operators lacking GLP-certified barrier facilities.
Pricing Analysis
Direct-to-sponsor contracting eliminates distributor markups for integrated full-service CROs, while subcontracting relationships introduce margin layering for specialized biomarker laboratories. Pricing stratifies across GLP certification tiers, with FDA and EMA audit-ready documentation commanding substantial premiums over exploratory non-GLP screening. Cost compression in standard xenograft services is intensifying because biotech sponsors unbundle peripheral pharmacokinetics and histopathology work for competitive bidding. Emerging biotech firms in Cambridge and South San Francisco exhibit highest price sensitivity, prioritizing milestone-driven contract flexibility over integrated service premiums.
Supply Chain Analysis
Direct-to-sponsor channels handle hyperscale demand from pharmaceutical headquarters, while regional subcontracting networks extend specialized capabilities without capital deployment. Genetically engineered mouse production concentrates in the United States, China, and Germany, with foundational transgenic models originating from concentrated academic repositories in Massachusetts and Oxford. CRISPR reagent supply, specialized barrier housing components, and LC-MS/MS bioanalytical instrumentation represent critical input dependencies. Single-source vulnerability in embryonic stem cell manipulation talent constrains capacity expansion across Boston and San Diego hubs. Distribution runs through integrated global networks for full-service contracts and fragmented regional laboratories for unbundled services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where NMPA's domestic replication mandate in China generates cost and timeline differentials against EMA's MDR-aligned documentation standards in Europe.
For Market Incumbents: Deepen GLP-certified capacity in Suzhou and Shanghai to capture regulatory-mandated China study replication demand before Western competitors localize. Expand integrated biomarker evaluation capabilities spanning digital pathology and flow cytometry to defend against unbundling pressure from specialized regional laboratories. Prioritize embryonic stem cell talent acquisition in Boston and San Diego to mitigate CRISPR specialist scarcity threatening model development timelines. For New Entrants and Emerging Players: The premium-to-economy pricing gap in pharmacokinetics services creates entry opportunity for laboratories offering non-GLP exploratory screening with rapid turnaround. Target underpenetrated central European demand for patient-derived xenograft services in Germany's Munich and Heidelberg clusters. Pursue organoid-xenograft hybrid model development as a differentiated go-to-market angle reducing animal usage while preserving microenvironment complexity. For Investors and Strategic Acquirers: Mid-cap pharmaceutical companies are the most active acquirer in this space, seeking to internalize preclinical capabilities and reduce CRO dependency. Long-term viability hinges on CRISPR platform ownership and informatics integration rather than commodity xenograft capacity. Monitor FDA guidance evolution on humanized mouse model qualification as the critical inflection signal reshaping competitive positioning between Western and Asia-Pacific operators.| Strategic Initiative | Industry Significance |
|---|---|
| GLP Campus Expansion in China | NMPA domestic replication mandate redirects sponsor budgets toward Suzhou and Shanghai facilities. |
| CRISPR Platform Licensing | Precision oncogene knock-in capabilities compress study timelines from years to months. |
| Digital Pathology Integration | AI-augmented histopathology enables unbundled biomarker services with recurring revenue capture. |
| Humanized Mouse Model Qualification | FDA guidance evolution reshapes facility investment priorities across immune system engraftment capabilities. |
| Organoid-Xenograft Hybrid Development | 3D tumor culture convergence reduces animal usage while preserving immuno-oncology screening validity. |
Research Methodology
Coverage spans the United States, China, Germany, the United Kingdom, and Japan, with primary inputs from each jurisdiction's regulatory cluster and biotech corridor. The research combines structured interviews with drug development executives, regulatory affairs leads, GLP facility directors, and biotech procurement managers with secondary validation against FDA filings, EMA submissions, NMPA IND databases, and ClinicalTrials.gov records. Bottom-up facility capacity modeling and top-down sponsor spending analysis were triangulated to derive market estimates.
Segmentation was modeled at the service type, therapy area, end user, and technology platform levels, with regional regulatory clusters as an additional cross-cutting dimension. CAGRs were derived through trend extrapolation of sponsor outsourcing ratios and capacity expansion pipelines across the analysis window. Forecast inputs incorporated GLP certification timelines, CRISPR model development velocity, and regulatory submission volume trends by geography.
Caveats apply where NMPA policy enforcement, FDA humanized mouse guidance finalization, or EMA MDR documentation standard revisions could materially shift the outlook. Forecasts reflect assumptions regarding sustained biotech funding levels and continued regulatory divergence between Western and Asia-Pacific jurisdictions. Periodic stress-testing of base assumptions against sponsor pipeline announcements and facility certification updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Europe Transfection Technologies Market
Biomedical Technology
Protein Expression Technology Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Inhalable Biologics Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Global Biocompatibility Testing Services Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Imaging Biomarkers Market
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Multiplex Biomarker Imaging Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market