
 Global Peptide Microarray Market | 2026-2036
Global Peptide Microarray Market Size, Share, and Industry Trends Forecast 2026-2036
Global Peptide Microarray Market Foresight
Specialized distributor networks serving life science instrumentation is reconfiguring as direct-to-laboratory digital procurement platforms gain share. Thermo Fisher Scientific leverages its integrated supply chain to control fulfillment timelines for high-density peptide arrays across North American research clusters. JPT Peptide Technologies specializes in custom synthesis workflows that anchor its position in European academic consortia. PEPperPRINT GmbH competes through proprietary SPOT synthesis platforms that extend its reach into vaccine development programs.
Peptide microarrays are solid-phase assay platforms comprising spatially organized peptide sequences immobilized on glass, membrane, or semiconductor substrates, typically spotted at densities exceeding ten thousand features per square centimeter for multiplexed binding analysis. Their primary commercial purpose is to enable high-throughput screening of protein interactions, epitope mapping, and antibody specificity profiling with minimal sample volumes. High-density arrays capture the largest revenue share due to their dominance in pharmaceutical screening pipelines where parallel analysis of thousands of peptide sequences compresses drug discovery timelines. Customized arrays represent the fastest-expanding category as biotechnology firms and contract research organizations demand project-specific peptide libraries tailored to proprietary target portfolios. Academic research end users sustain steady demand for low-density and targeted formats where budget constraints favor modular, lower-throughput configurations.
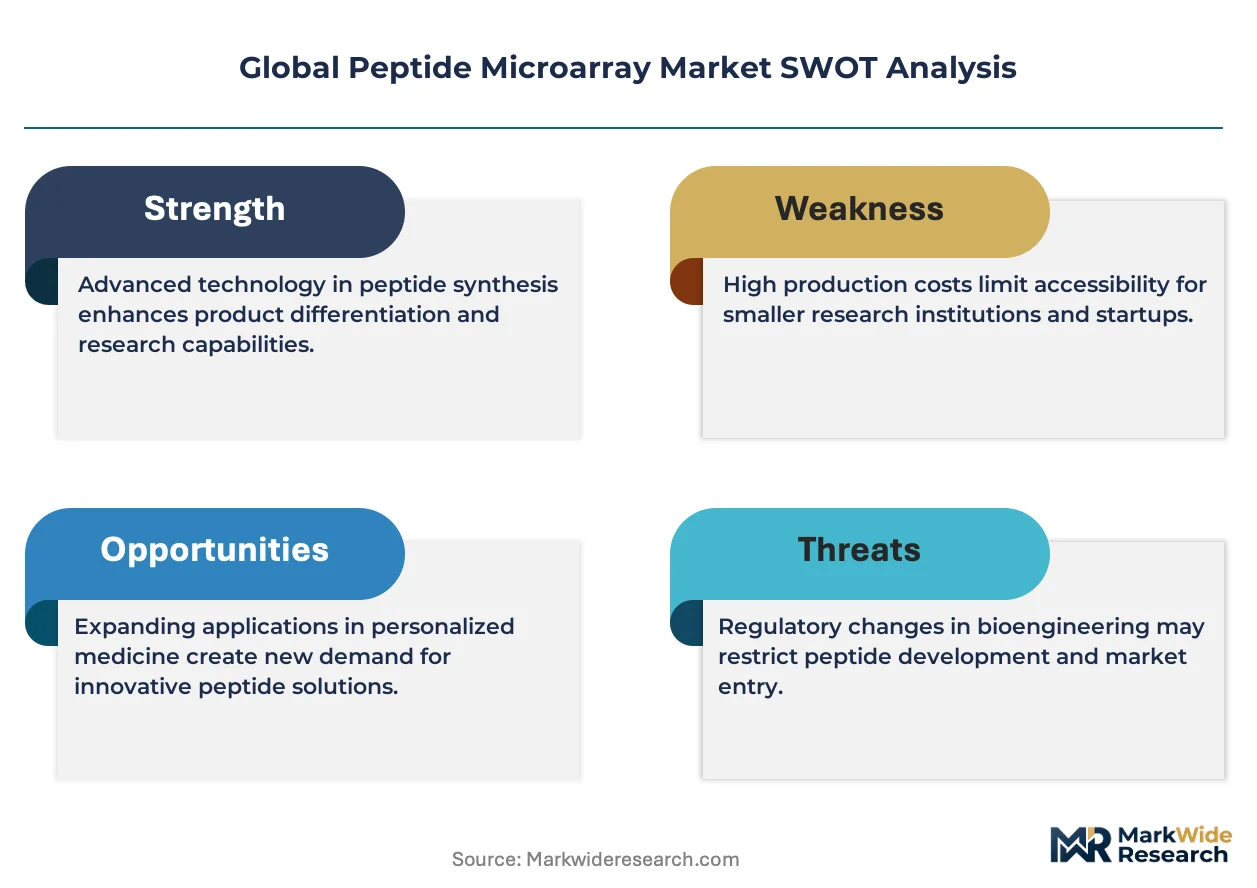
FDA guidance on in vitro diagnostic validation and the EU MDR framework for companion diagnostics are tightening analytical performance requirements for peptide microarrays used in clinical biomarker applications. REACH compliance and ECHA substance registration obligations shape material selection for European manufacturers, while ISO 13485 certification serves as a baseline quality threshold for suppliers targeting diagnostic laboratory customers. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on array-based assay qualification standards to anticipate compliance investments that could reshape competitive positioning in transatlantic procurement channels.
Market Dynamics
Precision medicine infrastructure investments are compressing validation timelines for peptide microarray platforms, forcing suppliers to reconfigure quality assurance workflows around FDA and EMA convergence on computational assay qualification standards.
Growth Catalysts
- EU AI Act compliance pathways:Diagnostic developers are embedding algorithmic transparency requirements into array-based biomarker pipelines, accelerating adoption of validated computational workflows in European clinical laboratories.
- Pharmaceutical screening densification:Contract research organizations are expanding high-density peptide array procurement to compress epitope mapping timelines for therapeutic antibody programs.
- Japan METI precision medicine clusters:Academic consortia in Kobe and Tsukuba are driving procurement of customized peptide libraries for infectious disease surveillance applications.
Market Restraints
- Fluorinated substrate cost volatility:Glass and semiconductor wafer input prices for high-density array manufacturing expose producers to energy-intensive supply chain disruptions.
- Single-source synthesis reagent dependence:European manufacturers face concentration risk in Fmoc-protected amino acid suppliers concentrated in German chemical clusters.
- Cross-reactivity technical ceiling:Peptide-protein binding specificity limitations constrain clinical diagnostic applications where false-positive rates trigger regulatory scrutiny.
Strategic Opportunities
- India CDSCO diagnostic pathway expansion:Streamlined approval frameworks for companion diagnostics create white space for array-based oncology biomarker platforms in Mumbai and Bangalore laboratory networks.
- CRISPR-peptide convergence:Gene-editing validation workflows are creating demand for peptide arrays that profile off-target binding interactions in cell therapy development.
- Direct-to-laboratory digital procurement:Specialized distributors are deploying e-commerce platforms that bypass traditional instrumentation vendor channels for consumable peptide libraries.
Industry Challenges
- ISO 13485 certification timeline compression:Diagnostic-targeted array manufacturers face 18-24 month quality system implementation cycles that delay market entry.
- Multiplex assay standardization gaps:Absence of harmonized reference materials across FDA and EMA jurisdictions complicates cross-border clinical validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Peptide Microarray Market |
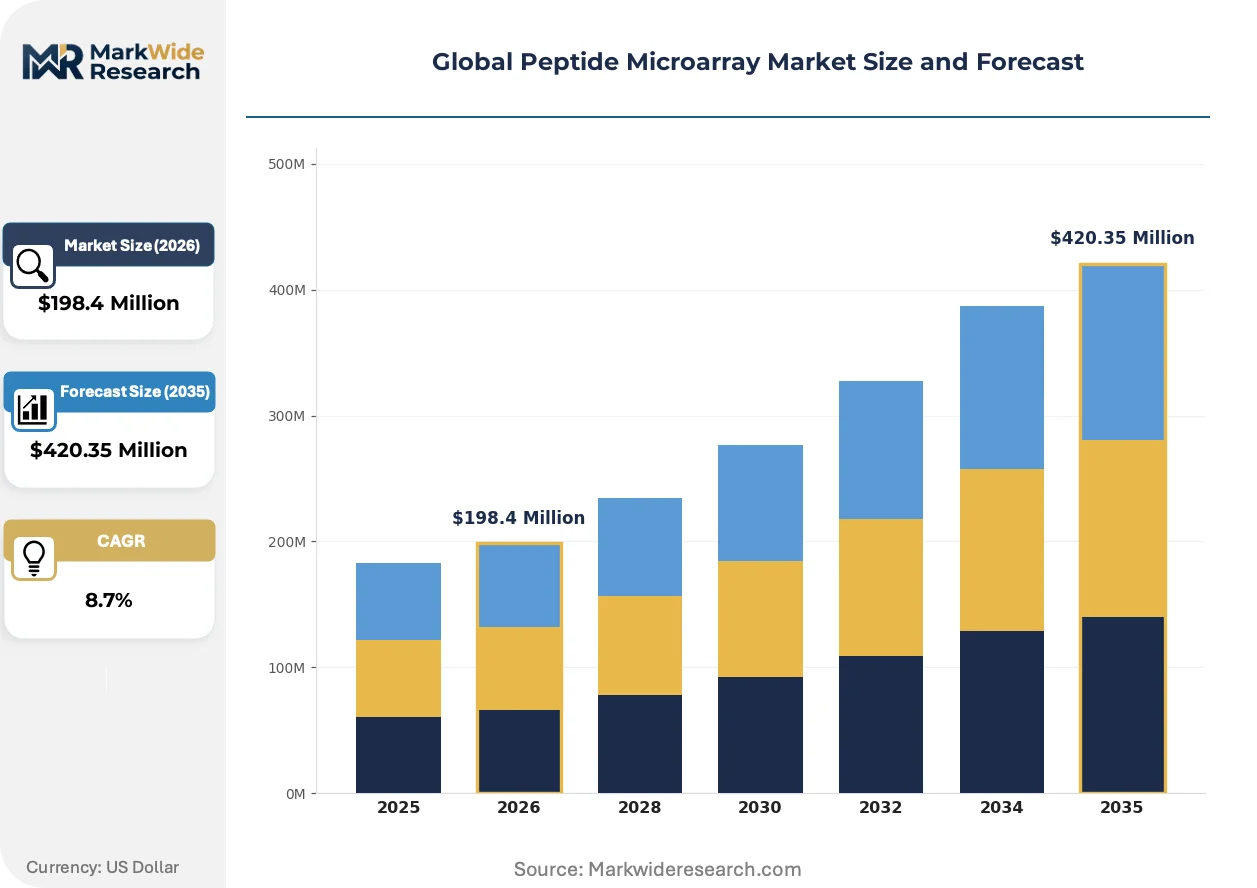
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $420.35 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Density, Low-Density, Customized Arrays, Multiplexed Arrays, Targeted Arrays Technology: SPOT Synthesis, Photolithography, Inkjet Printing, Laser Printing, Solid-Phase Peptide Synthesis Application: Drug Discovery, Biomarker Identification, Vaccine Development, Protein-Protein Interaction, Enzyme Profiling End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research, Contract Research Organizations, Diagnostic Laboratories |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Abbott Laboratories, JPT Peptide Technologies, PEPperPRINT GmbH, Bio-Rad Laboratories, Merck KGaA, RayBiotech, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Peptide Microarray Market Shifts & Advancements
Next-generation synthesis platforms and computational validation frameworks are restructuring competitive advantage in peptide microarray supply, compressing the gap between discovery-scale and clinical-grade production capabilities.
Photolithographic peptide synthesis is rendering obsolete traditional spot-synthesis methods for high-density applications. Pharmaceutical screening operations in Boston and Basel are adopting semiconductor-fabrication-derived patterning technologies that enable 100,000-feature arrays on single slides. This convergence is rendering obsolete the throughput limitations that previously separated academic research tools from industrial-scale screening platforms.
REACH substance registration obligations are forcing European manufacturers to requalify surface chemistries and linker molecules used in array substrates. ECHA compliance deadlines in 2025-2026 are accelerating substitution of legacy fluorinated compounds with bio-based alternatives in German and Dutch production facilities. Customized array suppliers targeting diagnostic customers are absorbing 12-18 month reformulation cycles to maintain CE marking eligibility.
Consolidated procurement by multi-site research consortia is displacing single-laboratory purchasing autonomy. National precision medicine initiatives in Germany, the United Kingdom, and Japan are centralizing peptide array procurement through framework agreements that favor suppliers with integrated synthesis-to-validation service capabilities. Academic medical centers in Heidelberg, Cambridge, and Osaka are migrating from transactional purchasing to multi-year supply contracts with embedded technical support provisions.
Global Peptide Microarray Market Segmentation
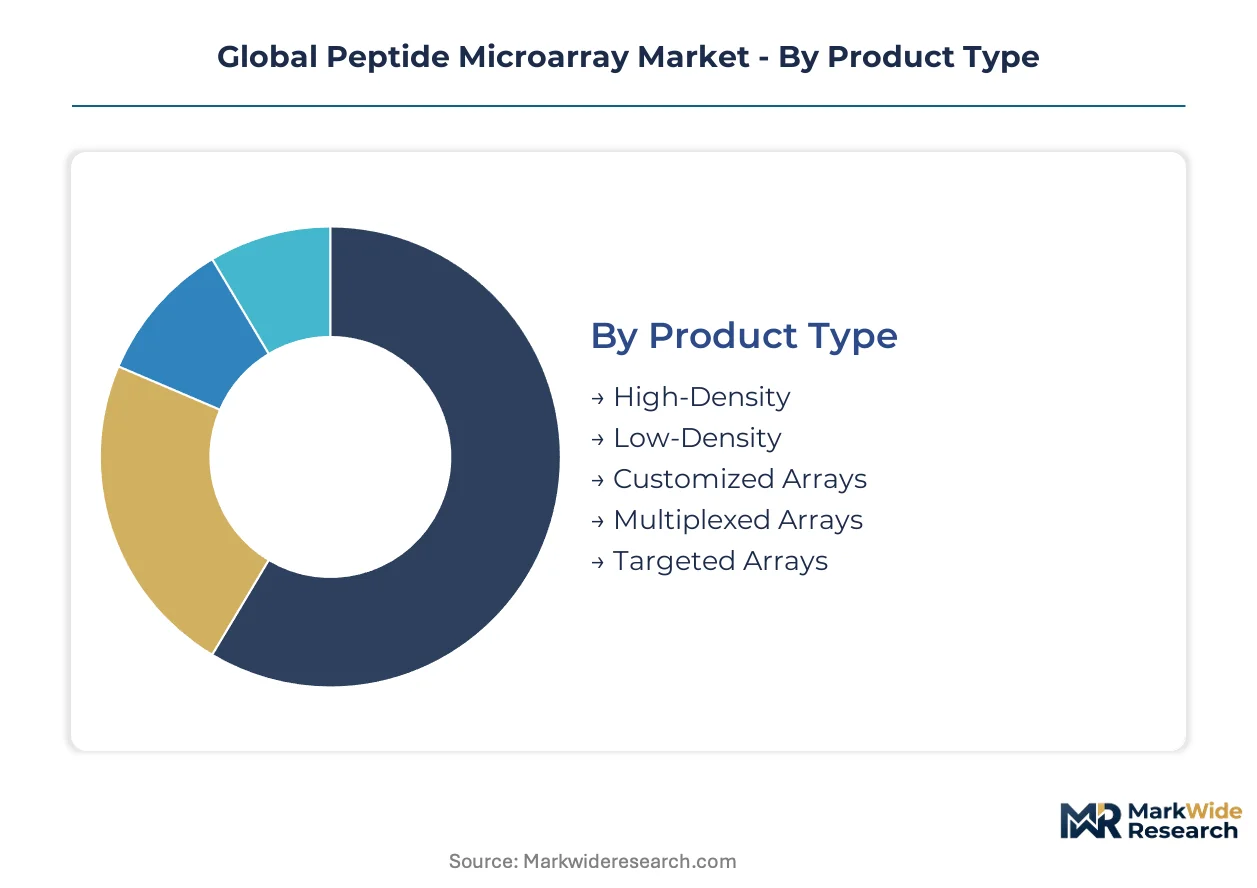
Peptide microarray segmentation reflects divergent procurement rhythms across product formats, synthesis technologies, and end-use applications. Cycle-time compression in pharmaceutical pipelines favors high-throughput configurations, while academic budgets sustain longer replacement intervals for modular systems.
Product Type:
High-density and customized arrays turn inventory fastest due to consumable replenishment cycles in pharmaceutical screening, whereas targeted formats sit longer in academic procurement queues.
- High-Density:Arrays exceeding ten thousand features per square centimeter enable parallel analysis of thousands of peptide sequences on single slides. Pharmaceutical screening operations in Boston and Basel compress epitope mapping timelines through semiconductor-fabrication-derived patterning. FDA guidance on in vitro diagnostic validation tightens analytical performance requirements for clinical biomarker applications.
- Customized Arrays:Project-specific peptide libraries tailored to proprietary target portfolios command premium positioning. Biotechnology firms and contract research organizations in Germany and Japan drive procurement for therapeutic antibody programs. ECHA compliance deadlines accelerate substitution of legacy fluorinated compounds with bio-based alternatives.
- Low-Density:Modular configurations serve budget-constrained academic laboratories with lower-throughput requirements.
- Multiplexed Arrays:Simultaneous detection of multiple analytes supports infectious disease surveillance applications in Japanese precision medicine clusters.
- Targeted Arrays:Pre-defined peptide sets for specific protein families suit hypothesis-driven research with predictable reagent consumption.
High-density formats anchor the volume base while customized arrays gain share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive photolithography from accessible SPOT synthesis, with laser printing occupying mid-range positioning for flexible production scales.
- Photolithography:Semiconductor-derived patterning achieves 100,000-feature densities through mask-based light-directed synthesis. Pharmaceutical operations in the United States and Switzerland adopt these platforms for industrial-scale screening where throughput justifies equipment amortization. REACH substance registration obligations force requalification of surface chemistries in European manufacturing.
- SPOT Synthesis:Pin-based parallel peptide synthesis on cellulose membranes enables rapid library generation without specialized capital equipment. European academic consortia and smaller biotechnology firms favor this approach for exploratory research with iterative design cycles. ECHA compliance timelines absorb 12-18 month reformulation cycles for CE marking maintenance.
- Inkjet Printing:Piezoelectric dispensing of amino acid building blocks supports medium-density applications with design flexibility.
- Laser Printing:Laser-induced forward transfer enables non-contact deposition for sensitive substrate materials.
- Solid-Phase Peptide Synthesis:Conventional resin-based chemistry underpins bulk peptide production for array spotting workflows.
Photolithography commands the premium tier while SPOT synthesis expands most quickly in mid-scale research segments.
Application:
Customer type concentration varies sharply: pharmaceutical procurement dominates drug discovery with consolidated multi-year contracts, while diagnostic laboratories drive biomarker identification through fragmented tender processes.
- Drug Discovery:High-throughput screening of protein interactions and lead optimization compresses therapeutic development timelines. Contract research organizations in the United States and Germany expand peptide microarray procurement for antibody program pipelines. FDA and EMA convergence on computational assay qualification standards reshapes validation workflows.
- Biomarker Identification:Clinical validation of disease-associated peptide signatures supports companion diagnostic development. Diagnostic laboratories in Japan and Germany navigate EU MDR framework requirements and FDA in vitro diagnostic guidance for array-based tools. Algorithmic transparency mandates under the EU AI Act embed into European clinical laboratory pipelines.
- Vaccine Development:Epitope mapping for immunogen design targets infectious disease and oncology applications.
- Protein-Protein Interaction:Mapping of binding domains and affinity characterization supports systems biology research.
- Enzyme Profiling:Substrate specificity determination for protease and kinase panels aids mechanistic studies.
Drug discovery anchors the volume base while biomarker identification climbs the fastest as regulatory pathways mature.
End User:
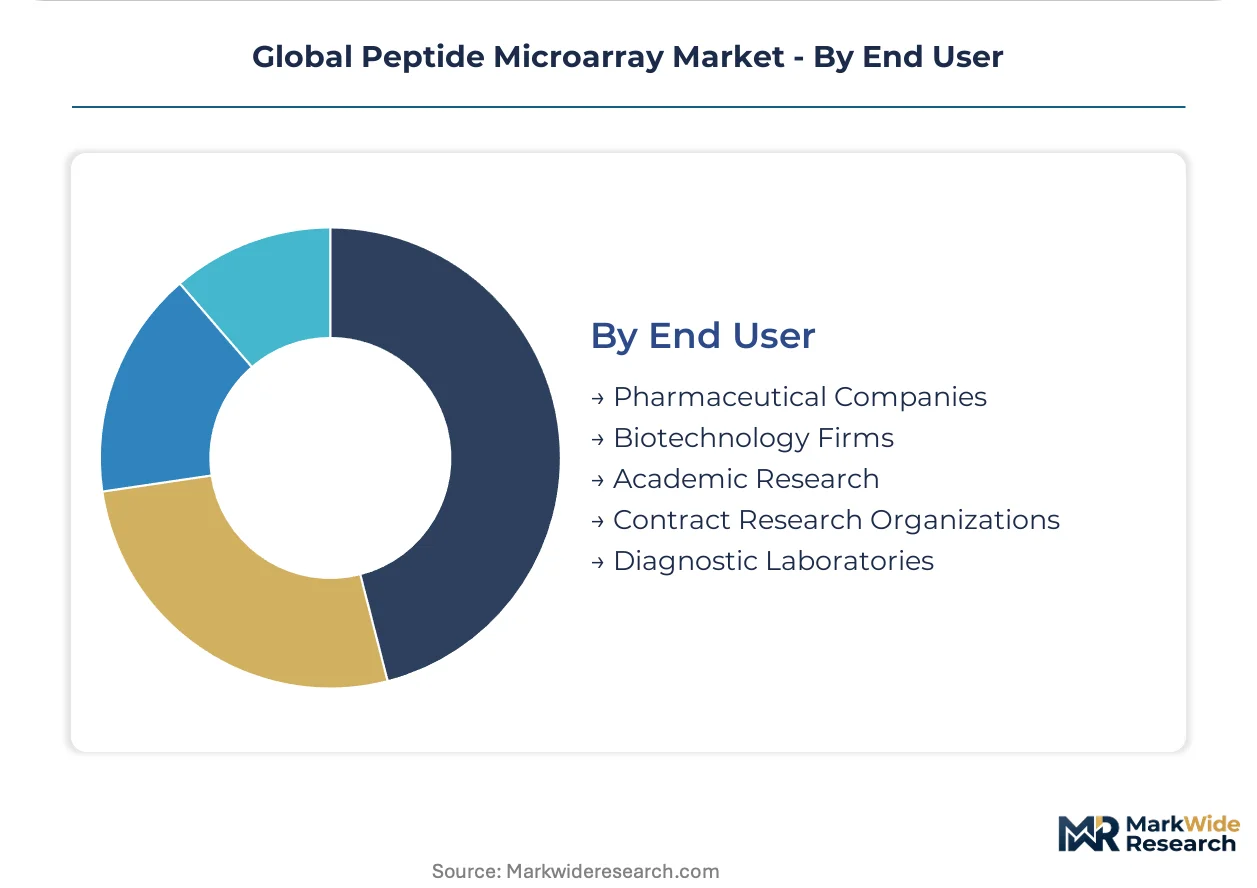
Geography shapes procurement autonomy: national precision medicine initiatives in Germany, the United Kingdom, and Japan consolidate purchasing through framework agreements that displace single-laboratory decision-making.
- Pharmaceutical Companies:Integrated screening operations demand validated high-density platforms with embedded quality assurance. Thermo Fisher Scientific supply chain control and JPT Peptide Technologies custom synthesis capabilities serve North American and European research clusters respectively. Multi-year supply contracts with technical support provisions replace transactional purchasing.
- Academic Research:Budget constraints favor modular low-density and targeted formats with extended replacement cycles. Heidelberg, Cambridge, and Osaka medical centers migrate toward consortia-based procurement through national precision medicine frameworks. ISO 13485 certification timelines delay diagnostic-targeted array market entry for emerging suppliers.
- Biotechnology Firms:Venture-backed development programs prioritize flexible customized array configurations for proprietary target portfolios.
- Contract Research Organizations:Service providers absorb client demand volatility through scalable synthesis partnerships.
- Diagnostic Laboratories:Clinical validation requirements under FDA and EMA jurisdictions drive harmonized reference material demands.
Pharmaceutical companies anchor the volume base while diagnostic laboratories gain share at the steepest rate as companion diagnostic pathways expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision medicine clusters while procurement fragmentation in Indian diagnostic networks compresses margins. The United States and Japan command premium positioning through regulatory convergence on computational validation standards.
United States
FDA guidance on in vitro diagnostic validation and pharmaceutical screening densification drive demand. The IRA framework shapes reimbursement pathways for companion diagnostics. Boston research clusters adopt photolithographic platforms for industrial-scale antibody screening.
Germany
ECHA compliance deadlines and REACH substance registration obligations reshape manufacturing inputs. The EU AI Act embeds algorithmic transparency into clinical laboratory workflows. Heidelberg academic medical centers consolidate procurement through national precision medicine framework agreements.
Japan
METI precision medicine clusters in Kobe and Tsukuba drive customized peptide library procurement. PMDA convergence with FDA standards accelerates computational assay qualification. Osaka medical centers migrate toward multi-year supply contracts with embedded technical support.
India
CDSCO streamlined approval frameworks for companion diagnostics create white space for array-based oncology platforms. Mumbai and Bangalore laboratory networks absorb procurement from fragmented tender processes. Domestic chemical synthesis capabilities remain underdeveloped for Fmoc-protected amino acid inputs.
United Kingdom
Cambridge academic consortia anchor demand for modular low-density formats within constrained research budgets. MHRA alignment with EU MDR frameworks sustains CE marking relevance post-Brexit. London precision medicine procurement centralizes through NHS framework agreements.
Global Peptide Microarray Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in synthesis and surface chemistry supply. The vendor base stratifies across three tiers: diversified life science conglomerates with integrated fulfillment networks, mid-scale peptide synthesis houses with custom library capabilities, and regional distributors pivoting toward digital procurement channels. Dominant competitive moves include backward integration into amino acid supply chains and technology licensing partnerships that bridge photolithographic and SPOT synthesis methodologies.
Among diversified platform integrators, Thermo Fisher Scientific exemplifies supply chain control across North American research clusters. JPT Peptide Technologies and PEPperPRINT GmbH occupy specialist positions anchored in European academic and vaccine development workflows. These three entities represent distinct archetypes: the integrated conglomerate, the custom synthesis house, and the proprietary platform developer.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Abbott Laboratories |
| JPT Peptide Technologies |
| PEPperPRINT GmbH |
| Bio-Rad Laboratories |
| Merck KGaA |
| RayBiotech |
| PerkinElmer |
| Others |
Supply & Pricing Matrix
Overcapacity in German Fmoc-protected amino acid synthesis clusters is forcing reagent suppliers toward volume-discount contracting, compressing margins for mid-scale peptide array manufacturers while concentrating pricing power with integrated conglomerates that control captive amino acid supply.
Pricing Analysis
The customization-premium spread between configured-to-order peptide libraries and standard catalog arrays spans three distinct tiers based on synthesis complexity and validation grade. Project-specific arrays command substantial premiums due to iterative design cycles and proprietary sequence protection, while high-density screening formats price on semiconductor-fabrication-equipment amortization schedules. Cost compression in standard catalog products is intensifying as digital procurement platforms disintermediate traditional distributor markups. Academic research end users exhibit the highest price sensitivity, whereas pharmaceutical screening operations prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China in precision glass substrate trade dominates supply chain risk planning for high-density array manufacturers. Production gravity centers on Germany, Switzerland, and the United States for photolithographic equipment and surface chemistry reagents, while Fmoc-protected amino acid synthesis concentrates in German and Chinese chemical clusters. Raw material dependencies include fluorinated glass substrates, photoresist compounds, and linker molecules subject to REACH requalification timelines. Distribution runs through direct-to-laboratory digital platforms that bypass traditional instrumentation vendor channels for consumable peptide libraries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peptide microarray market is entering a cyclical recovery phase as pharmaceutical screening densification and precision medicine infrastructure investments compress replacement cycles for high-throughput platforms.
For Market Incumbents: Entrench market position through backward integration into amino acid supply chains and accelerated ISO 13485 certification timelines that delay competitor entry. Threat from photolithographic platform specialists demands defensive patent licensing around semiconductor-derived patterning technologies. Capacity addition in Swiss and German precision medicine clusters anchors multi-year supply contracts with embedded technical support provisions. For New Entrants and Emerging Players: Indian diagnostic laboratory networks represent the most penetrable geographic underpenetration, with CDSCO streamlined approval frameworks creating white space for array-based oncology biomarker platforms. Target Mumbai and Bangalore laboratory networks through partnerships with domestic chemical distributors lacking Fmoc-protected amino acid synthesis capabilities. CRISPR-peptide convergence applications in cell therapy development offer a differentiated go-to-market angle with limited incumbent specialization. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because national precision medicine initiatives in Germany, Japan, and the United Kingdom are centralizing procurement through framework agreements that favor suppliers with integrated synthesis-to-validation service capabilities. Acquisition targets should display captive surface chemistry expertise and existing CE marking or FDA master file documentation. Monitor EMA-FDA convergence timelines on computational assay qualification standards as the critical inflection signal for diagnostic-grade array valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Supply | German manufacturers securing captive Fmoc-protected reagent supply hedge against single-source concentration risk. |
| Photolithographic Platform Licensing | Technology partnerships bridging semiconductor-fabrication and SPOT synthesis methodologies accelerate high-density array adoption. |
| ISO 13485 Certification Acceleration | Diagnostic-targeted suppliers compressing quality system implementation cycles gain first-mover advantage in clinical laboratory procurement. |
| Direct-to-Laboratory Digital Procurement | E-commerce platforms displacing traditional instrumentation vendor channels capture consumable replenishment cycles. |
| REACH-Compliant Surface Chemistry Reformulation | Substitution of legacy fluorinated compounds with bio-based alternatives maintains CE marking eligibility through ECHA deadlines. |
Research Methodology
A standing panel of peptide synthesis chemists, pharmaceutical screening directors, diagnostic laboratory managers, and regulatory affairs specialists provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from FDA guidance documents, EMA qualification standards, ECHA substance registration databases, and national precision medicine initiative procurement records. Bottom-up demand modeling from individual laboratory and pharmaceutical facility procurement data triangulated against top-down market sizing from synthesis equipment installed base estimates.
Scenario-bracketing around regulatory convergence timelines and pharmaceutical R&D budget cycles anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format density tiers, synthesis technology capital intensity, application workflow stage, and end-user procurement autonomy level. CAGRs derived from equipment replacement cycle compression rates and consumable replenishment frequency data, with peptide-protein binding specificity limitations and fluorinated substrate cost volatility serving as key sensitivity inputs.
Practitioners should monitor EU AI Act implementation timelines and EMA-FDA computational assay qualification convergence for early signals of diagnostic-grade array demand inflection. Forecasts reflect assumptions around precision medicine infrastructure investment continuity and pharmaceutical screening densification sustainability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
Inhalable Biologics Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
Biomarker Detection Systems Market
Biomedical Technology
Live Cell RNA Detection Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Global Molecular Biosensors Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
Ontogenetic Market