
 Global Protein Crystallization Market | 2026-2036
Global Protein Crystallization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protein Crystallization Market Foresight
North American reagent manufacturing is restructuring around higher-purity consumables for cryo-EM sample preparation. Thermo Fisher Scientific leverages its integrated life sciences platform to anchor supply contracts across academic synchrotron facilities. Bruker Corporation sustains instrument placements through specialized detectors that differentiate its structural biology portfolio from general-purpose analytical competitors.
Protein crystallization encompasses the controlled precipitation of purified proteins into ordered three-dimensional lattices, typically achieved through vapor diffusion or microbatch methods at temperatures between 4°C and 20°C with precise precipitant concentrations. The technique enables atomic-resolution structure determination essential for rational drug design and enzyme mechanism elucidation. Vapor diffusion dominates routine screening workflows due to its minimal sample requirements, while cryo-EM technology captures the fastest expansion as membrane protein targets resist traditional crystallization approaches. Pharmaceutical companies represent the most concentrated end-user segment, with contract research organizations gaining share as biotech firms outsource structural biology capabilities.
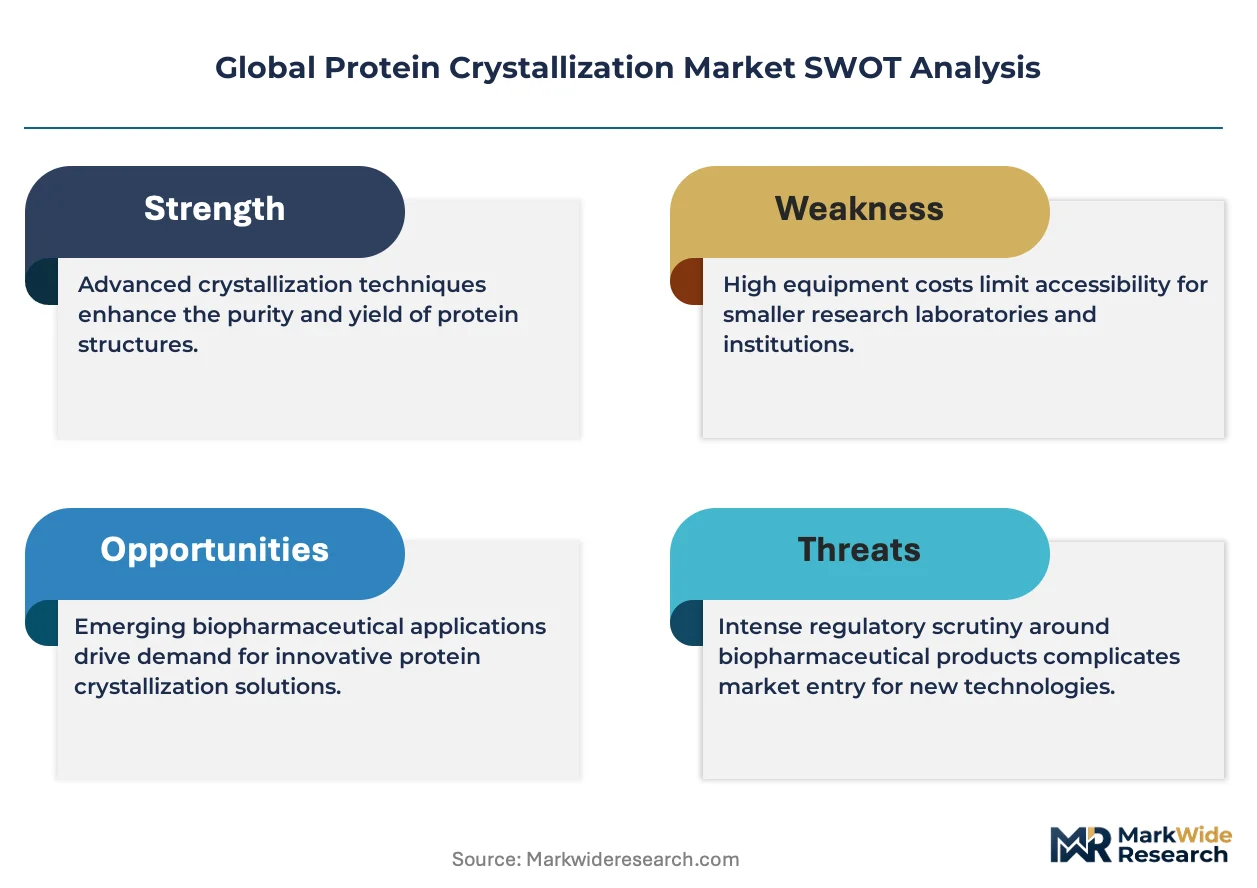
FDA guidelines on quality-by-design for biologic drug development shape crystallization documentation requirements for IND submissions, while the EMA's ICH Q5C stability testing standards influence protein formulation strategies that precede crystallization trials. ISO 17025 accreditation requirements for analytical laboratories affect instrument validation protocols across the supply chain. Stakeholders must monitor how AI-driven structure prediction tools from DeepMind and others reshape the economic rationale for experimental crystallization investments.
Market Dynamics
Automated crystallization workflows are compressing screening timelines from weeks to days, forcing reagent suppliers to restructure around just-in-time consumable delivery models that match the cadence of high-throughput structural biology pipelines.
Growth Catalysts
- FDA quality-by-design guidelines:IND submissions for biologic drugs now mandate crystallization documentation, compelling pharmaceutical developers to expand in-house structural biology capabilities or secure specialized CRO partnerships.
- Synchrotron infrastructure investments:National research agencies in the United States, Germany, and Japan sustain beamline upgrades that reduce data collection bottlenecks and stimulate downstream demand for crystallization screening services.
- Cryo-EM convergence:Membrane protein targets resistant to vapor diffusion methods are redirecting investment toward integrated workflows combining crystallization screening with single-particle electron microscopy validation.
Market Restraints
- Purified protein input volatility:Expression system yields for complex eukaryotic targets remain inconsistent, creating batch-to-batch variation that destabilizes crystallization trial success rates.
- Reagent supply concentration:High-purity precipitant chemistries and specialized crystallization plates concentrate manufacturing among a limited supplier base in the United States and Germany.
- AI structure prediction substitution:DeepMind's AlphaFold and competing neural network models deliver atomic-resolution predictions without physical samples, eroding the economic rationale for experimental crystallization in target classes where prediction accuracy exceeds validation thresholds.
Strategic Opportunities
- India biopharma expansion:CDSCO accelerated approval pathways for biosimilars are attracting multinational structural biology investments into Hyderabad and Bangalore research clusters.
- Microgravity crystallization:International Space Station access programs and commercial low-Earth orbit platforms enable superior crystal quality for difficult protein classes, opening premium service tiers for academic and pharmaceutical clients.
- ISO 17025 laboratory accreditation:Analytical laboratories pursuing crystallization services for quality control applications face validation protocol gaps that accredited providers can capture as differentiated offerings.
Industry Challenges
- Crystallographer talent scarcity:Academic training programs have not kept pace with industry demand for specialists capable of integrating automated screening with synchrotron data interpretation.
- Legacy instrument integration:Pharmaceutical facilities maintaining decade-old imaging systems face compatibility barriers when connecting to modern liquid-handling robotics and LIMS platforms.
- IP licensing complexity:Protein construct designs and crystallization condition optimizations generate fragmented patent landscapes that complicate collaborative research agreements between institutions and commercial entities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protein Crystallization Market |
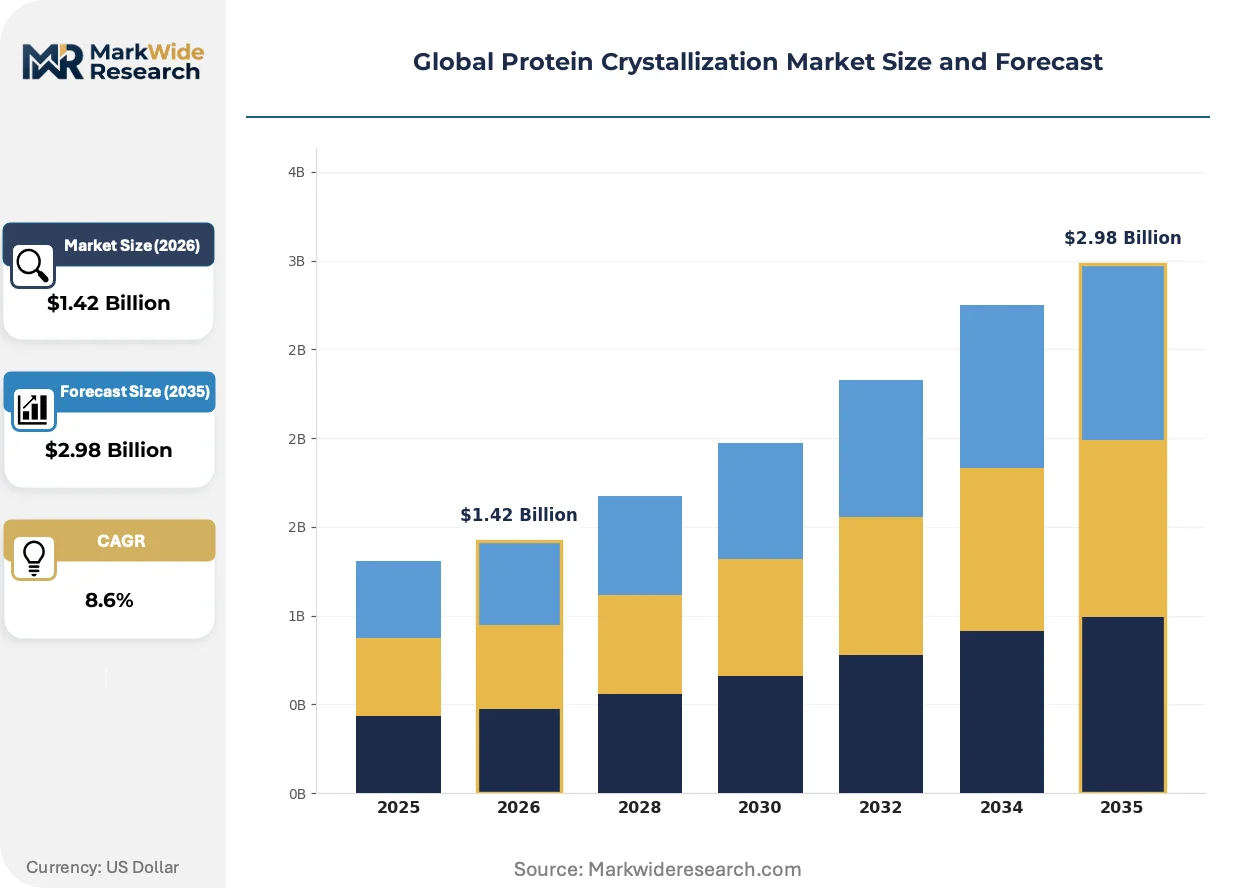
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vapor Diffusion, Batch Crystallization, Microbatch, Dialysis, Free Interface Diffusion Technology: X-ray Crystallography, Nuclear Magnetic Resonance, Electron Microscopy, Cryo-EM, Neutron Diffraction Application: Drug Discovery, Structural Biology, Enzyme Engineering, Antibody Development, Agriculture Research End User: Pharmaceutical Companies, Biotech Firms, Academic Research, Contract Research Organizations |
| Companies Covered | Rigaku Corporation, Bruker Corporation, Thermo Fisher Scientific, Hampton Research, Jena Bioscience GmbH, Formulatrix, Agilent Technologies, Molecular Dimensions, METTLER TOLEDO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protein Crystallization Market Shifts & Advancements
Structural biology instrumentation is bifurcating between high-automation crystallization platforms and cryo-EM sample preparation systems, with vendors restructuring R&D investments to serve both modalities through unified software ecosystems.
Liquid-handling robotics is overtaking manual pipetting in pharmaceutical crystallization operations. Novartis and Roche have deployed integrated screening platforms across multiple discovery sites. This automation compression is eliminating technician-intensive workflows and reallocating structural biology headcount toward data interpretation rather than plate preparation.
EMA's ICH Q5C stability testing standards are reshaping protein formulation strategies that precede crystallization trials. Biologic developers must now document degradation pathways under forced conditions. European CROs have responded by bundling formulation screening with crystallization feasibility assessments to capture integrated service contracts.
Academic core facilities are unbundling crystallization screening from synchrotron data collection. University clients now procure plate imaging and hit identification as standalone services, then select beamtime allocation through competitive peer-review cycles. This disaggregation is most advanced in the United Kingdom and Switzerland, where national synchrotron programs operate independent access mechanisms from institutional screening laboratories.
Global Protein Crystallization Market Segmentation
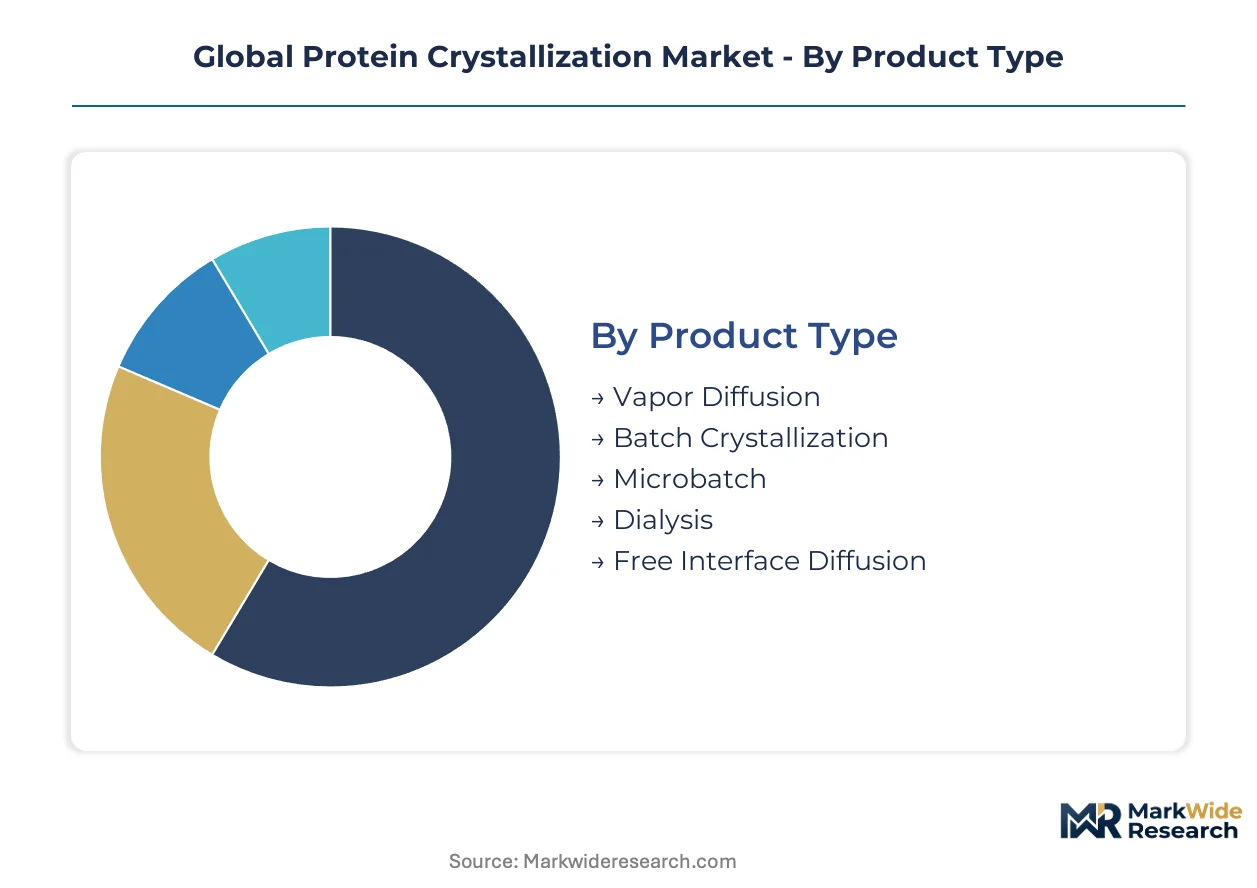
Protein crystallization market segmentation reflects the tension between established vapor diffusion workflows and emerging cryo-EM integration. Equipment upgrade cycles and consumable replenishment patterns differ sharply across product categories, creating distinct revenue rhythms for suppliers.
Product Type:
Upgrade cycles for crystallization instrumentation compress as pharmaceutical laboratories replace aging manual systems with integrated liquid-handling platforms. Replacement demand concentrates in facilities running decade-old imaging infrastructure that cannot interface with modern robotics.
- Vapor Diffusion:Hanging-drop and sitting-drop configurations dominate routine screening through minimal sample consumption. Pharmaceutical companies in the United States and Germany sustain demand for high-throughput vapor diffusion workstations that compress screening timelines from weeks to days.
- Cryo-EM:Single-particle electron microscopy captures the steepest expansion trajectory as membrane protein targets resist traditional crystallization. Academic synchrotron facilities in Japan and Switzerland redirect capital toward integrated workflows combining cryo-EM validation with initial crystallization screening.
- Batch Crystallization:Large-volume precipitation methods serve industrial enzyme production where crystal size uniformity outweighs atomic resolution requirements.
- Microbatch:Under-oil crystallization chambers reduce evaporation artifacts for salt-sensitive proteins.
- Dialysis:Gradual equilibration against precipitant buffers benefits protein complexes requiring slow maturation kinetics.
- Free Interface Diffusion:Counter-diffusion geometries enable kinetic trapping of transient crystalline intermediates for time-resolved structural studies.
Vapor Diffusion sits at the top of the volume ranking, with Cryo-EM climbing the fastest.
Technology:
Cost tier stratification separates synchrotron-dependent methods from laboratory-scale alternatives, with capital intensity determining access patterns across end-user segments.
- X-ray Crystallography:Synchrotron radiation sources deliver the highest-resolution data for drug-bound protein structures. Beamline investments by national research agencies in the United States, Germany, and Japan sustain downstream demand for crystallization screening services.
- Cryo-EM:Single-particle reconstruction eliminates crystal quality constraints for flexible macromolecular assemblies. Structural biology CROs in Bangalore and Hyderabad capture premium pricing for cryo-EM sample preparation as Indian biopharma expands.
- Nuclear Magnetic Resonance:Solution-state dynamics complement static crystal structures for intrinsically disordered protein regions.
- Electron Microscopy:Negative-stain screening precedes high-resolution cryo-EM investment decisions.
- Neutron Diffraction:Hydrogen atom visibility supports enzyme mechanism studies requiring protonation state determination.
X-ray Crystallography commands the largest installed base, while Cryo-EM expands most rapidly.
Application:
Customer type concentration varies by therapeutic maturity, with antibody developers running denser crystallization pipelines than agricultural researchers.
- Drug Discovery:Structure-based design campaigns require iterative co-crystallization with lead compound series. FDA quality-by-design guidelines for IND submissions mandate crystallization documentation, compelling pharmaceutical developers to expand structural biology headcount.
- Antibody Development:Fab and Fc domain structures guide humanization and affinity maturation strategies. Biotech firms in Boston and San Francisco outsource crystallization screening to CROs with integrated synchrotron access.
- Structural Biology:Fundamental mechanism studies sustain academic core facility utilization.
- Enzyme Engineering:Active-site architectures direct directed evolution libraries for biocatalysis applications.
- Agriculture Research:Crop protection target structures support herbicide and fungicide discovery pipelines.
Drug Discovery generates the highest screening volumes, with Antibody Development gaining share fastest.
End User:
Procurement centralization distinguishes pharmaceutical conglomerates from fragmented academic purchasing, with biotech firms occupying an intermediate position on vendor consolidation.
- Pharmaceutical Companies:Integrated discovery platforms at Novartis and Roche anchor multi-year supply contracts for consumables and instrumentation. Internal structural biology capabilities insulate against CRO capacity constraints during peak screening cycles.
- Contract Research Organizations:European CROs bundle formulation screening with crystallization feasibility assessments to capture integrated service contracts under EMA ICH Q5C stability testing standards.
- Biotech Firms:Venture-funded startups in Cambridge and South San Francisco prioritize cryo-EM access over crystallization infrastructure ownership.
- Academic Research:University core facilities unbundle screening from synchrotron data collection, procuring imaging services independently from beamtime allocation.
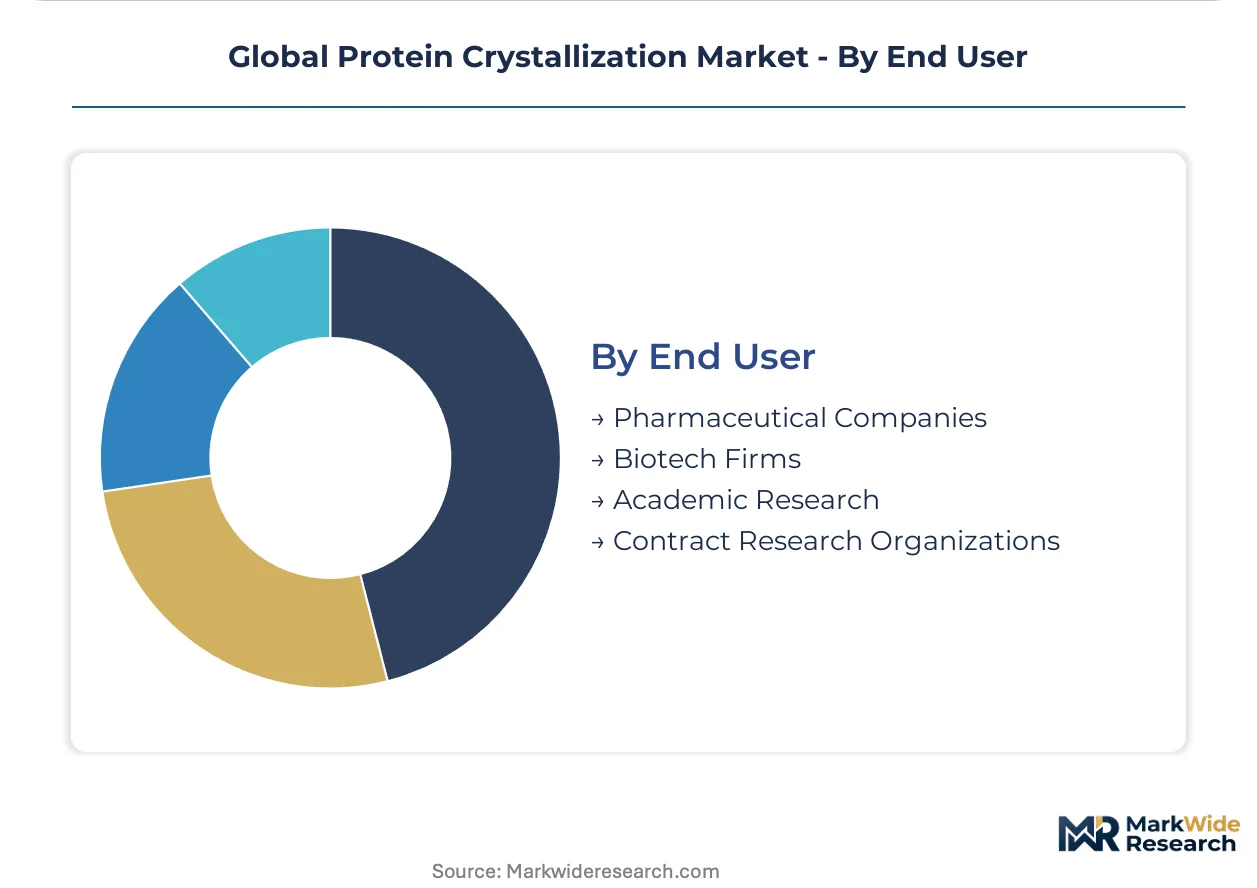
Pharmaceutical Companies dominate absolute spending, with Contract Research Organizations expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting crystallization service contracts toward jurisdictions with streamlined biologics approval pathways and lower operational cost bases. National research agencies compete for structural biology investment through differential beamline access pricing and accelerated ethics review timelines.
United States
FDA quality-by-design guidelines for IND submissions mandate crystallization documentation, compelling pharmaceutical developers to expand in-house structural biology capabilities. The National Institutes of Health sustains synchrotron infrastructure investments through the National Synchrotron Light Source II at Brookhaven National Laboratory. Greater Boston anchors contract research demand as biotech firms in Cambridge and South San Francisco outsource screening to CROs with integrated beamtime access.
Germany
EMA ICH Q5C stability testing standards reshape protein formulation strategies that precede crystallization trials across European biologic developers. The Helmholtz Association operates PETRA III at DESY in Hamburg, supplying high-brilliance X-ray sources for pharmaceutical structure determination. Munich and Heidelberg research clusters concentrate automated crystallization platform deployments as Max Planck Institutes expand structural biology headcount.
Japan
METI funding for advanced structural biology infrastructure sustains demand for high-throughput crystallization screening services. SPring-8 in Hyogo Prefecture operates as Asia's highest-flux synchrotron radiation facility, reducing data collection bottlenecks for membrane protein targets. Tokyo and Osaka metropolitan areas host pharmaceutical R&D centers running integrated vapor diffusion workflows for antibody development pipelines.
India
CDSCO accelerated approval pathways for biosimilars attract multinational structural biology investments into Hyderabad and Bangalore research clusters. The Department of Biotechnology funds cryo-EM facility installations at Indian Institute of Science and Centre for Cellular and Molecular Biology. CROs in Genome Valley and Biocon Park capture premium pricing for integrated screening and electron microscopy validation services.
Switzerland
Swissmedic guidelines on biologic drug stability documentation influence crystallization trial design for IND-enabling studies. The Swiss Light Source at Paul Scherrer Institute supplies specialized beamlines for pharmaceutical co-crystallography with fragment-based lead compounds. Basel and Zurich pharmaceutical corridors sustain concentrated demand for high-purity reagent manufacturing and automated liquid-handling platforms.
Global Protein Crystallization Market Competitive Landscape
United States producers anchor the premium instrumentation tier; German and Japanese specialists hold differentiated positions in detector technologies and synchrotron-integrated systems. The vendor base stratifies across three tiers: diversified life sciences conglomerates with integrated structural biology platforms; mid-scale instrument manufacturers with specialized crystallization automation; and regional reagent suppliers serving academic core facilities. Consolidation pressures intensify as pharmaceutical procurement centralizes around multi-year supply contracts, while technology licensing agreements proliferate between synchrotron facilities and commercial screening service providers.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Agilent Technologies occupy positions leveraging broad life sciences portfolios to anchor supply contracts across academic synchrotron facilities. Bruker Corporation exemplifies the specialized instrumentation archetype, sustaining placements through detector technologies that differentiate structural biology offerings from general-purpose analytical competitors. Among mid-scale automation specialists, Formulatrix and Hampton Research represent the focused crystallization platform segment, serving pharmaceutical screening operations and academic core facilities with liquid-handling robotics and imaging infrastructure.
| Leading Market Players |
|---|
| Rigaku Corporation |
| Bruker Corporation |
| Thermo Fisher Scientific |
| Hampton Research |
| Jena Bioscience GmbH |
| Formulatrix |
| Agilent Technologies |
| Molecular Dimensions |
| METTLER TOLEDO |
| Others |
Supply & Pricing Matrix
High-purity precipitant chemistries originating from German and United States specialty chemical manufacturers cascade through three pricing tiers before reaching pharmaceutical screening operations, with ISO 17025 certification premiums separating contract research laboratories from academic core facilities.
Pricing Analysis
Distributor margins on crystallization consumables compress as direct procurement channels expand between reagent manufacturers and high-volume pharmaceutical buyers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales technical support bundling. Price differentiation stems from batch documentation depth and validated supply chain traceability required for FDA IND submissions. Academic laboratories exhibit highest price sensitivity, while integrated biopharmaceutical discovery platforms absorb premium tiers for guaranteed lot-to-lot consistency.
Supply Chain Analysis
Regional distribution centers in Hamburg, Boston, and Osaka operate hub-and-spoke patterns serving synchrotron-adjacent research clusters within 48-hour delivery windows. Manufacturing concentrates in the United States and Germany for high-purity crystallization plates, while specialized detector components draw from Japanese precision optics suppliers. Single-source vulnerability persists for vapor diffusion consumables where patent-protected surface chemistries limit qualified vendors. Distribution runs through authorized distributors for academic accounts and direct sales teams for pharmaceutical conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protein crystallization market has entered a late-cycle quality phase where automated platform reliability and reagent batch consistency command premium positioning over raw throughput capacity, as antibody developers prioritize IND-enabling documentation packages.
For Market Incumbents: Anticipate margin compression in standard-grade consumables as Indian CROs backward-integrate into basic reagent manufacturing. Defend positioning through captive supply of ISO 17025-certified screening services and exclusive beamtime allocation partnerships at United States and German synchrotron facilities. Deepen upstream control over high-purity precipitant chemistries to insulate against specialty chemical supply volatility.
For New Entrants and Emerging Players: The premium-to-economy price gap in cryo-EM sample preparation consumables offers entry terrain for mid-tier automation specialists. Capture share in Bangalore and Hyderabad CRO clusters where multinational biopharma outsources integrated screening and validation workflows. Lead with modular liquid-handling platforms compatible with legacy imaging infrastructure to bypass replacement cycle delays.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional reagent suppliers lack automated manufacturing scale to serve pharmaceutical procurement centralization. Target mid-scale crystallization platform specialists with installed bases at academic synchrotron facilities for defensive portfolio expansion. Watch AlphaFold prediction accuracy thresholds as the inflection signal for experimental crystallization demand displacement in soluble protein target classes.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Platform Integration | Novartis and Roche deployments validate robotics as the default screening architecture, compressing manual workflow timelines. |
| Cryo-EM Convergence Investment | Membrane protein target resistance to vapor diffusion redirects capital toward integrated electron microscopy validation capabilities. |
| Synchrotron Partnership Structuring | Exclusive beamtime allocation agreements at NSLS-II and PETRA III lock in downstream screening service demand. |
| ISO 17025 Accreditation Expansion | Regulatory documentation requirements for FDA IND submissions differentiate certified providers in quality-control applications. |
| Indian CRO Capacity Buildout | CDSCO accelerated biosimilar pathways attract multinational structural biology investments into Hyderabad research clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with structural biology platform directors, reagent procurement managers at pharmaceutical conglomerates, academic core facility administrators, and synchrotron beamline scientists with secondary validation against SEC filings, NIH instrumentation grant databases, EMA regulatory guidance documents, and customs trade data for crystallization consumables. Bottom-up triangulation across product-level shipment data and top-down reconciliation against national research agency capital expenditure disclosures anchored volume estimates.
Segment-weighting applied differential growth coefficients across vapor diffusion, cryo-EM, and batch crystallization modalities, with technology adoption curves modeled separately for pharmaceutical, CRO, and academic end-user archetypes. CAGRs derived from instrument replacement cycle analysis and consumable replenishment patterns observed across the projection horizon. Forecast inputs incorporated AI structure prediction substitution rates and synchrotron infrastructure investment pipelines from the United States, Germany, and Japan.
Caveats apply where AlphaFold accuracy breakthroughs or microgravity crystallization platform commercialization could materially shift the outlook for terrestrial screening demand. Forecasts reflect documented assumptions regarding regulatory documentation requirements and national research agency funding continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Biochips Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Global Cell Signaling Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
DNA Synthesis Market