
 Asia-Pacific Proteomics Market | 2026-2036
Asia-Pacific Proteomics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Proteomics Market Outlook
Capability gaps in high-resolution mass spectrometry manufacturing is unwinding competitive stability across the Asia-Pacific proteomics landscape. Thermo Fisher Scientific Inc. leverages its Orbitrap technology leadership to anchor premium instrument sales in Japan and Australia. Danaher Corporation sustains broad reagent and consumables portfolios that dominate recurring revenue streams across Chinese diagnostic laboratories. Bruker Corporation differentiates through specialized timsTOF platforms that occupy emerging spatial proteomics niches in South Korean research institutes.
Proteomics encompasses the large-scale study of proteins, their structures, functions, and interactions within biological systems, typically employing mass spectrometry with resolution thresholds exceeding 100,000 full width at half maximum to identify and quantify thousands of protein species simultaneously. Its primary commercial purpose centers on accelerating therapeutic target validation, enabling disease biomarker discovery, and supporting personalized treatment stratification in clinical settings. Mass spectrometry instruments command the dominant share of product-type value pools due to capital intensity and replacement cycles, while immunoassay technologies capture expanding volume in point-of-care diagnostic applications across Asia-Pacific healthcare networks. Software segments represent the fastest-growing margin category as cloud-based bioinformatics platforms reduce downstream analysis bottlenecks for pharmaceutical and academic end users.
Japan's PMDA and South Korea's MFDS enforce stringent analytical validation standards for clinical proteomics assays, shaping product development priorities and market access timelines for instrument vendors. China's NMPA implements accelerated review pathways for innovative diagnostic devices, directly stimulating domestic proteomics platform adoption in tertiary hospitals. Australia's TGA alignment with ISO 13485 quality management systems facilitates instrument import flows from European and American manufacturers. Stakeholders must monitor evolving harmonization between national regulatory frameworks and the WHO's prequalification standards for in vitro diagnostics to anticipate certification cost structures and competitive positioning requirements.
Market Dynamics
High-resolution mass spectrometry manufacturing concentration in Germany and the United States is fragmenting competitive stability across the Asia-Pacific proteomics landscape, forcing regional buyers into multi-year procurement cycles and technology transfer negotiations.
Growth Catalysts
- China's NMPA accelerated review pathways:Tertiary hospitals in Beijing and Shanghai are fast-tracking clinical proteomics platform procurement, compressing traditional 18-month approval timelines into 9-month windows for innovative diagnostic devices.
- Spatial proteomics demand from South Korean research institutes:The Korea Research Institute of Bioscience and Biotechnology is scaling timsTOF-based tissue imaging programs, driving instrument replacement cycles in Seoul's biomedical corridor.
- Precision medicine hubs:Singapore's National Precision Medicine program is mandating proteomic stratification for oncology therapeutic selection, creating anchored demand for cloud-based bioinformatics infrastructure.
Market Restraints
- Helium supply volatility:Mass spectrometry instruments depend on liquid helium for superconducting magnet cooling, and Qatar's export concentration creates 6-9 month lead time uncertainty for Japanese and Australian laboratories.
- PMDA analytical validation requirements:Japan's pharmaceutical regulator enforces 24-month clinical validation timelines for proteomics-based companion diagnostics, extending commercialization pathways beyond venture capital fund horizons.
- Reagent import dependency:Chinese diagnostic laboratories source 70% of high-purity solvents and calibration standards from European suppliers, exposing operations to freight cost spikes and customs clearance friction.
Strategic Opportunities
- Vietnam's underpenetrated hospital network:Ho Chi Minh City's Cho Ray Hospital is piloting proteomics-driven sepsis biomarker panels, creating first-mover positioning for instrument vendors ahead of national health insurance reimbursement expansion.
- Single-cell proteomics convergence:The integration of microfluidic cell isolation with data-independent acquisition mass spectrometry is opening therapeutic target validation workflows previously inaccessible to bulk analysis methods.
- Australia's TGA-ISO 13485 alignment:Streamlined quality management certification is enabling European manufacturers to bypass redundant factory audits, accelerating instrument registration in Melbourne and Sydney research clusters.
Industry Challenges
- Bioinformatics specialist scarcity:Pharmaceutical companies in Tokyo and Seoul face 8-12 month recruitment cycles for computational biologists capable of integrating spectral libraries with machine learning pipelines.
- Legacy LIMS integration complexity:Hospital information systems in China's provincial tier-2 cities run on decade-old Oracle architectures that resist API connectivity with modern cloud-based proteomics data platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Proteomics Market |
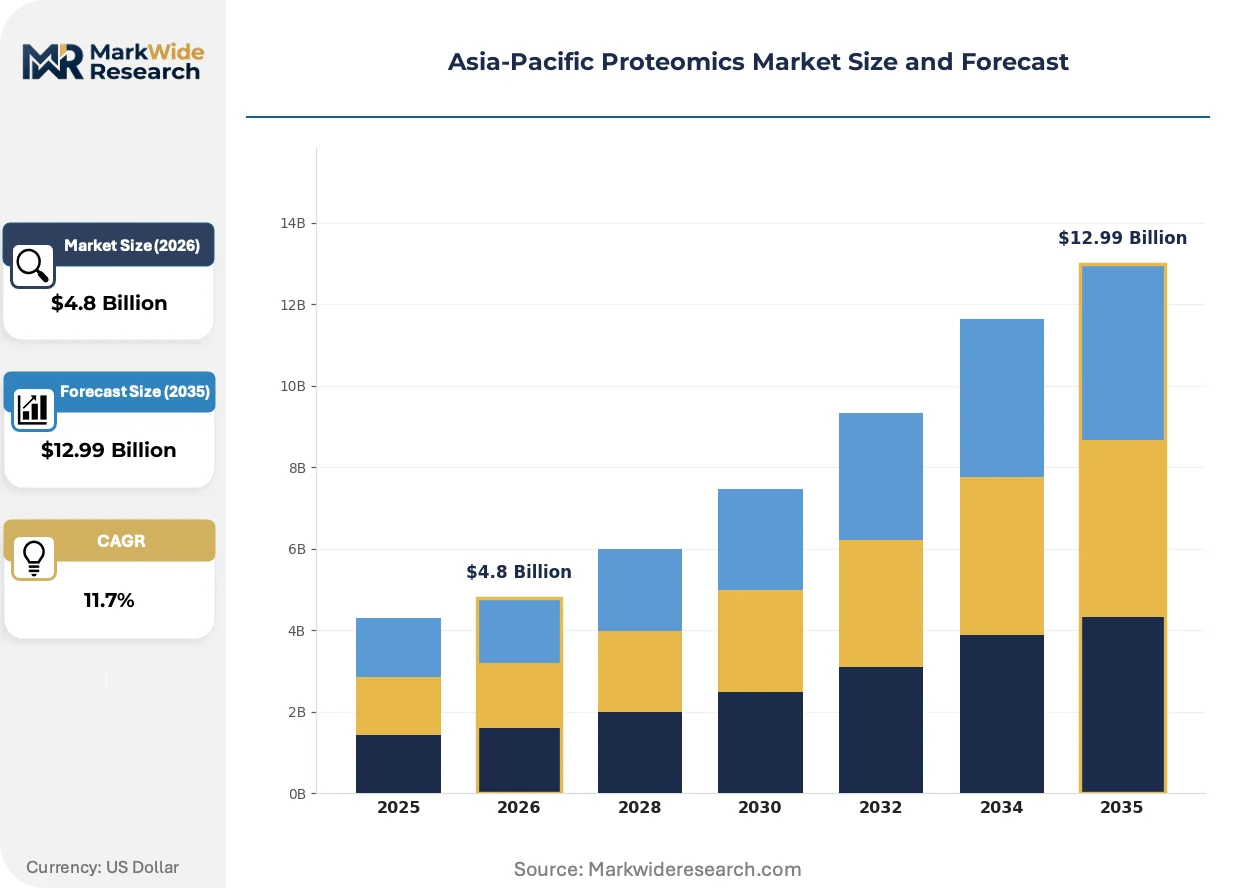
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Consumables Technology: Mass Spectrometry, Chromatography, Immunoassays, Microarrays Application: Drug Discovery, Clinical Diagnostics, Biomarker Research, Personalized Medicine End User: Pharmaceutical Companies, Research Institutes, Diagnostic Laboratories, Academic Institutions |
| Companies Covered | Agilent Technologies, Inc., Bio-Rad Laboratories, Inc., Danaher Corporation, Thermo Fisher Scientific Inc., Bruker Corporation, GE Healthcare, Merck KGaA, Waters Corporation, Shimadzu Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Proteomics Market Strategic Shifts
Cloud-native bioinformatics architectures are compressing analysis bottlenecks while regulatory harmonization efforts and procurement centralization are restructuring how proteomics capabilities reach end users across the Asia-Pacific region.
Microfluidic sample preparation cartridges are miniaturizing proteomics workflows from bench-scale liquid handling to handheld formats. Point-of-care diagnostic networks in Australia's regional health districts are piloting these devices for rapid infectious disease profiling. The technology is miniaturizing capital requirements for hospital laboratories, enabling decentralized testing nodes that bypass centralized core facility dependencies.
Japan's PMDA revised its In Vitro Diagnostics Quality Management System Ordinance in 2023, mandating traceable calibration chains for quantitative proteomics assays used in clinical decision-making. Domestic instrument vendors must now maintain ISO 17025-accredited reference material production or partner with certified third-party suppliers. Academic medical centers in Osaka and Nagoya are responding by consolidating procurement through university hospital alliances that pool validation resources.
Hospital procurement consortia in China's Jiangsu and Zhejiang provinces are displacing single-institution purchasing with provincial tendering platforms that aggregate demand across 30-50 tertiary facilities. Thermo Fisher and Danaher are restructuring distribution contracts to interface directly with these consortia, bypassing traditional regional distributor networks. This concentration is most visible in Shanghai's Pudong district, where the municipal health commission coordinates proteomics instrument acquisition for 12 affiliated hospitals.
Asia-Pacific Proteomics Market Segmentation
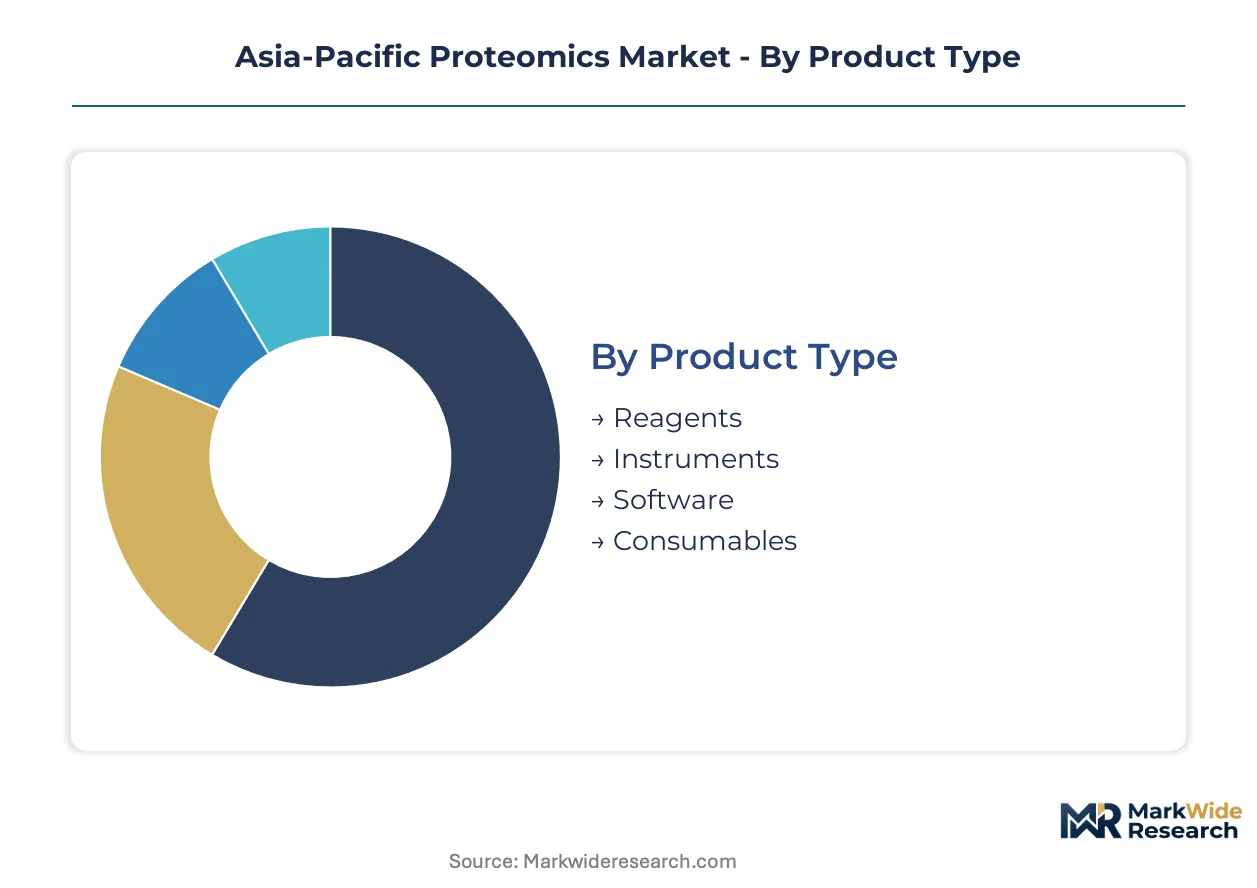
Proteomics market segmentation in Asia-Pacific reflects divergent regulatory pathways across national health authorities and varying capital intensity thresholds between research and clinical environments. Product categories face distinct approval timelines from China's NMPA, Japan's PMDA, and Australia's TGA, while technology choices map directly to helium supply constraints and bioinformatics integration capabilities.
Product Type:
Japan's PMDA and South Korea's MFDS enforce differentiated quality management requirements across product categories, with instruments facing 24-month validation cycles versus 9-12 month windows for reagents and consumables.
- Instruments:High-resolution mass spectrometry systems with Orbitrap and timsTOF architectures dominate capital expenditure pools in Japan and Australia. Thermo Fisher's installation base across Tokyo and Osaka academic medical centers anchors replacement demand despite helium supply volatility from Qatar.
- Reagents:High-purity solvents, calibration standards, and sample preparation kits constitute recurring revenue streams with compressed margins. Chinese diagnostic laboratories source 70% of these inputs from European suppliers, exposing procurement to freight cost spikes and customs clearance friction.
- Software:Cloud-native bioinformatics platforms reduce downstream analysis bottlenecks for pharmaceutical end users in Singapore and Seoul. These segments are expanding most quickly as machine learning pipelines integrate spectral library searching.
- Consumables:Microfluidic sample preparation cartridges miniaturize workflows for point-of-care networks in Australia's regional health districts.
Established volume favors instruments; emerging adoption favors software.
Technology:
Technology selection correlates with end-use maturity, where clinical diagnostics demand validated immunoassay platforms while exploratory research tolerates higher-variance mass spectrometry methods.
- Mass Spectrometry:Data-independent acquisition methods with resolution thresholds exceeding 100,000 FWHM enable simultaneous identification of thousands of protein species. South Korea's Korea Research Institute of Bioscience and Biotechnology is scaling timsTOF-based tissue imaging programs in Seoul's biomedical corridor.
- Chromatography:Liquid chromatography upstream of mass detection remains essential for complex sample deconvolution in biomarker discovery workflows. Reagent import dependency constrains operational continuity in Chinese provincial laboratories.
- Immunoassays:Enzyme-linked and chemiluminescent formats capture expanding volume in point-of-care diagnostic applications across Asia-Pacific healthcare networks, particularly where NMPA accelerated review pathways compress approval timelines.
- Microarrays:Multiplexed protein detection on solid substrates retains niche positioning for targeted biomarker panels with established clinical utility.
Research intensity concentrates in mass spectrometry; clinical translation favors immunoassay standardization.
Application:
Application segmentation tracks reimbursement policy divergence, with drug discovery and biomarker research receiving venture funding while clinical diagnostics and personalized medicine depend on national health insurance inclusion.
- Drug Discovery:Therapeutic target validation workflows integrate single-cell proteomics with microfluidic isolation methods previously inaccessible to bulk analysis. Pharmaceutical companies in Tokyo and Seoul face 8-12 month recruitment cycles for computational biologists capable of managing these pipelines.
- Clinical Diagnostics:Quantitative proteomics assays for clinical decision-making now require traceable calibration chains under Japan's 2023 revised IVD Quality Management System Ordinance. Domestic instrument vendors must maintain ISO 17025-accredited reference material production.
- Biomarker Research:Discovery-phase protein signature development concentrates in Australia's biomedical research corridor and Singapore's precision medicine hubs.
- Personalized Medicine:Singapore's National Precision Medicine program mandates proteomic stratification for oncology therapeutic selection, creating anchored demand for cloud-based bioinformatics infrastructure.
Funding availability favors drug discovery; regulatory clarity favors clinical diagnostics.
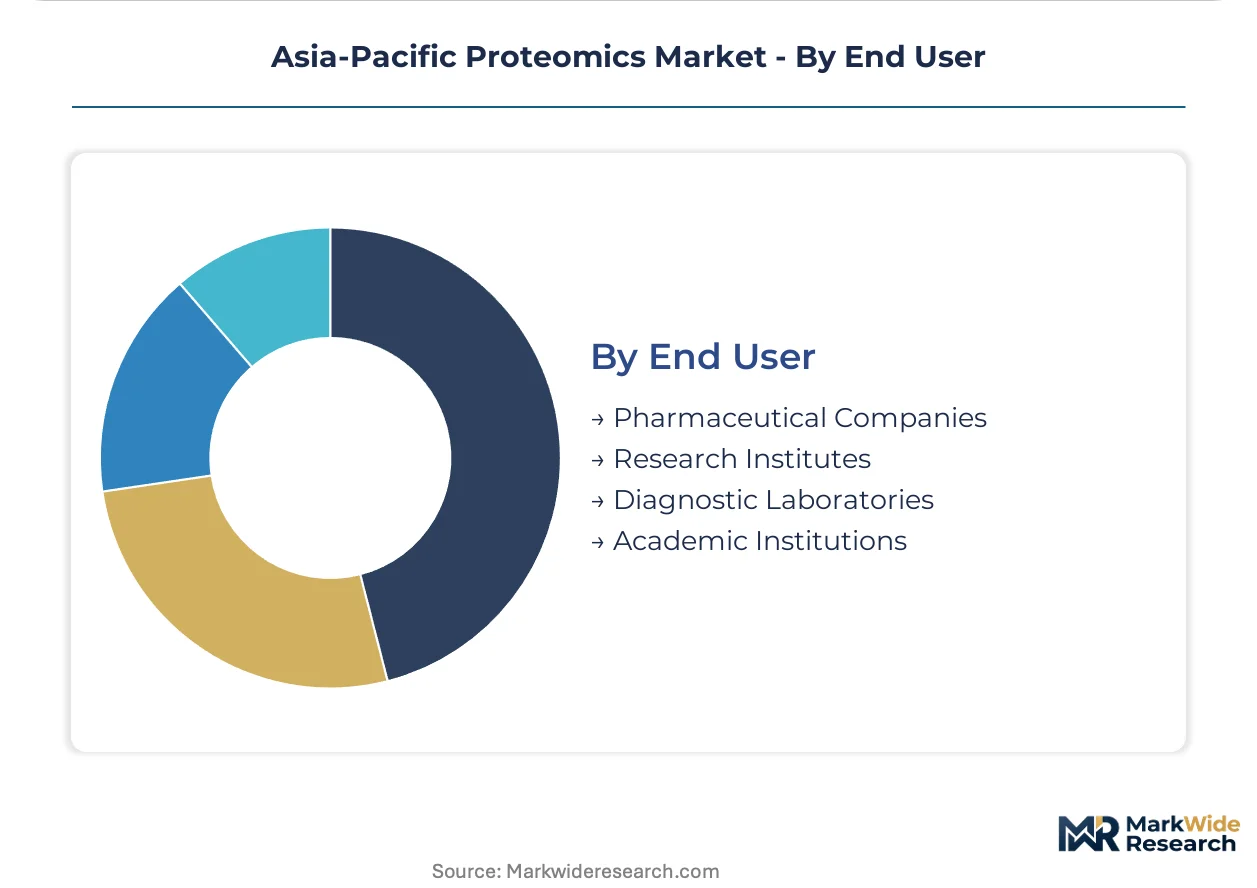
End User:
End user segmentation reflects procurement centralization trends, where hospital consortia in Jiangsu and Zhejiang provinces aggregate demand across 30-50 tertiary facilities, displacing single-institution purchasing.
- Pharmaceutical Companies:Biomarker program scaling in Japan and South Korea drives premium instrument procurement with dedicated bioinformatics support contracts.
- Research Institutes:Spatial proteomics demand from South Korean institutes accelerates instrument replacement cycles. The Korea Research Institute of Bioscience and Biotechnology anchors national capability in this segment.
- Diagnostic Laboratories:Provincial tendering platforms in China restructure distribution relationships, with Thermo Fisher and Danaher interfacing directly with municipal health commissions rather than regional distributors.
- Academic Institutions:University hospital alliances in Osaka and Nagoya pool validation resources to meet PMDA calibration requirements for quantitative assays.
Consolidated procurement favors diagnostic laboratories; specialized capability favors research institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratories in Vietnam and Indonesia exhibit acute price elasticity for proteomics consumables, while pharmaceutical companies in Japan and Singapore absorb premium instrument costs with minimal procurement friction.
China
Tertiary hospitals in Beijing and Shanghai are compressing traditional 18-month procurement cycles into 9-month windows. NMPA accelerated review pathways for innovative diagnostic devices directly stimulate domestic platform adoption. The municipal health commission in Shanghai's Pudong district coordinates instrument acquisition across 12 affiliated hospitals.
Japan
Pharmaceutical companies in Tokyo and Osaka scale biomarker programs requiring dedicated bioinformatics support contracts. PMDA enforces 24-month clinical validation timelines for proteomics-based companion diagnostics. University hospital alliances in Osaka and Nagoya pool validation resources to meet calibration requirements.
South Korea
The Korea Research Institute of Bioscience and Biotechnology anchors national spatial proteomics capability in Seoul's biomedical corridor. MFDS analytical validation standards shape product development priorities for instrument vendors. timsTOF-based tissue imaging programs drive instrument replacement cycles in research institutes.
Australia
Biomedical research corridors in Melbourne and Sydney concentrate discovery-phase protein signature development. TGA alignment with ISO 13485 quality management systems facilitates instrument import flows from European manufacturers. Point-of-care networks in regional health districts pilot microfluidic sample preparation for infectious disease profiling.
Singapore
National Precision Medicine program mandates proteomic stratification for oncology therapeutic selection. Anchored demand for cloud-based bioinformatics infrastructure supports pharmaceutical end users. Research hubs concentrate precision medicine capability with minimal price sensitivity for premium platforms.
Asia-Pacific Proteomics Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that concentrates in spatial proteomics and point-of-care diagnostics. The integrated tier commands capital expenditure pools through high-resolution mass spectrometry platforms, while specialists occupy emerging application niches with differentiated architectures. Three archetypes define competitive positioning: full-stack instrument-reagent-software providers, premium platform specialists, and consumables-dominant suppliers. Dominant competitive moves include direct distribution restructuring to bypass regional networks and university alliance partnerships to pool regulatory validation resources.
Among integrated instrumentation providers, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the full-stack archetype through combined instrument-reagent-software portfolios. Bruker Corporation occupies a specialist position within the premium platform tier. These three companies anchor competitive dynamics across procurement centralization trends and regulatory validation requirements in Japan, China, and South Korea.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| Bio-Rad Laboratories, Inc. |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| Bruker Corporation |
| GE Healthcare |
| Merck KGaA |
| Waters Corporation |
| Shimadzu Corporation |
| Others |
Value Chain & Pricing Dynamics
Japan's PMDA analytical validation requirements gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified reagent vendors while anchoring premium pricing for ISO 17025-accredited instrument providers serving Tokyo's academic medical centers.
Pricing Analysis
After-sales service contracts and extended warranty tiers drive lifetime value capture across the Asia-Pacific proteomics landscape. Three-tier pricing structure across premium, standard, and economy levels separates Orbitrap-equipped installations from timsTOF configurations and entry-level quadrupole systems. Price differentiation rests on helium supply security guarantees and bioinformatics integration depth. Cost compression in economy-tier consumables is intensifying because Chinese diagnostic laboratories are consolidating procurement through provincial tendering platforms. Hospital procurement consortia in Jiangsu and Zhejiang provinces exhibit acute price sensitivity, while Singapore's precision medicine hubs absorb premium instrument costs with minimal friction.
Supply Chain Analysis
Port congestion along the Shanghai-Rotterdam trade lane elevates inbound logistics costs for European-sourced calibration standards and high-purity solvents. Manufacturing concentration in Germany and the United States feeds mass spectrometry instrument supply, while China and South Korea anchor chromatography component production. Raw material dependencies center on liquid helium from Qatar, rare earth magnets for superconducting systems, and specialized ion optics. Single-source vulnerability in helium supply creates operational continuity risk for Japanese and Australian laboratories. Distribution runs through municipal health commission consortia in China's tier-1 cities, displacing traditional regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where PMDA and NMPA validation timelines create switching costs that lock hospital procurement consortia into established supplier relationships.
For Market Incumbents: Fortify market position by deepening captive supply of ISO 17025-accredited reference materials and securing long-term helium offtake agreements with Qatari exporters. Threat from microfluidic point-of-care substitutes demands accelerated cloud-native bioinformatics platform development to maintain software attach rates. Priority lever centers on direct distribution contracts with Shanghai's municipal health commission, bypassing fragmented regional networks.
For New Entrants and Emerging Players: Differentiate on spatial proteomics specialization targeting South Korea's Korea Research Institute of Bioscience and Biotechnology and Seoul's biomedical corridor. White-space opportunity concentrates in Vietnam's underpenetrated hospital network, where Cho Ray Hospital's sepsis biomarker pilot creates first-mover positioning ahead of national reimbursement expansion. Go-to-market angle emphasizes microfluidic cartridge miniaturization for Australia's regional health districts.
For Investors and Strategic Acquirers: China's NMPA accelerated review pathways reshape the acquisition landscape by compressing regulatory validation timelines and elevating domestic platform valuations. Long-term viability favors vertically integrated instrument-reagent-software providers with established PMDA certification infrastructure. Acquisition target archetype: specialized timsTOF platform developers with anchored research institute relationships. Signal to watch: harmonization between national regulatory frameworks and WHO prequalification standards for in vitro diagnostics.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | PMDA ISO 17025 accreditation secures premium pricing in Japan's university hospital alliances. |
| Direct Distribution Restructuring | Bypassing regional networks interfaces vendors with Jiangsu and Zhejiang provincial tendering platforms. |
| Helium Supply Diversification | Long-term offtake agreements with Qatari exporters mitigate superconducting magnet cooling risk. |
| Cloud-Native Bioinformatics Development | Machine learning pipeline integration addresses pharmaceutical recruitment cycles for computational biologists. |
| Microfluidic Cartridge Miniaturization | Handheld formats enable Australia's regional health districts to bypass centralized core facility dependencies. |
Study Parameters
Cross-validation between primary interviews with mass spectrometry platform engineers, hospital procurement committee members, regulatory affairs specialists at NMPA and PMDA, and diagnostic laboratory directors anchors the qualitative findings. Secondary validation draws from NMPA device registration databases, PMDA IVD quality management ordinance filings, ISO 13485 certification records, and helium import trade statistics. Bottom-up instrument installation base analysis triangulates with top-down market size estimation across product type, technology, application, and end user segmentation dimensions.
Sensitivity analysis around helium supply disruption scenarios and NMPA approval timeline compression informs projection robustness. The analytical framework models mass spectrometry resolution tier, immunoassay standardization level, spatial versus bulk analysis method, and cloud versus on-premise bioinformatics deployment across the analysis window. CAGRs derive from instrument replacement cycle analysis, reagent consumption intensity per installed base unit, and software subscription renewal patterns. Industry-specific forecast inputs include tertiary hospital procurement budget trajectories in Beijing and Shanghai and precision medicine program funding allocations in Singapore.
Decision-makers should treat outputs as directional under sustained NMPA accelerated review pathway continuity and stable Qatar helium export volumes; material deviation would warrant model refresh. Specific risk factors that could revise forecasts include PMDA validation timeline extensions for companion diagnostics and freight cost spikes disrupting European reagent supply chains. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Nucleic Acid Electrophoresis and Blotting Market
Biomedical Technology
Fluoro Enzymatic Assays Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Drug Delivery Technology Market
Biomedical Technology
Biochips Market
Biomedical Technology
North America Proteomics Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Proteomics Market
Biomedical Technology
Middle East and Africa Cell Counting Market
Biomedical Technology
Global Cell Counting Market
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market