
 Global Autologous Conditioned Plasma Market | 2026-2036
Global Autologous Conditioned Plasma Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autologous Conditioned Plasma Market Foresight
ISO 13485 certification for medical device quality management is rotating as the decisive gate for market participation in autologous conditioned plasma processing. Arthrex leverages its vertically integrated manufacturing of centrifugation systems to dominate North American hospital procurement. EmCyte Corporation anchors its position through specialized filtration technologies that sustain premium positioning in orthopedic clinics.
Autologous conditioned plasma comprises patient-derived blood fractions with platelet concentrations typically exceeding baseline levels by four to five times, prepared through controlled centrifugation to isolate growth factor-rich serum for localized tissue regeneration. The orthopedics application segment leads volume due to established reimbursement pathways for tendon and joint interventions, while microfluidics-based preparation technology represents the fastest-growing structural category as manufacturers compete on processing speed and platelet recovery rates. Leukocyte-rich formulations command margin concentration in sports medicine, whereas leukocyte-poor variants occupy standard-care positioning in cosmetic dermatology.
The FDA's regenerative medicine advanced therapy designation shapes clinical trial requirements and manufacturing controls for US market access, while the EU Medical Device Regulation imposes stricter conformity assessment on automated preparation systems sold in Europe. Japan's PMDA oversees comparable premarket approval pathways that filter which preparation technologies reach Japanese orthopedic and dental practices. Stakeholders must monitor how divergent classification standards across FDA, EMA, and PMDA jurisdictions determine where automated processing platforms gain commercial traction first.
Market Dynamics
The FDA's regenerative medicine advanced therapy designation is compressing clinical trial timelines while simultaneously tightening manufacturing controls, forcing preparation system vendors to reconfigure quality management infrastructure ahead of commercial scale-up.
Growth Catalysts
- Sports medicine clinic expansion:Orthopedic and athletic training facilities across the United States, Germany, and South Korea are standardizing platelet-rich plasma protocols for tendon and ligament repair, creating installed base demand for automated preparation systems.
- ISO 13485 certification convergence:Medical device quality management standards are becoming the non-negotiable procurement filter for hospital and clinic buyers, elevating certified manufacturers above uncertified competitors in contract awards.
- Microfluidics processing speed:Next-generation preparation technologies are reducing centrifugation cycles from hours to minutes, enabling same-day clinical workflows that expand addressable procedure volume in high-throughput settings.
Market Restraints
- Leukocyte formulation complexity:The technical trade-off between leukocyte-rich and leukocyte-poor preparations fragments manufacturing scale economies, forcing vendors to maintain dual product lines with divergent filtration specifications.
- Supply concentration in centrifugation components:Precision rotor and chamber assemblies concentrate among a limited set of German and Japanese precision engineering suppliers, exposing downstream device makers to input bottlenecks.
- EMA MDR conformity assessment friction:The EU Medical Device Regulation's stricter notified body requirements for automated preparation systems are extending time-to-market for new platform launches in European orthopedic clinics.
Strategic Opportunities
- Brazilian cosmetic dermatology penetration:ANVISA regulatory pathways for aesthetic applications remain less congested than orthopedic indications, offering first-mover positioning for leukocyte-poor formulation specialists in São Paulo and Rio de Janeiro clinic networks.
- Japan's PMDA regenerative medicine framework:The Pharmaceuticals and Medical Devices Agency's conditional approval pathways for tissue repair biologics are creating accelerated market access for preparation technologies that demonstrate consistent platelet recovery metrics.
- Point-of-care integration with surgical navigation:Convergence between automated plasma preparation and intraoperative imaging systems is enabling real-time treatment customization in hospital operating rooms, differentiating integrated platform vendors.
Industry Challenges
- Bioprocessing technician scarcity:The specialized skill set required for aseptic handling of autologous blood fractions and quality-controlled centrifugation operation outpaces training program output in major metropolitan hospital systems.
- Multi-jurisdiction certification timeline compression:Simultaneous pursuit of FDA 510(k), EMA MDR, and PMDA approvals for automated preparation platforms strains regulatory affairs bandwidth and capital allocation across geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autologous Conditioned Plasma Market |
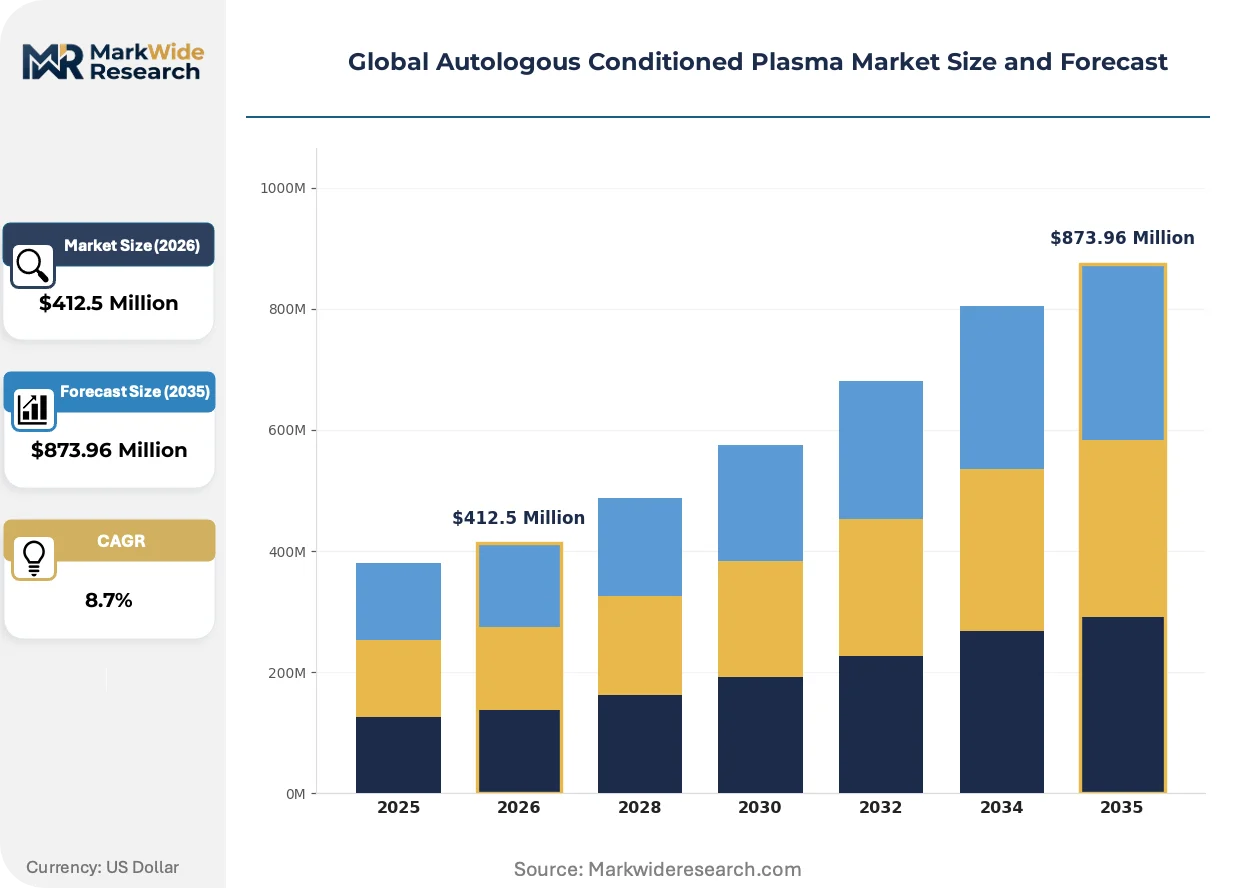
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Area: Orthopedics, Dermatology, Sports Medicine, Dentistry, Plastic Surgery Product Type: Leukocyte-Rich, Leukocyte-Poor, Activated, Non-Activated, Gel Form End User: Ambulatory Surgical Centers, Specialty Clinics, Dental Offices, Cosmetic Centers, Physiotherapy Centers Preparation Technology: Centrifugation, Filtration, Automated Systems, Manual Kits, Microfluidics |
| Companies Covered | Arthrex, EmCyte Corporation, Zimmer Biomet, Stryker Corporation, Terumo Corporation, Regen Lab SA, Dr. PRP America LLC, Biotechnology Institute BTI, AdiStem Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autologous Conditioned Plasma Market Shifts & Advancements
Preparation technology is fragmenting into speed-optimized and purity-optimized branches, while regulatory jurisdictions diverge on classification standards for automated versus manual processing systems.
Microfluidic separation platforms are decomposing the traditional centrifugation workflow by enabling continuous-flow platelet concentration without batch processing delays. Outpatient surgical centers in the United States are adopting these systems to compress same-day procedure timelines. The technology is decomposing the installed base advantage of legacy centrifuge manufacturers by reducing capital requirements and footprint constraints for new clinic entrants.
The EU Medical Device Regulation's classification of automated plasma preparation systems as Class IIa or IIb devices is imposing clinical evidence requirements that manual preparation kits escape. European orthopedic clinics are responding by consolidating procurement around vendors with established technical documentation and notified body relationships. Smaller device manufacturers without MDR transition experience are retreating to manual kit markets or exiting Europe entirely.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, treating consumables and maintenance as separately negotiable line items. This pattern compresses vendor margin structures in the United States and Germany while rewarding manufacturers with transparent consumable pricing and third-party service compatibility. Sports medicine clinic chains are driving this behavior most aggressively, using volume commitments to extract service flexibility concessions.
Global Autologous Conditioned Plasma Market Segmentation
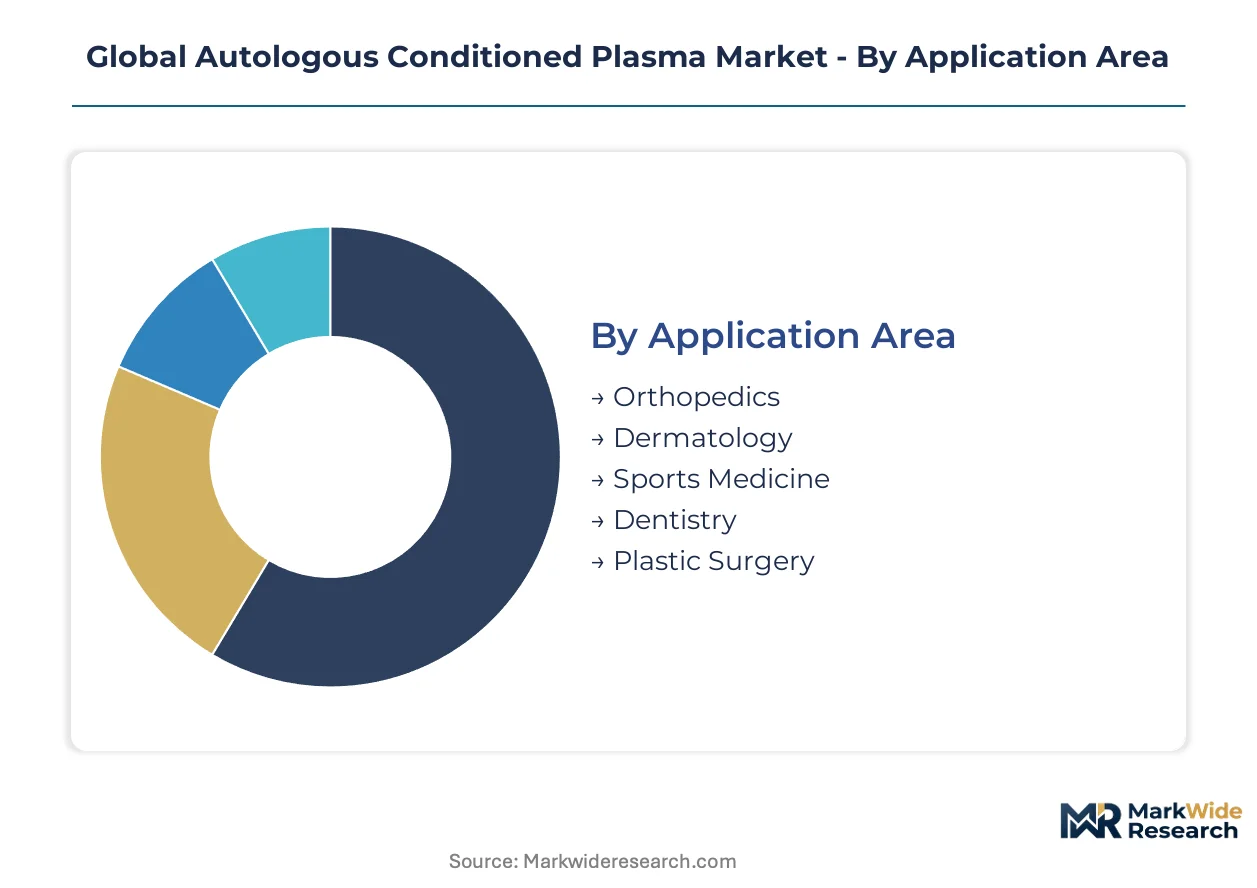
Segmentation in autologous conditioned plasma reveals how reimbursement pathways, processing speed requirements, and clinical workflow constraints concentrate demand across distinct product configurations. Understanding these divisions exposes where vendors can defend margin pools against commoditization pressures.
Application Area:
Margin concentration in this category tracks reimbursement density and procedure volume scalability across therapeutic domains.
- Orthopedics:Tendon and joint interventions dominate volume through established CPT codes that cover platelet-rich plasma injections for chronic conditions. Hospital outpatient departments in the United States and Germany are standardizing protocols for rotator cuff and Achilles repair, creating recurring demand for preparation systems with validated platelet recovery metrics.
- Sports Medicine:Athletic training facilities and professional team medical staffs command premium pricing for leukocyte-rich formulations that accelerate ligament healing. South Korean baseball and football franchises are expanding on-site preparation capabilities, compressing treatment-to-return timelines for high-value athletes.
- Dermatology:Cosmetic applications favor leukocyte-poor variants with lower inflammatory profiles for facial rejuvenation procedures.
- Dentistry:Periodontal regeneration and implant site preparation drive specialized formulation requirements in oral surgery practices.
- Plastic Surgery:Post-operative healing protocols and scar revision applications support niche positioning for activated plasma preparations.
Orthopedics holds installed capacity. Sports Medicine is rotating up the share rankings.
Product Type:
Formulation complexity in this category fragments manufacturing scale economies while creating tiered pricing architecture.
- Leukocyte-Rich:Elevated white blood cell content enhances growth factor release for tissue repair in orthopedic and sports applications. German sports medicine clinics specify these formulations for acute injury protocols, accepting higher inflammatory response risk for accelerated healing trajectories.
- Leukocyte-Poor:Reduced immunogenicity suits aesthetic applications where inflammation control determines patient satisfaction. São Paulo cosmetic centers are standardizing these variants for facial volume restoration, driving volume in Brazilian aesthetic markets.
- Activated:Exogenous thrombin or calcium chloride triggering accelerates clot formation for surgical site applications.
- Non-Activated:Native platelet release kinetics support gradual growth factor delivery in chronic wound management.
- Gel Form:Scaffold-integrated preparations enable localized retention in dental and periodontal procedures.
Leukocyte-Rich captures premium pricing in orthopedic accounts. Leukocyte-Poor is expanding most quickly through cosmetic dermatology penetration.
End User:
Procurement authority and capital equipment access divide this category between institutional buyers and independent practice owners.
- Ambulatory Surgical Centers:High-throughput settings in the United States demand automated preparation platforms that integrate with same-day discharge workflows. These facilities negotiate consumable contracts separately from capital purchases, compressing vendor margin structures.
- Specialty Clinics:Orthopedic and sports-focused practices in Germany prioritize ISO 13485-certified systems for liability protection and insurer recognition.
- Dental Offices:Implantology practices in Japan source compact centrifugation units with periodontal-specific protocols.
- Cosmetic Centers:Brazilian aesthetic clinics favor manual preparation kits to minimize regulatory compliance burdens under ANVISA pathways.
- Physiotherapy Centers:Rehabilitation-focused settings in South Korea adopt point-of-care systems for tendon loading protocols.
Ambulatory Surgical Centers concentrate capital purchasing volume. Specialty Clinics are climbing the fastest in procurement sophistication.
Preparation Technology:
Speed-versus-purity trade-offs in this category determine which vendors capture replacement cycles versus greenfield installations.
- Microfluidics:Continuous-flow separation eliminates batch processing delays, enabling sub-15-minute preparation cycles. United States outpatient surgical centers are adopting these platforms to compress procedure scheduling and expand daily case volume.
- Centrifugation:Density-gradient separation remains the reference standard for platelet recovery validation in regulated markets. Legacy installed base in European hospitals creates replacement demand as MDR compliance deadlines approach.
- Filtration:Membrane-based concentration suits compact footprint requirements in dental and cosmetic settings.
- Automated Systems:Closed-loop processing with integrated quality controls addresses technician scarcity in metropolitan hospital systems.
- Manual Kits:Low capital requirements sustain penetration in price-sensitive markets and regulatory jurisdictions with lighter device classification.
Centrifugation maintains the largest installed base. Microfluidics is gaining share fastest through speed-based differentiation in high-throughput environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regenerative medicine incentives accelerate US clinic adoption while EMA MDR compliance deadlines reshape European procurement patterns. PMDA conditional approval pathways in Japan and ANVISA aesthetic regulations in Brazil create divergent access timelines for preparation technologies.
United States
Hospital outpatient departments standardize platelet-rich plasma protocols for rotator cuff repair. FDA regenerative medicine advanced therapy designation compresses clinical trial timelines for automated preparation systems. Texas Medical Center clusters drive demand for same-day microfluidic processing platforms.
Germany
Sports medicine clinics specify leukocyte-rich formulations for acute ligament injury protocols. EU Medical Device Regulation conformity assessment requirements elevate ISO 13485-certified manufacturers in procurement decisions. Munich and Berlin orthopedic networks consolidate around validated centrifugation systems with established technical documentation.
Japan
Professional baseball and football medical staffs expand on-site preparation capabilities for high-value athletes. PMDA conditional approval pathways for tissue repair biologics accelerate market access for consistent platelet recovery technologies. Osaka dental implantology practices source compact centrifugation units with periodontal-specific protocols.
South Korea
Rehabilitation-focused physiotherapy centers adopt point-of-care systems for tendon loading protocols. MFDS medical device registration requirements filter which automated platforms reach orthopedic clinics. Seoul Capital Area sports medicine chains drive volume for high-throughput preparation systems.
Brazil
São Paulo and Rio de Janeiro cosmetic centers standardize leukocyte-poor variants for facial rejuvenation procedures. ANVISA regulatory pathways for aesthetic applications remain less congested than orthopedic indications. Clinic networks minimize compliance burdens through manual preparation kit adoption.
Global Autologous Conditioned Plasma Market Competitive Landscape
Listed leaders compete with private specialists across certification and technology dimensions in the autologous conditioned plasma processing space. Arthrex and Stryker leverage scale advantages in North American hospital procurement while smaller specialists capture premium positioning through filtration specialization. Three archetypes dominate: vertically integrated device manufacturers, component-focused technology licensors, and regional preparation kit distributors. Competitive moves concentrate on M&A for regulatory certification assets and capacity expansion in microfluidic platform production.
Within the integrated manufacturing tier, Arthrex exemplifies the vertically integrated archetype through captive centrifugation system production. EmCyte Corporation occupies a specialist position in filtration technology segments. Zimmer Biomet sits within the diversified orthopedic portfolio tier, representing scale-driven platform vendors that span multiple regenerative medicine applications.
| Leading Market Players |
|---|
| Arthrex |
| EmCyte Corporation |
| Zimmer Biomet |
| Stryker Corporation |
| Terumo Corporation |
| Regen Lab SA |
| Dr. PRP America LLC |
| Biotechnology Institute BTI |
| AdiStem Ltd. |
| Others |
Supply & Pricing Matrix
Microfluidics displacement of legacy centrifugation systems is rerouting component sourcing from German precision engineering clusters toward East Asian semiconductor fabrication hubs, simultaneously compressing capital equipment pricing tiers and fragmenting aftermarket service contract structures.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-validated platforms and uncertified manual kits. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance status, EMA MDR technical documentation depth, and consumable bundling arrangements. Price erosion runs through manual kit tiers as Brazilian and Southeast Asian clinics prioritize regulatory cost minimization. Ambulatory surgical centers in the United States exhibit lowest price sensitivity due to same-day procedure revenue capture, while independent cosmetic centers in São Paulo drive hardest consumable contract negotiations.
Supply Chain Analysis
Germany and Japan anchor precision rotor and chamber assembly production for density-gradient centrifugation systems. Manufacturing draws from specialty steel alloys, ceramic bearings, and medical-grade polymer seals. Single-source vulnerability concentrates in Munich-area precision machining subcontractors serving Arthrex and Stryker installed base replacement cycles. Distribution runs through orthopedic GPO contracts in North America, direct hospital procurement in Germany, and regional distributor networks in Brazil and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autologous conditioned plasma processing equipment generates recurring revenue through consumable cartridges and preventive maintenance contracts expanding faster than capital hardware replacement cycles. Service-attach ratios climb as microfluidics platforms require specialized calibration protocols unavailable to in-house biomedical engineering teams.
For Market Incumbents: Fortify aftermarket service moats through captive technician certification programs addressing bioprocessing specialist scarcity in Texas Medical Center and Seoul Capital Area hospital systems. Deepen backward integration into consumable membrane production to offset price compression from unbundled procurement negotiations led by United States ambulatory surgical center chains. For New Entrants and Emerging Players: Post-sales technical training gaps in Japanese dental implantology practices and South Korean physiotherapy centers offer white-space entry points. ANVISA's lighter aesthetic device classification enables leukocyte-poor formulation specialists to establish Brazilian beachhead before orthopedic regulatory congestion intensifies. Partner with São Paulo clinic networks for co-branded training certification programs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed filtration technology specialists holding ISO 13485 credentials but lacking MDR transition experience. Five-to-ten year viability hinges on regulatory certification breadth rather than manufacturing scale alone. Monitor PMDA conditional approval pathway queue depths as inflection signal for Japanese market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | EMA notified body relationships determine European hospital procurement eligibility for automated platforms. |
| Microfluidics Platform Launch | Sub-15-minute processing cycles capture United States outpatient surgical center replacement demand. |
| Consumable Cartridge Supply Agreement | Long-term contracts with German sports medicine chains stabilize recurring revenue against capital purchase volatility. |
| Bioprocessing Technician Certification Program | Addressing skill scarcity in metropolitan hospital systems differentiates service attach rates. |
| Brazilian Aesthetic Clinic Partnership | ANVISA pathway positioning for leukocyte-poor formulations ahead of orthopedic regulatory congestion. |
Research Methodology
Cross-validation between primary interviews with orthopedic surgeons, hospital procurement managers, biomedical engineers, and GPO contracts specialists anchors the qualitative findings. Secondary sources include FDA 510(k) filings, EMA MDR technical documentation databases, CMS Medicare reimbursement schedules, and South Korean MFDS registration records. Bottom-up procedure volume estimates triangulate against top-down capital equipment shipment data.
Sensitivity analysis around platelet recovery rate assumptions and reimbursement pathway stability shapes the analytical framework across the analysis window. Segmentation dimensions span application area, product formulation type, preparation technology, and end-user facility category. CAGRs derive from installed base replacement cycles, greenfield clinic expansion rates, and technology substitution elasticities.
Material uncertainties — FDA regenerative medicine designation timeline shifts, EMA notified body capacity constraints, and precision component supply bottlenecks — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory clearance velocity and clinician protocol standardization. Recalibration cycles align with material shifts in reimbursement density and automated platform adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
Stem Cell Banking Market
Biomedical Technology
PD L1 Biomarker Testing Market
Biomedical Technology
Global Biocompatibility Testing Services Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
E2 Antibody Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
Europe Transfection Technologies Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Neoantigen Market
Biomedical Technology
Global Molecular Biosensors Market