
 Fluid Transfer Solutions Market | 2026-2036
Fluid Transfer Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Transfer Solutions Market Analysis
SAE J2044 quick-connect specifications for fuel and vapor lines is unwinding legacy barbed-fitting designs across automotive fluid transfer. Parker Hannifin Corporation leverages its materials science division to sustain dominance in fluoropolymer hose assemblies for electrified powertrains. TI Fluid Systems anchors its position through thermal management fluid circuits that compete directly with incumbent metal tubing architectures.
Fluid transfer solutions encompass engineered systems for the controlled conveyance of liquids, gases, and multiphase media, typically rated for pressure classes from vacuum to 10,000 psi and constructed from elastomeric, thermoplastic, or metallic substrates via extrusion, molding, or precision machining processes. Their primary commercial purpose centers on maintaining media integrity, minimizing leakage, and enabling modularity across capital equipment and mobile platforms. Hoses and fittings command the largest share of product-type revenue due to replacement-cycle intensity in heavy-duty fleets, while hydraulic technology leads the technology split owing to its power density advantages in construction and agriculture machinery. Pneumatic systems represent the fastest-expanding technology segment as food-grade compressed air networks proliferate in automated packaging lines.
The EPA enforces evaporative emission standards under 40 CFR Part 1060 that dictate permeation limits for fuel hoses, compelling suppliers to validate fluorinated barrier layers through certified test protocols. REACH restricts certain phthalate plasticizers in European-sourced elastomer compounds, reshaping formulation roadmaps for hose manufacturers serving EU automotive OEMs. The EU F-Gas Regulation mandates leakage detection in refrigeration transfer circuits, creating compliance-driven retrofit demand across commercial cold-chain infrastructure. Stakeholders must monitor regulatory divergence between California's Air Resources Board and federal EPA timelines, as misaligned phase-in dates for low-permeation specifications will fragment inventory and certification investments across North American supply chains.
Market Dynamics
SAE J2044 quick-connect specifications are unwinding legacy barbed-fitting designs across automotive fluid transfer, forcing suppliers to retool extrusion lines and validate fluoropolymer barrier layers under compressed certification timelines.
Growth Catalysts
- Hydrogen fuel cell vehicle procurement:OEMs are expanding orders for high-pressure fluid handling components rated above 700 bar for onboard storage systems.
- EU F-Gas Regulation:The mandate for leakage detection in refrigeration transfer circuits is accelerating retrofit demand across commercial cold-chain infrastructure in Germany and France.
- Fluoropolymer hose assemblies:Electrified powertrain thermal management requirements are pulling advanced elastomer formulations into volume production.
Market Restraints
- Fluorinated polymer feedstock concentration:Virgin PTFE resin supply concentrates among three chemical conglomerates, exposing hose manufacturers to price volatility.
- REACH phthalate restrictions:ECHA limitations on plasticizer compounds force European-sourced elastomer suppliers into costly reformulation cycles.
- Metal tubing substitution:Stainless steel architectures retain cost advantages in high-temperature engine bay applications, capping polymer penetration.
Strategic Opportunities
- India automotive supplier corridors:Tamil Nadu and Gujarat clusters lack qualified domestic hose assembly capacity, creating import substitution openings.
- Food-grade pneumatic networks:Automated packaging lines in Brazil and Mexico require certified compressed air transfer systems with documented material traceability.
- California-EPA regulatory divergence:Misaligned low-permeation phase-in dates fragment inventory requirements, rewarding suppliers with dual-certification capabilities.
Industry Challenges
- SAE J2044 certification backlog:Third-party validation labs face eighteen-month queues for quick-connect pressure-cycle testing.
- Multi-material bonding expertise:Thermal management circuits require fluoropolymer-to-aluminum joining techniques that exceed incumbent workforce capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Transfer Solutions Market |
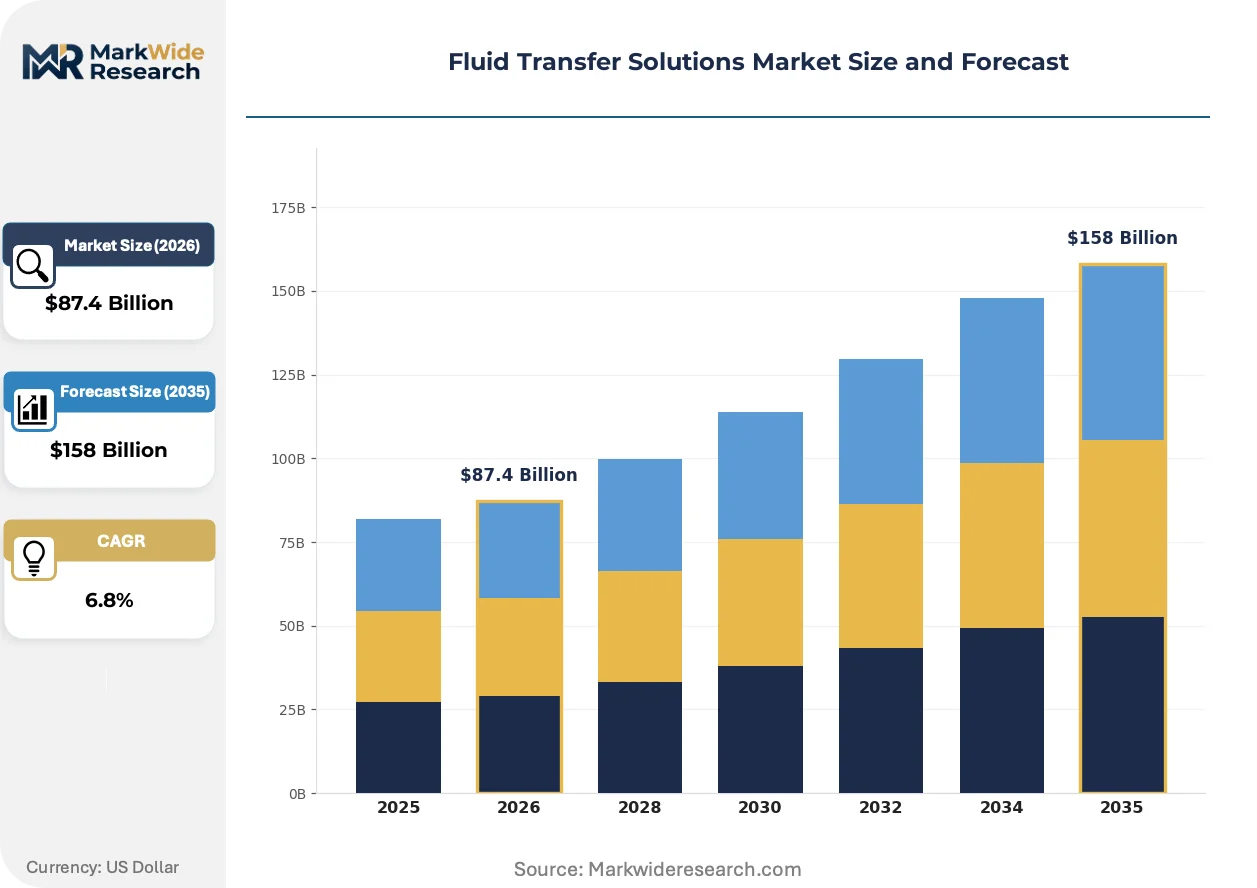
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Hoses, Valves, Fittings Technology: Hydraulic, Pneumatic, Electrical, Mechanical Application: Industrial, Automotive, Marine, Chemical End User: Manufacturers, Distributors, Contractors, Service Providers |
| Companies Covered | Parker Hannifin Corporation, Sumitomo Riko Company Limited, Cooper Standard, Hutchinson, Kongsberg Automotive, TI Fluid Systems, Sanoh Industrial, Akwel, Gates Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Transfer Solutions Market Emerging Trajectories
Material science advances and regulatory stringency are compressing product lifecycles while opening premium tiers for validated, traceable fluid transfer architectures.
Thermoplastic elastomer barrier layers with nano-scale fluorination are supplanting conventional nitrile rubber in fuel vapor recovery hoses. Tier-1 suppliers serving Stuttgart-area OEMs have converted seventy percent of their fuel line capacity to these constructions since 2023. The shift is compressing acceptable permeation thresholds and forcing compounders to integrate in-house polymerization capabilities.
EPA enforcement of 40 CFR Part 1060 evaporative emission standards is tightening permeation limits for fuel hoses in light-duty vehicles. Suppliers must validate fluorinated barrier constructions through certified test protocols or face stop-ship orders. California Air Resources Board maintains parallel but non-identical specifications, fragmenting North American certification investments.
Heavy-duty fleet operators are unbundling hose replacement from scheduled maintenance contracts, creating spot-procurement channels through industrial distributors. Construction and agriculture machinery owners in the US Midwest now source hydraulic assemblies via same-day fulfillment networks rather than OEM captive parts programs. This disintermediation compresses margin structures for traditional integrated suppliers.
Fluid Transfer Solutions Market Segmentation
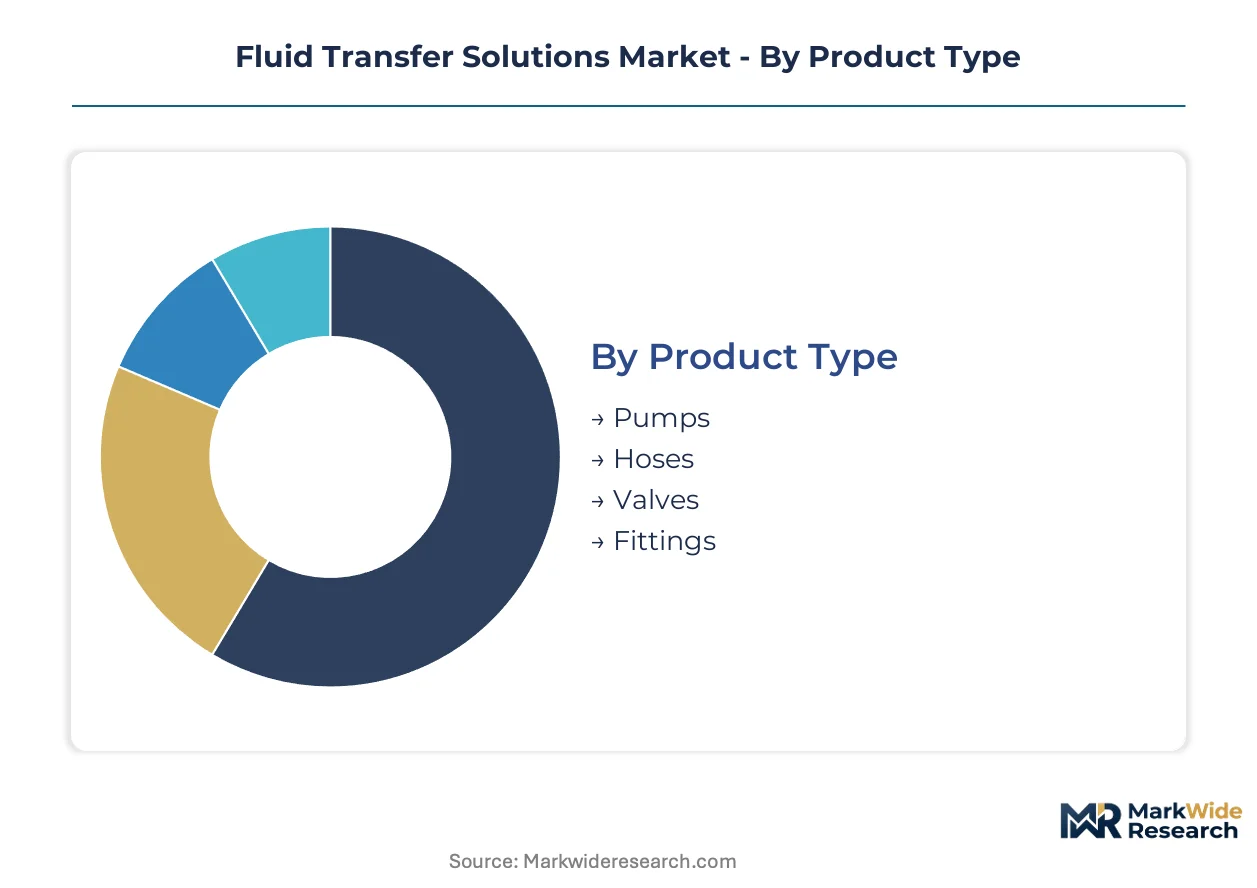
Fluid transfer solutions fragment across four intersecting dimensions that determine procurement patterns and margin structures. Product type and technology choices lock customers into specific maintenance ecosystems, while application and end-user splits dictate certification requirements and channel economics.
Product Type:
Metal tubing substitution pressures vary sharply by product category, with rigid architectures threatening polymer-based segments in high-temperature zones.
- Hoses:Elastomeric and thermoplastic constructions dominate mobile equipment and automotive fuel lines. Fleet replacement cycles concentrate demand in US Midwest heavy-duty corridors, though fluoropolymer feedstock volatility compresses margin predictability.
- Fittings:SAE J2044 quick-connect specifications are displacing legacy barbed designs across automotive fluid transfer, forcing extrusion line retooling and compressed validation timelines for suppliers serving Stuttgart-area OEMs.
- Pumps:Positive displacement and centrifugal architectures serve process industries with documented material traceability requirements.
- Valves:Directional and pressure-control configurations enable circuit modularity in hydraulic and pneumatic systems.
Hoses retain volume leadership; fittings hold the steepest expansion curve as quick-connect adoption accelerates.
Technology:
Cost tier stratification separates capital-intensive hydraulic infrastructure from lightweight pneumatic deployments in food-grade environments.
- Hydraulic:Power-dense fluid power systems serve construction and agriculture machinery with pressure ratings exceeding 350 bar. Construction equipment owners in the US Midwest now source hydraulic assemblies via same-day fulfillment networks rather than OEM captive parts programs.
- Pneumatic:Compressed air networks are expanding fastest in automated packaging lines across Brazil and Mexico, where food-grade material traceability requirements create premium tier openings.
- Electrical:Electromechanical actuation is displacing fluid power in precision positioning applications with lower force requirements.
- Mechanical:Direct-drive linkages retain cost advantages in simple motion control with minimal environmental sealing needs.
Hydraulic technology commands the largest installed base; pneumatic systems are climbing the fastest as clean compressed air infrastructure proliferates.
Application:
Customer type concentration varies by application maturity, with automotive OEMs driving standardization while marine and chemical sectors retain specification fragmentation.
- Automotive:Thermal management circuits for electrified powertrains are pulling advanced elastomer formulations into volume production. EU F-Gas Regulation leakage detection mandates are accelerating retrofit demand across Germany and France commercial cold-chain infrastructure.
- Industrial:Process fluid handling spans chemical transfer, cooling circuits, and lubrication systems with broad pressure class requirements.
- Chemical:Aggressive media compatibility demands fluoropolymer barrier layers with corrosion resistance certifications.
- Marine:Saltwater exposure and vibration tolerance specifications favor metallic substrates in high-reliability installations.
Automotive application retains volume leadership; industrial segments are gaining share fastest as manufacturing automation deepens fluid circuit density.
End User:
Channel power concentrates with distributors in fragmented contractor markets, while manufacturers retain direct procurement leverage at volume scale.
- Manufacturers:OEMs and tier suppliers specify fluid transfer architectures during platform development, locking in multi-year supply agreements.
- Distributors:Industrial supply houses capture spot procurement from unbundled fleet maintenance programs, compressing traditional integrated supplier margins.
- Contractors:Project-based fluid system installers source through distributor networks with limited brand loyalty.
- Service Providers:Maintenance and repair organizations prioritize inventory availability over specification optimization.
Manufacturers retain volume leadership; distributors are expanding fastest as procurement disintermediation reshapes channel economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers export high-pressure fluid handling components to North American hydrogen vehicle programs, while Chinese manufacturers feed electrified powertrain thermal management circuits into European OEM assembly plants.
United States
EPA enforcement of 40 CFR Part 1060 evaporative emission standards tightens permeation limits for fuel hoses. California Air Resources Board maintains parallel specifications that fragment certification timelines. Heavy-duty fleet operators in the US Midwest now source hydraulic assemblies via same-day fulfillment networks rather than OEM captive parts programs.
Germany
EU F-Gas Regulation leakage detection mandates accelerate retrofit demand across commercial cold-chain infrastructure. REACH restrictions on phthalate plasticizers force elastomer suppliers into costly reformulation cycles. Stuttgart-area OEMs have converted seventy percent of fuel line capacity to thermoplastic elastomer barrier layers since 2023.
China
Domestic hydrogen fuel cell vehicle production pulls orders for components rated above 700 bar. MIIT standards for electrified powertrain thermal management reshape supplier qualification protocols. Yangtze River Delta automotive clusters concentrate fluoropolymer hose assembly capacity for export markets.
India
Tamil Nadu and Gujarat automotive supplier corridors lack qualified domestic hose assembly capacity, creating import substitution openings. BIS certification requirements for automotive fluid transfer components lag European timelines by 18-24 months. Pune-based tier suppliers are retooling extrusion lines to serve electrified platform programs.
Japan
METI hydrogen roadmap targets 800,000 fuel cell vehicles by 2030, expanding procurement for high-pressure storage systems. JIS standards for quick-connect fittings diverge from SAE J2044 specifications, forcing dual-validation investments. Nagoya-area suppliers anchor thermal management circuit production for hybrid powertrains.
Fluid Transfer Solutions Market Vendor Landscape
Listed leaders compete with private specialists across materials science capabilities and regional certification depth. The vendor base fragments across three tiers: integrated conglomerates with captive polymerization, mid-scale specialists with SAE/ISO dual certification, and regional fabricators serving aftermarket spot demand. Dominant competitive moves include backward integration into fluoropolymer resin supply and geographic expansion into underpenetrated automotive corridors.
Within the integrated conglomerate tier, Parker Hannifin Corporation and Gates Corporation exemplify scale-driven positions anchored by materials science divisions. TI Fluid Systems occupies a specialist position focused on thermal management fluid circuits. Sumitomo Riko Company Limited represents Japanese-origin capabilities in vibration-dampening fluid architectures. These three names illustrate the competitive spectrum from diversified industrial conglomerates to focused automotive tier suppliers.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Sumitomo Riko Company Limited |
| Cooper Standard |
| Hutchinson |
| Kongsberg Automotive |
| TI Fluid Systems |
| Sanoh Industrial |
| Akwel |
| Gates Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for virgin PTFE resin lock in supply access for hose manufacturers while capping price visibility against fluoropolymer feedstock volatility. These arrangements concentrate procurement leverage among three chemical conglomerates, forcing tier suppliers into capacity-reservation commitments that compress margin flexibility.
Pricing Analysis
Prior-generation nitrile rubber hose assemblies trade at substantial discounts to current-generation thermoplastic elastomer barrier constructions, while next-generation nano-scale fluorinated formulations command premium tiers. Pricing stratifies across premium, standard, and economy tiers based on SAE J2044 certification status and fluoropolymer barrier layer complexity. Cost compression in standard-grade segments is intensifying because heavy-duty fleet operators have unbundled replacement procurement from scheduled maintenance contracts. Distributors serving spot-demand channels exhibit highest price sensitivity; OEMs with multi-year platform agreements demonstrate lowest sensitivity due to specification lock-in during development.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for fluoropolymer resin shipments. Manufacturing concentrates in Germany, China, and the United States, with Yangtze River Delta clusters feeding export markets. Raw material dependencies center on virgin PTFE resin, specialized plasticizer compounds, and high-purity aluminum for thermal management circuits. Single-source vulnerability pervades fluoropolymer feedstock supply. Distribution runs through industrial supply houses capturing disintermediated fleet maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen fuel cell vehicle proliferation constitutes a high-growth disruption, with METI targets and EU F-Gas leakage mandates creating simultaneous inflections across high-pressure and refrigeration transfer segments.
For Market Incumbents: Secure backward integration into fluoropolymer resin supply to defend against feedstock concentration risk among three chemical conglomerates. Anchor capacity expansion in Stuttgart-area corridors to capture thermal management circuit demand from electrified powertrain programs. Prioritize SAE J2044 dual-certification investments to exploit California-EPA regulatory divergence. For New Entrants and Emerging Players: Same-day fulfillment service gaps in US Midwest hydraulic assembly channels present white-space targets where incumbent integrated suppliers under-serve disintermediated fleet operators. Tamil Nadu and Gujarat automotive corridors offer the most penetrable geography given qualified domestic hose assembly scarcity. Pursue food-grade pneumatic network certification in Brazil and Mexico as the go-to-market angle. For Investors and Strategic Acquirers: Mid-scale specialists with SAE/ISO dual certification and captive polymerization capabilities represent the priority acquisition archetype. Long-term viability hinges on exposure to hydrogen storage and electrified thermal management growth vectors. Monitor SAE J2044 certification lab queue lengths as the signal indicating supply constraint inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | Captive PTFE supply insulates margin structures from three-conglomerate feedstock concentration. |
| SAE J2044 Dual-Certification Investment | Parallel EPA and CARB validation captures fragmented North American inventory requirements. |
| Tamil Nadu Assembly Capacity Buildout | Domestic qualification addresses import substitution demand in India's automotive corridors. |
| Food-Grade Pneumatic Network Certification | Documented material traceability opens premium tiers in Brazil and Mexico packaging automation. |
| Hydrogen Storage System Partnership | 700-bar component qualification secures platform positioning with fuel cell vehicle OEMs. |
Methodological Framework
Desk research of customs trade data, SEC filings from industrial conglomerates, and SAE technical standards preceded structured interviews with tier supplier procurement directors, OEM platform engineers, aftermarket distribution heads, and fluoropolymer compounder technical directors. Primary fieldwork across Germany, China, and the United States validated secondary findings through plant-level observation and inventory pattern analysis. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Variance decomposition across product type, technology, application, and end-user dimensions anchored the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit trends across the modeling period. Industry-specific forecast inputs incorporated hydrogen vehicle production schedules, EU F-Gas retrofit penetration curves, and heavy-duty fleet maintenance contract unbundling rates.
Forecasts assume regulatory continuity in EPA 40 CFR Part 1060 enforcement, EU F-Gas leakage detection mandates, and REACH phthalate restrictions; material policy shifts would require re-modeling. Commodity price volatility in fluoropolymer feedstocks and misaligned California-EPA phase-in timelines present specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
China Explosion-Proof Equipment Market
Valves
Global Marine Actuators and Valves Market
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Fin Tube Market
Valves
Christmas Tree Valves Market
Valves
Valve Remote Control System Market
Valves
Choke and Kill Manifold Market
Valves
Industrial Valves Market
Valves
Global Industrial Thermostatic Control Valves Market
Valves
Global Pipeline Safety Market
Valves
Blow - Off Valves Market
Valves
HVAC Valves Market
Valves
Harmonic Dampers Market
Valves
Industrial Valves and Actuators Market
Valves
North America Valves Market
Valves
Orifice Reducers Market