
 Subsea Multiphase Flowmeter Market | 2026-2036
Subsea Multiphase Flowmeter Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Multiphase Flowmeter Market Analytics
Multi-source procurement for subsea instrumentation is recalibrating how offshore engineering firms manage supplier risk and capital deployment. Baker Hughes Company leverages its integrated turbomachinery portfolio to bundle flowmeter sales with subsea production systems. TechnipFMC plc anchors its metering offerings within larger subsea tree and manifold packages, controlling project specification from the front end. Schlumberger Limited competes through reservoir characterization integration, positioning multiphase meters as data nodes within digital oilfield architectures.
A subsea multiphase flowmeter measures oil, gas, and water flow rates simultaneously at seabed wellheads without prior separation, typically operating at pressures exceeding 10,000 psi and depths beyond 3,000 meters to optimize reservoir management and production allocation. Compact flowmeters dominate brownfield retrofit demand where deck space and installation vessel capacity constrain equipment footprint, while ultrasonic technology leads greenfield specifications due to its non-intrusive measurement path and reduced maintenance exposure in corrosive high-salinity environments. Differential pressure flowmeters retain share in heavy-oil applications where density contrast between phases simplifies signal interpretation.
The US Bureau of Safety and Environmental Enforcement mandates subsea flow measurement for allocation and leak detection in federal offshore leases, while Norway's Petroleum Safety Authority enforces functional safety standards that shape meter redundancy and verification protocols. Brazil's national petroleum regulator requires local content thresholds that influence manufacturing location decisions for projects in the pre-salt province. Operators and meter suppliers must monitor how electrification mandates and methane intensity targets rewrite specification criteria before the next investment cycle locks in platform architecture.
Market Dynamics
Subsea processing electrification is compressing hydraulic umbilical demand while expanding power-over-fiber telemetry requirements for seabed instrumentation. This shift forces flowmeter suppliers to redesign electronics packages for all-electric subsea architectures.
Growth Catalysts
- Pre-salt development mandates:Brazil's national petroleum regulator enforces local content thresholds that accelerate domestic manufacturing partnerships for deepwater metering systems.
- Wet-gas algorithm maturation:Advances in gamma-ray spectroscopy and neural-net signal processing eliminate separator vessel requirements, shrinking field development footprints.
- North Sea electrification push:Norway's Petroleum Safety Authority mandates functional safety redundancies that drive redundant multiphase meter installations on subsea tiebacks.
Market Restraints
- Titanium alloy supply concentration:Pressure housing fabrication depends on sponge titanium from a concentrated supplier base, exposing lead times to raw material volatility.
- Deepwater installation vessel scarcity:Heavy-lift capacity for subsea tree and manifold deployment constrains project scheduling flexibility in Brazil and West Africa.
- Heavy-oil measurement limitations:High-viscosity crudes degrade ultrasonic signal propagation, forcing retention of intrusive differential pressure alternatives with higher maintenance exposure.
Strategic Opportunities
- Retrofit brownfield instrumentation:Aging North Sea infrastructure requires compact meter replacements where deck space and crane capacity limit equipment dimensions.
- Methane intensity compliance:The US Inflation Reduction Act imposes emissions fees that incentivize real-time flow monitoring for leak detection and venting quantification.
- Fiber-optic sensing convergence:Distributed acoustic sensing integration with multiphase meters enables pipeline surveillance and flow assurance from a single seabed node.
Industry Challenges
- Subsea electronics reliability engineering:Pressure-compensated housing design and thermal management at 3,000-meter depths strain specialized talent pools.
- API 17F certification timelines:Subsea production equipment qualification protocols extend product development cycles and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Multiphase Flowmeter Market |
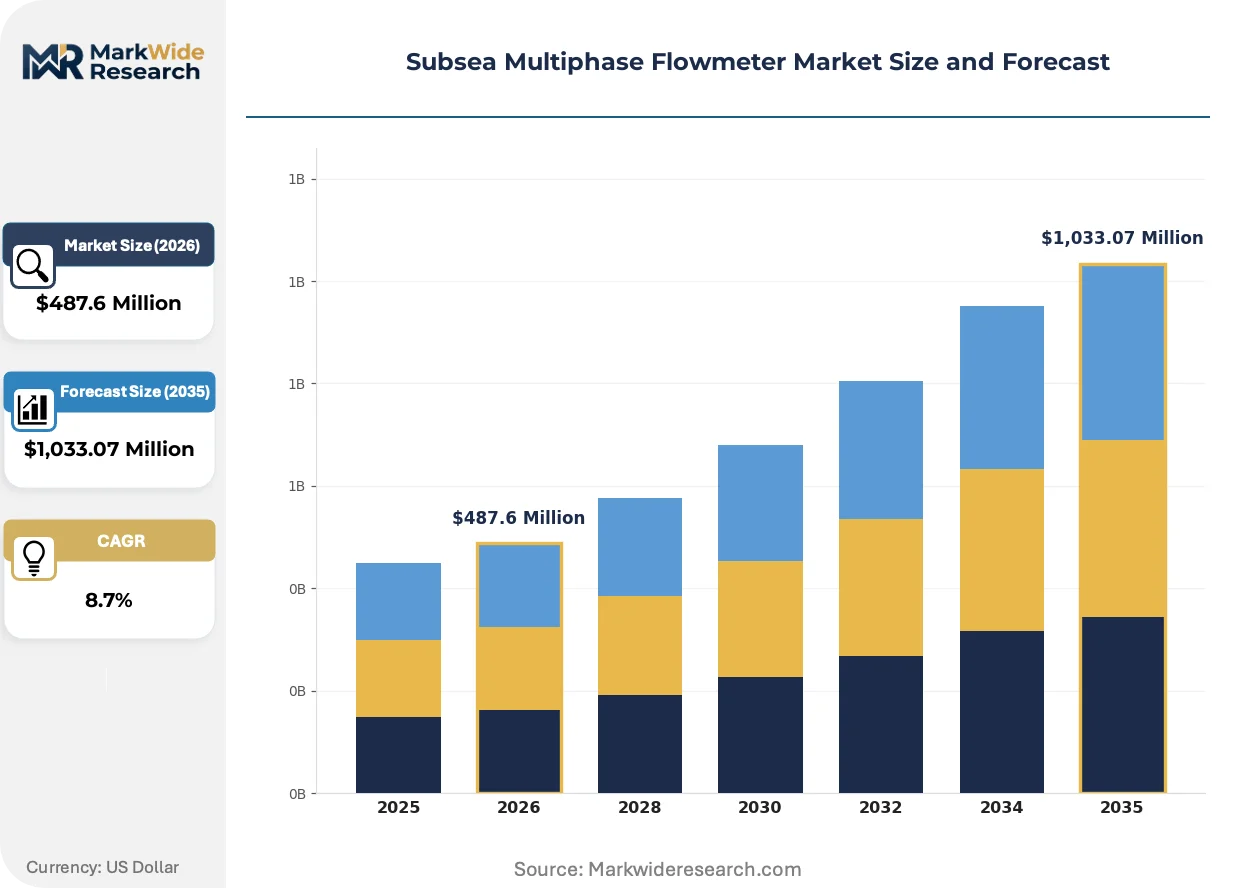
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Flowmeters, Differential Pressure Flowmeters, Coriolis Flowmeters, Electrical Resistance Flowmeters Technology: Ultrasonic Technology, Magnetic Technology, Optical Technology, Thermal Technology Application: Oil Production, Gas Measurement, Water Injection, Chemical Injection End User: Oil & Gas Operators, Offshore Contractors, Engineering Services, Research Institutions |
| Companies Covered | Baker Hughes Company, TechnipFMC plc, Schlumberger Limited, Haimo Technologies Group Corp, Siemens AG, Emerson Electric Co., Weatherford International Ltd., Pietro Fiorentini S.p.a., ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Multiphase Flowmeter Market Evolving Landscape
Measurement instrumentation is migrating from passive monitoring devices to active data nodes within digital reservoir management systems. This evolution demands embedded edge computing and subsea power distribution compatibility.
All-electric subsea actuator technology is electrifying control system architectures across greenfield developments. Equinor and Aker BP specify fully electric trees and manifolds in Norway's Johan Sverdrup and Breidablikk fields. This transition compresses hydraulic fluid inventory requirements while expanding demand for high-voltage wet-mate connectors and power conditioning electronics.
The US Bureau of Safety and Environmental Enforcement mandates subsea flow measurement for allocation and leak detection in federal offshore leases. Operators must install certified meters on all new wellheads in the Gulf of Mexico. Deepwater projects in the Mississippi Canyon and Green Canyon protraction areas now specify redundant ultrasonic flowmeters to satisfy verification protocols.
Integrated service contracting is consolidating procurement decisions for subsea production packages. Engineering firms now specify flowmeters within bundled subsea tree and manifold awards rather than standalone instrument purchases. This pattern concentrates in Norway's North Sea cluster and Brazil's pre-salt province, where integrated project delivery models dominate capital allocation.
Subsea Multiphase Flowmeter Market Segmentation
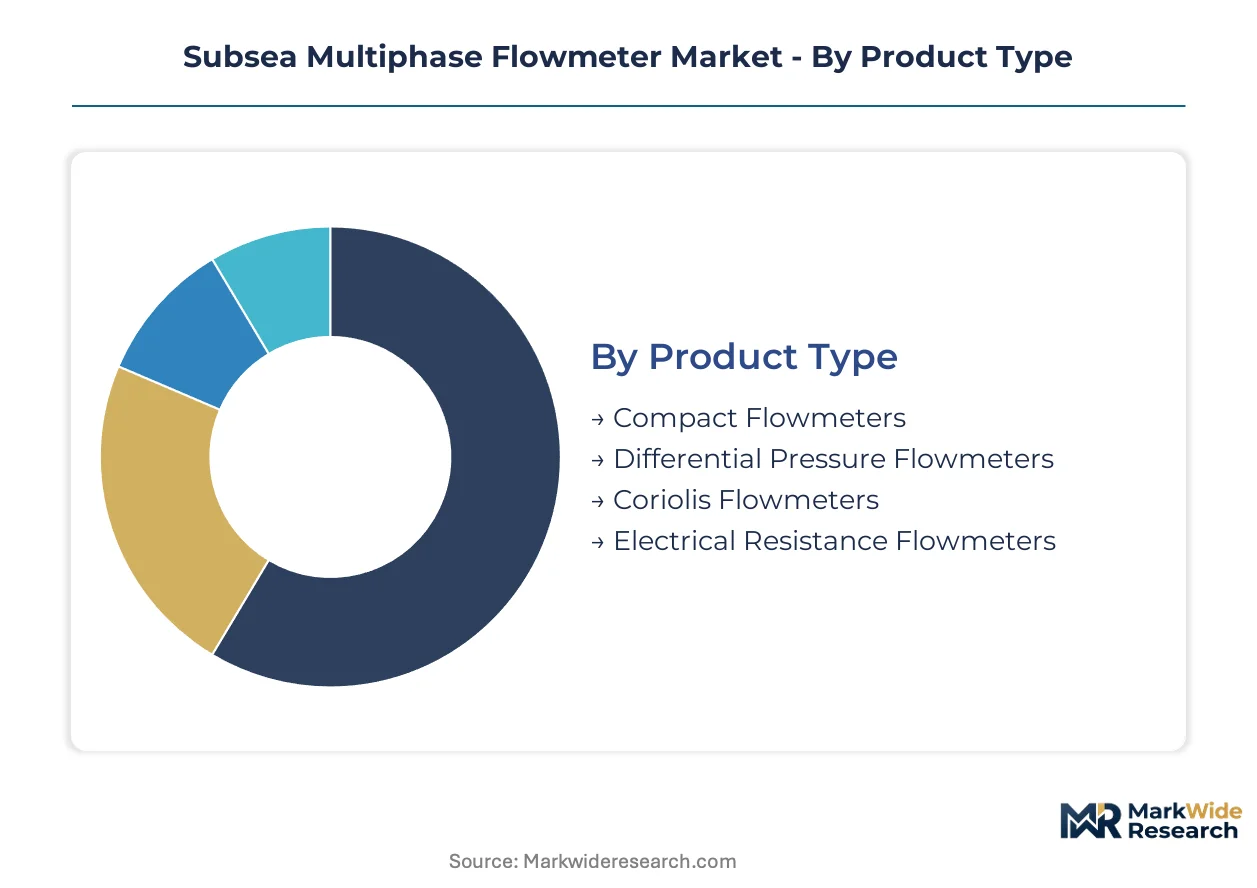
Subsea multiphase flowmeter procurement splits between standalone instrument sales and embedded subsystem bundles, reshaping how suppliers configure electronics packages and service architectures. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization pressures intensify.
Product Type:
Compact flowmeters operate as discrete retrofit units for brownfield installations where deck space constraints dominate specification, while differential pressure and Coriolis variants embed within integrated subsea production systems requiring deeper vendor integration.
- Compact Flowmeters:These units minimize footprint through stacked sensor arrays and pressure-compensated housings rated beyond 10,000 psi. Demand clusters in Norway's North Sea brownfield retrofits where aging platforms lack crane capacity for larger equipment, driven by Equinor and Aker BP's all-electric conversion programs.
- Differential Pressure Flowmeters:Intrusive venturi and orifice designs exploit density contrast between oil, gas, and water phases for signal interpretation. Brazil's pre-salt heavy-oil developments retain these units where high-viscosity crudes degrade alternative measurement modalities, constrained by ANVISA local content mandates on pressure housing fabrication.
- Coriolis Flowmeters:Vibrating tube designs deliver direct mass flow measurement with immunity to multiphase slip effects.
- Electrical Resistance Flowmeters:Impedance-based water-cut detection complements primary velocity sensors in hybrid architectures.
Volume placements concentrate in compact flowmeters; the faster expansion belongs to Coriolis designs as all-electric subsea processing demands higher measurement fidelity.
Technology:
Technology selection tracks the divergence between intrusive mechanical sensors and non-intrusive electromagnetic or acoustic paths, with cost tiers separating legacy installations from next-generation seabed nodes.
- Ultrasonic Technology:Transit-time and Doppler methods eliminate wetted components through clamp-on or spool-piece transducer arrangements. Gulf of Mexico greenfield specifications from the US Bureau of Safety and Environmental Enforcement favor these units for reduced maintenance exposure in corrosive high-salinity environments.
- Magnetic Technology:Electromagnetic flow measurement requires continuous fluid conductivity above threshold levels, limiting deployment to water-dominated production streams.
- Optical Technology:Near-infrared and laser-based phase discrimination enables real-time composition analysis without nuclear sources.
- Thermal Technology:Heat-pulse anemometry addresses niche applications in low-flow gas-condensate systems.
Procurement volumes skew toward ultrasonic paths; optical methods are climbing the fastest as fiber-optic sensing convergence enables distributed pipeline surveillance.
Application:
Application segmentation reflects the upstream workflow sequence from reservoir extraction through secondary recovery and chemical management, with each stage imposing distinct accuracy and redundancy requirements.
- Oil Production:Wellhead allocation metering demands custody-transfer accuracy for joint-venture revenue distribution. West African deepwater projects in Angola and Nigeria deploy redundant multiphase meters on subsea tiebacks to satisfy production sharing contract audit protocols.
- Gas Measurement:Wet-gas quantification at elevated gas volume fractions challenges conventional separation-based methods. Wet-gas algorithm maturation in the North Sea eliminates separator vessel requirements, shrinking Johan Sverdrup field development footprints.
- Water Injection:Seawater and produced water reinjection monitoring focuses on volumetric throughput rather than phase discrimination.
- Chemical Injection:Scale inhibitor and hydrate suppressant dosing verification requires compact inline sensors at manifold distribution points.
Revenue concentration sits with oil production allocation; gas measurement applications are expanding most quickly as pre-salt gas-cap developments proliferate.
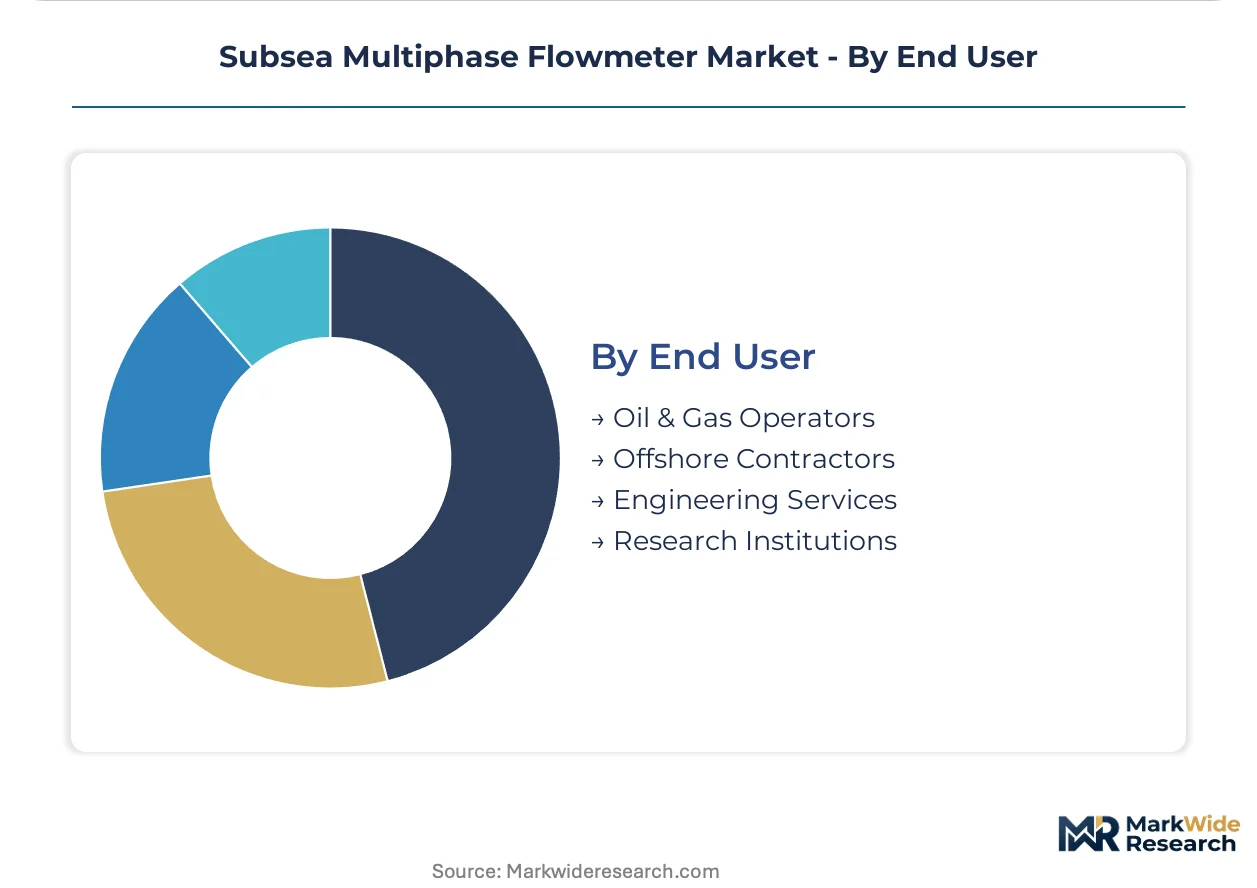
End User:
End-user categories span asset ownership, construction execution, design engineering, and research validation, with procurement authority shifting toward integrated service contractors in major capital projects.
- Oil & Gas Operators:Equinor, Petrobras, and supermajors specify meter performance standards within field development plans. Norway's Petroleum Safety Authority functional safety mandates drive redundant installations on all subsea tiebacks, with operators retaining final certification authority.
- Offshore Contractors:Subsea installation firms bundle flowmeter procurement within tree and manifold construction contracts. Integrated project delivery models in Brazil's pre-salt province concentrate procurement decisions with TechnipFMC and similar integrated service providers.
- Engineering Services:Front-end engineering and design contractors influence meter specification during conceptual field architecture selection.
- Research Institutions:Universities and national laboratories validate multiphase flow correlations for regulatory acceptance.
Contracting authority is concentrating with offshore contractors; research institution engagement is gaining share fastest as digital twin validation requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater field operators in Brazil, Norway, and the United States concentrate procurement authority for subsea multiphase flowmeters. Brazil's pre-salt province, Norway's North Sea electrification push, and US Gulf of Mexico regulatory mandates shape regional demand patterns. Local content requirements and functional safety standards fragment specification criteria across these three dominant markets.
Brazil
Petrobras drives pre-salt development with subsea tieback economics improving across the Santos Basin. ANVISA enforces local content thresholds that accelerate domestic manufacturing partnerships for pressure housing fabrication. The Rio de Janeiro industrial cluster hosts assembly operations serving deepwater projects in the Búzios and Mero fields.
Norway
Equinor and Aker BP mandate all-electric subsea processing architectures across Johan Sverdrup and Breidablikk developments. The Petroleum Safety Authority enforces functional safety redundancies that drive dual multiphase meter installations on subsea tiebacks. Stavanger anchors the North Sea supplier ecosystem where integrated service contracting concentrates procurement decisions.
United States
Gulf of Mexico deepwater projects in Mississippi Canyon and Green Canyon specify redundant ultrasonic flowmeters for new wellhead installations. The Bureau of Safety and Environmental Enforcement mandates subsea flow measurement for allocation and leak detection across federal offshore leases. Houston hosts the primary engineering and procurement hub serving US offshore operators.
United Kingdom
North Sea brownfield retrofits demand compact flowmeter replacements where aging platforms lack crane capacity for larger equipment. The Health and Safety Executive shapes verification protocols for subsea production equipment qualification. Aberdeen maintains its position as the central service hub for UK continental shelf developments.
Angola
West African deepwater projects deploy redundant multiphase meters on subsea tiebacks to satisfy production sharing contract audit protocols. The national petroleum regulator influences local content requirements for offshore service procurement. The Luanda supply base supports installation campaigns across Block 15 and Block 17 developments.
Subsea Multiphase Flowmeter Market Competitive Landscape
Integrated service contracting dominates the current landscape as engineering firms bundle flowmeter procurement within subsea tree and manifold awards. The vendor base splits between diversified energy technology conglomerates and specialized subsea instrumentation houses. Three archetypes define competitive positioning: integrated production system suppliers, standalone measurement specialists, and industrial automation multinationals. Portfolio diversification and strategic partnerships represent the dominant competitive moves as suppliers reposition for all-electric subsea architectures.
Among diversified energy technology providers, Baker Hughes Company, TechnipFMC plc, and Schlumberger Limited occupy positions spanning turbomachinery, subsea production systems, and reservoir characterization integration. These entities exemplify the integrated service model where flowmeter sales anchor within larger capital equipment packages. Their geographic footprints and project execution capabilities represent the scale threshold required for pre-salt and North Sea developments.
| Leading Market Players |
|---|
| Baker Hughes Company |
| TechnipFMC plc |
| Schlumberger Limited |
| Haimo Technologies Group Corp |
| Siemens AG |
| Emerson Electric Co. |
| Weatherford International Ltd. |
| Pietro Fiorentini S.p.a. |
| ABB Ltd. |
| Others |
Value Network & Pricing Analysis
All-electric subsea actuator migration is compressing hydraulic umbilical demand while expanding power-over-fiber telemetry requirements, simultaneously elevating electronics packaging costs and concentrating procurement leverage with integrated service contractors in Norway and Brazil. This technology shift forces meter suppliers to absorb redesign expenses for high-voltage wet-mate compatibility while buyers bundle instruments within larger subsea tree awards.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers offering 10-year subsea electronics reliability guarantees from unbundled economy alternatives where operators assume refurbishment risk. Three-tier pricing structure across premium, standard, and economy levels tracks API 17F certification status and local content compliance in Brazil. Cost compression in economy tiers is intensifying because integrated project delivery models concentrate volume with bundled subsystem providers. Offshore contractors exhibit highest price sensitivity due to fixed-lump-sum construction contracts, while national oil companies prioritize functional safety redundancy over unit cost.
Supply Chain Analysis
Reverse-logistics flows for pressure-compensated housing refurbishment and sensor recalibration anchor aftermarket revenue streams for suppliers maintaining regional service hubs in Stavanger, Rio de Janeiro, and Houston. Titanium sponge supply concentrates in Japan, Russia, and China, with pressure housing fabrication drawing from specialized aerospace-forging capacity. Single-source vulnerability pervades high-voltage wet-mate connector supply, where qualified subsea-rated suppliers number fewer than five globally. Distribution runs through integrated service contractors rather than standalone instrument channels, compressing direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deepwater installation vessel scarcity constrains project scheduling flexibility across Brazil and West Africa, propping pricing power for qualified meter suppliers with confirmed manufacturing slots.
For Market Incumbents: To counter emerging optical technology entrants displacing ultrasonic paths in wet-gas applications, Baker Hughes and TechnipFMC should deepen backward integration into fiber-optic sensing components while accelerating API 17F certification timelines for all-electric architectures. Capacity addition in Norway's Stavanger cluster addresses the specialized talent bottleneck for pressure-compensated housing design. For New Entrants and Emerging Players: The price-point gap between premium integrated packages and economy retrofit units opens white-space targeting North Sea brownfield operators with compact meter replacements. Focus on UK continental shelf aging platforms lacking crane capacity, deploying direct sales teams in Aberdeen rather than channeling through integrated contractors. For Investors and Strategic Acquirers: Re-rating potential sits with specialized subsea instrumentation houses possessing fiber-optic sensing IP given electrification mandate acceleration by Norway's Petroleum Safety Authority. Long-term viability over the coming decade favors targets with proven 3,000-meter depth qualification records. Monitor ANVISA local content threshold adjustments as inflection indicator for Brazilian manufacturing partnership valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber-Optic Components | Captures margin from power-over-fiber telemetry expansion in Equinor's all-electric fields. |
| API 17F Certification Acceleration | Compresses product development cycles to match Norway's Johan Sverdrup electrification timeline. |
| Brazil Local Content Partnership | Satisfies ANVISA thresholds for pressure housing fabrication in Búzios and Mero developments. |
| Brownfield Retrofit Service Hub | Positions compact meter offerings for UK North Sea platforms with crane capacity constraints. |
| Wet-Gas Algorithm Licensing | Monetizes neural-net signal processing advances eliminating separator vessel requirements. |
Research Methodology
Independent corroboration across subsea engineering directors at integrated service contractors, procurement leads at Petrobras and Equinor, and regulatory affairs specialists at Norway's Petroleum Safety Authority underwrites the qualitative findings. Secondary validation drew from Bureau of Safety and Environmental Enforcement federal lease filings, ANVISA local content compliance records, and API 17F certification databases. Bottom-up project pipeline enumeration triangulates against top-down expenditure forecasts from national oil company capital allocation disclosures.
Historical reference periods spanning pre-salt development acceleration and North Sea electrification commissioning anchored the forecast window across the projection horizon. Segmentation modeling incorporated product type, technology path, application workflow, and end-user procurement authority dimensions. CAGRs were derived from weighted project sanction probabilities and meter-per-wellhead penetration assumptions, with wet-gas algorithm maturation and fiber-optic sensing convergence as primary demand elasticity inputs.
Inputs from operator engineering teams and regulatory filing repositories were available through the study window; gaps in real-time subsea electronics failure rate data introduce uncertainty bands around reliability-guarantee pricing assumptions. Forecasts reflect documented assumptions regarding vessel availability and titanium alloy supply continuity. Practitioners should monitor deepwater installation vessel charter rate movements and ANVISA local content rule revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
Malaysia Oil and Gas Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
North America Proppants Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
North America Oil Storage Market
Oil & Gas
Geothermal Drilling Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Middle-East and Africa Pigging Services Market