
 Orifice Reducers Market | 2026-2036
Orifice Reducers Market Size, Share, and Industry Trends Forecast 2026-2036
Orifice Reducers Market Analytics
EU REACH chemical safety mandates and FDA material compatibility standards for pharmaceutical packaging are consolidating procurement specifications across the orifice reducers supply base. Berry Global Inc. leverages its multi-material extrusion platform to serve regulated pharmaceutical accounts with validated polymer formulations. West Pharmaceutical Services anchors its position through integrated elastomer science and drug delivery system design. Amcor Limited competes via global manufacturing scale and healthcare packaging certification depth.
An orifice reducer is a precision-engineered insert that restricts opening diameter to control flow rate, drip formation, or dispensing volume, typically manufactured from medical-grade thermoplastics, fluoropolymers, or stainless steel with tolerances of ±0.05 mm. The component seals into bottle necks or vial openings via interference fit, threaded engagement, or snap-lock geometry to ensure repeatable fluid discharge in pharmaceutical, chemical, and laboratory applications. Plastic orifice reducers lead volume demand due to cost efficiency and moldability for complex geometries, while metal variants command premium positioning in high-pressure and corrosive media environments. Flow measurement applications represent the fastest-growing segment as process industries deploy smart metering infrastructure requiring calibrated restriction elements.
FDA enforces material biocompatibility and extractables testing under USP Class VI protocols for pharmaceutical-contact components, while EPA regulates chemical emissions from polymer manufacturing processes affecting domestic production economics. EMA's Medical Device Regulation and ISO 10993 standards in Europe impose additional conformity assessment burdens on suppliers seeking dual-market access. Stakeholders must monitor evolving pharmacopeial standards and regional polymer recycling mandates to anticipate specification shifts and qualification timelines.
Market Dynamics
Precision dispensing requirements in pharmaceutical manufacturing are compressing tolerance specifications and forcing material qualification cycles that reshape supplier economics across the orifice reducers value chain.
Growth Catalysts
- USP Class VI biocompatibility mandates:FDA material safety protocols for pharmaceutical-contact components drive validated polymer formulations into standard procurement specifications.
- Smart metering infrastructure deployment:Process industries integrate calibrated restriction elements into flow measurement systems requiring precision-engineered inserts.
- Germany's industrial corridor concentration:Pharmaceutical packaging manufacturers cluster procurement decisions around REACH-compliant elastomer science capabilities.
Market Restraints
- Fluoropolymer feedstock volatility:PTFE and FEP resin prices fluctuate with semiconductor sector demand cycles, compressing margin buffers for medical-grade component producers.
- EMA MDR conformity assessment burdens:Extended qualification timelines for dual-market access delay revenue recognition for suppliers seeking European and United States pharmaceutical accounts simultaneously.
- Metal-to-plastic substitution ceiling:High-pressure corrosive media applications in Texas Gulf Coast petrochemical operations retain stainless steel specifications despite polymer cost advantages.
Strategic Opportunities
- India CDSCO pharmaceutical packaging expansion:Domestic formulation manufacturing growth creates demand for controlled dispensing components with localized material certification pathways.
- ISO 10993-5 cytotoxicity testing convergence:Harmonized biocompatibility standards reduce duplicate qualification costs for suppliers serving multiple regulated markets.
- Closed-loop polymer recycling mandates:EU Green Deal circular economy requirements position recycled-content medical thermoplastics as differentiated supply options.
Industry Challenges
- Multi-material extrusion technician scarcity:Precision orifice reducer manufacturing requires specialized mold flow analysis skills concentrated among aging workforce cohorts in established industrial regions.
- Extractables validation timeline compression:Pharmaceutical sponsors demand accelerated USP <661.1> container closure qualification without compromising analytical rigor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orifice Reducers Market |
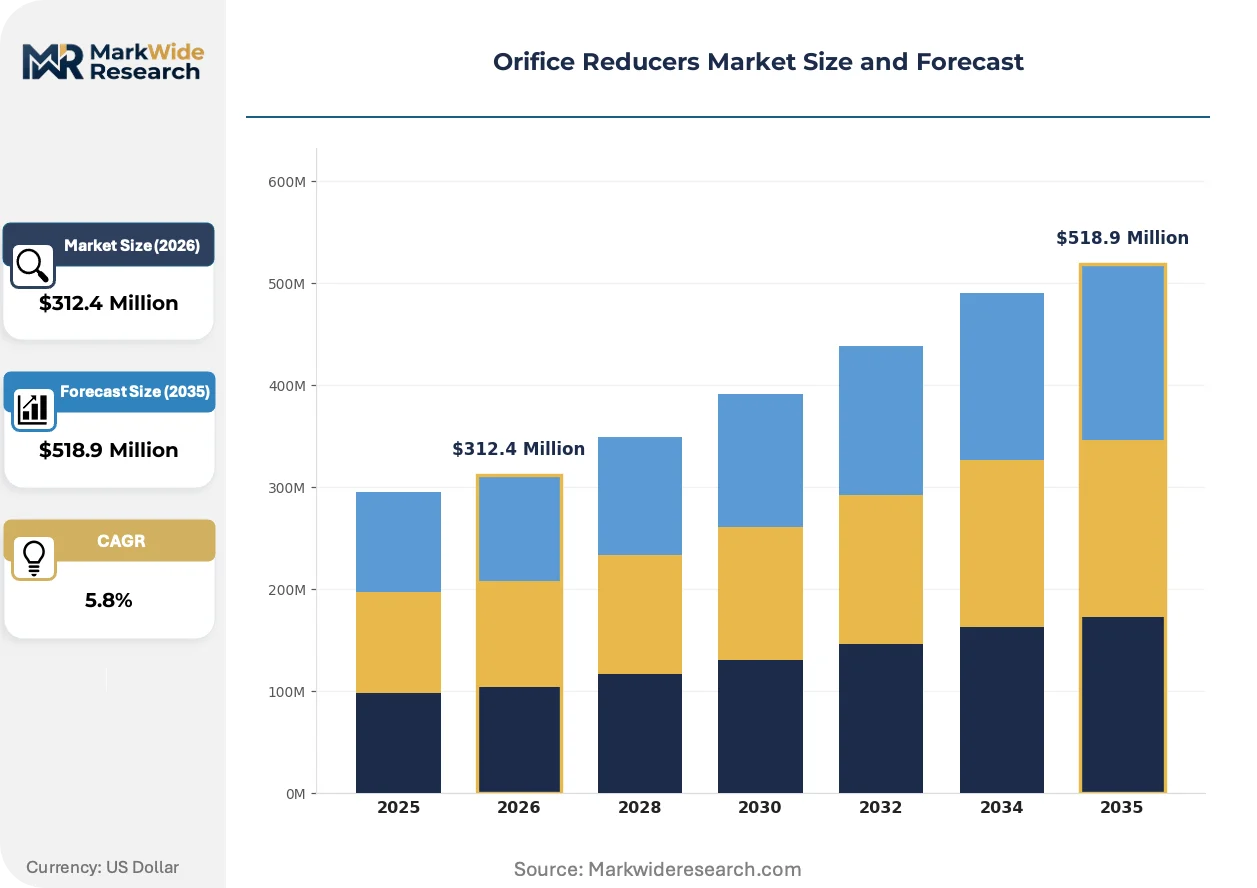
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, Plastic, Composite, Rubber Application: Fluid Control, Gas Control, Pressure Regulation, Flow Measurement Installation: Inline, Side Entry, Flanged, Threaded End User: Manufacturing, Oil & Gas, Water Treatment, Chemical Processing |
| Companies Covered | Amcor Limited, Berry Global Inc., Comar LLC, Plastipro Canada Ltd., Acme Vial & Glass, Berlin Packaging, O.Berk Company, SKS Bottle & Packaging, West Pharmaceutical Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orifice Reducers Market Evolving Landscape
Material science advances and regulatory harmonization pressures are converging to redefine performance benchmarks and supplier qualification protocols across precision dispensing component categories.
Multi-cavity micro-molding with hot runner systems is overtaking conventional cold runner tooling for complex geometry orifice reducers. Pharmaceutical packaging contract manufacturers in Switzerland and Singapore adopt these platforms to achieve ±0.03 mm repeatability on 0.5 mm wall sections. The technology is overtaking established suppliers lacking capital deployment capacity for tool refurbishment cycles.
REACH Annex XVII restricted substance updates tighten phthalate and heavy metal thresholds for polymer additives used in pharmaceutical-contact applications. European compounders reformulate masterbatch compositions to maintain ECHA compliance without sacrificing elastomer compression set performance. German and French pharmaceutical packaging specialists now require full material disclosure documentation upstream of component qualification.
Consolidated supplier qualification programs are compressing approved vendor lists at major pharmaceutical packaging integrators. Direct material specification authority shifts from component distributors to end-use manufacturing quality departments. This concentration is most visible among United States-based contract packaging organizations serving generic drug manufacturers with high-volume standardized dispensing formats.
Orifice Reducers Market Segmentation
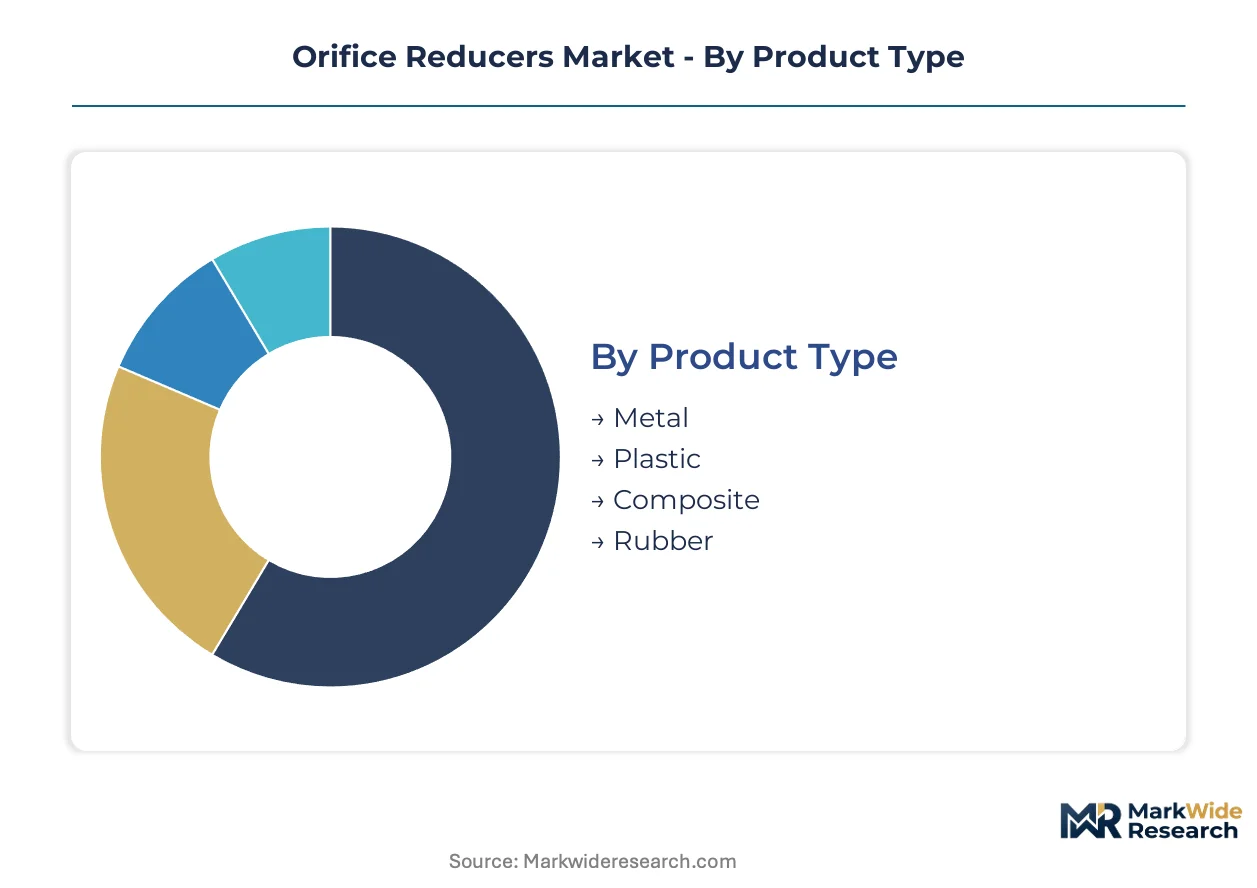
Orifice reducer procurement splits across material performance tiers, precision requirements, and regulatory exposure levels. Specification authority increasingly resides with end-user quality departments rather than distributor intermediaries.
Product Type:
Standardization dominates high-volume pharmaceutical runs, while precision metal variants command premium positioning in corrosive process environments.
- Metal:Stainless steel and exotic alloy constructions withstand extreme pressures and aggressive chemical media. Demand clusters in Texas Gulf Coast petrochemical operations where fluoropolymer alternatives fail under thermal cycling.
- Plastic:Medical-grade thermoplastics and fluoropolymers deliver cost efficiency at ±0.05 mm tolerances for pharmaceutical dispensing. Germany's industrial corridor drives procurement concentration around REACH-compliant polymer formulations.
- Composite:Hybrid metal-polymer structures balance chemical resistance with weight reduction for aerospace fluid systems.
- Rubber:Elastomeric inserts provide compression sealing in laboratory glassware with interference-fit geometries.
Most installed capacity flows through Plastic. Expansion is steepest in Metal.
Application:
Functional requirements determine tolerance specifications and material qualification burdens across process industries.
- Fluid Control:Pharmaceutical manufacturing demands drip-free dispensing with validated extractables profiles under USP Class VI protocols.
- Gas Control:Precision orifice sizing manages pneumatic system pressure drops in automated production lines.
- Pressure Regulation:Calibrated restriction elements protect downstream equipment from surge events in chemical processing trains.
- Flow Measurement:Smart metering infrastructure deployment drives specification for instrument-grade orifice plates with traceable calibration certificates.
Flow Measurement commands the steepest expansion trajectory as utilities modernize distribution monitoring.
Installation:
Mounting geometry dictates seal reliability and field serviceability in high-cycling process environments.
- Inline:Straight-through configurations dominate pipeline integration with welded or compression sleeve attachment.
- Side Entry:Lateral access points enable instrument tapping without flow interruption in critical process lines.
- Flanged:Bolted connections facilitate rapid exchange during maintenance windows in chemical processing facilities.
- Threaded:NPT and BSP fittings serve lower-pressure laboratory and pilot-scale applications with hand-tight assembly.
Threaded variants dominate unit volume. Flanged configurations capture value concentration in heavy industry.
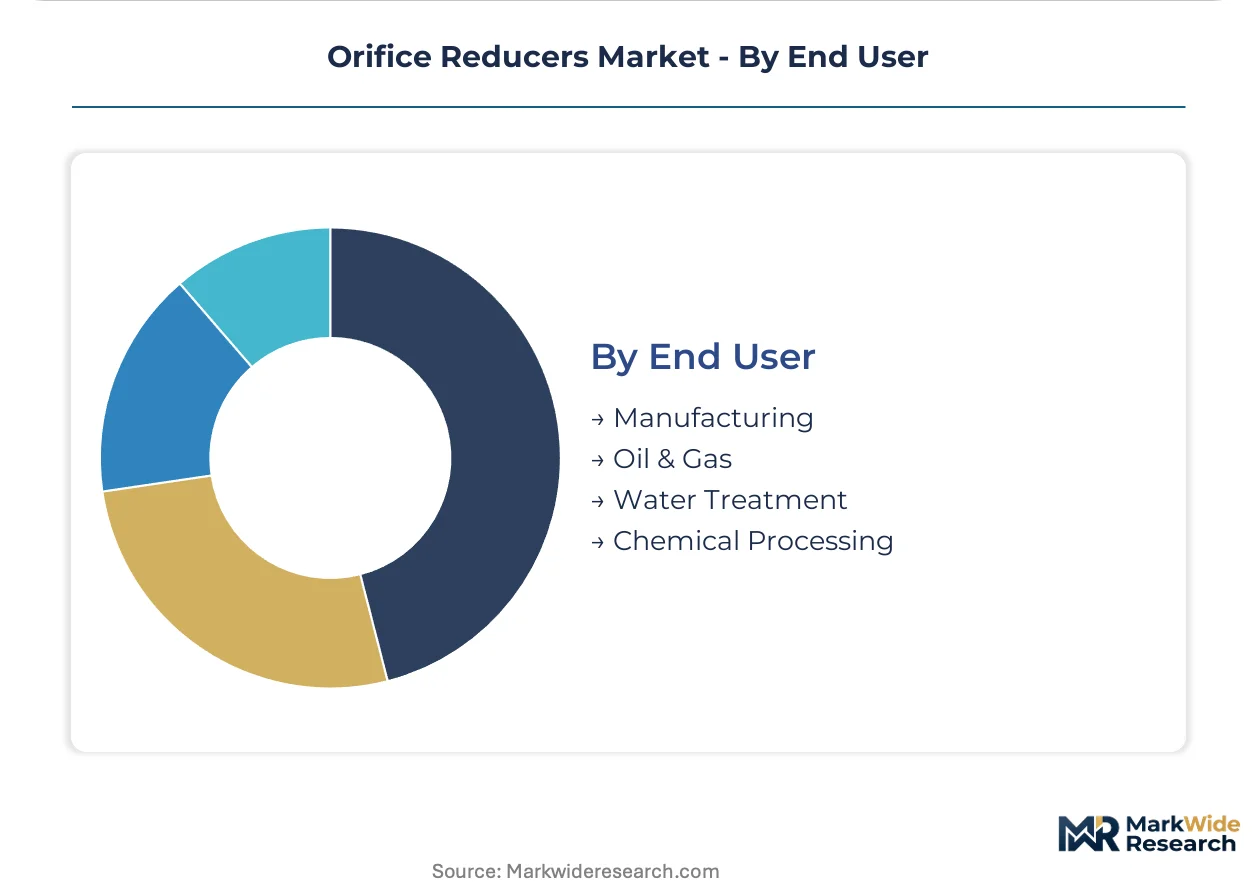
End User:
Industry-specific regulatory exposure shapes material documentation requirements and supplier qualification intensity.
- Manufacturing:Pharmaceutical and medical device producers enforce USP <661.1> container closure integrity standards with full material disclosure.
- Oil & Gas:Upstream and midstream operators specify corrosion-resistant alloys for sour service environments under API standards.
- Water Treatment:Municipal and industrial utilities deploy calibrated restriction elements for flow balancing in distribution networks.
- Chemical Processing:Batch and continuous producers demand elastomer compatibility with aggressive solvents under EPA emissions constraints.
Manufacturing leads specification intensity. Chemical Processing presents the steepest volume expansion as specialty chemical capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer compounding technicians concentrate in Germany's industrial corridor and along the Texas Gulf Coast, anchoring precision orifice reducer manufacturing capacity for pharmaceutical and petrochemical end-users.
United States
FDA USP Class VI biocompatibility protocols and EPA emissions regulations on polymer manufacturing reshape domestic procurement specifications. Texas Gulf Coast petrochemical operations sustain stainless steel orifice reducer demand for high-pressure sour service environments where fluoropolymer alternatives degrade under thermal cycling.
Germany
EMA Medical Device Regulation conformity assessments and REACH Annex XVII restricted substance updates tighten material disclosure requirements for pharmaceutical-contact components. The Rhine-Ruhr industrial corridor hosts compounders reformulating masterbatch compositions to maintain ECHA compliance without sacrificing elastomer compression set performance.
India
CDSCO pharmaceutical packaging regulations and domestic formulation manufacturing expansion create demand for controlled dispensing components with localized material certification pathways. Maharashtra and Gujarat pharmaceutical clusters drive procurement of precision orifice reducers for export-oriented generic drug packaging operations.
Switzerland
Swissmedic medical device standards and ISO 10993 biocompatibility harmonization reduce duplicate qualification costs for suppliers serving European and United States markets simultaneously. Basel-region pharmaceutical packaging specialists require full material disclosure documentation upstream of component qualification.
China
NMPA pharmaceutical packaging material registrations and GB standards for medical-grade polymers compress supplier qualification timelines for domestic and export markets. Yangtze River Delta contract manufacturers adopt multi-cavity micro-molding platforms to achieve sub-0.05 mm tolerances for complex geometry orifice reducers.
Orifice Reducers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the orifice reducers value chain. The supplier base stratifies between integrated packaging conglomerates with captive polymer science capabilities and specialized component fabricators serving niche regulatory segments. Three archetypes dominate: multi-material extrusion platforms with validated pharmaceutical formulations, precision metal machining specialists for corrosive process environments, and regional molders with localized certification pathways. Consolidation accelerates through approved vendor list compression at major pharmaceutical packaging integrators, while capacity expansion concentrates in Switzerland and Singapore for high-repeatability micro-molding platforms.
Among integrated packaging conglomerates, Amcor Limited and Berry Global Inc. exemplify the scale-driven archetype with global manufacturing footprints and healthcare certification depth. West Pharmaceutical Services occupies a distinct position anchored in elastomer science and drug delivery system integration. These three entities represent the tier where direct material specification authority has shifted from distributor intermediaries to end-use manufacturing quality departments.
| Leading Market Players |
|---|
| Amcor Limited |
| Berry Global Inc. |
| Comar LLC |
| Plastipro Canada Ltd. |
| Acme Vial & Glass |
| Berlin Packaging |
| O.Berk Company |
| SKS Bottle & Packaging |
| West Pharmaceutical Services |
| Others |
Value Network & Pricing Analysis
EU Green Deal circular economy requirements gate both qualified supply and premium-tier pricing access, as pharmaceutical packaging buyers demand recycled-content medical thermoplastics with full ECHA traceability documentation. Manufacturers lacking validated polymer recycling pathways face exclusion from approved vendor lists at major European contract packaging organizations.
Pricing Analysis
Component-plus-certification bundling separates quoted prices from base material costs. Three-tier pricing structure across USP Class VI-validated, REACH-compliant, and uncertified economy levels reflects qualification burden differentials. Price differentiation hinges on extractables testing depth and FDA master file status. Cost compression in standard plastic tiers is intensifying because Indian and Chinese molders are expanding ISO 10993-certified capacity. Generic drug manufacturers in Gujarat and Maharashtra exhibit the highest price sensitivity, while Swiss and German innovator pharma accounts prioritize specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from FDA-regulated pharmaceutical sponsors mandate qualified backup suppliers for all critical dispensing components. Feedstock concentration in Germany, Switzerland, and the Texas Gulf Coast anchors precision orifice reducer manufacturing for regulated end-users. Supply chains draw from medical-grade thermoplastic resin, fluoropolymer compounding, and precision mold tooling. Single-source vulnerability persists in multi-cavity micro-molding hot runner systems, where Swiss and Singaporean equipment suppliers dominate. Distribution runs through pharmaceutical packaging integrators with captive quality departments rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as pharmaceutical sponsors shift procurement authority toward manufacturing quality departments demanding validated extractables profiles. Premium specification tiers capture disproportionate margin expansion.
For Market Incumbents: To counter approved vendor list compression at major pharmaceutical packaging integrators, deepen backward integration into polymer compounding to secure REACH-compliant formulation control. Expand micro-molding capacity in Switzerland or Singapore to capture ±0.03 mm tolerance demand from innovator drug manufacturers. Certification investment in ISO 10993-5 cytotoxicity testing convergence reduces duplicate qualification costs across dual-market access. For New Entrants and Emerging Players: Begin with CDSCO-compliant material certification pathways for India's Maharashtra and Gujarat pharmaceutical clusters, where domestic formulation manufacturing growth outpaces local precision component supply. Target flow measurement applications for smart metering infrastructure as the most penetrable segment, with instrument-grade calibration certificate capabilities as the specific go-to-market angle. White-space exists in recycled-content medical thermoplastics meeting EU Green Deal mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among regional molders with localized certification pathways but lacking multi-material extrusion platforms. Long-term viability over a five-to-ten-year window favors targets with validated pharmaceutical formulations and captive elastomer science capabilities. The signal to watch is EMA MDR conformity assessment timeline compression, which would accelerate revenue recognition for dual-qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH Annex XVII compliance secures formulation control for pharmaceutical-contact applications. |
| Multi-Cavity Micro-Molding Capacity Expansion | Swiss and Singaporean platforms achieve ±0.03 mm repeatability for complex geometry orifice reducers. |
| ISO 10993-5 Cytotoxicity Testing Investment | Harmonized biocompatibility standards reduce duplicate qualification costs across EMA and FDA jurisdictions. |
| Recycled-Content Medical Thermoplastic Development | EU Green Deal circular economy requirements position sustainable materials as differentiated supply options. |
| CDSCO Localized Certification Pathway Establishment | Maharashtra and Gujarat pharmaceutical clusters demand domestic controlled dispensing component supply. |
Research Methodology
Multiple input streams — primary interviews with pharmaceutical packaging procurement directors, regulatory affairs specialists, and precision molding plant managers; secondary validation through FDA 510(k) filings, EMA Medical Device Regulation submissions, and customs trade data; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Conversations with quality department heads at contract packaging organizations and elastomer science directors at integrated packaging conglomerates informed specification trend assessments. SEC 10-K disclosures from listed packaging companies and ISO certification databases provided secondary anchor points.
Data-stream reconciliation across material type, application function, installation geometry, and end-user regulatory exposure dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit trends. Forecast inputs included USP <661.1> container closure qualification timelines, REACH Annex XVII restricted substance update schedules, and smart metering infrastructure deployment curves from utility capital expenditure disclosures.
Caveats apply where EMA MDR conformity assessment delays, fluoropolymer feedstock volatility from semiconductor sector demand cycles, or polymer recycling mandate acceleration could materially shift the outlook. Deviation in pharmaceutical sponsor procurement centralization toward manufacturing quality departments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Control Valves Market
Valves
Valve Remote Control System Market
Valves
Explosion Isolation Valves Market
Valves
Liner Regulators Market
Valves
Tubing Heads Market
Valves
Pipeline Pigging Equipment Market
Valves
Chemical Injection Metering Pumps and Valves Market
Valves
Emergency Shutdown Valves Market
Valves
APAC Valves Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Pressure Gauge Market
Valves
Fluid Power Cylinder Market
Valves
Vacuum Insulated Pipe Market
Valves
One-Way Valve Market
Valves
Total Containment Vessels Market
Valves
Asia Pacific Pipeline Maintenance Market