
 Industrial Valves Market | 2026-2036
Industrial Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Valves Market Intelligence
The US EPA's stringent fugitive emissions standards are rebalancing the competitive landscape by increasing the cost of compliance for lower-tier manufacturers. Emerson leverages its extensive automation and control technology portfolio to offer integrated solutions meeting these new standards. Flowserve sustains its market position through specialization in severe service applications for the petrochemical industry. Meanwhile, KSB Group differentiates with highly engineered pumps and valves for the water treatment and power generation sectors.
Industrial valves are mechanical devices engineered to control, regulate, or direct the flow and pressure of fluids within a piping system. Their construction from materials like carbon steel or specialized alloys ensures they meet critical pressure and temperature ratings. While ball and gate valves constitute a large portion of the market, butterfly valves are specified for larger-diameter applications. The power generation and water treatment sectors increasingly favor electric actuation over manual methods for enhanced automation.
Compliance with Europe's CE marking and China's GB standards is essential for market access in those key regions. The ISO 9001 quality management framework provides a baseline for manufacturing process integrity across the supply chain. End-users must decide whether to prioritize the lower upfront cost of standard components or invest in intelligent valves that offer superior lifecycle performance and diagnostic capabilities.
Market Dynamics
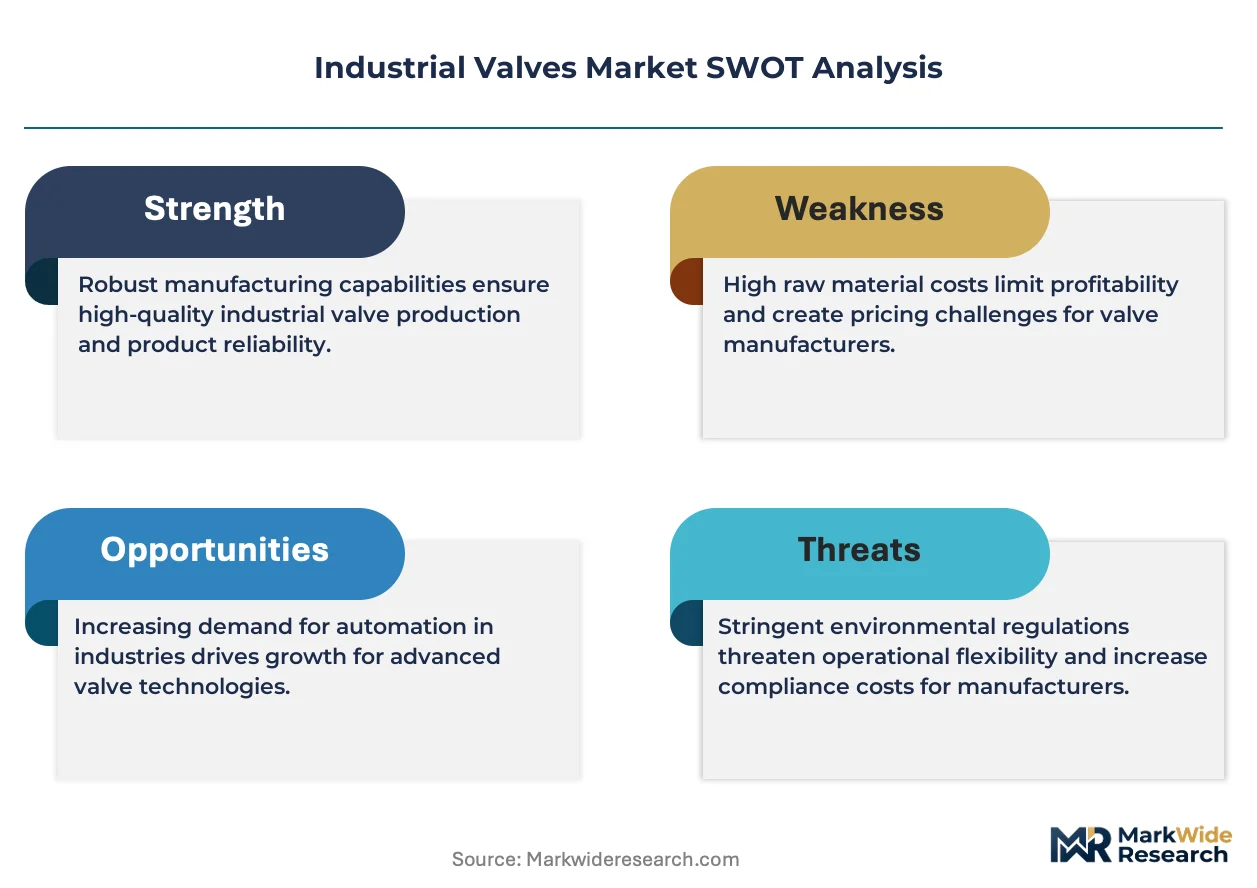
The industrial valves market is defined by a structural push towards higher performance and intelligence. Stringent environmental mandates, including the US EPA's fugitive emissions standards and the EU's F-Gas Regulation, are compelling end-users to invest in advanced sealing technologies and automated control systems.
Growth Catalysts
- Petrochemical Expansion:New project investment in the petrochemical sector, with significant concentration in China and the Middle East, sustains demand for high-specification, severe-service valves designed for corrosive and high-pressure environments.
- Regulatory Mandates:The EU's F-Gas Regulation directly influences material selection and valve design, creating demand for units with certified low leakage rates to handle specific refrigerants and industrial gases.
- Automation in Utilities:The power generation and water treatment sectors are accelerating the replacement of manual valves with electrically actuated units to enable remote operation, improve process control, and integrate with plant-wide automation networks.
Market Restraints
- Input Cost Volatility:Price fluctuations in key raw materials, particularly specialized alloys containing nickel, chromium, and molybdenum required for corrosion-resistant valves, create margin pressure and complicate project bidding for manufacturers.
- Casting Supply Concentration:A dependency on a limited number of large-scale foundries, primarily located in Asia, for producing large-diameter steel castings creates supply chain vulnerabilities and potential lead time extensions for major projects.
- Technical Substitution:In certain low-pressure, non-critical applications, the use of variable frequency drives (VFDs) on pumps to control flow can reduce or eliminate the need for dedicated control valves, representing a substitution threat.
Strategic Opportunities
- Intelligent Valve Systems:Integrating valves with IoT sensors, diagnostic software, and predictive analytics offers a significant opportunity to provide outcome-based services focused on asset health monitoring, predictive maintenance, and optimizing lifecycle performance.
- Hydrogen Economy Infrastructure:The global build-out of hydrogen production, storage, and transport infrastructure creates a new market for highly engineered valves capable of handling cryogenic temperatures and high-pressure gaseous hydrogen safely.
- Low-Emission Certifications:Stricter environmental regulations like the US EPA's fugitive emissions rules create a premium market for valves certified to API 624 and ISO 15848 standards, allowing manufacturers to differentiate on performance.
Industry Challenges
- Specialized Skills Gap:A persistent shortage of technicians with the combined mechanical and digital skills needed to install, commission, and service sophisticated intelligent valve systems and their associated control networks presents an operational challenge.
- Legacy System Integration:Integrating modern, digitally enabled valves and actuators with older, legacy Distributed Control Systems (DCS) in existing industrial plants can be complex and costly, slowing adoption in brownfield sites.
- Complex Certification Pathways:Navigating the multiple, region-specific certification requirements, such as CE marking in Europe, GB standards in China, and various API standards, adds significant time and expense to product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Valves Market |
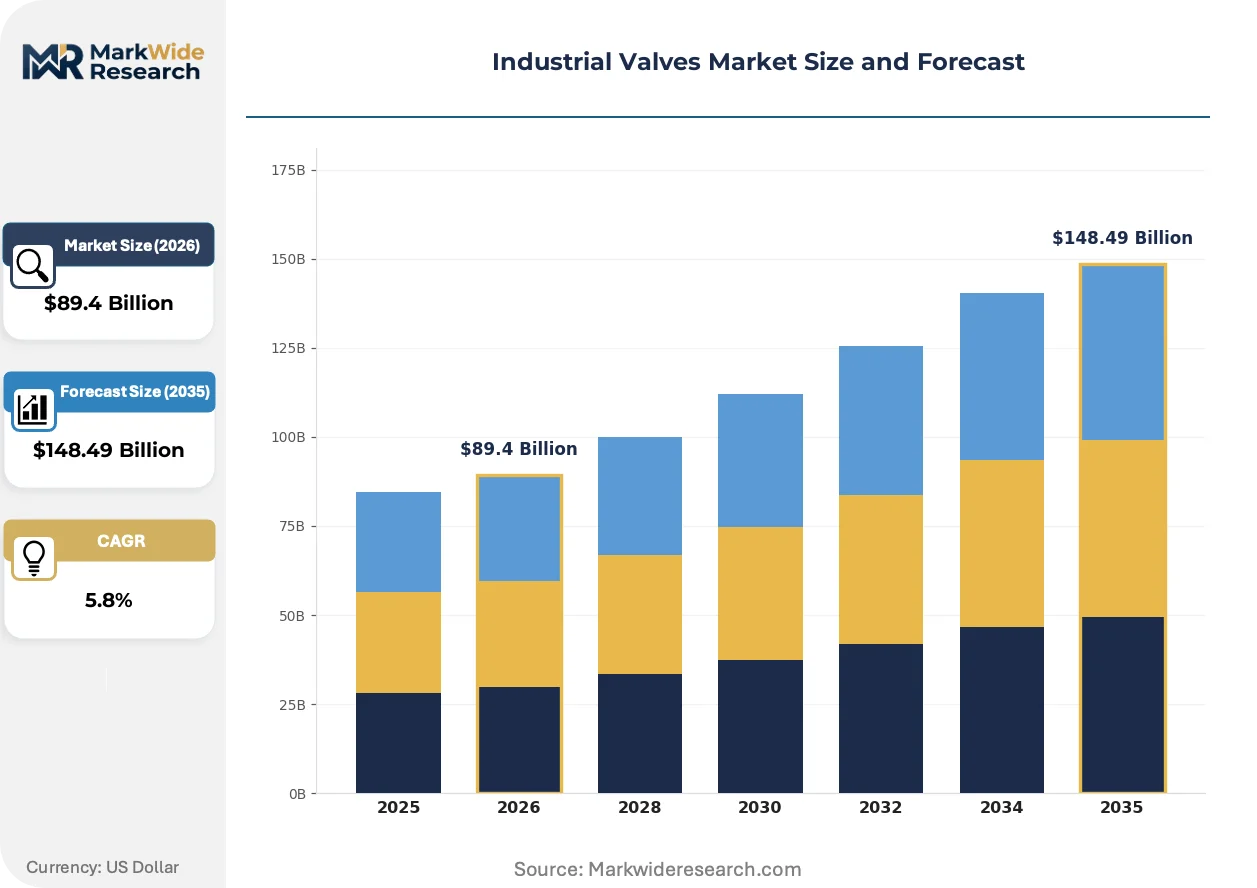
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $148.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Valve Type: Gate, Globe, Ball, Butterfly, Diaphragm, Needle Actuation Method: Manual, Pneumatic, Electric, Hydraulic, Solenoid End User Industry: Petrochemical, Power Generation, Water Treatment, Mining, Food Processing Connection Type: Flanged, Threaded, Welded, Socket Weld, Compression |
| Companies Covered | KSB Group, KITZ Corporation, Emerson, Neway Valve, Spirax Sarco, Flowserve, Velan Inc., Schlumberger, Crane Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Valves Market Strategic Shifts & Innovations
The evolution from standalone mechanical components to integrated, data-generating assets is actively reshaping the market. This shift is driven by demands for tighter process control, verifiable emissions reduction, and enhanced operational visibility across complex industrial facilities, favoring intelligent and highly engineered solutions.
Intelligent valves incorporate embedded sensors and microprocessors to perform self-diagnostics and transmit real-time operational data. The chemical processing and oil and gas industries are leading adopters, seeking to improve plant safety, reduce unplanned downtime, and optimize maintenance schedules. This technology is converging with plant-wide automation platforms, transforming valves from passive flow controllers into active, intelligent nodes within a broader digital industrial ecosystem.
Europe's F-Gas Regulation sets firm limits on the use of certain fluorinated greenhouse gases, impacting the refrigeration and HVAC industries. This rule directly compels the use of valves with superior sealing integrity to prevent leakage of controlled substances. The segment most affected is commercial refrigeration, which is responding by specifying valves with certified low-leakage performance and materials compatible with alternative, low-GWP refrigerants.
A significant behavioral shift sees sophisticated end-users prioritizing total cost of ownership and lifecycle performance over initial unit cost. This trend diminishes the appeal of standard commodity valves in critical process lines, creating preference for engineered solutions that offer documented reliability and lower long-term maintenance. This procurement mindset is most prominent in the North American power generation and European pharmaceutical sectors, where process integrity and uptime are non-negotiable.
Industrial Valves Market Segmentation
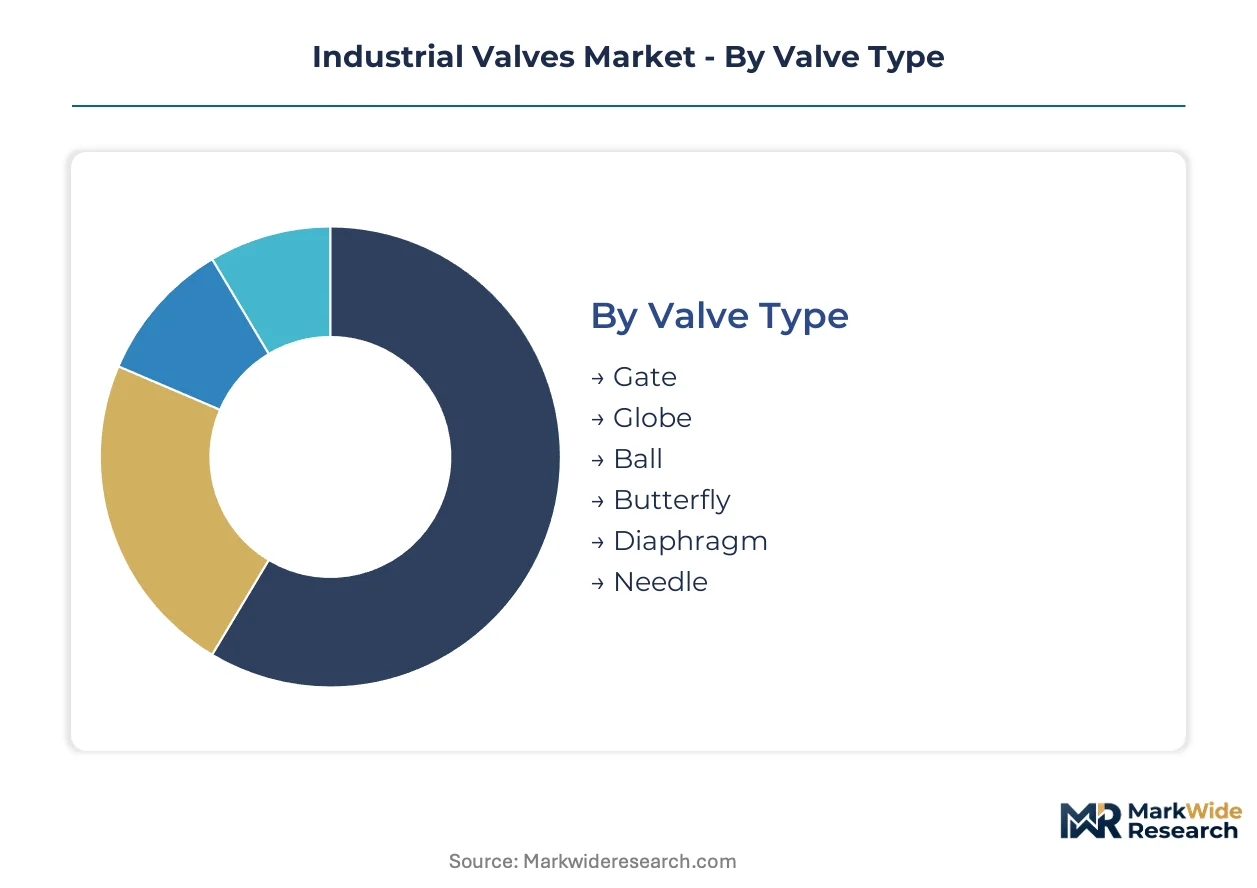
The industrial valves market segments across diverse parameters, reflecting the specialized requirements of various applications and end-user industries. Understanding these distinctions is critical for manufacturers to align product development with specific performance needs and regulatory landscapes.
Valve Type:
Valve types are subject to rigorous certification pathways, with specific designs requiring adherence to standards like API 624 or ISO 15848 for fugitive emissions compliance.
- Ball:These valves offer excellent shut-off capabilities, using a rotating ball to control fluid flow. The oil and gas industries heavily specify ball valves for their tight sealing and quick quarter-turn operation in high-pressure lines.
- Butterfly:Featuring a rotating disc to regulate flow, butterfly valves are suitable for larger diameter pipelines. Power generation facilities increasingly adopt these for their compact design and efficient flow control in cooling water systems.
- Gate:Gate valves provide full flow with minimal pressure drop, primarily used for on/off service in water distribution networks.
- Globe:Designed for throttling and flow regulation, globe valves are commonly found in steam and condensate systems within industrial plants.
- Diaphragm:These valves offer a leak-tight seal, often employed in sterile applications within the pharmaceutical and food processing sectors.
- Needle:Needle valves provide precise flow control for low flow rates, essential for instrumentation and sampling systems in chemical analysis.
Leading the category by volume: Ball. Growing fastest: Butterfly.
Actuation Method:
The choice of actuation method directly impacts operational efficiency and integration with plant-wide automation networks, influencing capital expenditure decisions.
- Electric:Electric actuators utilize motors for precise control and remote operation, enabling seamless integration with Distributed Control Systems. The water treatment sector increasingly favors these for automated filtration backwash cycles.
- Manual:Manual actuators rely on human intervention via handwheels or levers for valve manipulation, offering simplicity and low upfront cost. Smaller industrial facilities continue to employ manual valves due to their reliability in basic on/off functions.
- Pneumatic:These actuators operate using compressed air, providing fast response times for emergency shut-off systems in petrochemical plants.
- Hydraulic:Hydraulic actuators employ pressurized fluid for high-force applications, commonly used in heavy industrial machinery and large-bore pipeline control.
- Solenoid:Solenoid valves are electrically controlled and open or close rapidly, critical for safety interlocks and precise dosing in chemical processing.
This segment sees significant investment in Electric units for enhanced automation. Manual methods remain prevalent for cost-sensitive applications.
End User Industry:
Demand across end-user industries is shaped by distinct operational requirements, process fluid characteristics, and regulatory compliance mandates.
- Petrochemical:This sector requires high-performance valves capable of handling corrosive media and extreme temperatures under stringent safety protocols. New project investments in China and the Middle East sustain demand for severe-service units.
- Power Generation:This industry employs valves for steam, water, and fuel management within thermal and nuclear plants, prioritizing reliability and automation. North American power utilities increasingly adopt intelligent valves for predictive maintenance.
- Water Treatment:This sector specifies corrosion-resistant valves for municipal and industrial water processing, focusing on durability and remote control.
- Mining:Mining operations demand robust valves to withstand abrasive slurries and harsh environmental conditions in mineral extraction.
- Food Processing:This industry utilizes hygienic valves with sanitary designs, ensuring product integrity and compliance with strict food safety regulations.
The Petrochemical sector drives high-specification valve procurement. Power Generation facilities are increasingly integrating advanced automation.
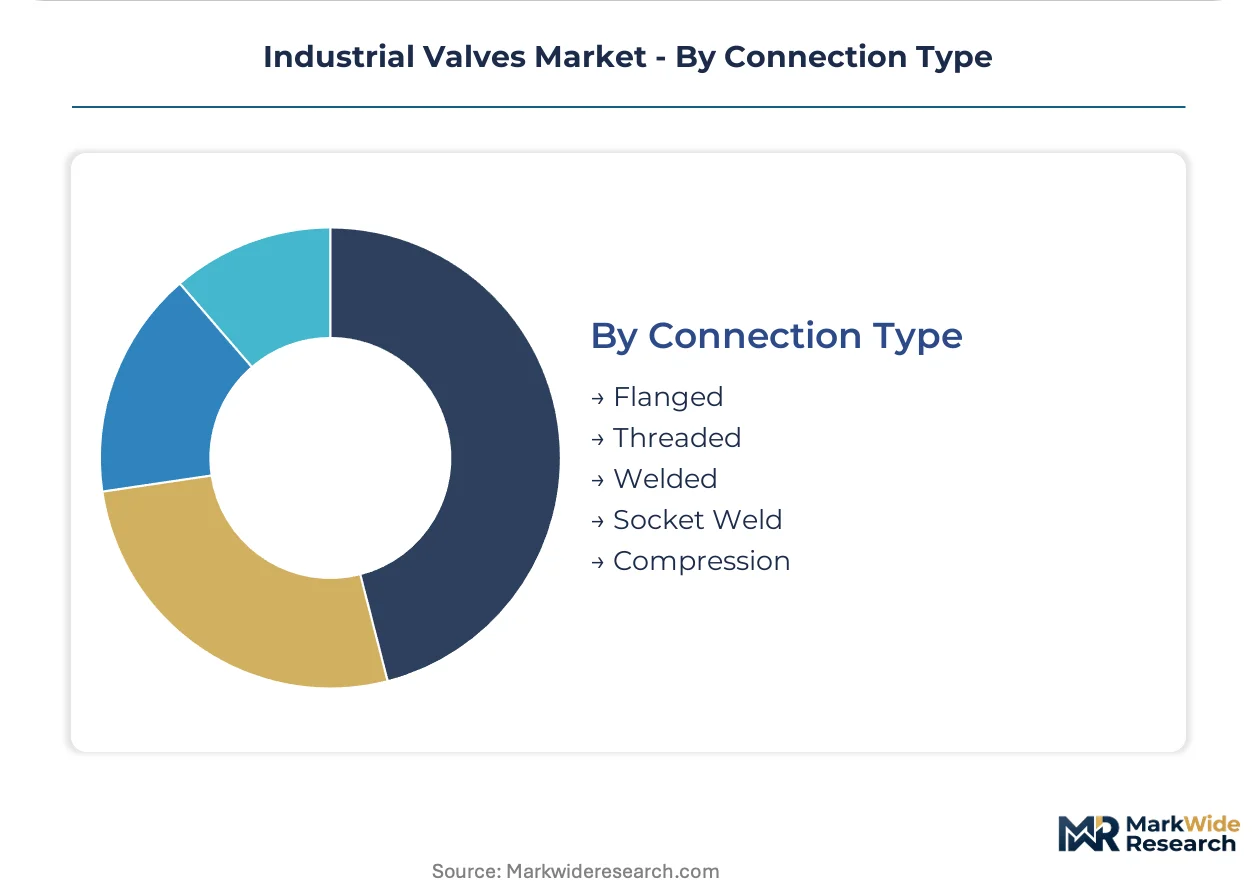
Connection Type:
The selection of connection type is determined by pressure ratings, fluid characteristics, and maintenance accessibility, impacting installation complexity and long-term integrity.
- Flanged:Flanged connections involve bolting two pipe ends together with a gasket, offering ease of assembly and disassembly for maintenance. These are widely used across chemical processing and water treatment sectors for their robust, standardized connections.
- Welded:Welded connections provide permanent, leak-tight joints, essential for high-pressure and high-temperature applications where absolute sealing is critical. The oil and gas industry frequently specifies welded connections for critical process lines to minimize fugitive emissions.
- Threaded:Threaded connections offer a simple, cost-effective option for smaller diameter pipes and lower pressure systems in general utilities.
- Socket Weld:Socket weld connections create a strong, leak-resistant joint for small-bore piping, commonly found in instrumentation and auxiliary lines.
- Compression:Compression connections utilize a ferrule to create a seal without welding or threading, preferred for quick installation in pneumatic and hydraulic systems.
Welded connections are critical for high-integrity systems. Flanged connections offer flexibility for maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for industrial valves is particularly pronounced in rapidly industrializing economies. China's sustained infrastructure development and significant petrochemical investments create substantial procurement volume. This regional dynamic shapes global supply chains and product specification requirements for advanced valve technologies.
China
China's industrial expansion, particularly in petrochemicals, drives significant demand for high-specification industrial valves. The country's GB standards ensure product quality and safety for domestic market access. Major industrial clusters in the Yangtze River Delta continue to expand, requiring advanced flow control solutions for new facilities.
United States
United States demand for industrial valves stems from its established oil and gas infrastructure and power generation sector. The US EPA's stringent fugitive emissions standards compel investment in certified low-leakage valve designs. Texas and Louisiana, with their extensive petrochemical and refining operations, remain critical hubs for high-performance valve procurement.
Germany
Germany’s industrial valve market benefits from strong activity in water treatment and power generation sectors. Compliance with the EU's F-Gas Regulation influences material and design choices for specific applications within Europe. The Rhine-Ruhr region, a dense industrial heartland, sees continuous demand for highly engineered flow control systems.
Saudi Arabia
Saudi Arabia's ambitious new project investments in the petrochemical sector generate substantial procurement for severe-service industrial valves. The country's focus on diversifying its economy through Vision 2030 initiatives includes massive industrial build-outs. Major industrial cities like Jubail and Yanbu are central to this demand, requiring robust valve solutions.
India
India’s growing infrastructure and industrialization efforts underpin a steady demand for industrial valves across various sectors. The country's regulatory framework, including BIS standards, guides product quality and certification. Manufacturing hubs in Gujarat and Maharashtra are expanding, driving requirements for both standard and specialized valve types.
Industrial Valves Market Key Industry Players
United States producers anchor one tier, specializing in advanced automation and control technologies; European specialists hold another, focusing on highly engineered solutions for critical applications. The market structure integrates global leaders with regional manufacturers serving specific industrial niches. Key strategic archetypes include integrated solution providers, severe-service specialists, and cost-efficient volume manufacturers. Competitive moves frequently involve technology differentiation through intelligent valve systems and strategic partnerships for localized market access.
Specialists in severe service applications include Flowserve, which maintains its market position through dedicated engineering for demanding petrochemical environments. This company's expertise in handling corrosive and high-pressure media highlights a critical segment of the industrial valve market. Emerson exemplifies a global player, leveraging an extensive automation and control technology portfolio to offer integrated solutions meeting stringent regulatory standards. KSB Group, with its German heritage, anchors the highly engineered segment, providing specialized pumps and valves for water treatment and power generation sectors, differentiating through precision and reliability. These companies collectively illustrate the market's differentiation across performance tiers and specific end-user requirements.
| Leading Market Players |
|---|
| KSB Group |
| KITZ Corporation |
| Emerson |
| Neway Valve |
| Spirax Sarco |
| Flowserve |
| Velan Inc. |
| Schlumberger |
| Crane Co. |
Cost & Logistics Intelligence
Backward integration into specialized alloy production anchors a manufacturer's supply position, significantly influencing pricing power for high-performance industrial valves. This strategic choice allows greater control over material costs and quality, impacting market competitiveness.
Pricing Analysis
Pricing stratifies across performance tiers, reflecting the volume-vs-margin split in the industrial valves market. Project-based and contract pricing models dominate for high-specification units, while transactional pricing applies to standard components. Price differentiation stems from certification levels like API 624 and specialized engineering for severe service applications. Input cost volatility, particularly for nickel and chromium alloys, creates margin pressure, while sophisticated end-users in critical sectors prioritize lifecycle performance over initial unit cost.
Supply Chain Analysis
Single-source vulnerability sits with a limited number of large-scale foundries, primarily located in Asia, for producing large-diameter steel castings. The industrial valves supply chain draws from specialized alloys containing nickel, chromium, and molybdenum for corrosion-resistant units. This concentration creates lead time extensions and potential supply chain vulnerabilities for major projects. Distribution runs through a network of global manufacturers, like Emerson, and regional specialists serving specific industrial niches, often leveraging strategic partnerships for localized market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial valves market operates as a supply-constrained story, where specialized casting capacity acts as a bottleneck. This constraint props up pricing power for manufacturers capable of securing reliable input streams.
For Market Incumbents:Deepen investment in advanced sealing technologies to meet stringent environmental mandates like the US EPA's fugitive emissions standards. Expand automation and control portfolios, leveraging integrated solutions to differentiate from lower-tier manufacturers. Prioritize R&D in intelligent valve systems, offering superior lifecycle performance and diagnostic capabilities. Pursue certification investment in standards such as API 624 to reinforce market leadership and mitigate regulatory threats.
For New Entrants and Emerging Players:Intelligent valve systems offer a technology-first wedge into underserved markets by providing outcome-based services focused on asset health monitoring. Target the nascent hydrogen economy infrastructure for highly engineered valves capable of cryogenic temperatures. Focus on specific applications within water treatment or low-pressure, non-critical systems where legacy integration challenges are less severe. Develop specialized solutions for brownfield sites, offering seamless integration with existing Distributed Control Systems.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized technology providers and severe-service application specialists within the industrial valves market. The long-term viability favors companies positioned for the market's transformation towards intelligence and higher performance over the coming years. Target acquisition archetypes include firms excelling in API 624 certified low-emission valves or advanced automation integration. The signal to watch is the accelerated adoption rates of intelligent valve systems in critical infrastructure projects across industrialized economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Specialized Casting | Addresses the supply bottleneck in large-diameter steel castings, reducing lead times for major projects. |
| R&D in Low-Emission Sealing Technologies | Meets stringent US EPA fugitive emissions standards, differentiating products in the petrochemical sector. |
| Partnerships for Digital Integration | Accelerates adoption of intelligent valve systems by enabling seamless integration with plant-wide automation networks. |
| Geographic Expansion in Middle East Petrochemicals | Captures demand from new project investments in Saudi Arabia, requiring high-specification, severe-service valves. |
| Certification for Hydrogen Applications | Positions manufacturers for the global build-out of hydrogen economy infrastructure, requiring specialized valve designs. |
Research Approach
Industry association reports, government industrial data, and technical standards publications formed the secondary backbone for this analysis. This was complemented by primary interviews with plant managers, procurement leads, R&D directors, and EPC contractors across key regions. The data underwent rigorous bottom-up and top-down triangulation to ensure accuracy and comprehensive market coverage.
Historical trendline analysis established foundational market sizing and growth projections across the analysis window. The quantitative model segmented the market by valve type, actuation method, end-user industry, connection type, and regulatory compliance tier. Compound annual growth rates were derived from historical growth rates and projected demand drivers, with petrochemical new project investment and F-Gas Regulation compliance timelines as key inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical instability and rapid shifts in global trade policies. Forecasts reflect assumptions about stable regulatory environments and sustained industrial investment. Deviation in raw material supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Thermal Power Valve Market
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Global Thermostatic Radiator Valve Market
Valves
One-Way Valve Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
Pneumatic Needle Valves Market
Valves
Aerospace Valves Market
Valves
Servo Valves Market
Valves
Float Traps Market
Valves
Mooring Inspection Market
Valves
Dense Phase Vessels Market
Valves
GCC and MENA Valves Market
Valves
Valve Driver Market
Valves
Harmonic Dampers Market
Valves
Valve Sack Market
Valves
Europe Butterfly Valve Market