
 Blow - Off Valves Market | 2026-2036
Blow - Off Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Blow - Off Valves Market Outlook
Electronic boost control integration is reshaping how blow-off valves interface with engine management systems, replacing purely mechanical spring-and-diaphragm architectures with sensor-driven actuation. Turbosmart leverages its Australian manufacturing base to sustain premium positioning in motorsport and street-performance channels across North America and Europe. HKS anchors its competitive stance through deep specialization in JDM platform compatibility and tuner-circuit brand equity. GO FAST BITS differentiates via patented venting adjustability that appeals to enthusiasts seeking acoustic and performance customization.
A blow-off valve is a pressure-release device installed in forced-induction systems, typically constructed from aluminum or stainless steel with a piston or diaphragm actuated at threshold boost levels between 5 and 30 psi to prevent compressor surge and turbocharger damage. The component serves to vent excess intake pressure when the throttle plate closes suddenly, preserving turbocharger shaft integrity and enabling faster spool recovery. Pneumatic valves retain the largest installed base due to proven reliability and minimal calibration complexity, though electronic valves are gaining traction as OEM turbocharger penetration deepens and engine control modules demand real-time feedback loops. Aftermarket Providers represent a concentrated margin pool where brand reputation and tuner-channel relationships command pricing power unavailable in commoditized OEM supply.
EPA emissions certification and NHTSA safety standards in the United States, alongside REACH material compliance and CE marking requirements in Europe, collectively elevate barrier costs for non-compliant suppliers and redirect procurement toward validated Tier 1 and Tier 2 vendors. Japan's METI energy-efficiency guidelines and JIS quality standards further shape product specifications for suppliers serving domestic OEMs and export markets. Stakeholders must monitor regulatory convergence between emissions, material traceability, and software-defined vehicle architectures to anticipate which valve technologies will retain market access across major automotive production jurisdictions.
Market Dynamics
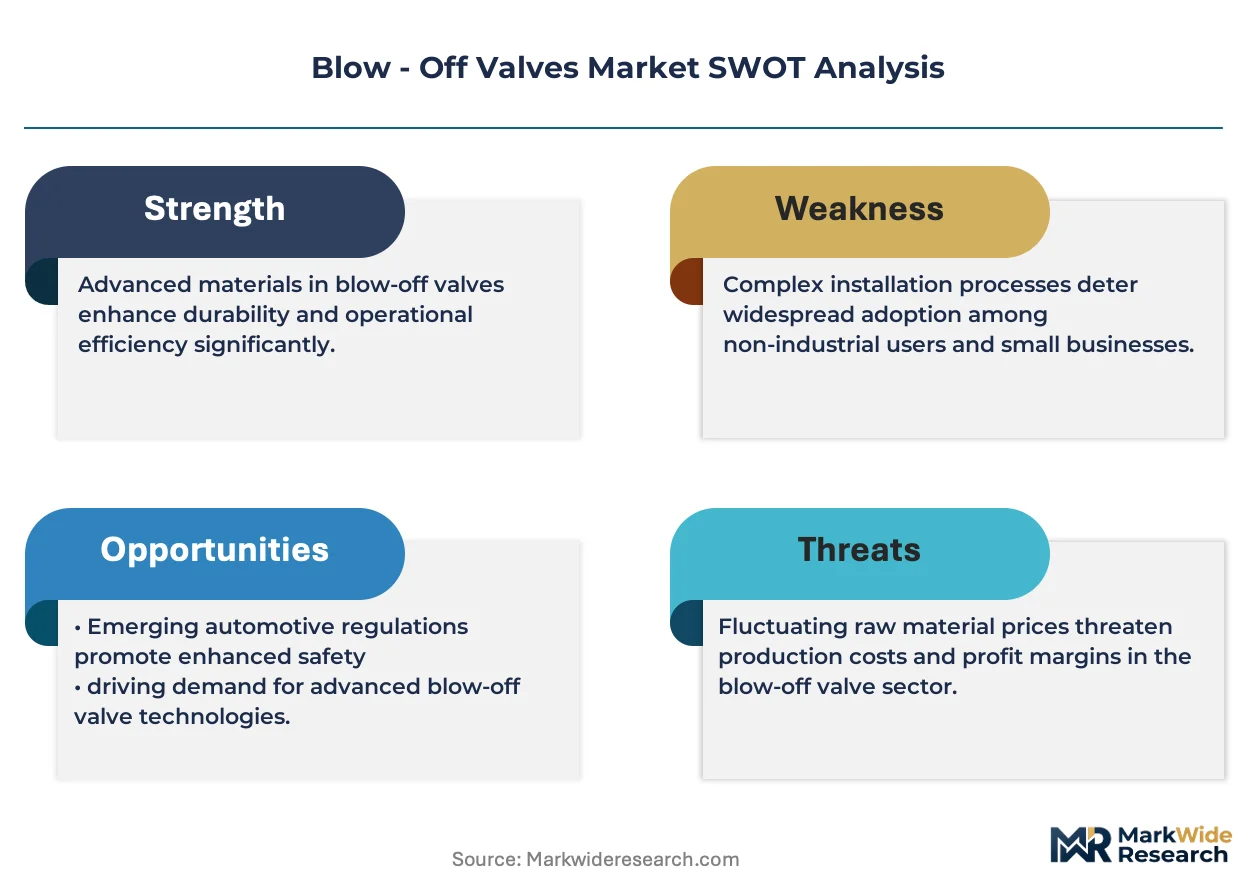
Electronic boost control integration is compressing the addressable market for purely mechanical blow-off valves while expanding premium tiers for sensor-actuated hardware that interfaces with engine control modules.
Growth Catalysts
- EPA Tier 4 and Euro 7 emissions protocols:These standards mandate precise boost pressure management, compelling OEMs to specify high-precision blow-off valves with tighter tolerance bands and faster actuation response.
- Passenger vehicle turbocharger penetration:Downsized engines with forced induction now dominate powertrain portfolios, expanding the installed base for both factory-fit and replacement blow-off valves across volume segments.
- Motorsport aftermarket clustering:Dense tuner ecosystems in Germany, Japan, and the United States sustain premium pricing for performance-spec valves with adjustable venting profiles and acoustic customization.
Market Restraints
- Aluminum and stainless steel input volatility:Raw material price swings compress margin predictability for valve housings and piston assemblies, particularly affecting smaller Tier 2 fabricators without long-term supply agreements.
- Electronic valve calibration complexity:Sensor-driven actuation requires integration with proprietary engine control module software, creating technical barriers that limit aftermarket participation to specialists with reverse-engineering capabilities.
- Pneumatic valve commoditization:Mature spring-and-diaphragm architectures face price erosion as Chinese and Indian manufacturers scale production of functionally equivalent units for budget segments.
Strategic Opportunities
- Software-defined vehicle architectures:Over-the-air calibration updates enable valve parameter tuning without physical replacement, creating recurring service revenue streams and reducing warranty exposure for OEM suppliers.
- Hybrid powertrain boost systems:Mild-hybrid and PHEV platforms require specialized valves managing transient loads from combined internal combustion and electric assist, opening specification windows for differentiated products.
- India's PLI scheme for automotive components:Production-linked incentives for advanced manufacturing attract capital investment in precision machining capacity serving domestic OEMs and export markets.
Industry Challenges
- Embedded software certification timelines:Functional safety validation under ISO 26262 extends development cycles for electronic valves, delaying revenue recognition and straining R&D budgets.
- Cross-platform compatibility engineering:Proprietary CAN bus protocols and manufacturer-specific sensor mappings fragment development resources, forcing suppliers to maintain multiple hardware variants.
- Tier 1 supplier consolidation pressure:OEM procurement teams are reducing approved vendor lists, requiring smaller valve specialists to demonstrate scale or unique technology to retain supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blow - Off Valves Market |
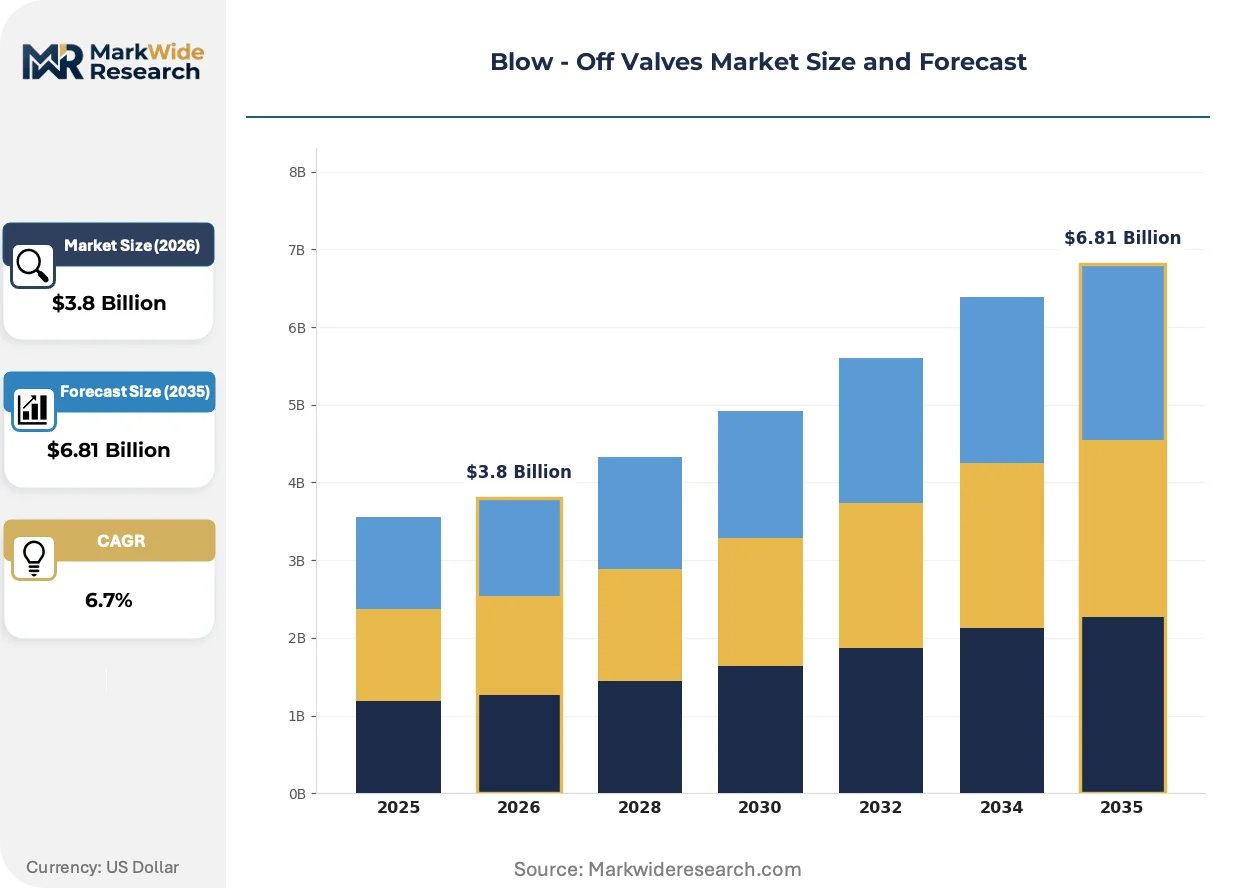
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Valves, Pneumatic Valves, Mechanical Valves, Hydraulic Valves End User: Automotive OEMs, Aftermarket Providers, Aerospace Manufacturers, Industrial Plants Application: Turbochargers, Engine Control, Wastegate Systems, Fuel Systems Material: Aluminum, Stainless Steel, Plastic, Brass |
| Companies Covered | Turbosmart, HKS, GReddy, GO FAST BITS, TiAL Sport, COBB Tuning, SARD Co, Synapse Engineering, Turbonetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blow - Off Valves Market Strategic Shifts
Sensor-actuated valve architectures are displacing mechanical systems across OEM specifications, while regulatory pressure on emissions traceability and materials compliance reshapes supplier qualification requirements.
Solenoid-driven blow-off valves with integrated pressure transducers and position feedback are digitizing how boost control hardware communicates with engine management systems. OEM powertrain divisions specify these units for new turbocharged platforms launching 2024-2027. The technology is digitizing valve calibration from a static mechanical process into a dynamic software-configurable function, compressing development lead times while expanding aftermarket reprogramming possibilities.
REACH substance restrictions and SCIP database requirements in Europe are forcing housing alloy reformulations and coating substitutions for valves exported to EU member states. Suppliers must document full material composition through supply chains or face market exclusion. Aftermarket providers serving German and French tuner markets are responding by qualifying alternative surface treatments and establishing EU-based assembly to simplify customs clearance.
Direct-to-consumer channel expansion through specialized e-commerce platforms is fragmenting traditional distribution for performance valves. Enthusiast buyers now research specifications, compare dyno-validated flow data, and purchase without intermediary retail markup. This pattern concentrates in North American and Australian markets where postal infrastructure supports rapid fulfillment of lightweight automotive components and manufacturer websites host technical documentation previously gatekept by distributor networks.
Blow - Off Valves Market Segmentation
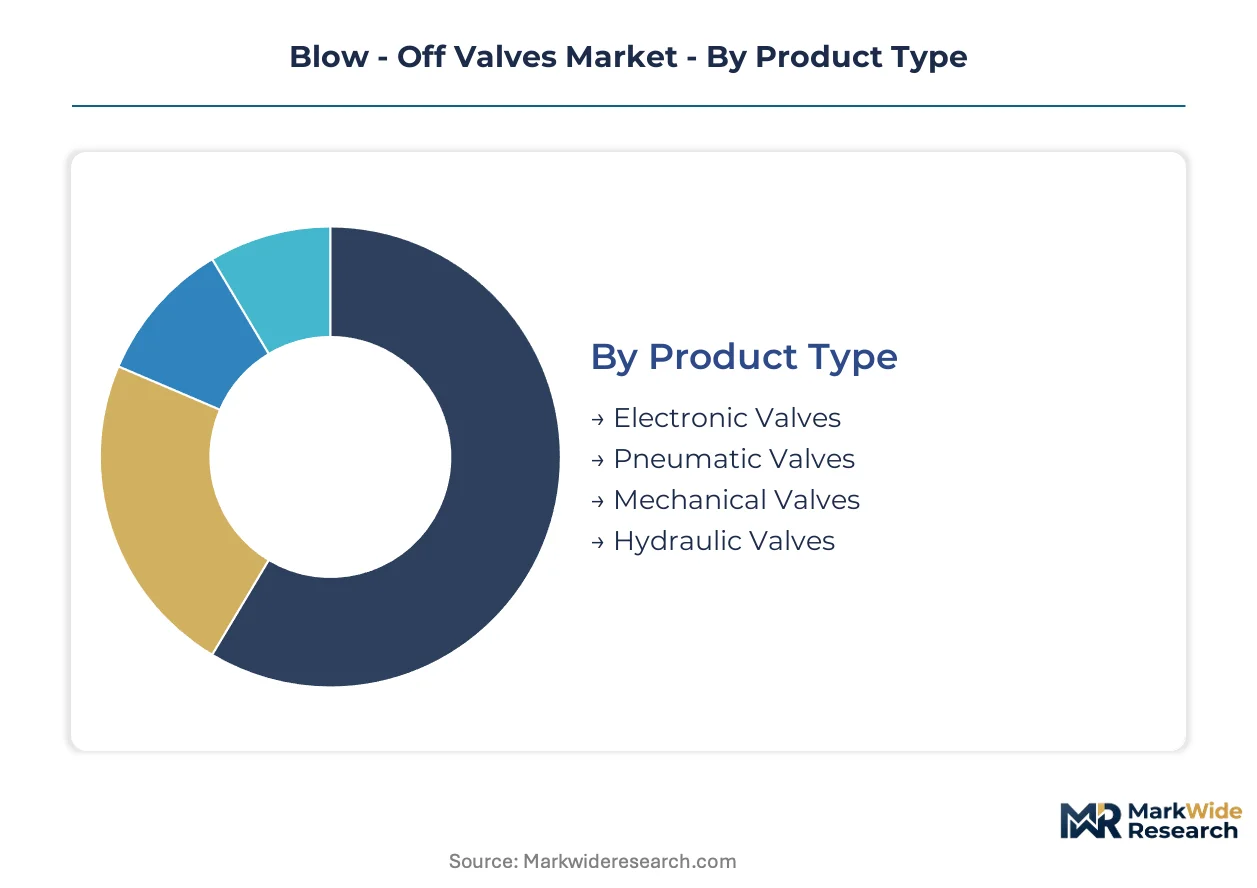
Segmentation in the blow-off valve market reflects divergent technical requirements across OEM integration versus aftermarket replacement, with material selection and actuation method determining compliance eligibility and margin structure. Understanding these divides clarifies where specification pressure concentrates and which supplier capabilities command pricing power.
Product Type:
Mature pneumatic architectures coexist with emerging electronic systems, creating a bifurcated supplier landscape where calibration complexity separates premium tiers from commoditized volume.
- Electronic Valves:Solenoid-driven units with integrated pressure transducers and position feedback enable real-time communication with engine control modules. OEM turbocharger programs in Germany and Japan specify these for new platforms requiring software-configurable boost parameters and over-the-air calibration updates.
- Pneumatic Valves:Spring-and-diaphragm mechanisms actuated by manifold pressure differentials dominate installed base across legacy vehicle fleets and budget aftermarket segments. Chinese and Indian fabricators scale production of functionally equivalent units, compressing margins for Tier 2 suppliers without long-term supply agreements.
- Mechanical Valves:Purely mechanical piston-and-spring designs serve racing applications where simplicity and rebuildability outweigh electronic integration needs.
- Hydraulic Valves:Fluid-actuated variants address high-boost commercial diesel systems where pneumatic response proves insufficient.
Pneumatic valves retain volume leadership; electronic valves hold the steepest expansion curve.
End User:
Customer type determines certification burden and channel economics, with OEM procurement teams imposing validation requirements that aftermarket channels escape.
- Automotive OEMs:Factory-fit specifications demand ISO 26262 functional safety validation and proprietary CAN bus protocol integration. NHTSA safety standards and EPA emissions certification in the United States, plus REACH material compliance in Europe, elevate barrier costs for non-compliant suppliers.
- Aftermarket Providers:Tuner-circuit distribution concentrates margin in brand reputation and acoustic customization rather than regulatory compliance. Dense motorsport ecosystems in Germany, Japan, and the United States sustain premium pricing for adjustable venting profiles.
- Aerospace Manufacturers:FAA certification requirements and traceability documentation govern material selection and fatigue testing protocols.
- Industrial Plants:Stationary engine and compressor applications prioritize durability cycles over response precision.
Aftermarket providers capture margin concentration; automotive OEMs anchor volume scale.
Application:
Functional placement within forced-induction systems dictates pressure thresholds and actuation speed requirements.
- Turbochargers:Primary pressure-release function preventing compressor surge when throttle plates close suddenly. Passenger vehicle turbocharger penetration across downsized engine portfolios expands replacement demand in United States and Japanese service markets.
- Engine Control:Integrated boost management within software-defined vehicle architectures. EPA Tier 4 and Euro 7 emissions protocols mandate precise pressure modulation, favoring sensor-actuated hardware with tighter tolerance bands.
- Wastegate Systems:Complementary boost regulation requiring coordinated valve response for optimal spool characteristics.
- Fuel Systems:Pressure relief in direct-injection fuel rails with distinct material compatibility requirements.
Turbocharger applications dominate unit volume; engine control integration claims the fastest technology refresh cycles.
Material:
Alloy selection balances thermal conductivity, corrosion resistance, and regulatory compliance across export jurisdictions.
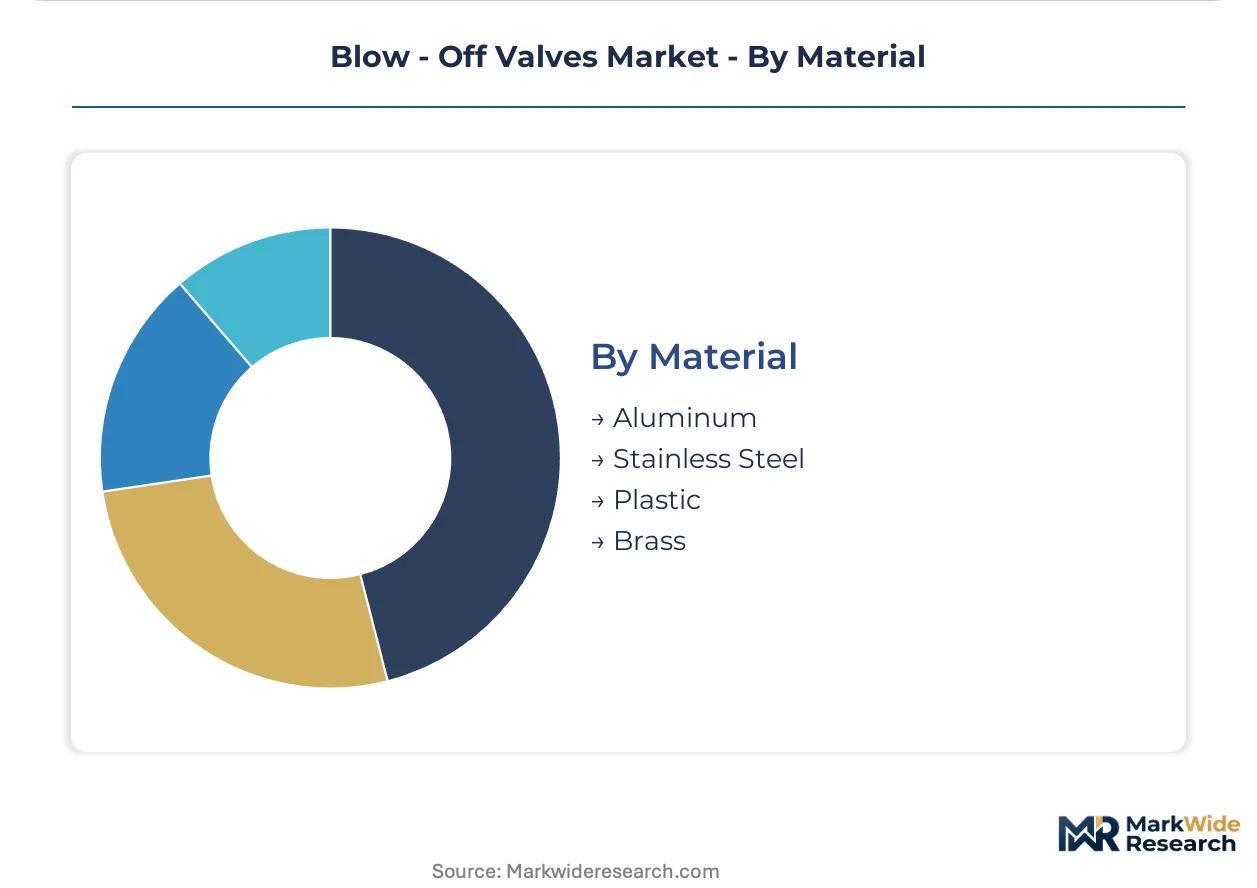
- Aluminum:Die-cast housings dominate volume production for weight-sensitive automotive applications. REACH substance restrictions in Europe force housing alloy reformulations and coating substitutions, requiring full material composition documentation through supply chains.
- Stainless Steel:Investment-cast or machined variants serve high-temperature turbocharger environments and motorsport specifications where thermal cycling resistance justifies cost premiums.
- Plastic:Glass-reinforced polymer pistons and diaphragm retainers reduce reciprocating mass in electronic valve designs.
- Brass:Lead-free formulations address drinking water contact regulations in ancillary industrial applications.
Aluminum retains cost-position leadership; stainless steel commands specification in premium thermal environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in blow-off valves track closely with automotive manufacturing density and motorsport aftermarket maturity. Countries with substantial domestic turbocharger production and established tuner ecosystems generate both outbound valve shipments and inbound premium component demand.
United States
Domestic OEM turbocharger programs and a robust aftermarket tuner culture sustain dual-channel valve demand. EPA Tier 4 emissions certification requirements shape product specifications for factory-fit applications. Southern California and Texas host dense clusters of performance automotive fabricators and specialty distributors serving both domestic and Latin American export markets.
Germany
Precision automotive engineering standards and proximity to major OEM powertrain development centers concentrate specification influence. REACH substance restrictions and CE marking requirements enforce material documentation protocols across supply chains. Stuttgart and Munich anchor development activity for motorsport-spec valves serving Nürburgring circuit demand and adjacent European tuner markets.
Japan
JDM platform specialization and domestic motorsport heritage sustain premium positioning for indigenous valve manufacturers. METI energy-efficiency guidelines and JIS quality standards govern export product specifications. Osaka and Nagoya metropolitan areas concentrate precision machining capacity serving both domestic OEMs and aftermarket channels across Southeast Asia.
China
Rapid expansion of domestic turbocharger manufacturing creates volume demand for cost-optimized valve architectures. MIIT emissions standards and GB technical regulations harmonize gradually with Euro 7 equivalent thresholds. Yangtze River Delta industrial zones host scaling production of pneumatic valve assemblies targeting both domestic fitment and emerging export markets.
Australia
Motorsport engineering reputation and geographic isolation sustain premium manufacturing for global performance channels. TGA-equivalent product safety frameworks and proximity to Asia-Pacific shipping lanes facilitate regional distribution. Melbourne-based fabricators leverage domestic V8 Supercars engineering heritage to anchor export positioning in North American and Middle Eastern aftermarket segments.
Blow - Off Valves Market Competitive Environment
On the supply side, the industry is bifurcated between precision OEM suppliers and specialized aftermarket fabricators with limited overlap in customer relationships. Tier 1 automotive suppliers dominate factory-fit specifications through embedded software integration and validation capabilities. Tier 2 specialists capture aftermarket margin through brand equity and acoustic customization. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as electronic valve architectures displace mechanical systems.
Within the heritage-performance tier, Turbosmart exemplifies Australian-based manufacturing anchored in motorsport credibility, while HKS occupies a position reflecting deep JDM platform specialization. GO FAST BITS represents the adjustable-venting archetype where patented mechanical customization sustains premium pricing independent of electronic integration trends.
| Leading Market Players |
|---|
| Turbosmart |
| HKS |
| GReddy |
| GO FAST BITS |
| TiAL Sport |
| COBB Tuning |
| SARD Co |
| Synapse Engineering |
| Turbonetics |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta freight corridor's container rate volatility feeds directly into landed cost spreads between Chinese pneumatic valve fabricators and German precision-machining houses, compressing margin buffers for Tier 2 suppliers without long-term freight contracts while amplifying price differentiation between commodity-grade and certified-electronic tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across ISO 26262-certified electronic tiers, standard pneumatic assemblies, and economy-grade mechanical units. Price differentiation hinges on functional safety validation burden and aluminum alloy grade sourcing. Cost compression in economy pneumatic segments is intensifying because Yangtze Basin fabricators scale die-casting capacity. Aftermarket tuner channels exhibit lowest price sensitivity; fleet procurement teams at commercial vehicle OEMs exhibit highest.
Supply Chain Analysis
Export-control restrictions on pressure-sensor microelectronics limit flows from specific jurisdictions into valve actuator manufacturing, forcing Tier 1 suppliers to qualify alternative transducer sources. Geographic supply concentration centers on China for aluminum die-cast housings, Germany for precision-machined stainless steel pistons, and Japan for solenoid coil assemblies. Raw material dependencies draw from 6061 aluminum billet, 17-4 PH stainless steel bar stock, and copper magnet wire. Single-source vulnerability in automotive-grade pressure transducers concentrates risk. Distribution runs through Tier 1 supplier consolidation into OEM platform engineering teams, with aftermarket channels fragmenting toward direct-to-consumer e-commerce.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded software calibration capabilities for electronic valve architectures remain scarce relative to expanding OEM demand, creating asymmetric returns for suppliers that bridge mechanical fabrication heritage with functional safety engineering depth.
For Market Incumbents: Entrench position by acquiring reverse-engineering specialists with proven CAN bus protocol integration track records, and by adding captive aluminum die-casting capacity in Yangtze River Delta zones to offset input volatility. Electronic valve commoditization from Chinese entrants threatens premium positioning; ISO 26262 certification investment serves as the primary defensive lever. For New Entrants and Emerging Players: Build out white-space presence in India's PLI-subsidized precision machining corridor serving domestic OEM turbocharger programs, and in hybrid powertrain boost system specifications where incumbent electronic valve portfolios remain underdeveloped. Mild-hybrid transient load management represents the most penetrable application segment. Go-to-market execution should lead with JIS-compliant documentation for Japanese OEM qualification pipelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive component parents where blow-off valve divisions lack scale for standalone ISO 26262 investment but retain established OEM relationships and precision machining assets. Long-term viability favors suppliers with software-defined vehicle architecture alignment over pure mechanical heritage. Monitor EPA Tier 4 enforcement intensity as inflection signal for electronic valve specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Die-Casting | Captive 6061 billet processing insulates margin from Yangtze Basin commodity swings and REACH coating compliance costs. |
| ISO 26262 Functional Safety Certification | Validation investment unlocks OEM electronic valve specifications in Germany and Japan where Tier 1 procurement gates access. |
| Direct-to-Consumer Channel Development | Manufacturer-controlled e-commerce captures aftermarket margin otherwise lost to distributor markups in Australian and North American tuner markets. |
| Hybrid Powertrain Boost System Specialization | Mild-hybrid transient load expertise opens specification windows ahead of incumbent electronic valve portfolio expansion. |
| India PLI Manufacturing Footprint Establishment | Production-linked incentive qualification reduces landed cost for domestic OEM supply and Southeast Asian export markets. |
Study Parameters
Operator-level perspectives from Tier 1 supplier procurement directors, OEM platform powertrain engineers, aftermarket distributor category managers, and precision machining plant managers anchored the qualitative base. Secondary validation drew from EPA certification filings, NHTSA safety standard documentation, REACH substance restriction updates, MIIT automotive component regulations, and customs trade flow data. Bottom-up unit economics triangulated against top-down automotive production forecasts across passenger and commercial vehicle segments.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated electronic valve penetration paths throughout the forecast period. Segmentation dimensions modeled encompassed actuation method, end-user certification tier, material alloy grade, and regional manufacturing cluster. CAGRs derived from fitted growth curves against observed turbocharger fitment rates and emissions protocol phase-in schedules. Industry-specific inputs included IHS Markit vehicle registration data and OEM powertrain platform launch cadence.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese pneumatic specialists or accelerated Euro 7 enforcement would shift outcomes. Material shifts in semiconductor export control scope or aluminum alloy REACH restriction expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Stainless Steel Valve Tag Market
Valves
Cryogenic Valve Market
Valves
Vaneometer Market
Valves
Explosion Proof Solenoid Valves Market
Valves
Industrial Safety Valves Market
Valves
Global Pressure Relief Valves Market
Valves
Pup Joint Market
Valves
Actuators and Valves Market
Valves
3-Way Pilot Operated Directional Control Valves Market
Valves
Middle East and Africa Electro Hydraulic Servo Valve Market
Valves
Diaphragm Valve Market
Valves
Air Heated Vaporizer Market
Valves
Transmission Overload Protectors Market
Valves
Global Thermostatic Radiator Valve Market
Valves
Float Traps Market
Valves
Mobile Hydraulic Valves Market