
 Emergency Shut Down Valves (ESDV) Market | 2026-2036
Emergency Shut Down Valves (ESDV) Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Shut Down Valves (ESDV) Market Insights
Direct sales channels for critical safety valves is fragmenting as end-users diversify procurement between authorized distributors, original equipment manufacturers, and integrated service contractors. Emerson leverages its automation platform to bundle ESDV packages with digital monitoring systems. Baker Hughes anchors its position through subsea and severe-service valve engineering. KITZ Corporation competes on forged-body manufacturing scale across Asian project markets.
Emergency Shut Down Valves are fail-safe flow isolation devices engineered to close within seconds of a trigger signal, typically achieving SIL 3 safety integrity ratings through spring-return or stored-energy actuator designs. Their primary purpose is to prevent catastrophic release of hazardous media in hydrocarbon processing, chemical transfer, and high-pressure steam systems. Ball valve configurations dominate pipeline protection applications due to tight shutoff and quarter-turn speed, while pneumatic actuation leads in offshore environments where instrument air infrastructure exists and explosion-proof electric alternatives carry weight penalties. Electric operation is gaining fastest in onshore chemical facilities integrating ESDVs into centralized distributed control architectures.
OSHA process safety management rules and EPA risk management program requirements mandate functional testing intervals for ESDV systems in US hazardous chemical facilities. The EU Machinery Directive and ATEX standards enforce CE-marked actuator compatibility and zone-rated construction for European installations. Stakeholders must monitor evolving cybersecurity standards for electric actuators as networked safety instrumented systems become attack vectors.
Market Dynamics
Offshore operators are consolidating ESDV specifications around integrated safety instrumented systems, compressing procurement cycles from multi-year project tenders to framework agreements with bundled digital monitoring. This shift concentrates purchasing power among integrated service contractors and automation platform vendors.
Growth Catalysts
- EU F-Gas Regulation phase-down:The regulation's tightening emission quotas for hydrofluorocarbon actuators is accelerating demand for pneumatic and electric alternatives in North Sea installations.
- Subsea tieback projects:Deepwater field developments in Brazil and West Africa require fail-safe isolation at wellheads, driving specification of high-pressure metal-seated ball valve configurations.
- SIL 3 certification mandates:Process hazard analysis requirements under OSHA PSM rules are forcing US Gulf Coast refineries to upgrade legacy pneumatic systems to certified safety instrumented function loops.
Market Restraints
- Specialized alloy supply concentration:Forged duplex stainless bodies depend on a limited supplier base in Western Europe, creating lead time volatility for severe-service specifications.
- Explosion-proof electric actuator weight penalties:Subsea umbilical load constraints favor pneumatic solutions, restricting electric adoption in floating production installations.
- Extended ATEX certification timelines:Zone 0 actuator approvals through notified bodies in Germany and France now exceed eighteen months, delaying project commissioning.
Strategic Opportunities
- Retrofit automation in mature North Sea assets:Aging platforms require partial stroke testing integration without full system replacement, creating aftermarket digital actuator attachment demand.
- Carbon capture injection networks:Supercritical CO2 pipeline protection specifications are emerging as a distinct application requiring cryogenic-rated seat materials and rapid cycling endurance.
- Integrated valve-as-a-service models:Operating companies are outsourcing ESDV maintenance and testing to OEM service arms, shifting revenue from equipment sale to lifecycle contracts.
Industry Challenges
- Safety instrumented systems cybersecurity:Networked electric actuators in US chemical facilities now fall under EPA risk management program scrutiny for remote access vulnerabilities.
- Partial stroke testing technician scarcity:Qualified personnel to execute automated valve diagnostics without process interruption are concentrated among a handful of specialist contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Shut Down Valves (ESDV) Market |
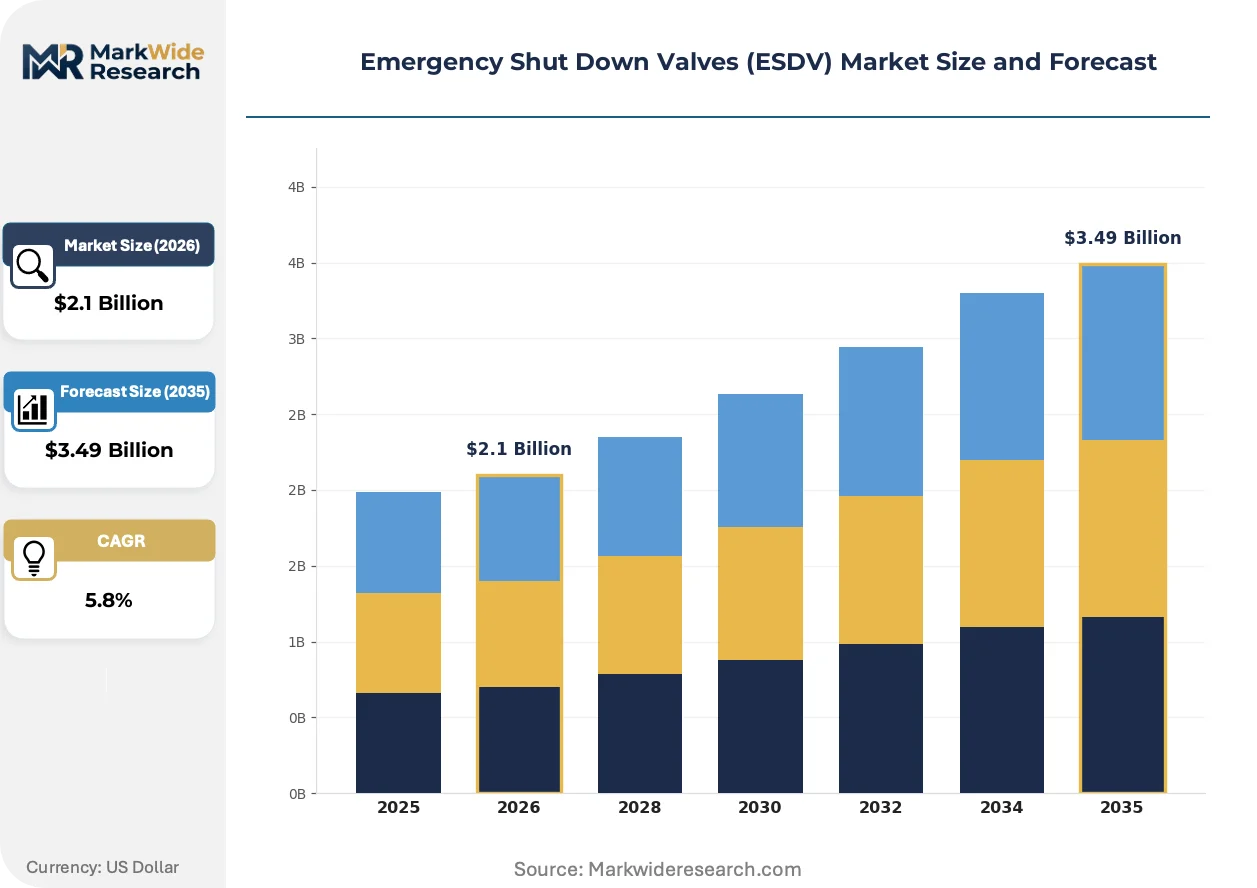
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Globe Valves, Butterfly Valves Operation Mode: Pneumatic, Hydraulic, Electric, Manual Industry Vertical: Oil & Gas, Chemicals, Power Generation, Water Treatment Application: Pipeline Protection, Emergency Isolation, System Shutdown, Process Control |
| Companies Covered | Neles, AUDCO Valves, Emerson, IMI Critical Engineering, KITZ Corporation, Valmet, Econtrol, L & T Valves, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Shut Down Valves (ESDV) Market Trends and Innovations
Digital integration is compressing the boundary between mechanical isolation hardware and process control software, forcing valve manufacturers to develop embedded sensing and edge computing capabilities. Three developments are restructuring competitive requirements.
Electro-hydraulic actuation with integrated positioners and diagnostic transmitters is rendering obsolete conventional pneumatic systems in onshore chemical complexes. Dow and BASF facilities in Texas and Louisiana are specifying these packages for centralized DCS architectures. The technology eliminates separate solenoid valve skids and instrument air distribution, collapsing installation footprint and commissioning labor.
The EU Machinery Directive's 2023 update tightened requirements for CE-marked actuator compatibility with safety-related control systems. Manufacturers must now demonstrate fault detection coverage through third-party certification. European ESDV procurement is shifting toward pre-certified subsystem packages rather than component-level sourcing, favoring integrated automation vendors over standalone valve suppliers.
Operator engineering standards are consolidating preferred vendor lists to reduce qualification overhead. Major integrated oil companies now mandate pre-approved manufacturer lists for subsea ESDVs, compressing competitive participation to three or four qualified sources. This concentration is most visible in Norwegian Continental Shelf projects, where NORSOK compliance and operator-specific technical practices create steep barriers for new market entrants.
Emergency Shut Down Valves (ESDV) Market Segmentation
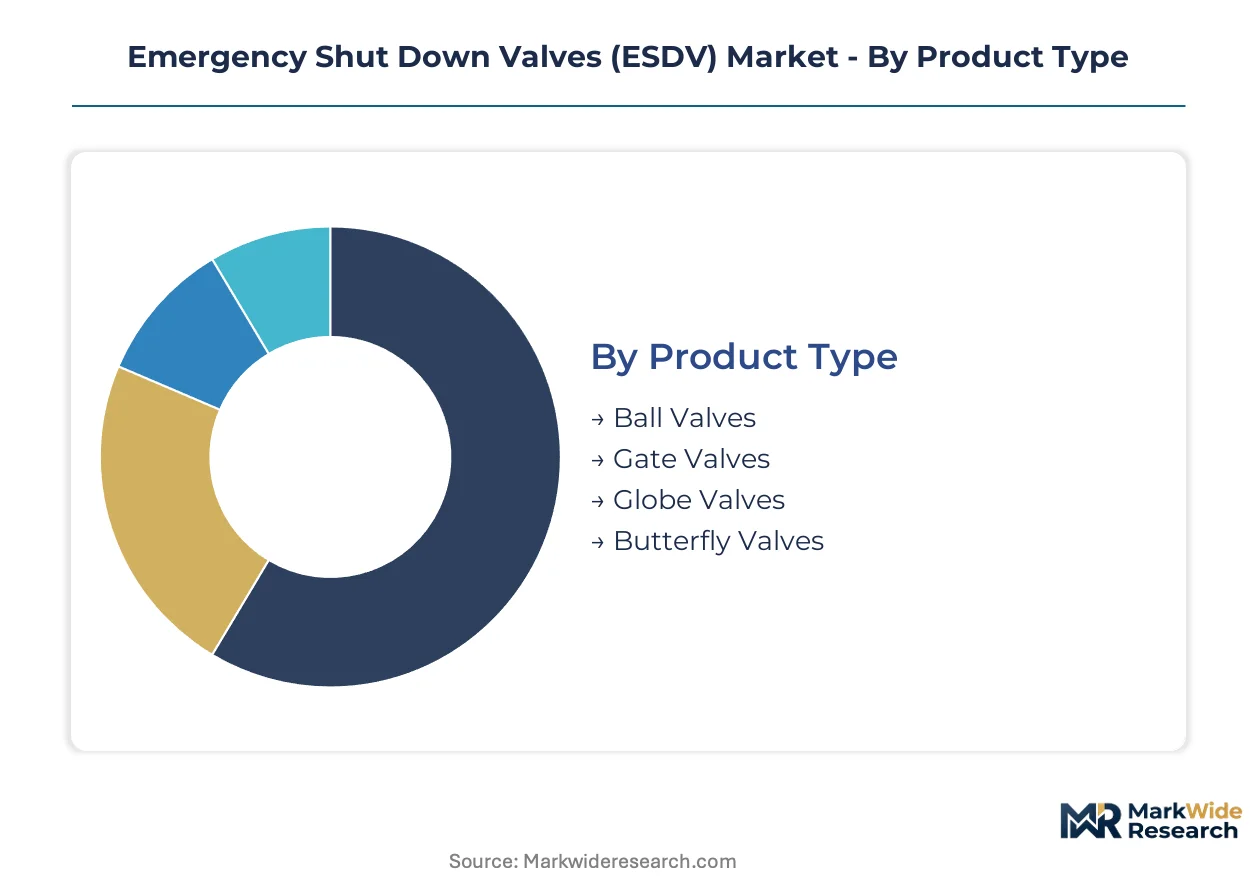
ESDV procurement patterns diverge sharply across operational contexts. Subsea wellhead isolation demands fundamentally different actuator specifications than onshore chemical facility integration. Understanding these fault lines enables targeted positioning against specific safety integrity requirements.
Product Type:
Use-case spectrum spans cryogenic LNG export terminals to supercritical CO2 injection networks, with metallurgy and sealing architecture driving specification divergence.
- Ball Valves:Quarter-turn metal-seated designs achieve tight shutoff under high-cycle conditions. Deepwater field developments in Brazil specify forged duplex stainless configurations for wellhead isolation. API 6D monogramming and SIL 3 certification dominate procurement checklists.
- Gate Valves:Linear-motion wedge designs suit infrequent full-bore isolation with minimal pressure drop. Onshore pipeline block valve stations favor these for straight-through flow efficiency. Rising stem configurations complicate subsea actuator integration.
- Globe Valves:Throttling-capable seat geometry suits control-loop integration rather than pure isolation. Combined cycle power plants specify these for steam attemperation safety loops. Higher flow resistance limits transmission pipeline adoption.
- Butterfly Valves:Compact face-to-face dimensions suit space-constrained platform installations. Resilient or metal-seated variants address fire-safe requirements in floating production hulls. Lower cost positioning drives water treatment and utility adoption.
Established volume favors ball valve configurations; emerging adoption favors butterfly valve formats in weight-sensitive offshore retrofits.
Operation Mode:
Actuator selection hinges on infrastructure availability, hazard zone classification, and response time specifications.
- Pneumatic:Spring-return diaphragm or piston designs dominate offshore environments with existing instrument air distribution. North Sea platforms specify these for fail-safe closure within ten seconds. Explosion-proof simplicity avoids ignition source complications.
- Hydraulic:Stored-energy accumulators deliver high torque for large-bore subsea valves. Pre-salt field developments off Angola and Brazil require these for seabed isolation at 3,000 meter depths. Subsea umbilical complexity concentrates supply among integrated service contractors.
- Electric:Multi-turn and quarter-turn motor operators integrate directly into distributed control architectures. US Gulf Coast chemical facilities specify these for centralized diagnostics and partial stroke testing. Zone 1 hazardous area certification delays procurement timelines.
- Manual:Gear-operated or handwheel configurations serve non-safety-critical isolation and maintenance bypass functions. Remote production facilities specify these as backup to automated systems. Lowest cost tier with minimal maintenance burden.
Maintenance simplicity favors pneumatic systems; integration flexibility favors electric actuation in greenfield chemical complexes.
Industry Vertical:
End-use concentration determines specification stringency, with hydrocarbon processing imposing the most severe metallurgical and certification requirements.
- Oil & Gas:Upstream, midstream, and downstream segments each generate distinct ESDV demand profiles. Offshore production drives highest value specifications through subsea and severe-service requirements. NORSOK and API standards govern material selection and testing protocols.
- Chemicals:OSHA process safety management and EPA risk management program rules mandate functional testing intervals. Texas and Louisiana petrochemical corridors concentrate demand for SIL-rated safety instrumented function loops. Corrosive media compatibility drives alloy selection.
- Power Generation:Combined cycle and thermal plants require rapid steam isolation to protect turbine assets. High-temperature seat materials and thermal cycling endurance differentiate specifications from hydrocarbon service. Grid stability requirements prioritize reliability over cost optimization.
- Water Treatment:Lower pressure ratings and ambient temperature ranges permit simplified actuator configurations. Municipal and industrial water facilities specify these for pump isolation and flood prevention. Stainless steel construction addresses corrosion without exotic alloy premiums.
Specification intensity favors oil and gas procurement; volume expansion favors water treatment infrastructure programs.
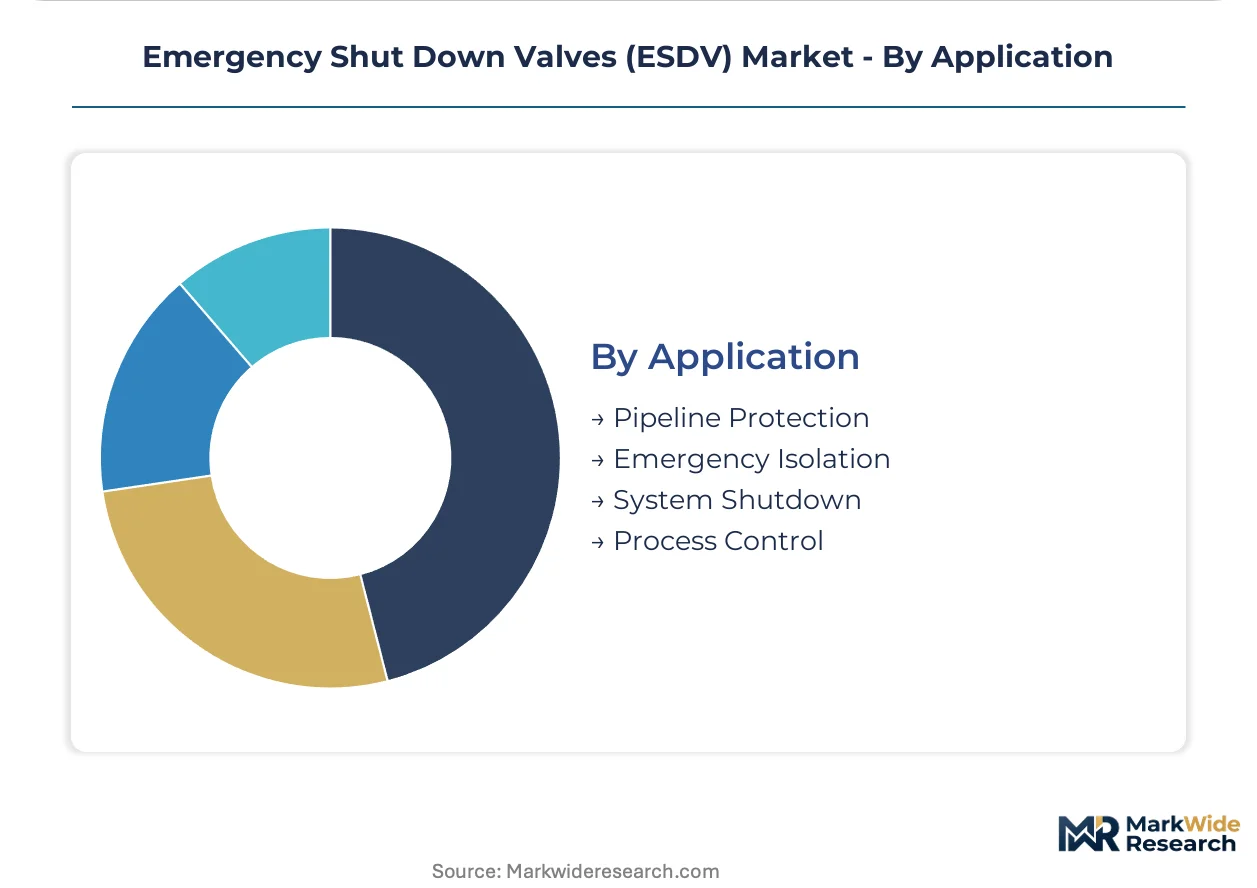
Application:
Functional role within safety instrumented systems determines response time targets and diagnostic depth.
- Pipeline Protection:Sectionalizing block valves isolate rupture events to limit inventory release. US interstate transmission operators specify these per DOT pipeline safety regulations. Remote monitoring and automated closure reduce incident consequence zones.
- Emergency Isolation:Final element functions in safety instrumented systems achieve SIL 3 through redundant architectures. Process hazard analysis identifies these as critical protection layers. Proof testing intervals and diagnostic coverage dominate lifecycle cost calculations.
- System Shutdown:Unit-level or plant-wide isolation sequences coordinate multiple ESDV actuations. Centralized safety PLC architectures manage these through hardwired or networked communication. Sequence timing prevents pressure surge and water hammer damage.
- Process Control:Non-safety-critical isolation supports batch sequencing and equipment protection. Lower integrity requirements permit standard PLC integration rather than certified safety systems. Cost optimization dominates procurement criteria.
Safety-critical specification favors emergency isolation; installation volume favors process control integration in facility expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Norwegian and US Gulf Coast procurement offices, while Asian fabricators compete on forged-body scale without equivalent specification premiums. This asymmetry shapes regional investment patterns and vendor qualification hierarchies.
United States
OSHA process safety management rules and EPA risk management program requirements mandate functional testing intervals for ESDV systems across Texas and Louisiana petrochemical corridors. The EPA enforces proof-testing documentation for safety instrumented functions in hazardous chemical facilities. Houston-area engineering firms specify SIL 3 certified packages for refinery expansion projects, compressing vendor qualification timelines.
Norway
NORSOK compliance requirements and operator-specific technical practices create steep barriers for new market entrants in North Sea platform retrofits. The country's petroleum regulator enforces fail-safe isolation standards for aging infrastructure partial stroke testing integration. Stavanger-based procurement teams consolidate preferred vendor lists to three qualified sources for subsea wellhead specifications.
Brazil
Pre-salt field developments off Angola and Brazil require high-pressure metal-seated ball valve configurations for seabed isolation at extreme depths. The national petroleum regulator mandates local content requirements for subsea equipment procurement. Rio de Janeiro engineering clusters coordinate specification packages for deepwater tieback projects, favoring integrated service contractors with accumulator-based hydraulic actuator capabilities.
Germany
The EU Machinery Directive's 2023 update tightened CE-marked actuator compatibility requirements for safety-related control systems. German notified bodies now exceed eighteen months for Zone 0 actuator approvals, delaying project commissioning. Düsseldorf-area automation vendors shift toward pre-certified subsystem packages rather than component-level sourcing.
Japan
JIS standards and METI industrial safety guidelines shape domestic ESDV procurement for combined cycle power plant steam isolation. Japanese engineering houses specify rapid turbine protection systems with high-temperature seat materials. Yokohama-based valve manufacturers develop embedded sensing capabilities for centralized diagnostic architectures.
Emergency Shut Down Valves (ESDV) Market Competitive Landscape
Integrated automation platforms and specialized valve engineering houses split the market between bundled digital monitoring solutions and severe-service metallurgy expertise. Tiering concentrates at the premium end, where pre-qualified vendor status determines participation in major project tenders. Three archetypes dominate: full-suite automation vendors with safety instrumented system integration capabilities; forged-body specialists with scale advantages in Asian project markets; and subsea engineering houses with accumulator-based hydraulic expertise. Competitive moves center on framework agreement consolidation and embedded diagnostic technology licensing.
Within the integrated automation tier, Emerson and Valmet exemplify platform bundling strategies that collapse installation footprint through electro-hydraulic packages with integrated positioners. Among forged-body specialists, KITZ Corporation occupies a position reflecting Asian manufacturing scale across project markets. Baker Hughes anchors the subsea engineering archetype through severe-service valve capabilities. These three represent distinct competitive vectors: centralized diagnostics, manufacturing scale, and deepwater technical performance.
| Leading Market Players |
|---|
| Neles |
| AUDCO Valves |
| Emerson |
| IMI Critical Engineering |
| KITZ Corporation |
| Valmet |
| Econtrol |
| L & T Valves |
| Baker Hughes |
| Others |
Pricing and Supply Chain Analysis
Western European forging clusters around Düsseldorf and Milan anchor duplex stainless capacity for severe-service valve bodies, translating alloy scarcity into pricing leverage for qualified suppliers serving North Sea and Gulf Coast project specifications. This geographic concentration of metallurgical capability creates asymmetric power between upstream mill operators and downstream valve assemblers.
Pricing Analysis
Configured-to-order pricing for SIL 3 certified subsea packages commands substantial premiums over standard onshore pneumatic configurations. Project-based contracting dominates, with price differentiation driven by certification grade and after-sales service bundling. Cost compression in standard butterfly valve tiers is intensifying because Asian fabricators are expanding forged-body scale. Municipal water treatment buyers exhibit highest price sensitivity, while offshore operators prioritize technical performance over unit economics.
Supply Chain Analysis
Specialized alloy feedstock draws from mills in Germany, Italy, and Sweden, with forged duplex stainless bodies resting on this limited Western European supplier base. Critical inputs include super-duplex bar stock, cryogenic seat polymers, and accumulator-based hydraulic power units. Single-source vulnerability concentrates in Zone 0 actuator certification through German and French notified bodies. Distribution runs through integrated service contractors and automation platform vendors rather than standalone component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electro-hydraulic actuation with embedded diagnostics threatens to displace conventional pneumatic systems, forcing incumbents to defend installed base through lifecycle service contracts and digital retrofit attachments.
For Market Incumbents: Build certification moats by accelerating ATEX and SIL 3 pre-approval investments ahead of competitor qualification timelines. Secure backward integration into forged duplex stainless supply through long-term mill partnerships, reducing lead time volatility. Defend against electro-hydraulic substitution by embedding partial stroke testing capabilities in legacy pneumatic installations. For New Entrants and Emerging Players: Pursue aftermarket digital actuator attachment opportunities in mature North Sea assets requiring partial stroke testing integration without full system replacement. Target carbon capture injection network specifications as an emerging application with undefined vendor hierarchies. Establish credibility through subsystem partnerships with established automation platform vendors rather than direct end-user sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated automation vendors with safety instrumented system bundling capabilities over standalone valve manufacturers. Long-term viability hinges on recurring revenue share from valve-as-a-service contracts versus transactional equipment sales. Watch for inflection in EPA enforcement intensity around networked electric actuator cybersecurity as a signal for pneumatic retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Approval Investment | Compresses vendor qualification timelines for Norwegian Continental Shelf tenders. |
| Backward Integration into Alloy Supply | Secures forged duplex stainless capacity against Western European mill constraints. |
| Valve-as-a-Service Contracting | Shifts revenue from equipment sale to lifecycle maintenance with integrated diagnostics. |
| Electro-Hydraulic Platform Development | Eliminates separate solenoid skids for Dow and BASF centralized DCS architectures. |
| Carbon Capture Specification Entry | Captures emerging demand for cryogenic-rated CO2 pipeline protection systems. |
Research Methodology
A spread of perspectives from plant engineers at Gulf Coast refineries, procurement leads at integrated oil companies, valve OEM technical directors, and aftermarket service contractors converged on the working assumptions. Secondary validation drew from OSHA enforcement records, EPA risk management program documentation, NORSOK standards publications, and EU Machinery Directive regulatory filings. Bottom-up project pipeline tracking and top-down safety instrumented system expenditure estimates were triangulated to anchor volume assumptions.
Demand-supply balance modeling across the projection horizon incorporated segmentation by valve configuration, actuator technology, industry vertical, and application safety integrity level. CAGRs were derived from regression against historical project award patterns and forward pipeline visibility. Industry-specific forecast inputs included subsea tieback project sanctioning rates and EU F-Gas Regulation phase-down implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in hydrocarbon capital expenditure cycles or offshore project financing availability would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement continuity and certification body capacity. Cross-checking against operator-approved manufacturer list dynamics and framework agreement renewal patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Battery Safety Valve Market
Valves
Subsea Control System Market
Valves
Instrumentation Valves and Fittings Market
Valves
HVAC Valves Market
Valves
North America Butterfly Valve Market
Valves
Manual Control Valve Market
Valves
Global Level Gauge Market
Valves
Global Valve Positioners Market
Valves
Construction Valve Seat Insert Market
Valves
Insulation Flanges Market
Valves
Pipeline Pigging System Market
Valves
Axial and Radial Seals Market
Valves
Degassing Valves Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Static Seals Market
Valves
Industrial Valves and Actuators Market