
 Flow Wraps Market | 2026-2036
Flow Wraps Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Wraps Market Foresight
Pharmaceutical manufacturers is collapsing the distance between sterile barrier requirements and cost efficiency in flow wrap procurement. Amcor plc leverages its pharmaceutical certification network to sustain high-margin contracts across European sterile packaging lines. Huhtamäki OYJ anchors its position through frozen food specialization, where puncture-resistant films dominate Nordic retail shelves. Constantia Flexibles Group differentiates via chocolate and confectionery expertise, occupying premium print-registration segments that command tighter tolerances.
Flow wraps constitute continuous-seal flexible packaging formed from oriented polyolefin or laminated film webs, typically sealed through rotary jaw mechanisms at speeds exceeding 300 packages per minute, designed to envelop individual or grouped products with hermetic closure for shelf-life extension and retail presentation. Horizontal flow wrapping dominates snack packaging throughput where line speeds and film economics prioritize mechanical reliability over format flexibility. Vertical flow wrapping leads pharmaceutical applications where gravity-fed product insertion and precise seal integrity align with FDA validation protocols for unit-dose compliance. Center fold wrapping competes in cosmetic packaging segments where aesthetic finish and tamper-evidence justify slower cycle rates.
FDA validation requirements for pharmaceutical packaging materials shape substrate selection and migration testing protocols that filter supplier qualification in the United States. The EU Green Deal and REACH chemical restrictions are forcing reformulation of adhesive layers and ink systems across European converter operations. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine which film recovery technologies achieve scale before compliance deadlines tighten material specifications.
Market Dynamics
High-barrier film specifications for unit-dose pharmaceuticals are compressing supplier qualification timelines while expanding the addressable premium substrate segment. Converter operations face simultaneous pressure from EMA migration testing protocols and EU Green Deal carbon accounting requirements.
Growth Catalysts
- EMA Annex 1 Sterile Manufacturing Updates:Revised aseptic processing guidelines mandate enhanced barrier properties for single-unit packaging, accelerating validation of coextruded films across European pharmaceutical lines.
- Confectionery Premiumization:Chocolate manufacturers in Belgium and Switzerland are specifying metallized and holographic flow wrap finishes for seasonal gift formats, expanding high-value print-registration demand.
- Rotary Jaw Mechanism Speed Advances:Servo-driven sealing systems now sustain 450 packages per minute on horizontal lines, enabling throughput gains for snack producers without format changeover penalties.
Market Restraints
- Ethylene Feedstock Volatility:Polyolefin resin costs fluctuate with naphtha-cracker margins in the Rotterdam-Antwerp hub, compressing converter gross margins during Q2-Q3 procurement cycles.
- Adhesive Reformulation Costs:REACH SVHC restrictions on solvent-based laminating adhesives force capital-intensive migration to waterborne or UV-cured systems with extended cure times.
- Mechanical Pouch Substitution:Pre-made stand-up pouches with reclosure features capture shelf-stable snack share in German and French retail, displacing traditional flow wrap for certain product categories.
Strategic Opportunities
- Poland and Czech Republic Manufacturing Expansion:Greenfield converter investments near Warsaw and Brno access EU structural funds while serving Central European pharmaceutical and food processing clusters.
- Pharma-Grade Recyclable Monomaterial Films:Polypropylene-based high-barrier structures compatible with existing sorting infrastructure address pending Extended Producer Responsibility fee differentials.
- Cold Chain Biologics Packaging:Insulin and mRNA vaccine unit-dose formats require ultra-low temperature seal integrity, creating specification premiums for qualified film suppliers.
Industry Challenges
- Migration Testing Laboratory Bottlenecks:EMA-recognized analytical capacity for extractables and leachables validation extends pharmaceutical qualification timelines to 18-24 months.
- Legacy Equipment Retrofit Complexity:Converters operating mechanical cam-driven flow wrappers face control system integration costs when upgrading to servo-based sealing precision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Wraps Market |
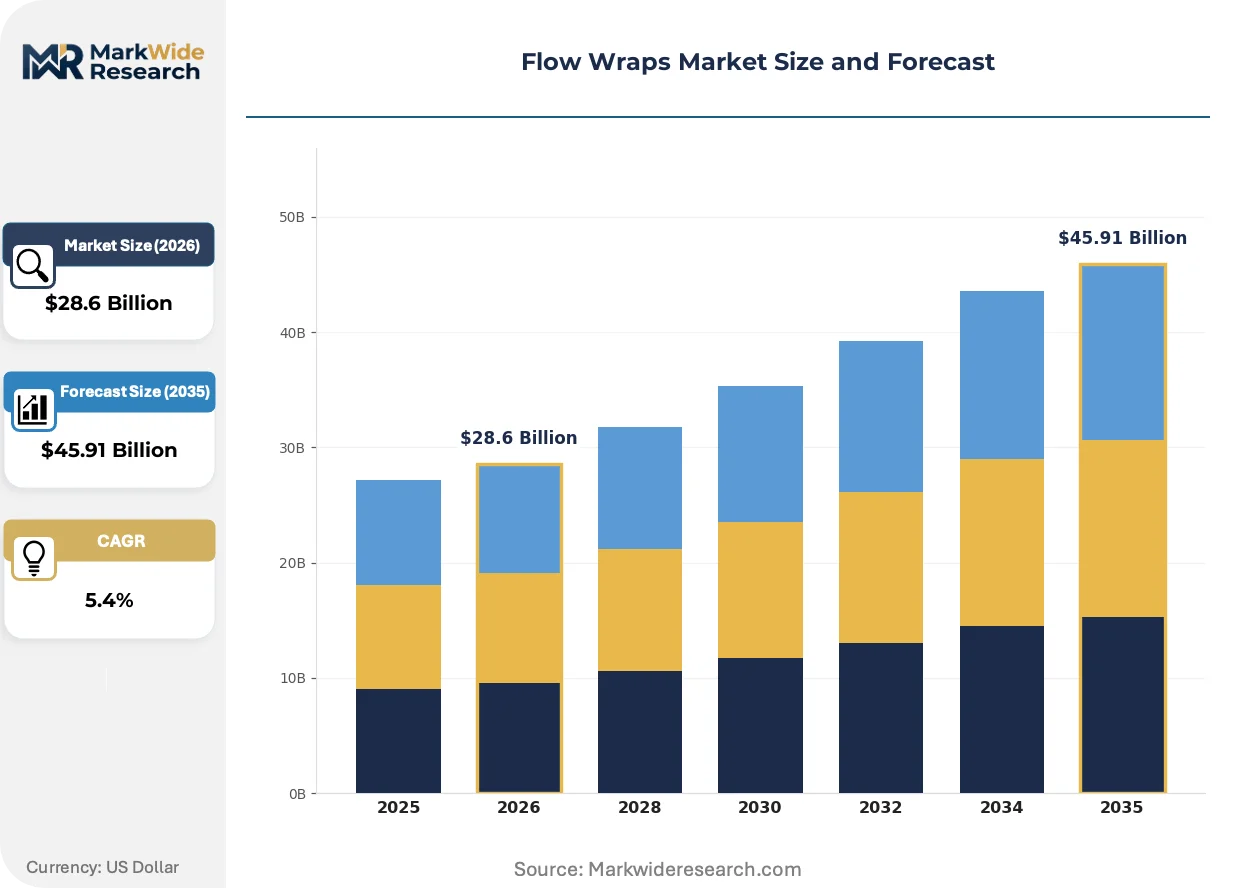
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate & Confectionery, Biscuits & Bakery, Frozen Food, Confectionery, Personal Care Technology: Horizontal Flow Wrapping, Vertical Flow Wrapping, Center Fold Wrapping, Overlap Wrapping, Continuous Motion Wrapping Application: Snack Packaging, Pharmaceutical Packaging, Cosmetic Packaging, Industrial Parts, Electronics Components End User: Food Processing Units, Pharmaceutical Manufacturers, Cosmetic Companies, Electronic Assemblers, Industrial Manufacturers |
| Companies Covered | Amcor plc, Constantia Flexibles Group, Huhtamäki OYJ, MONDI PLC, Sonoco Products Company, Sealed Air Corporation, Billerud AB, Winpak Ltd, KM Packaging Services Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Wraps Market Shifts & Advancements
Active and intelligent packaging integration is redefining flow wrap functionality beyond passive barrier protection. Film substrates now incorporate sensing, authentication, and communication capabilities that reshape value capture across pharmaceutical and food verticals.
Printed electronics on flexible substrates is miniaturizing. Conductive ink circuits and NFC antennas embed directly into oriented polyolefin webs, enabling unit-level traceability without secondary label application. Pharmaceutical manufacturers in Germany and the Netherlands are piloting these structures for anti-counterfeiting verification. The technology is miniaturizing authentication costs to pennies per package, collapsing the economic barrier to item-level serialization.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent manufacturing processes to convert. Extrusion lines historically dependent on hydrofluorocarbon cooling must retrofit to CO2 or ammonia-based systems, adding capital intensity for mid-scale converters. Chocolate and frozen food packaging operations in Northern Europe face the most compressed compliance timelines, with several facilities accelerating site consolidation to shared service centers.
Direct-to-retailer procurement contracts are consolidating specification authority. Major grocery chains in France and the United Kingdom now mandate film substrate certifications and carbon footprint disclosures upstream of traditional converter relationships. This bypasses legacy distributor networks and concentrates technical negotiation with packaging material scientists rather than commercial intermediaries. Snack and bakery verticals exhibit the most advanced contract restructuring, with annual renegotiation cycles replacing multi-year framework agreements.
Flow Wraps Market Segmentation
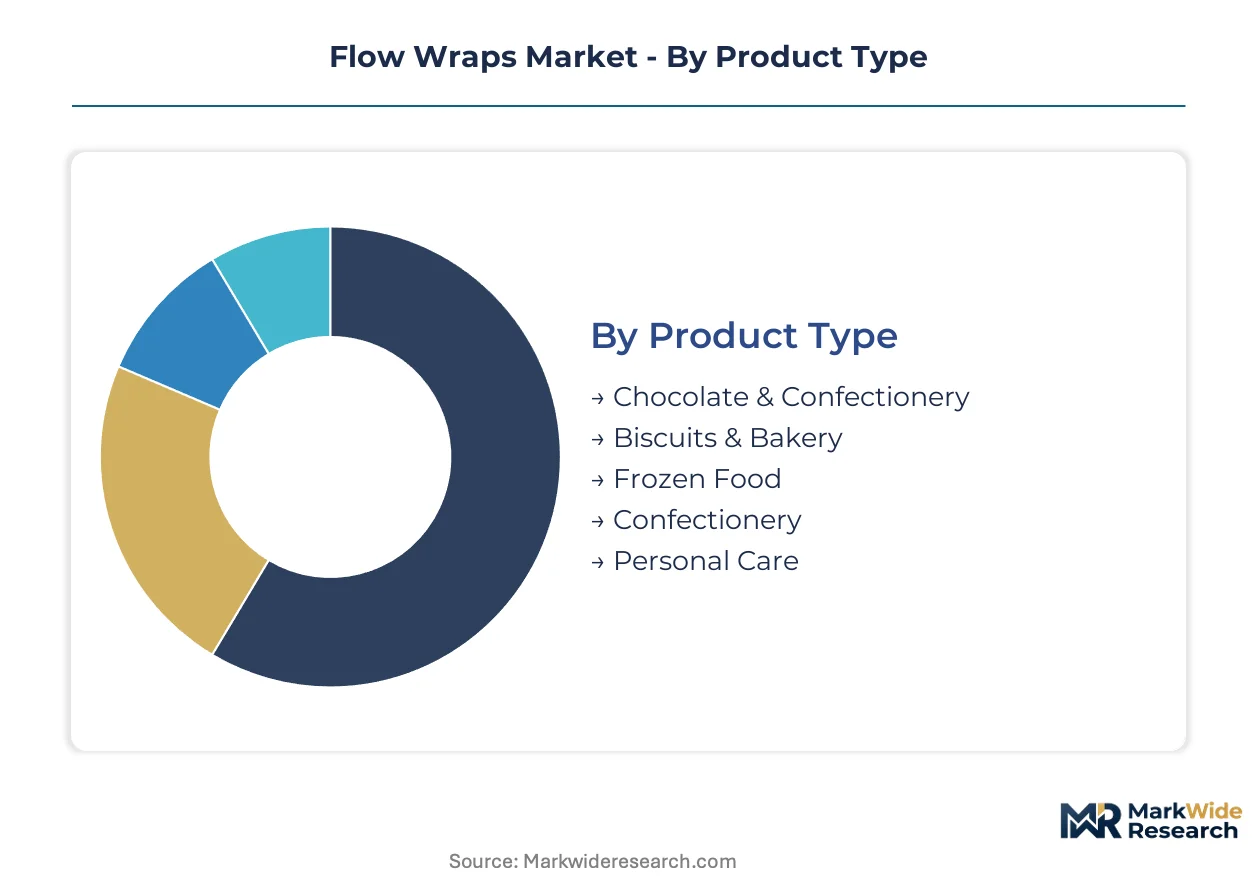
Flow wrap specification authority fragments across regulatory domains, with EMA sterile manufacturing rules governing pharmaceutical substrates while EU Green Deal carbon accounting reshapes food packaging procurement. Segmentation clarity determines converter capital allocation between barrier film investments and servo-driven line upgrades.
Product Type:
EMA Annex 1 sterile manufacturing updates and F-Gas Regulation phase-down schedules are bifurcating substrate requirements between pharmaceutical barrier films and confectionery print-registration specifications.
- Chocolate & Confectionery:Metallized and holographic finishes dominate Belgian and Swiss seasonal gift formats. Premium print-registration tolerances command specification premiums from Constantia Flexibles Group and specialized converters.
- Biscuits & Bakery:High-speed horizontal lines process oriented polyolefin webs at 300-450 packages per minute. German retail chains now mandate carbon footprint disclosures upstream of converter relationships.
- Frozen Food:Puncture-resistant films anchor Nordic retail shelf presence.
- Confectionery:Overlap exists with chocolate segment; distinct in sugar-based applications.
- Personal Care:Tamper-evidence and aesthetic finish requirements justify slower cycle rates than food applications.
Chocolate & Confectionery handles the majority of throughput; Frozen Food is expanding most quickly on share as Nordic retail consolidates around puncture-resistant specifications.
Technology:
Cost tier differentiation separates capital-intensive servo-driven systems from mechanical cam-driven legacy installations facing retrofit complexity.
- Horizontal Flow Wrapping:Rotary jaw mechanisms sustain 450 packages per minute on snack lines. Servo-driven sealing precision enables throughput gains without format changeover penalties for German and French producers.
- Vertical Flow Wrapping:Gravity-fed product insertion aligns with FDA validation protocols for pharmaceutical unit-dose compliance. EMA migration testing requirements extend qualification timelines to 18-24 months.
- Center Fold Wrapping:Cosmetic packaging applications prioritize aesthetic finish over speed.
- Overlap Wrapping:Niche applications in industrial segments.
- Continuous Motion Wrapping:Highest throughput category for mass-market snack volumes.
Horizontal Flow Wrapping commands installed base dominance; Vertical Flow Wrapping is gaining share fastest as pharmaceutical validation accelerates.
Application:
Customer type concentration varies sharply between direct-to-retailer procurement in snacks and specification-heavy pharmaceutical qualification cycles.
- Snack Packaging:Pre-made stand-up pouches with reclosure features capture shelf-stable share in German and French retail, displacing traditional flow wrap for certain categories. Annual renegotiation cycles now replace multi-year framework agreements.
- Pharmaceutical Packaging:High-barrier coextruded films face EMA-recognized analytical bottlenecks for extractables and leachables validation. Cold chain biologics applications create specification premiums for insulin and mRNA vaccine formats.
- Cosmetic Packaging:Tamper-evidence requirements dominate specification sheets.
- Industrial Parts:Durability and moisture protection drive substrate selection.
- Electronics Components:Anti-static and barrier properties required for sensitive assemblies.
Snack Packaging handles the majority of throughput; Pharmaceutical Packaging shows the steepest expansion trajectory as unit-dose sterile requirements tighten.
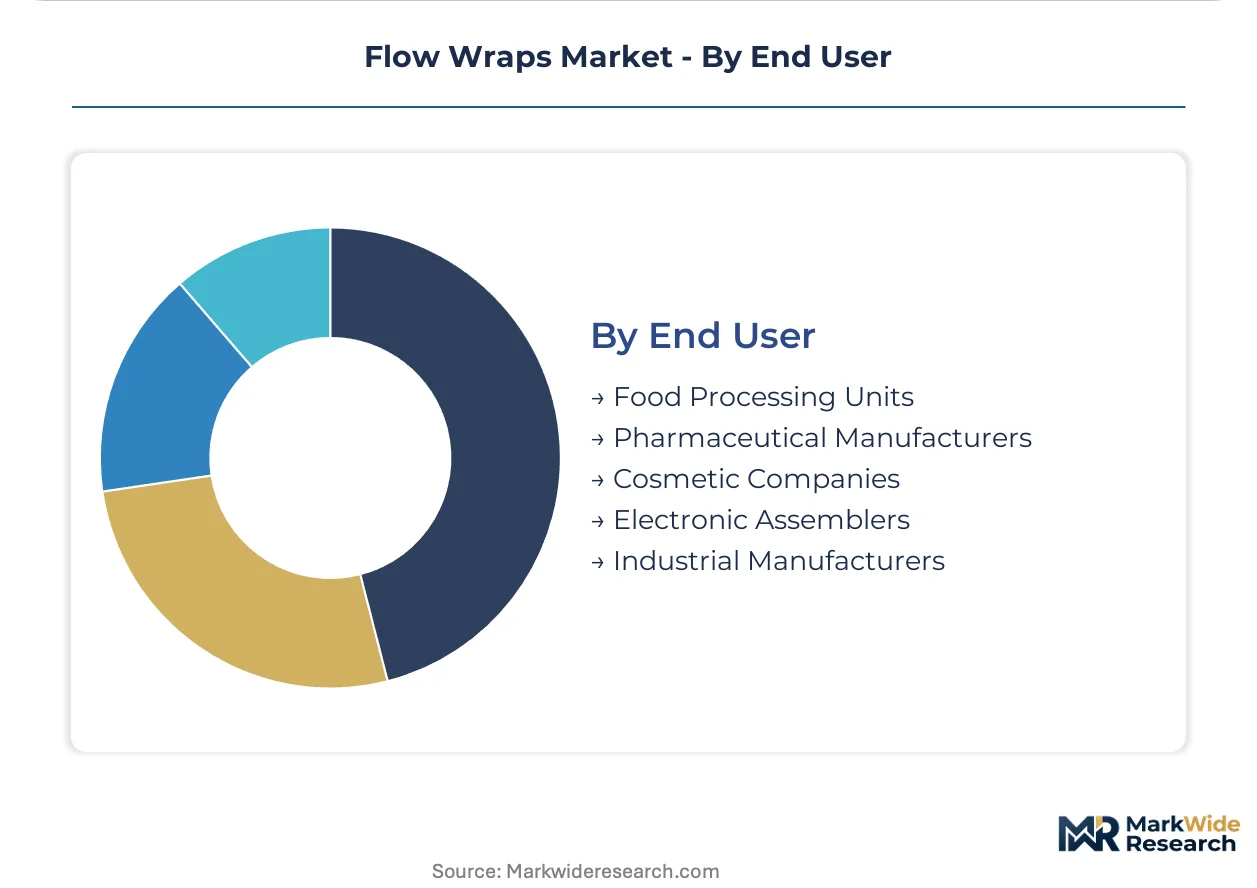
End User:
Geographic concentration of processing clusters determines converter site selection, with Frankfurt pharmaceutical packaging and Warsaw-Brno manufacturing expansion attracting greenfield investment.
- Food Processing Units:Direct-to-retailer procurement consolidation in France and United Kingdom bypasses legacy distributor networks. Technical negotiation now concentrates with packaging material scientists rather than commercial intermediaries.
- Pharmaceutical Manufacturers:Amcor plc sustains high-margin contracts across European sterile packaging lines through pharmaceutical certification network density. REACH SVHC restrictions on solvent-based laminating adhesives force capital-intensive system migrations.
- Cosmetic Companies:Premium finish requirements align with center fold wrapping technology.
- Electronic Assemblers:Cleanroom-compatible packaging specifications apply.
- Industrial Manufacturers:Volume procurement with lower barrier requirements than pharmaceutical or food segments.
Food Processing Units handle the majority of throughput; Pharmaceutical Manufacturers are climbing the fastest on share as sterile barrier specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main logistics corridor underwrites Germany's central role in European flow wrap distribution, connecting Frankfurt pharmaceutical clusters to Rotterdam-Antwerp resin supply chains.
Germany
Pharmaceutical packaging demand around Frankfurt and industrial confectionery operations anchor regional volume. The EU F-Gas Regulation compresses compliance timelines for extrusion cooling systems across Baden-Württemberg facilities. Bavarian frozen food processors specify puncture-resistant films for Nordic retail export.
United States
Snack producers operate high-speed horizontal lines exceeding 450 packages per minute. FDA validation protocols for pharmaceutical unit-dose compliance filter supplier qualification in New Jersey and North Carolina clusters. Midwest converter operations face ethylene feedstock volatility tied to Gulf Coast petrochemical capacity.
China
Domestic snack consumption drives horizontal flow wrap throughput in Yangtze River Delta manufacturing zones. NMPA pharmaceutical packaging material regulations shape substrate selection for export-oriented producers. Guangdong province converters retrofit solvent-based laminating adhesive systems under environmental enforcement tightening.
India
Unit-dose pharmaceutical packaging demand accelerates as CDSCO aligns with ICH quality guidelines. Maharashtra and Gujarat pharmaceutical clusters import high-barrier coextruded films pending domestic converter qualification. FSSAI food contact material notifications reshape confectionery packaging procurement in Mumbai-Pune industrial corridor.
Switzerland
Chocolate manufacturers specify metallized and holographic finishes for seasonal gift formats. Swissmedic pharmaceutical packaging regulations exceed EMA baseline requirements, extending validation timelines. Zurich-Basel corridor hosts specialized converters serving premium confectionery print-registration segments.
Flow Wraps Market Competitive Landscape
Listed leaders compete with private specialists across capital access and technical certification density. The vendor base clusters around three tiers: integrated multinationals with pharmaceutical certification networks, regional converters with frozen food or confectionery specialization, and private specialists serving niche pharmaceutical or cosmetic segments. Strategic archetypes include barrier film innovators, print-registration specialists, and cold-chain qualification leaders. Competitive moves concentrate on M&A for certification assets and greenfield capacity near Warsaw-Brno pharmaceutical clusters.
Within the integrated multinational tier, Amcor plc and Huhtamäki OYJ exemplify divergent specialization strategies. Amcor anchors pharmaceutical certification density across European sterile packaging lines. Huhtamäki occupies a position in frozen food puncture-resistant films serving Nordic retail concentration. Constantia Flexibles Group represents the print-registration specialist archetype, with Swiss and Belgian chocolate manufacturers driving premium specification demand.
| Leading Market Players |
|---|
| Amcor plc |
| Constantia Flexibles Group |
| Huhtamäki OYJ |
| MONDI PLC |
| Sonoco Products Company |
| Sealed Air Corporation |
| Billerud AB |
| Winpak Ltd |
| KM Packaging Services Ltd |
| Others |
Supply & Pricing Matrix
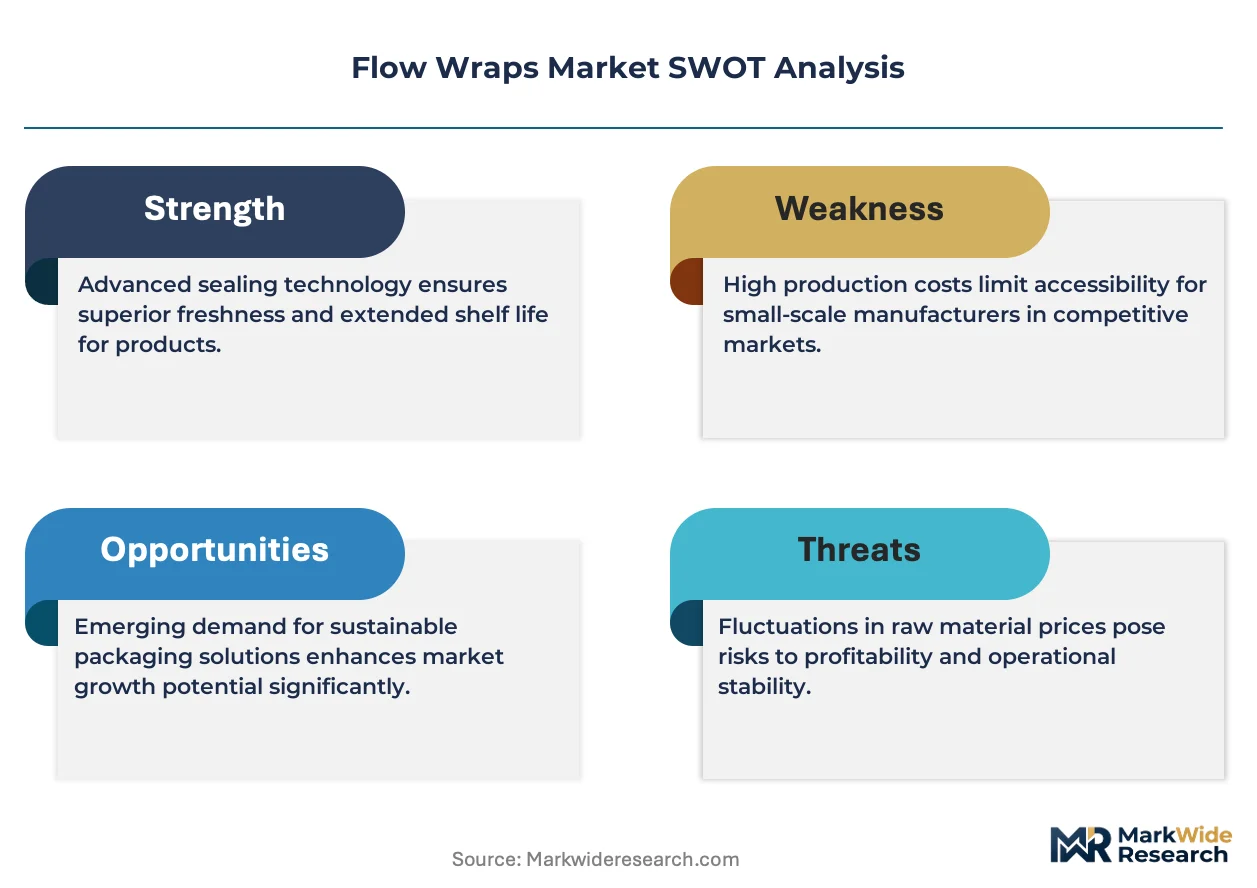
Rotterdam-Antwerp naphtha-cracker utilization rates above 85% compress polyolefin resin margins and establish price floors for European converter operations. Scale concentration in this petrochemical corridor funnels feedstock cost volatility directly into flow wrap substrate pricing, while smaller converters lack procurement leverage to buffer margin erosion.
Pricing Analysis
Volume-discount tiering structures stratify across pharmaceutical certification grade, with EMA-validated sterile barrier films commanding substantial premiums over standard food-grade specifications. Price differentiation hinges on migration testing documentation depth and carbon footprint disclosure granularity demanded by German and French retail chains. Cost compression in economy-tier snack packaging intensifies as pre-made stand-up pouches capture shelf-stable segments. Pharmaceutical manufacturers exhibit lowest price sensitivity due to regulatory compliance imperatives, while biscuit and bakery processors face acute margin pressure from direct-to-retailer procurement consolidation.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underscores ethylene feedstock exposure for European converters dependent on Middle Eastern naphtha supply. Manufacturing gravity centers on Germany, China, and the United States, with film extrusion capacity clustering around Rotterdam-Antwerp, Yangtze River Delta, and Gulf Coast petrochemical hubs. Raw material dependencies encompass oriented polyolefin resins, metallized film substrates, and solvent-free laminating adhesives. Single-source vulnerability concentrates in high-barrier coextruded film supply qualified for pharmaceutical validation. Distribution runs through converter-direct relationships increasingly bypassing legacy distributor networks in snack and bakery verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flow wrap incumbents face sustained substitution pressure from pre-made stand-up pouches with reclosure features capturing shelf-stable snack share in German and French retail channels.
For Market Incumbents: Secure EMA-recognized analytical capacity partnerships to compress pharmaceutical qualification timelines from 24 months toward industry benchmarks. Lock in backward integration into polyolefin resin supply through long-term offtake agreements with Rotterdam-Antwerp crackers, insulating margin structures from Q2-Q3 feedstock volatility. Pre-made pouch substitution in snacks demands format innovation investment to defend horizontal line throughput economics. For New Entrants and Emerging Players: Differentiate on pharma-grade recyclable monomaterial film development, targeting pending Extended Producer Responsibility fee differentials that will penalize multi-layer structures. Poland and Czech Republic greenfield sites near Warsaw-Brno pharmaceutical clusters offer penetrable geography with EU structural fund access. Cold chain biologics packaging for insulin and mRNA vaccine formats presents specification-premium entry angle with limited incumbent qualification density. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors servo-driven sealing system specialists over mechanical cam-driven legacy equipment operators facing retrofit complexity. Long-term viability across the analysis window rests on pharmaceutical certification network density and carbon-accounting disclosure capabilities. Acquisition targets should demonstrate EMA migration testing laboratory relationships or F-Gas Regulation-compliant extrusion cooling infrastructure. Watch for EMA Annex 1 sterile manufacturing update implementation pace as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Pharma-Grade Recyclable Monomaterial Film Development | Addresses EU Green Deal Extended Producer Responsibility fee structures before compliance deadlines tighten. |
| Servo-Driven Sealing System Retrofit | Enables 450 packages per minute throughput without format changeover penalties for German snack producers. |
| EMA-Recognized Analytical Laboratory Partnership | Compresses extractables and leachables validation timelines from 24 months for pharmaceutical qualification. |
| Poland-Czech Republic Greenfield Capacity | Accesses EU structural funds while serving Central European pharmaceutical and food processing clusters. |
| Cold Chain Biologics Packaging Qualification | Captures specification premiums for insulin and mRNA vaccine unit-dose formats requiring ultra-low temperature seal integrity. |
Research Methodology
A standing panel of pharmaceutical packaging engineers, frozen food procurement directors, confectionery brand managers, and flow wrap equipment OEM technical leads provided ongoing calibration across primary fieldwork. Secondary validation drew from EMA regulatory filings, EU F-Gas Regulation implementation schedules, REACH SVHC restriction updates, and customs data tracking oriented polyolefin resin trade flows through Rotterdam-Antwerp. Bottom-up segmentation modeling triangulated against top-down industry association capacity estimates.
Consistency checks validated volume and value outputs against external benchmarks including converter capacity utilization surveys and pharmaceutical packaging spend disclosures. The analytical framework modeled product type, technology, application, and end-user dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers and regulatory implementation timelines. Forecast inputs incorporated EMA Annex 1 sterile manufacturing update adoption curves and EU Green Deal carbon accounting disclosure mandates.
The analysis sits within stated boundaries; outcomes outside EMA migration testing laboratory capacity expansion or F-Gas Regulation compliance timeline acceleration would require recalibration. Forecasts reflect assumptions regarding polyolefin resin price stability and pharmaceutical unit-dose format adoption rates. Practitioners should keep alternative scenarios live as REACH adhesive reformulation costs and pre-made pouch substitution velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
EPE Liner Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Foam Bottle Technology Market
Packaging Materials
Reel in Box Market
Packaging Materials
GCC Disposables (Single-Use) Packaging Market
Packaging Materials
Urn Liners Market
Packaging Materials
Foil Laminates Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
Shrink Packaging Market
Packaging Materials
Packaging Lacquering Market