
 EPE Liner Market | 2026-2036
EPE Liner Market Size, Share, and Industry Trends Forecast 2026-2036
EPE Liner Market Foresight
Buyer concentration among industrial packaging purchasers is hardening as e-commerce fulfillment centers and automotive parts distributors consolidate vendor lists to reduce qualification overhead. Sealed Air Corporation leverages its global manufacturing footprint to serve these consolidated accounts with standardized liner programs. Pregis Corporation differentiates through specialized heavy-duty liner configurations for aerospace and medical device segments. Kaneka anchors Asian supply chains with captive EPE foam resin production.
Expanded polyethylene (EPE) liner denotes a closed-cell foam cushioning insert manufactured through physical or chemical foaming of low-density polyethylene, typically exhibiting densities between 20-100 kg/m³ and compression set resistance below 10 percent. These liners absorb impact energy during transit, protecting fragile goods from shock and vibration damage across temperature ranges of -60°C to 80°C. Custom liners command premium positioning due to die-cut complexity and short-run tooling requirements, while standard liners compete on throughput scale for high-volume agricultural storage applications. Heavy-duty liners incorporating reinforced plastics or laminated barrier films capture margin pools in hazardous material containment and long-cycle industrial packaging.
The EPA's Resource Conservation and Recovery ActSubtitle D criteria govern liner permeability and thickness minimums for waste disposal applications in the United States, directly specifying EPE composite structures for secondary containment. REACH registration requirements and the EU Green Deal's packaging waste directives in Europe restrict certain blowing agents and mandate recyclability disclosures for EPE foam products sold into member states. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments in one geography may not transfer to emerging standards elsewhere.
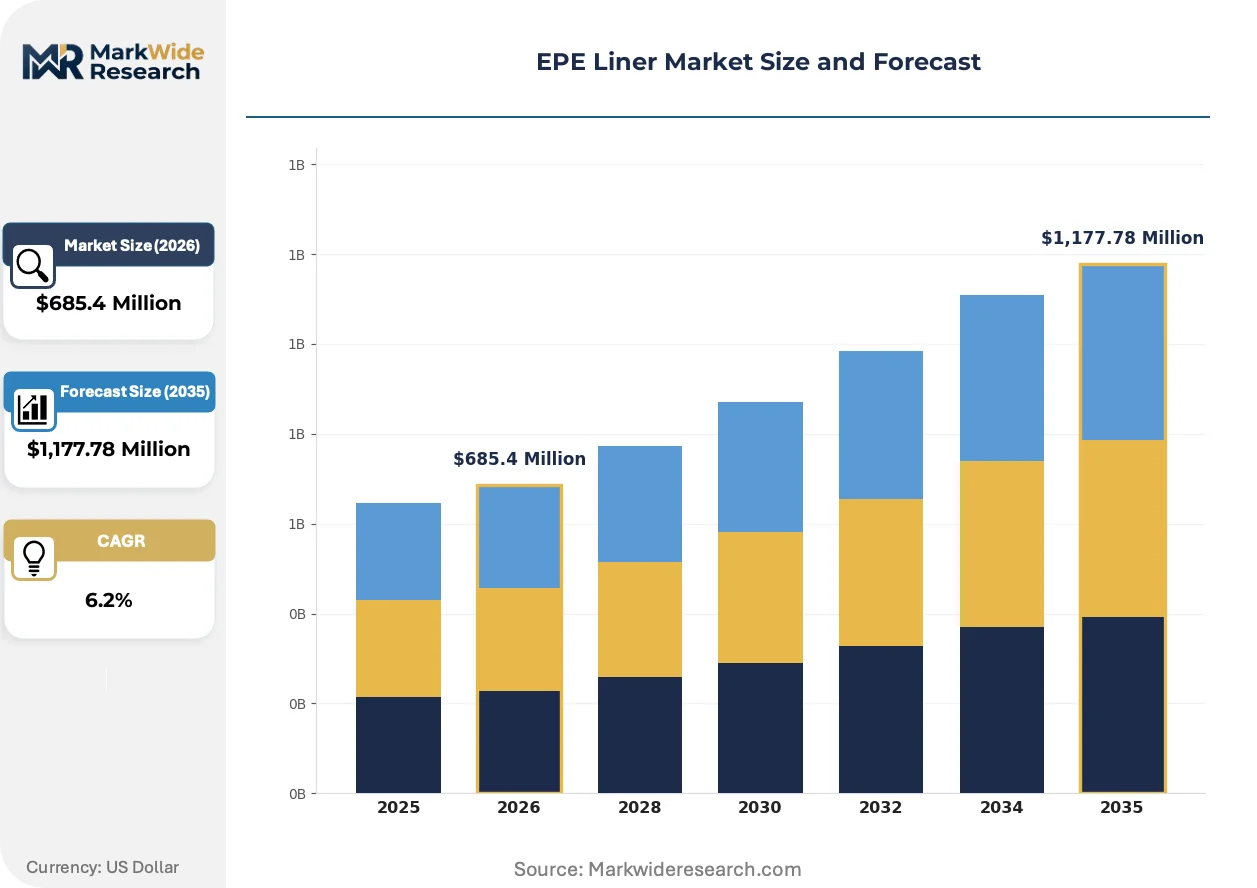
Market Dynamics
Industrial packaging buyers are consolidating procurement volumes around fewer suppliers while REACH compliance in Europe and evolving EPA landfill liner standards in the United States simultaneously tighten material specifications. This dual pressure of buyer concentration and regulatory escalation compresses margin tolerance for mid-tier producers.
Growth Catalysts
- Automotive Export Surge:Electronics and automotive exports from China's manufacturing belt require premium cushioning solutions with compression set resistance below 10 percent.
- EPA Subtitle D Criteria:The Resource Conservation and Recovery Act mandates EPE composite structures for secondary containment in waste disposal applications, locking in material demand.
- Physical Foaming Advancement:Low-density polyethylene foaming processes now achieve densities between 20-100 kg/m³ with improved temperature stability from -60°C to 80°C.
Market Restraints
- Blowing Agent Restrictions:REACH registration requirements and EU Green Deal packaging waste directives restrict certain chemical blowing agents, forcing reformulation investments.
- Resin Supply Concentration:Captive EPE foam resin production in Asia creates dependency on a narrow supplier base for non-integrated converters.
- Paper-Based Substitution:Molded pulp and corrugated fiber alternatives gain traction in agricultural storage applications where throughput scale matters more than cushioning performance.
Strategic Opportunities
- Hazardous Material Containment:Heavy-duty liners incorporating reinforced plastics or laminated barrier films capture margin pools in long-cycle industrial packaging with limited competition.
- EU Recyclability Mandates:The EU Green Deal's packaging waste directives create first-mover advantage for producers with validated closed-loop recycling pathways and material passports.
- Medical Device Cold Chain:Specialized heavy-duty liner configurations for temperature-sensitive pharmaceutical distribution represent an underpenetrated premium segment.
Industry Challenges
- Die-Cut Tooling Turnaround:Custom liners require short-run tooling with complexity that strains production scheduling and compresses quoting windows.
- Cross-Border Compliance Transferability:Investments in EPA-compliant composite structures do not automatically satisfy REACH registration requirements, forcing duplicate certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EPE Liner Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Liners, Custom Liners, Heavy-Duty Liners, Lightweight Liners Application: Agricultural Storage, Industrial Packaging, Waste Disposal, Water Management Material: EPE Foam, LDPE, HDPE, Reinforced Plastics End User: Agriculture, Construction, Waste Management, Environmental Services |
| Companies Covered | Tri-SEAL, Sonoco, Kaneka, Captel International Private, Rhyno Flexipack, Ziling Packaging, Sansheng, Sealed Air Corporation, Pregis Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPE Liner Market Shifts & Advancements
Material science advances and regulatory fragmentation are simultaneously expanding performance boundaries and complicating certification pathways. Producers must now engineer for multi-jurisdictional compliance while differentiating through functional specialization.
Multi-layer coextrusion with embedded barrier films is electrifying the heavy-duty liner category by enabling simultaneous chemical resistance and impact absorption. Aerospace parts distributors and medical device manufacturers are adopting these configurations fastest, demanding liners that survive both drop testing and prolonged exposure to hydraulic fluids or sterilants. This capability expansion is compressing the addressable market for single-material EPE in premium applications.
REACH registration requirements and the EU Green Deal's packaging waste directives are tightening material specifications across European member states. ECHA now mandates recyclability disclosures for EPE foam products, forcing producers to document post-consumer pathways or face market exclusion. Custom liner specialists with established take-back programs are capturing specification authority from commodity producers.
Consolidated procurement among e-commerce fulfillment centers is compressing vendor qualification cycles and demanding standardized liner programs across multiple distribution nodes. Automotive parts distributors now require single-source accountability for cushioning performance across temperature extremes. This concentration is most visible in Germany and the United States, where fulfillment network density supports centralized purchasing authority.
EPE Liner Market Segmentation
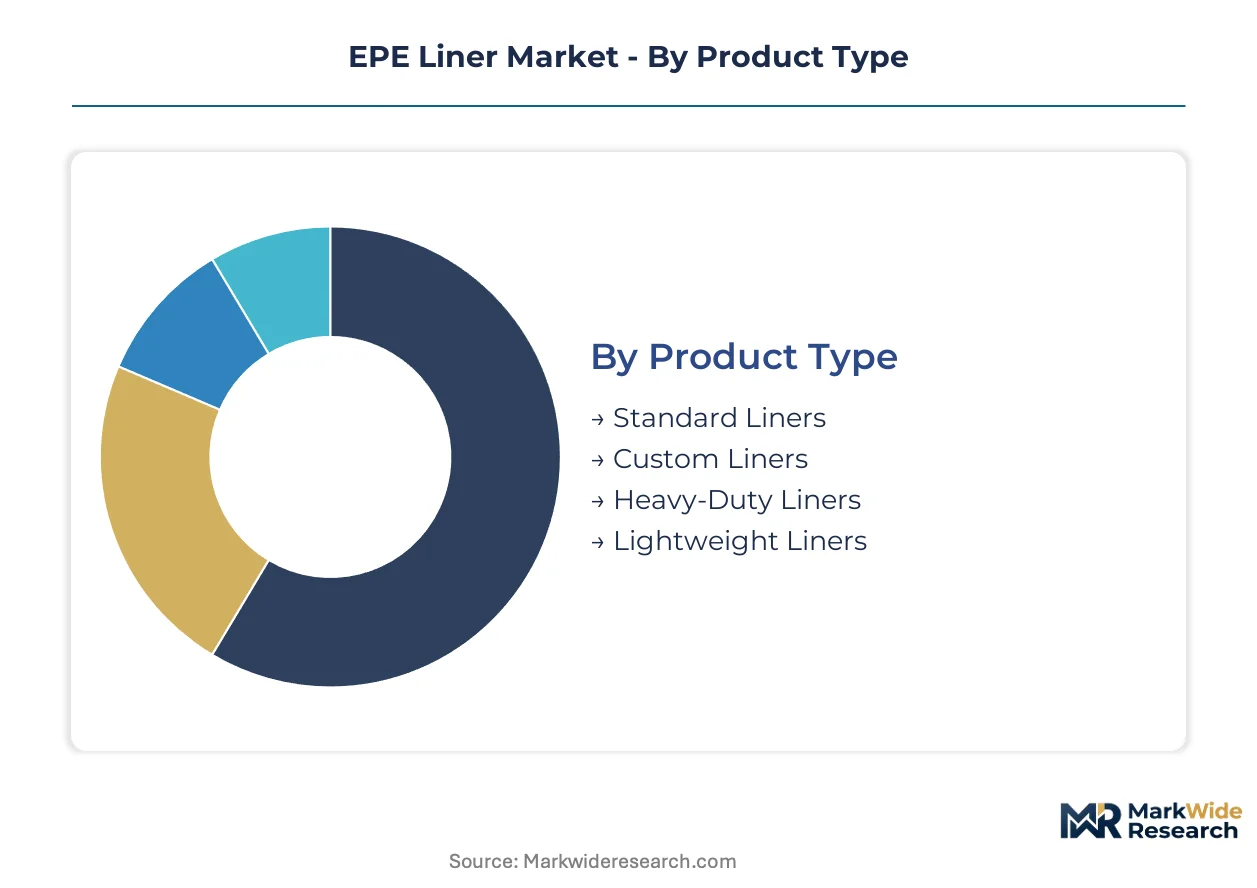
EPE liner procurement patterns diverge sharply across product tiers and application contexts, with specification complexity driving supplier selection criteria. Understanding segment boundaries reveals where margin pools concentrate versus where throughput scale dominates competitive positioning.
Product Type:
Replacement cycles vary dramatically by liner durability tier, with heavy-duty configurations outlasting standard alternatives by multiples while custom solutions face obsolescence from design changes.
- Standard Liners:These closed-cell foam inserts utilize low-density polyethylene foaming at 20-50 kg/m³ densities for general cushioning applications. Agricultural storage buyers in the US Midwest and Central Plains specify these for bulk grain protection where throughput scale outweighs performance differentiation.
- Custom Liners:Die-cut configurations with compression set resistance below 10 percent serve electronics and automotive exporters from China's manufacturing belt. Short-run tooling requirements and design complexity command premium positioning despite constrained production scheduling.
- Heavy-Duty Liners:Reinforced plastics or laminated barrier films enable hazardous material containment with temperature stability from -60°C to 80°C. Aerospace parts distributors and medical device manufacturers specify these for long-cycle industrial packaging.
- Lightweight Liners:Reduced-density EPE foam targets e-commerce fulfillment centers where shipping weight directly impacts logistics costs. These configurations sacrifice some impact absorption for dimensional efficiency.
Standard liners sit at the top of the volume ranking, with heavy-duty liners climbing the fastest as hazardous material regulations tighten.
Application:
Cost tier segmentation separates commodity-specified applications from engineered-performance contexts where failure carries regulatory or liability consequences.
- Agricultural Storage:High-volume grain and produce protection relies on throughput-scaled liner procurement. Molded pulp alternatives from corrugated fiber producers are gaining traction where cushioning performance matters less than cost minimization.
- Industrial Packaging:Automotive parts distributors and electronics exporters demand compression set resistance and temperature stability across distribution nodes. Consolidated procurement among fulfillment centers compresses vendor qualification cycles.
- Waste Disposal:EPA Subtitle D criteria mandate EPE composite structures for secondary containment in US landfill applications. Permeability and thickness minimums lock in material demand regardless of price fluctuations.
- Water Management:Containment and seepage control applications specify liners with barrier film lamination. Infrastructure investment cycles in municipal and industrial water systems drive project-based demand.
Industrial packaging commands the largest revenue pool, with waste disposal expanding most quickly as EPA enforcement intensifies.
Material:
Supply concentration around captive resin production in Asia creates dependency structures that favor integrated converters over merchant buyers.
- EPE Foam:Closed-cell expanded polyethylene manufactured through physical or chemical foaming dominates cushioning applications. REACH registration requirements and EU Green Deal packaging waste directives restrict certain blowing agents, forcing reformulation investments.
- LDPE:Low-density polyethylene serves as the base resin for standard and lightweight liner configurations. Density ranges of 20-100 kg/m³ accommodate diverse application requirements.
- HDPE:High-density polyethylene provides structural rigidity in heavy-duty composite constructions. Less common as a primary liner material but critical in reinforced multi-layer systems.
- Reinforced Plastics:Embedded barrier films and fiber reinforcement enable simultaneous chemical resistance and impact absorption. Kaneka's captive production in Japan anchors Asian supply chains for these specialized grades.
EPE foam dominates absolute volume, with reinforced plastics gaining share fastest in aerospace and medical device segments.
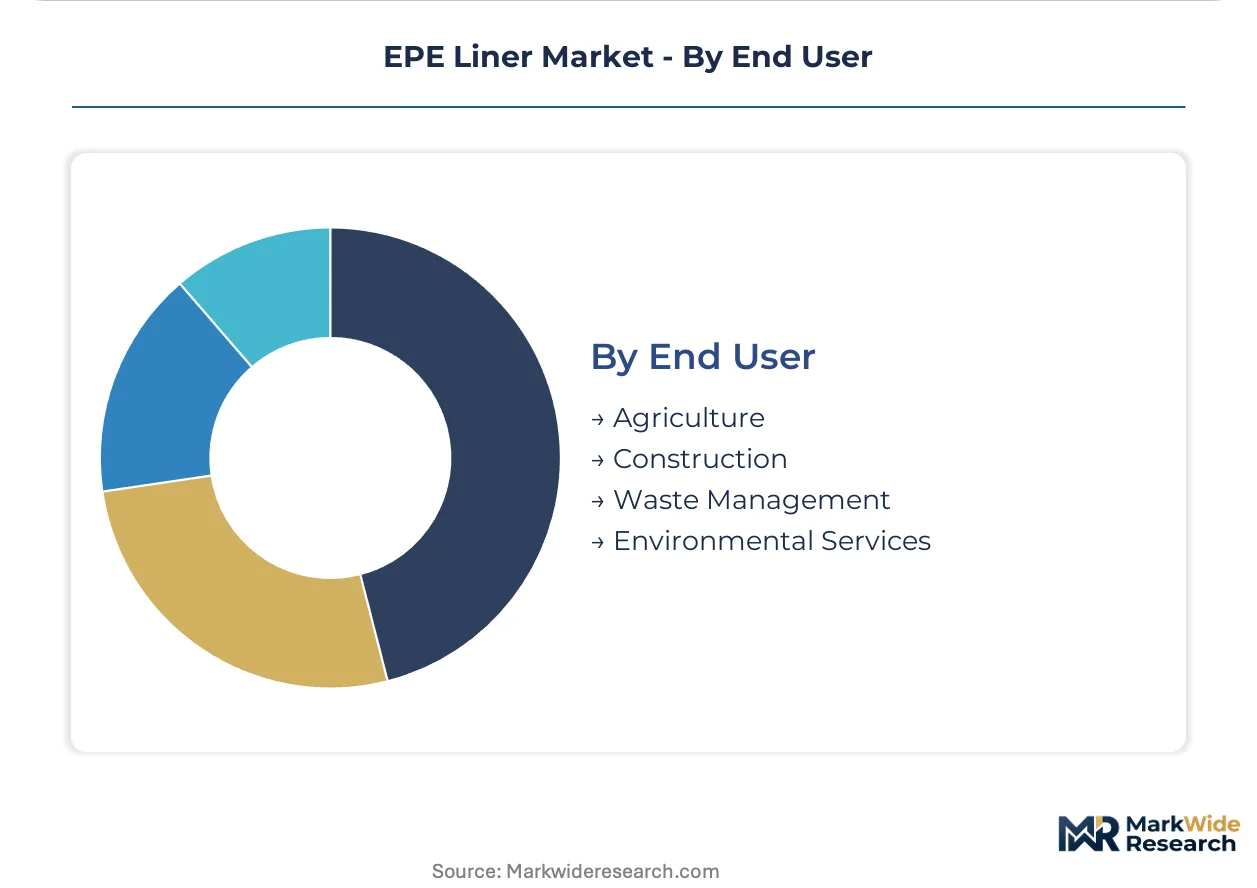
End User:
Customer type segmentation separates price-sensitive commodity buyers from specification-driven engineered purchasers with extended qualification horizons.
- Agriculture:Grain elevators, produce distributors, and food processors prioritize throughput scale and cost minimization. Paper-based substitution threatens EPE penetration in this segment.
- Construction:Building material protection and temporary containment applications specify liners for moisture and impact protection. Project-based demand tracks regional construction cycles.
- Waste Management:Landfill operators and hazardous waste handlers face EPA Subtitle D compliance mandates. Liner permeability specifications create captive demand for certified composite structures.
- Environmental Services:Remediation and containment contractors require validated performance documentation for regulatory submission. Custom liner specialists with established take-back programs capture specification authority.
Waste management generates the steadiest demand trajectory, with environmental services showing the steepest expansion as remediation obligations accumulate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing belt generates premium liner demand for automotive and electronics exports, while Germany's automotive supply chain imposes stricter REACH compliance requirements on cushioning specifications.
United States
Automotive parts distributors consolidate vendor lists across Midwest and Southeast fulfillment networks. EPA Subtitle D criteria mandate EPE composite structures for secondary containment in Texas and California landfill operations. Houston's petrochemical corridor anchors heavy-duty liner production for hazardous waste applications.
China
Electronics exporters in the Yangtze River Delta and Pearl River Delta require compression set resistance below 10 percent for premium cushioning. MIIT's evolving packaging standards and dual carbon goals restrict certain foaming processes. Shenzhen and Suzhou manufacturing clusters drive specification authority for custom die-cut configurations.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg demand temperature-stable liners from -60°C to 80°C for component distribution. ECHA's REACH registration requirements and EU Green Deal packaging waste directives restrict blowing agent formulations. Stuttgart's supplier engineering centers qualify liners for pan-European supply chains.
Japan
Medical device manufacturers in Kansai and automotive suppliers in Chubu specify heavy-duty liners with barrier film lamination. METI's chemical substance management framework and JIS standards govern material traceability. Nagoya's industrial packaging cluster concentrates aerospace-grade liner fabrication.
India
Pharmaceutical cold chain distributors in Maharashtra and Gujarat adopt specialized liner configurations for temperature-sensitive shipments. BIS certification requirements and CDSCO medical device regulations drive quality documentation. Mumbai-Pune corridor's logistics hubs consolidate procurement for generic drug exports.
EPE Liner Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated resin-to-liner producers capturing Asian supply chains, specialized custom fabricators serving aerospace and medical segments, and scale-driven commodity suppliers for agricultural storage. M&A activity concentrates on regional converter networks, while technology licensing agreements proliferate for physical foaming process improvements.
Among North American packaging conglomerates, Sealed Air Corporation and Pregis Corporation exemplify divergent positioning archetypes. Sealed Air leverages global manufacturing footprints to serve consolidated e-commerce accounts with standardized programs. Pregis occupies a position within specialized heavy-duty configurations for aerospace and medical device segments. Kaneka anchors the integrated producer tier through captive EPE foam resin production in Japan.
| Leading Market Players |
|---|
| Tri-SEAL |
| Sonoco |
| Kaneka |
| Captel International Private |
| Rhyno Flexipack |
| Ziling Packaging |
| Sansheng |
| Sealed Air Corporation |
| Pregis Corporation |
| Others |
Supply & Pricing Matrix
EU Green Deal packaging waste directives gate both qualified supply and premium-tier pricing access for EPE liner producers, forcing recyclability documentation as a condition of market entry while compressing margin tolerance for non-compliant converters. Buyers with validated closed-loop pathways command specification authority and pricing premiums, while commodity producers face exclusion from European procurement lists.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for standard liner grades, intensifying competition in agricultural storage applications where throughput scale outweighs performance differentiation. Three-tier pricing structure across premium, standard, and economy levels separates heavy-duty barrier-laminated configurations from die-cut custom solutions and bulk agricultural grades. Pricing pressure stems from paper-based substitution in grain protection, with molded pulp alternatives eroding EPE share where cushioning performance matters less than cost minimization. Agricultural buyers exhibit highest price sensitivity, while aerospace and medical device manufacturers accept premium positioning for validated temperature stability and chemical resistance.
Supply Chain Analysis
EPE foam resin supply rests on captive production in Japan, South Korea, and China, creating dependency structures that favor integrated converters over merchant buyers. Low-density polyethylene feedstock, chemical blowing agents, and barrier film laminates constitute critical input tiers, with REACH restrictions on certain foaming chemicals forcing reformulation investments. Single-source vulnerability concentrates in Asian resin supply, where non-integrated converters lack upstream control over material qualification. Distribution runs through automotive parts distributors and e-commerce fulfillment centers that consolidate procurement volumes across multiple nodes, compressing vendor qualification cycles and demanding standardized programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPE liner markets offer margin-expansion pathways through heavy-duty configuration premiums and regulatory compliance barriers that screen out commodity competitors. Physical foaming process improvements and closed-loop recycling investments represent the primary cost-down and premium-tier shift levers.
For Market Incumbents: Acquire regional converter networks in Germany and the US Midwest to anchor consolidated procurement relationships with automotive distributors and agricultural buyers. Incumbent producers must deepen backward integration into captive resin production to offset Asian supply concentration, while investing in multi-layer coextrusion capabilities for aerospace and medical device specifications. Paper-based substitution in agricultural storage threatens volume-based producers who lack premium-tier diversification. For New Entrants and Emerging Players: Pharmaceutical cold chain distributors in India and environmental services contractors in Europe represent the most penetrable white-space targets, with limited incumbent specialization in temperature-validated liner configurations. New entrants should pursue technology licensing agreements for physical foaming process improvements rather than greenfield resin production, leveraging established material science partnerships to bypass capital-intensive integration requirements. Regulatory documentation capabilities differentiate specification authority from commodity positioning. For Investors and Strategic Acquirers: Roll-up economics work for custom liner fabricators with established take-back programs because EU Green Deal mandates create irreversible demand for recyclability-validated suppliers. The 5-10 year viability window favors producers with demonstrated closed-loop pathways and material passport systems over commodity converters facing margin compression. Watch EPA enforcement intensity in US landfill applications as the signal for heavy-duty liner demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive EPE foam supply insulates against Asian supply concentration and REACH reformulation costs. |
| Multi-Layer Coextrusion Capacity Addition | Barrier film lamination captures aerospace and medical device premiums with limited competition. |
| Closed-Loop Recycling Program Launch | EU Green Deal compliance creates specification authority and pricing power in European markets. |
| Regional Converter Network Acquisition | Midwest and German automotive clusters anchor consolidated procurement relationships. |
| Physical Foaming Process Licensing | Technology partnerships enable density and temperature stability improvements without capital intensity. |
Research Methodology
Direct dialogue with plant managers at EPE foam converters, procurement leads at automotive parts distributors, technical R&D directors at resin producers, and channel partners in industrial packaging distribution grounded this analysis. Secondary validation drew from EPA Subtitle D regulatory filings, ECHA REACH registration databases, customs and trade data for polyethylene foam imports, and SEC 10-K disclosures from diversified packaging conglomerates. Bottom-up demand modeling across application segments triangulated against top-down supply-side capacity assessments.
Bottom-up segment modeling tracked product type, application context, material grade, and end-user industry across the projection horizon, with value outputs reconciled against resin production capacity and converter throughput data. CAGRs derived from segment-level volume trajectories weighted by pricing tier concentration, incorporating physical foaming technology diffusion rates and regulatory compliance cost pass-through assumptions. Temperature stability requirements and chemical resistance specifications provided industry-specific forecast anchors for heavy-duty liner demand.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH blowing agent restrictions, EPA enforcement variability, and paper-based substitution acceleration in agricultural applications. Forecasts reflect documented assumptions regarding resin supply concentration and regulatory divergence between jurisdictions. Material deviation in EU Green Deal implementation timelines or sudden shifts in automotive export patterns from China's manufacturing belt warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Foam Trays Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Coconut Wraps Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Fiber Lids Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
Disposable Icepacks Market