
 Expendable Packaging Market | 2026-2036
Expendable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Expendable Packaging Market Analysis
The capital-intensity divergence between integrated paperboard producers and specialty converters is collapsing as automated corrugation lines lower entry barriers for mid-scale operators. Smurfit Kappa Group leverages its European mill network to sustain integrated containerboard supply. Mondi Group anchors its position through kraft paper specialization in industrial wrap segments. Sealed Air Corporation differentiates via engineered foam and inflatable protective systems for electronics end users.
Expendable packaging denotes single-use or limited-reuse containment and protective materials designed for product distribution, typically manufactured from corrugated fiberboard, molded pulp, expanded polystyrene, or polyethylene films with basis weights ranging from 23 to 450 grams per square meter depending on load-bearing requirements. Its primary purpose is to ensure product integrity through transit while minimizing unit cost per shipment. Corrugated boxes occupy the largest value share across food and beverage distribution channels where stack strength and printability drive procurement decisions. Plastic-based wraps and bags represent the fastest-expanding material category within e-commerce fulfillment as stretch film and mailer pouch volumes scale with parcel throughput. Foam trays retain concentrated margin pools in pharmaceutical cold chain applications where thermal insulation performance justifies premium positioning.
The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes and minimum recycled content thresholds that reshape material selection across cardboard and plastic segments. REACH compliance and FSC chain-of-custody certification further constrain supply base qualification for consumer goods and electronics exporters. The US EPA sustainable materials management framework and state-level extended producer responsibility laws in California and Maine introduce parallel compliance layers for multinational suppliers. Stakeholders must monitor regulatory divergence between European harmonized standards and fragmented US state-level rules when configuring regional manufacturing footprints and material sourcing strategies.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles across the expendable packaging sector as recyclability mandates force simultaneous material substitution and supply base requalification.
Growth Catalysts
- E-commerce parcel throughput:Fulfillment centers in Germany and the Netherlands are scaling corrugated box consumption to match same-day delivery velocity requirements.
- REACH compliance thresholds:Chemical safety documentation is filtering out non-compliant converters, concentrating procurement among certified suppliers.
- Molded pulp thermal protection:Cold chain pharmaceutical distributors are adopting fiber-based insulation as polystyrene alternatives meet EFSA contact-material standards.
Market Restraints
- Containerboard input cost volatility:OCC (old corrugated containers) price swings in European spot markets compress converter margins without pass-through mechanisms.
- Supply concentration in Nordic kraft pulp:Integrated producers control 60% of virgin fiber supply to the region, limiting negotiating leverage for independent converters.
- Technical limitation in barrier coatings:Water-based grease barriers for food contact applications fail moisture resistance tests against polyethylene laminates, restricting paperboard penetration in wet-food segments.
Strategic Opportunities
- Underpenetrated Polish fulfillment infrastructure:Central European distribution hubs are consolidating warehouse capacity without matching packaging supply localization.
- Regulatory tailwind from EU Green Deal:Carbon border adjustment mechanisms will penalize imported plastic-based protective packaging, favoring regional fiberboard producers.
- Technology convergence of digital print and short-run corrugation:Hybrid presses enable batch-size-one production for seasonal promotional packaging without plate costs.
Industry Challenges
- Skill gap in automated corrugation line operation:Maintenance technicians familiar with legacy BHS and Fosber systems command wage premiums that mid-scale converters struggle to match.
- Capex intensity for ECT (edge crush test) certification:Laboratory equipment and third-party validation cycles delay new product introductions by 4-6 months.
- Integration complexity with WMS (warehouse management system) protocols:Packaging specifications must synchronize with automated dimensioning and sortation equipment deployed by major retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expendable Packaging Market |
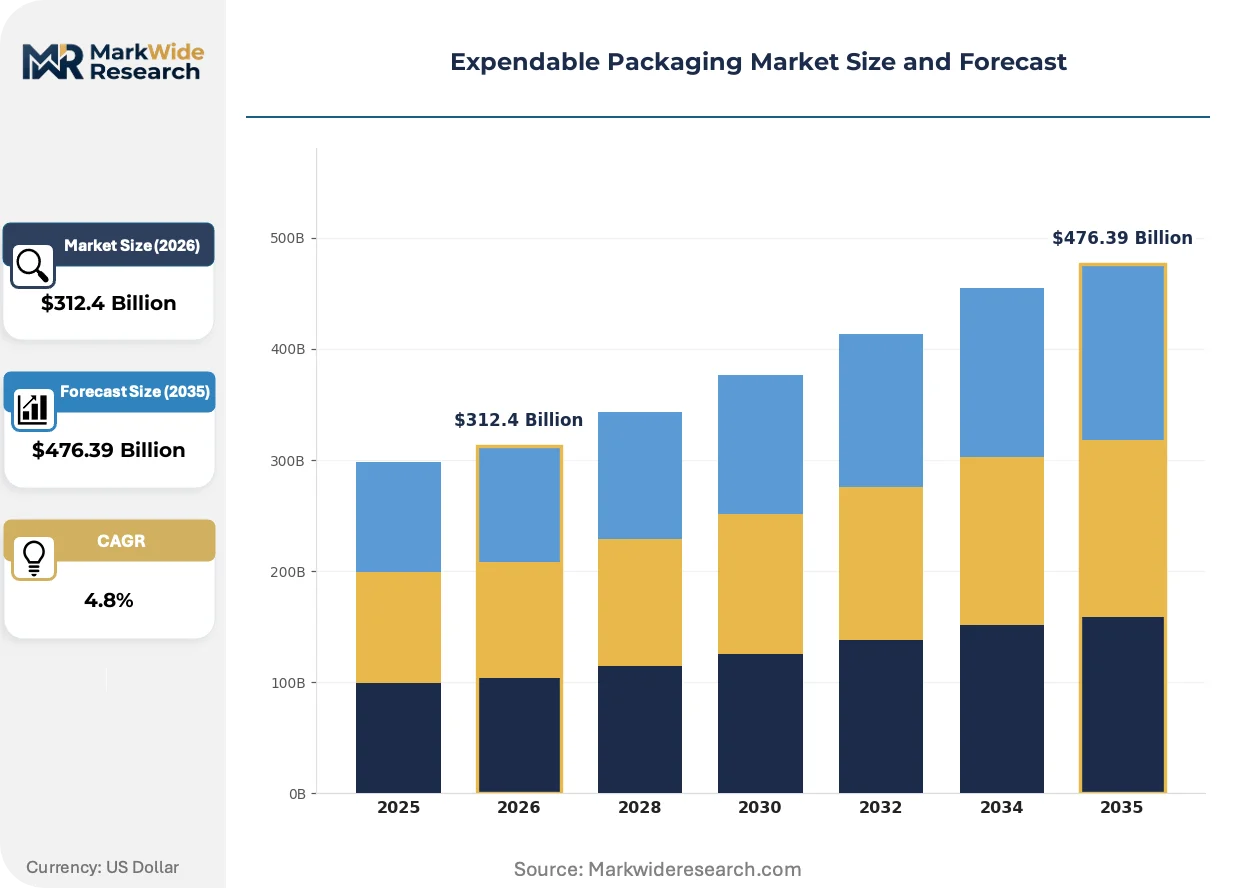
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $476.39 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
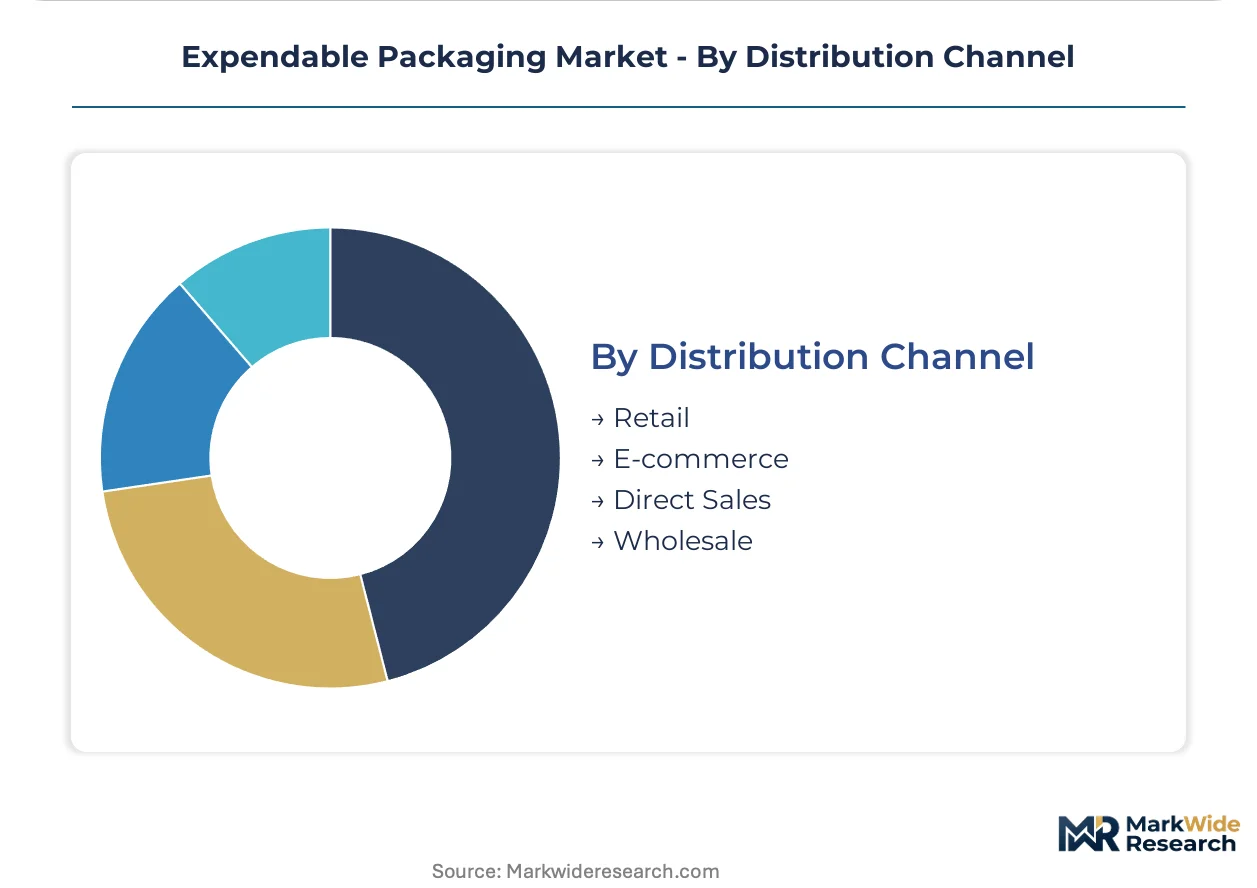
| Segmentation | Product Type: Boxes, Trays, Bags, Wraps Material: Cardboard, Plastic, Paper, Foam End User: Food & Beverage, Consumer Goods, Electronics, Pharmaceuticals Distribution Channel: Retail, E-commerce, Direct Sales, Wholesale |
| Companies Covered | Amcor plc, Sealed Air Corporation, Berry Global Inc., Mondi Group, Smurfit Kappa Group, DS Smith Plc, WestRock Company, International Paper Company, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expendable Packaging Market Emerging Trajectories
Material science advances and regulatory compression are converging to redefine performance benchmarks across protective and containment applications.
Barrier-coated paperboard engineered for direct food contact is supplanting polyethylene-lined alternatives in chilled ready-meal distribution. Retailers in France and Belgium are mandating plastic-free shelf-ready packaging by 2026. This shift is compressing converter R&D timelines while opening margin pools for coating technology licensors.
REACH substance restrictions on per- and polyfluoroalkyl substances (PFAS) are eliminating oil-and-grease-resistant treatments from pizza box and bakery packaging supply chains. German converters are accelerating fluorine-free alternative qualification with ECHA guidance. The substitution pressure falls heaviest on quick-service restaurant supply contracts where product safety documentation must update before contract renewal cycles.
Consolidated procurement by omnichannel retailers is compressing supplier panels and extending quality audit requirements to tier-two raw material sources. Electronics manufacturers now mandate FSC chain-of-custody verification through molded pulp tray suppliers. The Netherlands and Germany exhibit the most advanced buyer concentration, with three retail groups controlling 40% of corrugated specification authority.
Expendable Packaging Market Segmentation

Segmentation in expendable packaging reveals how material substitution pressures and channel migration reshape procurement priorities. Understanding these fault lines enables suppliers to align capacity investments with the fastest-shifting demand pockets.
Product Type:
Corrugated boxes face intensifying substitution from mailer pouches in lightweight e-commerce, while foam-dependent segments confront regulatory phase-outs.
- Boxes:Corrugated fiberboard containers with ECT ratings from 23 to 55 lb/in dominate food and beverage distribution networks. German retailers specify stack strength thresholds that favor double-wall construction for palletized shipments.
- Trays:Molded pulp and expanded polystyrene formats provide structural protection for electronics and pharmaceutical cold chain. EFSA contact-material standards are accelerating fiber-based adoption in meal-kit delivery across France and Belgium.
- Bags:Polyethylene mailer pouches and paper-based alternatives serve single-item e-commerce fulfillment. Stretch film variants secure palletized loads in wholesale distribution.
- Wraps:Protective cushioning materials including bubble film, kraft paper dunnage, and inflatable systems fill void spaces in parcel containers. Electronics manufacturers in the Netherlands specify anti-static properties for semiconductor shipments.
Boxes anchor the volume base while Wraps gains share at the steepest rate.
Material:
Cost tier stratification separates commodity fiberboard from specialty barrier coatings and engineered foams with divergent margin structures.
- Cardboard:Recycled and virgin containerboard grades form the cost-competitive foundation of dry-goods packaging. OCC price volatility in European spot markets compresses converter margins without contractual pass-through mechanisms.
- Plastic:Polyethylene films, stretch wrap, and mailer pouches deliver moisture resistance and dimensional stability. REACH substance restrictions on PFAS are eliminating oil-and-grease-resistant treatments from quick-service restaurant supply chains.
- Paper:Kraft wraps, tissue, and molded pulp provide renewable alternatives to plastic films. Retailers in France mandate plastic-free shelf-ready packaging specifications by 2026.
- Foam:Expanded polystyrene and polyurethane systems retain concentrated margin pools in pharmaceutical cold chain where thermal insulation performance justifies premium positioning.
Cardboard commands the highest shipment volumes while Paper expands most quickly on regulatory tailwinds.
End User:
Application-specific performance requirements drive material selection with divergent compliance burdens and specification authority concentration.
- Food & Beverage:Chilled ready-meal distribution demands barrier-coated paperboard engineered for direct food contact. Belgian retailers are compressing converter R&D timelines with plastic-free packaging mandates.
- Consumer Goods:Omnichannel fulfillment requires protective systems compatible with automated sortation equipment. Three retail groups in Germany and the Netherlands control 40% of corrugated specification authority.
- Electronics:Anti-static foam trays and inflatable protective systems safeguard high-value components during transit. FSC chain-of-custody verification is now mandatory through molded pulp tray suppliers.
- Pharmaceuticals:Cold chain distributors adopt molded pulp thermal protection as polystyrene alternatives meet EFSA contact-material standards.
Food & Beverage generates the baseline demand while Pharmaceuticals climbs the fastest on cold chain infrastructure investment.
Distribution Channel:
Customer type fragmentation separates high-velocity fulfillment centers from relationship-driven wholesale accounts with opposing service requirements.
- Retail:Shelf-ready packaging specifications demand print quality and structural integrity for point-of-sale display. French hypermarkets are consolidating supplier panels and extending quality audits to tier-two raw material sources.
- E-commerce:Same-day delivery velocity requirements in Germany and the Netherlands are scaling corrugated box consumption. Automated dimensioning equipment integration constrains packaging specification flexibility.
- Direct Sales:Manufacturer-controlled fulfillment enables customized protective configurations for specialized equipment. WMS protocol synchronization adds integration complexity.
- Wholesale:Palletized unit loads prioritize stack strength and stretch film efficiency over print aesthetics. Volume concentration supports dedicated converter capacity allocation.
Retail maintains the largest procurement scale while E-commerce shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German and Dutch integrated producers while Polish converters absorb margin compression from raw material volatility. Containerboard cost pass-through mechanisms function asymmetrically across these adjacent markets. Regulatory divergence between REACH-aligned frameworks and emerging national schemes fragments procurement strategies.
Germany
Fulfillment center automation in the Rhine-Ruhr corridor drives specification demand for ECT-certified double-wall construction. The country's national packaging regulator enforces extended producer responsibility thresholds under the Verpackungsgesetz amendment. Hamburg anchors North European containerboard distribution with mill-direct supply relationships to major converters.
Netherlands
Rotterdam-Antwerp port logistics clusters generate concentrated demand for palletized stretch film and anti-static protective systems. ECHA substance restrictions on PFAS eliminate legacy coating treatments from food-contact specifications. Eindhoven's electronics manufacturing corridor mandates FSC-verified molded pulp for semiconductor shipments.
France
Parisian retail consolidation compresses supplier panels for shelf-ready packaging with plastic-free mandates by 2026. EFSA contact-material standards accelerate barrier-coated paperboard qualification for chilled ready-meal distribution. Lyon and Lille distribution hubs consolidate procurement authority among three retail groups controlling specification decisions.
Poland
Central European warehouse capacity expansion outpaces localized packaging supply infrastructure. The country's national environmental regulator implements EU Packaging and Packaging Waste Regulation compliance deadlines with limited transitional flexibility. Warsaw and Łódź logistics zones rely on imported containerboard from Nordic integrated producers.
Belgium
Pharmaceutical cold chain distributors in the Brussels-Antwerp corridor adopt molded pulp thermal protection as polystyrene alternatives meet EFSA standards. REACH compliance documentation filters procurement toward certified converter networks. Ghent's biotech cluster drives demand for temperature-validated protective configurations.
Expendable Packaging Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the expendable packaging sector. Integrated paperboard producers with captive pulp supply command input cost stability, while specialty converters compete on barrier coating innovation and short-run flexibility. Three archetypes dominate: multinational integrated groups with mill networks, regional corrugators serving e-commerce fulfillment, and niche protective material specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as mid-scale operators deploy automated corrugation lines.
Within the integrated producer tier, Smurfit Kappa Group and Mondi Group exemplify divergent specialization strategies. Smurfit Kappa's European mill network sustains containerboard supply continuity for corrugated applications. Mondi anchors industrial positioning through kraft paper specialization in protective wrap segments. Sealed Air Corporation occupies a distinct archetype as an engineered protective systems specialist serving electronics end users with inflatable and foam-based configurations.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Berry Global Inc. |
| Mondi Group |
| Smurfit Kappa Group |
| DS Smith Plc |
| WestRock Company |
| International Paper Company |
| Sonoco Products Company |
| Others |
Supply Flow & Price Mechanics
REACH compliance documentation gates both supplier qualification and price differentiation simultaneously, as converters lacking ECHA-certified chemical safety records face exclusion from retailer panels while certified operators command configured-to-order premiums for validated barrier coatings.
Pricing Analysis
The customization-premium spread separates standard corrugated box contracts from configured specifications with ECT certification and FSC chain-of-custody verification. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with bulk retail procurement commanding lowest unit rates. Cost compression in mid-scale converter tiers is intensifying because OCC price volatility lacks contractual pass-through mechanisms. Food and beverage distributors exhibit highest price sensitivity, while pharmaceutical cold chain buyers prioritize thermal performance over unit cost.
Supply Chain Analysis
Nordic kraft pulp supply concentration in Sweden, Finland, and Norway anchors virgin fiber availability for European containerboard production. Raw material flows draw from OCC recovery networks, imported softwood pulp, and domestic recycled fiber streams. Single-source vulnerability concentrates in integrated mill networks controlling 60% of regional virgin fiber supply. Distribution runs through mill-direct relationships to major converters, with spot market layering for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as three retail groups in Germany, France, and the Netherlands now control 40% of corrugated specification authority, fragmenting supplier negotiating leverage.
For Market Incumbents: Compound barrier coating R&D investment to capture margin pools from PFAS substitution mandates before contract renewal cycles close. Defend position by securing FSC chain-of-custody certification across tier-two raw material sources, as electronics manufacturers now mandate verification through molded pulp tray suppliers. Capacity addition in Poland addresses the underpenetrated Central European fulfillment infrastructure before regional competitors establish localized supply. For New Entrants and Emerging Players: Short-run corrugation services for seasonal promotional packaging represent a service-layer gap where incumbents under-serve mid-market e-commerce merchants. Target Polish warehouse zones where fulfillment center expansion outpaces packaging supply localization. Qualify fluorine-free grease barrier coatings for quick-service restaurant contracts as German converters accelerate ECHA-guided alternative validation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated corrugation line deployment as mid-scale operators achieve scale without integrated mill ownership. Long-term viability favors converters with digital print hybrid press capabilities enabling batch-size-one production. Acquisition target archetype: regional corrugators with WMS protocol integration expertise serving omnichannel retail fulfillment. Watch automated dimensioning equipment deployment rates as inflection indicator for packaging specification flexibility constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Recovery | Captive OCC supply insulates converter margins from European spot market volatility. |
| Barrier Coating Technology Licensing | Fluorine-free formulations capture margin pools from PFAS elimination mandates. |
| Digital Print Hybrid Press Deployment | Batch-size-one capability serves seasonal promotional packaging without plate costs. |
| WMS Protocol Integration Partnership | Automated fulfillment center compatibility secures specification authority with major retailers. |
| Polish Manufacturing Footprint Expansion | Central European hub positioning addresses warehouse capacity consolidation without matching supply localization. |
Methodological Framework
The analysis maps corrugated fiberboard, molded pulp, plastic films, and protective foam segments, each validated through procurement managers at omnichannel retailers, plant directors at integrated paperboard mills, technical R&D leads at coating technology licensors, and logistics operators at fulfillment centers. Primary interview findings triangulate against secondary sources including EU Packaging and Packaging Waste Regulation filings, ECHA substance restriction databases, FSC chain-of-custody certification records, and customs trade data for containerboard imports. Bottom-up volume estimates from converter capacity utilization cross-check against top-down demand projections from end-use sector consumption patterns.
Consistency checks validate outputs against external benchmarks including mill production disclosures and retailer procurement volume reports across the projection horizon. The analytical framework models product type, material composition, end-use application, and distribution channel dimensions throughout the forecast period. CAGRs derive from segmented demand growth trajectories applied to base-year value allocations. Forecast inputs incorporate e-commerce parcel throughput velocity requirements and regulatory compliance timeline assumptions for extended producer responsibility schemes.
Underlying assumptions cover OCC price stability, REACH substance restriction enforcement timelines, and fulfillment center automation adoption rates, with deviation risk concentrated in regulatory implementation delays and raw material cost spikes. Practitioners should keep alternative scenarios live as EU Green Deal carbon border adjustment mechanisms and PFAS elimination deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Book Wraps Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
Thermoformed Trays Market
Packaging Materials
EPE Liner Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Packaging Supplies Market
Packaging Materials
Packaging Reel Market
Packaging Materials
Non-Breathable Films Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Food Grade Sealant Market
Packaging Materials
Reel in Box Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Thermal Insulation Packaging Market