
 Hot-Melt Based Packaging Market | 2026-2036
Hot-Melt Based Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
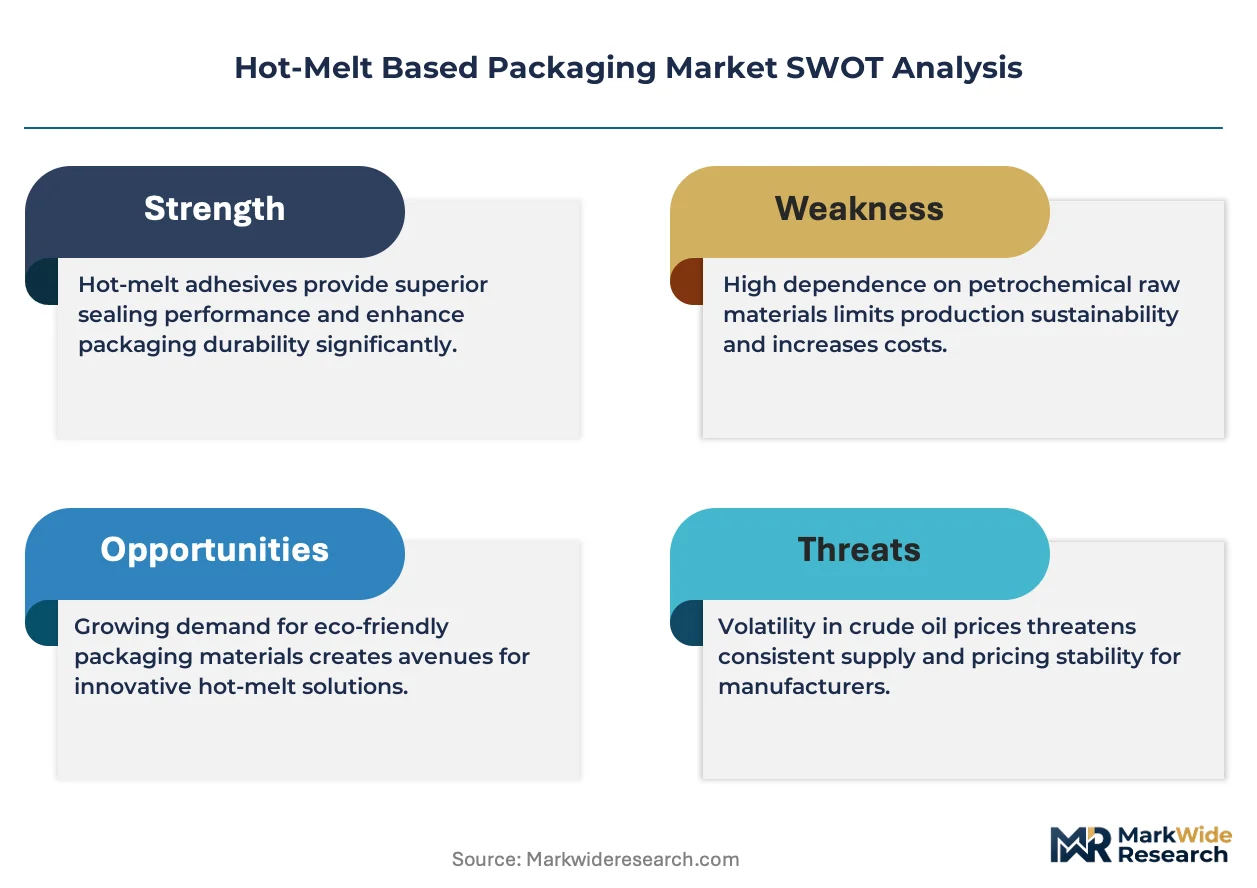
Hot-Melt Based Packaging Market Foresight
Ethylene-vinyl acetate is expanding its share of carton sealing formulations as converters seek faster set times and lower energy use on high-speed lines. Henkel AG & Co. KGaA leverages its European manufacturing footprint to supply certified food-contact adhesives for dairy and bakery packaging. H.B. Fuller Company anchors its position through captive resin production and technical service centers in North American corrugated hubs. Arkema Group differentiates via specialty copolymer grades designed for pharmaceutical blister packaging cold-chain integrity.
Hot-melt based packaging refers to thermoplastic adhesive systems applied in molten state, typically between 120°C and 180°C, that solidify upon cooling to form bonds with substrates including corrugated board, films, and foils; these systems eliminate solvent drying stages and enable line speeds exceeding 500 cartons per minute in automated fulfillment environments. Styrene-block copolymers command premium positioning in pharmaceutical and personal care applications where clean removability and temperature resistance justify higher formulation costs. Polyethylene dominates volume in food and beverage carton sealing where cost efficiency and broad substrate compatibility drive procurement decisions across high-throughput bakeries and dairy processors.
FDA food-contact substance notifications govern adhesive migration limits for direct and indirect food packaging in the United States, while REACH and the EU Packaging and Packaging Waste Directive constrain substance selection and recyclability claims across European supply chains. China's GB standards and evolving MEE enforcement on volatile organic compound emissions are elevating compliance costs for domestic producers serving export-oriented packaging converters. Stakeholders must monitor regulatory divergence between bio-based content mandates in Europe and performance-driven specifications in Asia-Pacific to align R&D portfolios with divergent compliance trajectories.
Market Dynamics
E-commerce fulfillment velocity is compressing set-time requirements for carton sealing adhesives, forcing reformulation toward low-temperature application chemistries that protect heat-sensitive printed substrates.
Growth Catalysts
- REACH substance restrictions:European ECHA enforcement on SVHC candidate list substances is redirecting R&D spending toward bio-based tackifier alternatives in carton sealing formulations.
- Pharmaceutical cold-chain expansion:Temperature-stable adhesive demand from vaccine distribution infrastructure is pulling specialty copolymer grades into blister packaging laminates.
- China domestic production scaling:Regional adhesive manufacturing clusters in Guangdong and Zhejiang provinces are reducing import dependency for corrugated board converters serving export packaging.
Market Restraints
- Crude oil derivative volatility:Hydrocarbon resin feedstock costs swing with naphtha cracking margins, compressing formulation economics for mid-tier producers lacking backward integration.
- Asian supply concentration:Styrene block copolymer capacity clusters in South Korea and Taiwan create single-source vulnerability for pharmaceutical-grade adhesive procurement.
- Hot-temperature performance ceiling:EVA-based systems soften above 60°C, limiting adoption in tropical logistics corridors and summer rail container applications.
Strategic Opportunities
- India corrugated packaging modernization:Organized retail expansion in Maharashtra and Karnataka states is pulling automated case-sealing line investment requiring compatible hot-melt systems.
- EU Packaging and Packaging Waste Directive recyclability mandates:Design-for-recycling criteria are creating specification windows for debondable adhesive technologies that enable fiber recovery.
- UV-LED curing convergence:Hybrid systems combining molten application with photochemical cure are opening temperature-sensitive substrate bonding in premium personal care folding cartons.
Industry Challenges
- Food-contact notification timelines:FDA FCN review cycles for new adhesive monomers extend 18-24 months, delaying commercialization of bio-based feedstock transitions.
- Legacy equipment retrofit costs:Tank and hose replacement for low-temperature formulation compatibility demands capital allocation that mid-scale converters defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot-Melt Based Packaging Market |
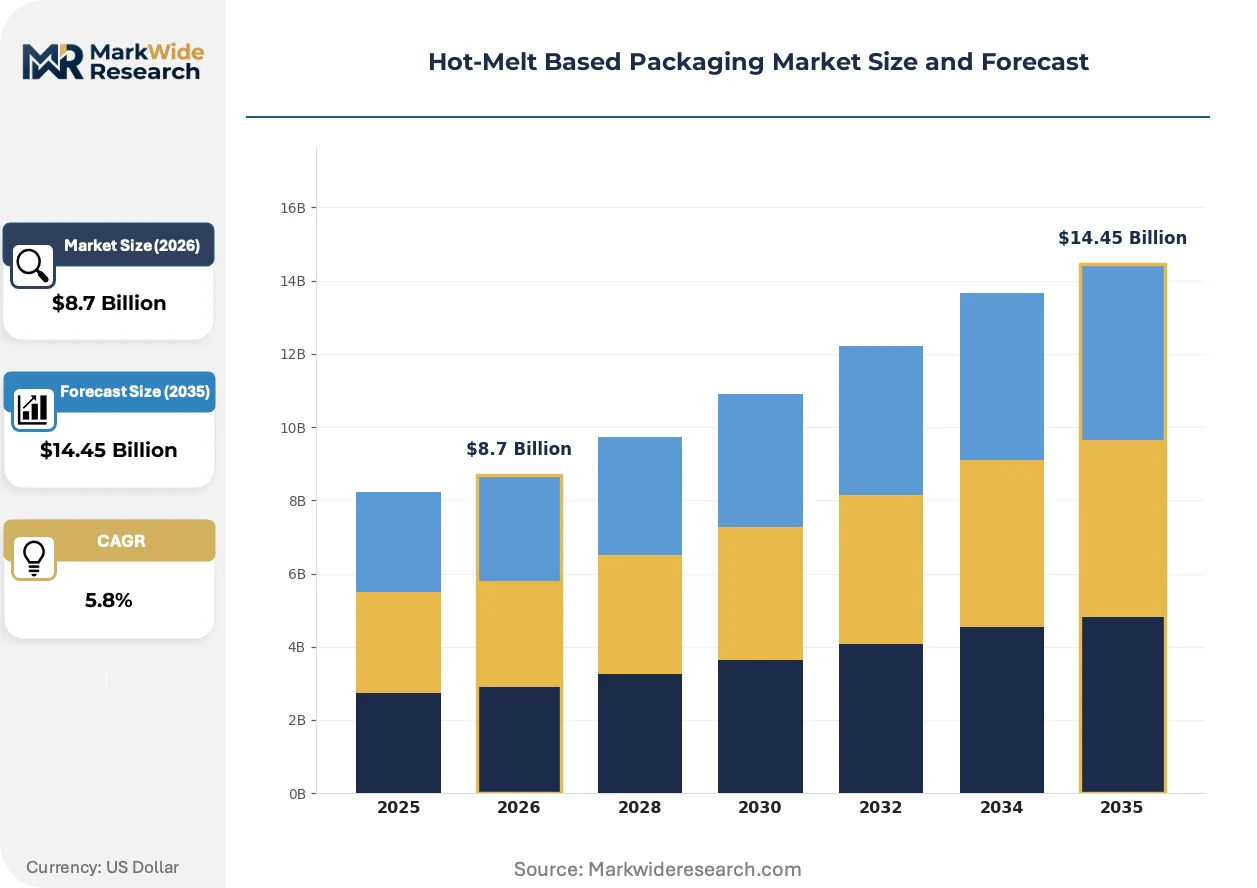
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
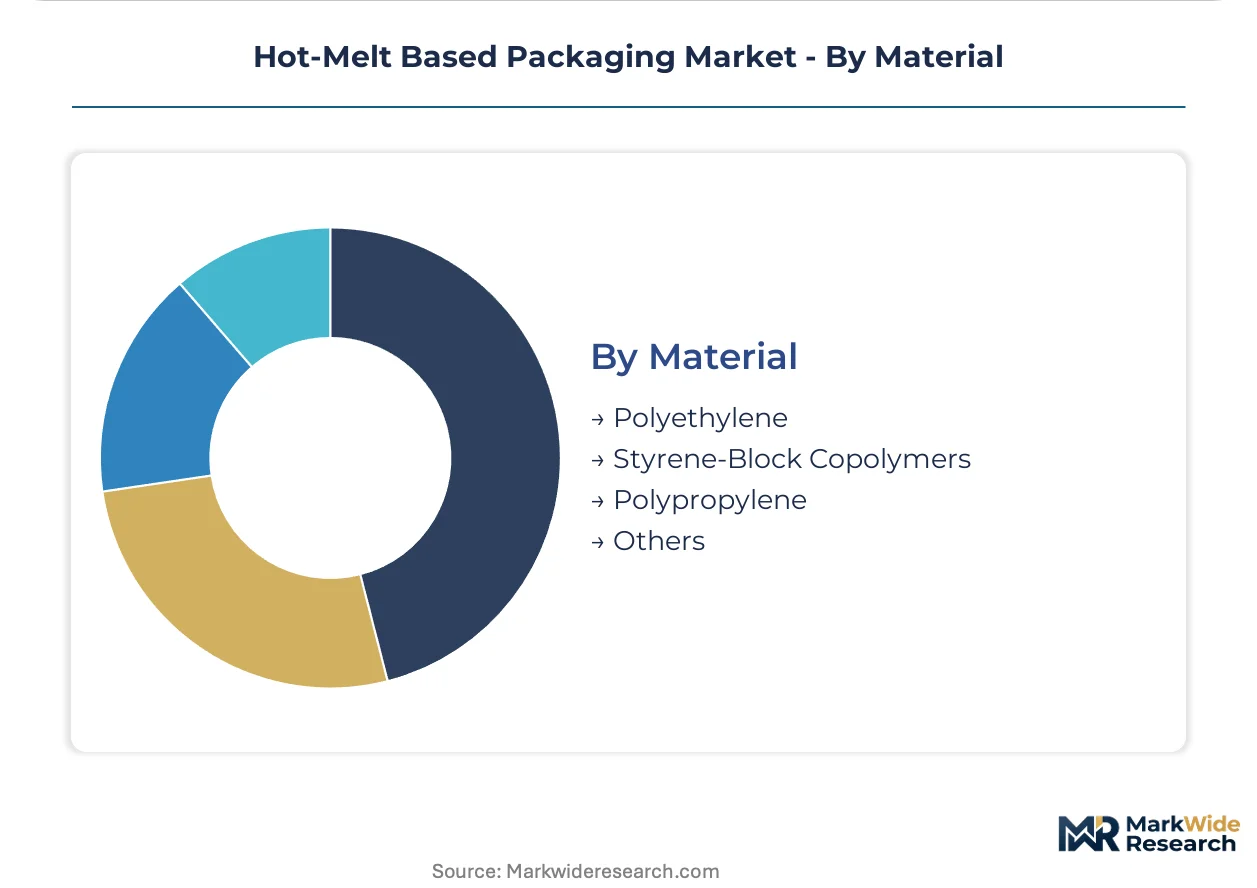
| Segmentation | Product Type: Hot-Melt Adhesives, Coatings, Sealants, Tapes End User: Food & Beverage, Consumer Electronics, Pharmaceuticals, Personal Care Application: Carton Sealing, Labeling, Product Assembly, Bag Closure Material: Polyethylene, Styrene-Block Copolymers, Polypropylene, Others |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, H.B. Fuller Company, Arkema Group, Sika AG, Jowat SE, Bostik Inc., BASF SE, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot-Melt Based Packaging Market Shifts & Advancements
Formulation chemistry is pivoting toward temperature-performance tradeoffs that protect printed substrates while maintaining line speed, with regulatory compliance emerging as the primary specification gate.
Metallocene-catalyzed polyolefin elastomers are absorbing narrow-molecular-weight distribution requirements for precision dot-pattern dispensing on high-speed case sealers. Bakery and dairy processors in Germany and the Netherlands are adopting these grades to eliminate stringing and tailing at 450+ cartons per minute. The technology is absorbing specification share from conventional EVA in European food-contact applications where clean cut-off justifies 15-20% formulation premiums.
REACH Annex XVII restrictions on microplastics and evolving ECHA guidance on polymer registration are forcing disclosure of additive packages previously treated as proprietary. Adhesive compounders serving European medical device packaging must now document tackifier hydrogenation levels and antioxidant migration profiles. Pharmaceutical blister pack converters in Ireland and Switzerland are responding by consolidating supplier bases toward certified compounders with established regulatory dossiers.
Consolidated buying desks at multinational CPG groups are compressing adhesive supplier rosters from regional fragmentation toward approved vendor lists with pan-continental service capability. Procurement teams at dairy and beverage packagers now specify single-source accountability across European plant networks, displacing country-level purchasing autonomy. This concentration is most visible in Benelux and Nordic markets where cooperative retail chains dominate private-label volume and demand supply chain transparency documentation.
Hot-Melt Based Packaging Market Segmentation
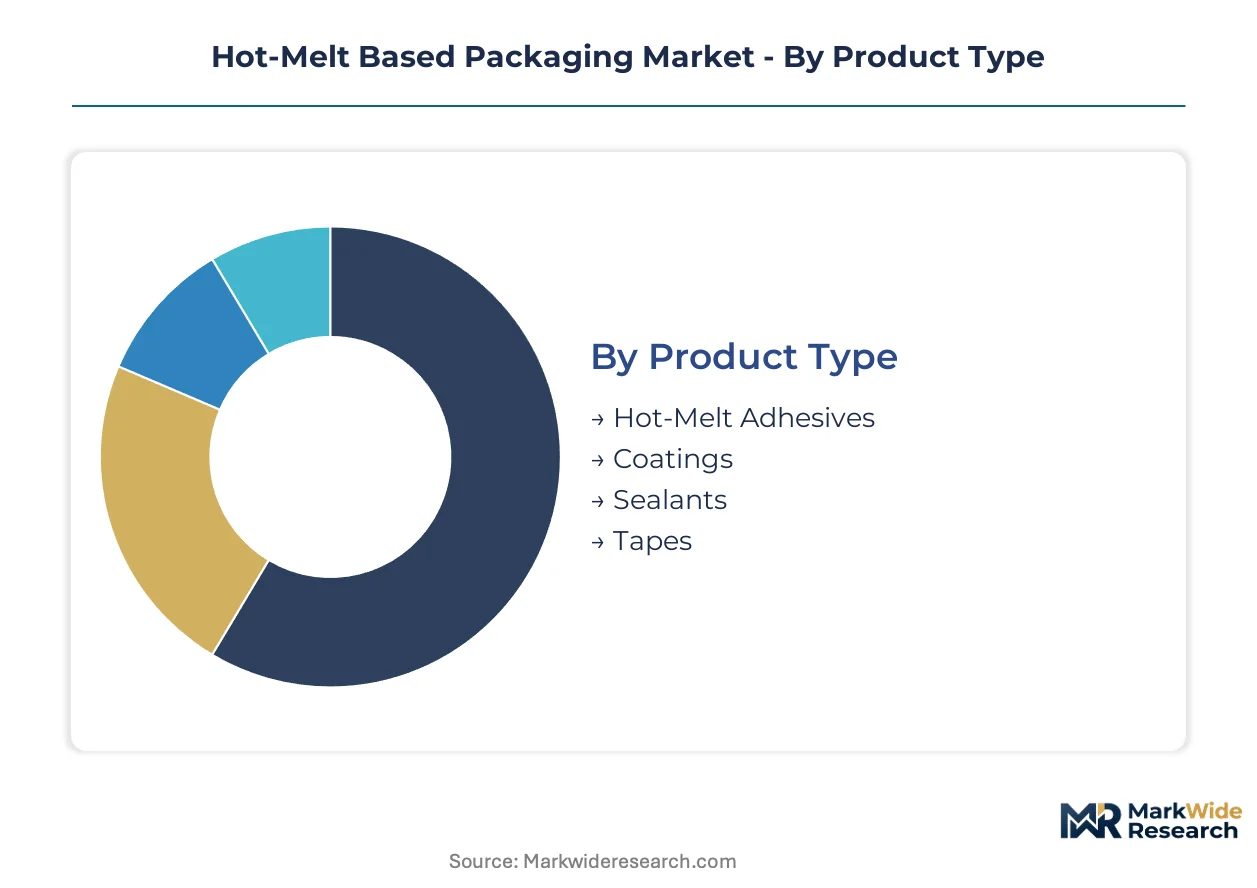
Hot-melt packaging adhesives serve divergent compliance regimes across food-contact, medical-device, and consumer-goods applications, making certification mapping the primary segmentation lens for procurement and R&D allocation. Each product category, end-use vertical, and substrate pairing carries distinct notification timelines and migration-limit requirements that reshape supplier qualification criteria.
Product Type:
FDA food-contact substance notifications and REACH SVHC declarations split this category by regulatory burden intensity, with direct-food-contact formulations demanding 18-24 month pre-market dossiers versus general industrial grades.
- Hot-Melt Adhesives:Thermoplastic formulations applied at 120-180°C dominate carton sealing and case erection in high-velocity e-commerce fulfillment centers. Demand concentrates in China where domestic production clusters in Guangdong province now supply regional corrugated converters previously dependent on European imports, compressing lead times for just-in-time adhesive replenishment.
- Coatings:Barrier and heat-seal layers applied to films and foils require EFSA compliance for dairy and bakery packaging across Benelux and Nordic markets. Pharmaceutical blister-pack converters in Ireland and Switzerland are consolidating supplier rosters toward compounders with established regulatory dossiers covering antioxidant migration profiles.
- Sealants:Edge-sealing compounds for flexible packaging must document tackifier hydrogenation levels under evolving ECHA guidance on polymer registration.
- Tapes:Pressure-sensitive hot-melt coatings on backing substrates serve secondary packaging reinforcement with lighter regulatory documentation burdens.
Leading the category by volume: Hot-Melt Adhesives. Growing fastest: Coatings.
End User:
Customer procurement concentration and specification stringency divide this dimension, with multinational CPG buying desks demanding pan-continental service capability versus fragmented regional converters.
- Food & Beverage:Dairy processors and high-throughput bakeries specify EVA and metallocene polyolefin grades for 450+ cartons per minute line speeds. German and Dutch facilities are absorbing 15-20% formulation premiums for clean cut-off properties that eliminate stringing on automated case sealers.
- Consumer Electronics:Precision dot-pattern dispensing for device packaging and accessories requires narrow-molecular-weight distribution elastomers. Demand clusters in South Korea and Taiwan where styrene block copolymer capacity concentration creates single-source vulnerability for temperature-stable adhesive procurement.
- Pharmaceuticals:Vaccine distribution infrastructure is pulling specialty copolymer grades into blister packaging laminates requiring cold-chain integrity down to -70°C.
- Personal Care:Premium folding cartons for cosmetics and skincare are adopting hybrid UV-LED curing systems that bond temperature-sensitive printed substrates without heat damage.
Food & Beverage commands the largest procurement volume. Pharmaceuticals shows the steepest expansion trajectory driven by cold-chain infrastructure buildout.
Application:
Line-speed requirements and substrate sensitivity determine formulation selection, with e-commerce velocity forcing reformulation toward low-temperature chemistries.
- Carton Sealing:The dominant application absorbs metallocene-catalyzed polyolefin elastomers for precision dispensing at 500+ units per minute. Asia-Pacific distribution networks are accelerating specification shifts as fulfillment automation penetrates regional logistics hubs.
- Labeling:Permanent and removable pressure-sensitive adhesives on bottles and containers demand clean removability in pharmaceutical and personal care segments where label repositioning protects premium packaging aesthetics.
- Product Assembly:Structural bonding of packaging components requires higher green-strength formulations that hold dimensional stability through downstream handling.
- Bag Closure:Side-seal and bottom-seal applications for flexible packaging use polyethylene-dominant formulations where cost efficiency overrides performance premiums.
Carton Sealing generates the highest adhesive consumption. Bag Closure is gaining specification share fastest as flexible packaging displaces rigid formats in e-commerce shipping.
Material:
Feedstock cost structure and performance ceiling differentiate this category, with bio-based transitions constrained by crude oil derivative volatility.
- Polyethylene:Volume leader in food and beverage carton sealing where broad substrate compatibility and formulation economy drive procurement decisions. Naphtha cracking margin swings compress economics for mid-tier producers lacking backward integration into resin supply.
- Styrene-Block Copolymers:Premium positioning in pharmaceutical and personal care applications justifies higher costs through clean removability and temperature resistance above 60°C. Capacity concentration in South Korea and Taiwan creates procurement vulnerability for medical-device packagers requiring certified grades.
- Polypropylene:Emerging alternative for high-temperature logistics corridors where EVA softening limits adoption in tropical rail container applications.
- Others:Bio-based tackifier alternatives and specialty amorphous polyolefins absorb R&D spending redirected by REACH substance restrictions on hydrocarbon resins.
Polyethylene dominates by tonnage. Styrene-Block Copolymers command the fastest value growth as pharmaceutical cold-chain specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong's export processing zones concentrate adhesive manufacturing for regional corrugated converters, compressing lead times for just-in-time replenishment across Asia-Pacific distribution networks.
China
Domestic production clusters in Guangdong and Zhejiang provinces scale to serve regional packaging manufacturing hubs. MEE enforcement on volatile organic compound emissions elevates compliance costs for producers serving export-oriented converters. Shenzhen and Dongguan adhesive compounders now supply corrugated board producers previously dependent on European imports.
Germany
Dairy processors and high-throughput bakeries specify metallocene polyolefin grades for 450+ cartons per minute line speeds. REACH Annex XVII restrictions on microplastics force disclosure of additive packages previously treated as proprietary. The Ruhr industrial corridor hosts compounders with established regulatory dossiers for medical-device packaging.
United States
FDA food-contact substance notifications govern adhesive migration limits for direct and indirect food packaging. E-commerce fulfillment velocity compresses set-time requirements for carton sealing adhesives. Midwestern corrugated hubs anchor technical service centers supporting automated case-sealing line investment.
India
Organized retail expansion in Maharashtra and Karnataka states pulls automated case-sealing line investment requiring compatible hot-melt systems. FSSAI compliance timelines for food-contact adhesives extend qualification periods for domestic compounders. Mumbai-Pune industrial corridor packaging converters upgrade equipment to serve modern trade distribution.
Switzerland
Pharmaceutical blister pack converters consolidate supplier bases toward certified compounders with established regulatory dossiers. Swissmedic oversight on medical-device packaging elevates documentation requirements for antioxidant migration profiles. Basel-region pharmaceutical clusters demand cold-chain integrity specifications down to -70°C.
Hot-Melt Based Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational chemical conglomerates commanding food-contact certification advantages while regional compounders compete on logistics responsiveness. The vendor base organizes around three archetypes: integrated resin producers with captive feedstock supply, formulation specialists with regulatory dossier depth, and regional toll compounders serving just-in-time replenishment. Consolidation pressures intensify as multinational CPG buying desks compress approved vendor lists from country-level fragmentation toward pan-continental accountability. Backward integration into hydrocarbon resin supply and certification-driven R&D partnerships represent the dominant competitive moves reshaping positioning.
Among European-headquartered diversified chemical groups, Henkel AG & Co. KGaA and BASF SE occupy positions anchored by manufacturing footprints spanning multiple regulatory jurisdictions. H.B. Fuller Company exemplifies the North American integrated model with technical service infrastructure concentrated in corrugated production hubs. These three entities represent distinct strategic postures: certification-led specification capture, scale-driven cost positioning, and service-intensive customer proximity respectively.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| H.B. Fuller Company |
| Arkema Group |
| Sika AG |
| Jowat SE |
| Bostik Inc. |
| BASF SE |
| Avery Dennison Corporation |
| Others |
Supply & Pricing Matrix
Adhesive formulation chemists concentrated in Germany's Ruhr corridor and Switzerland's Basel region command wage premiums that compress pricing-tier spreads between certified food-contact grades and general industrial formulations. Labor-cost differentials between these European technical centers and China's Guangdong manufacturing clusters widen the gap between premium pharmaceutical-grade adhesives and economy carton-sealing products.
Pricing Analysis
Volume-driven polyethylene formulations trade at commodity margins while styrene-block copolymer specialty grades capture premium spreads. Pricing stratifies across pharmaceutical certification tiers, food-contact notification status, and cold-chain performance specifications. Cost compression in mid-tier EVA formulations is intensifying because naphtha cracking margin volatility erodes compounder economics. Dairy processors and high-throughput bakeries show highest price sensitivity, while vaccine distribution infrastructure shows least sensitivity due to cold-chain integrity requirements.
Supply Chain Analysis
Reverse-logistics flows for adhesive drum returns and packaging waste recovery are concentrating in Benelux and Nordic cooperative retail networks. Hydrocarbon resin feedstock draws from South Korea, Taiwan, and Germany, with styrene block copolymer capacity anchored in East Asian petrochemical corridors. Single-source vulnerability runs through South Korean and Taiwanese specialty copolymer producers serving pharmaceutical-grade procurement. Distribution runs through regional toll compounders in China's Guangdong province and technical service centers in North American corrugated hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hot-melt packaging adhesives are transitioning from conventional EVA systems toward metallocene-catalyzed polyolefin elastomers and bio-based tackifier alternatives, with low-temperature application chemistry displacing legacy high-temperature formulations in automated fulfillment environments.
For Market Incumbents: Deploy certification dossier depth as the primary defensive lever. Consolidate supplier rosters toward compounders with established REACH Annex XVII and FDA food-contact substance notification portfolios to preempt regulatory displacement. Deepen backward integration into hydrocarbon resin supply to buffer naphtha cracking margin volatility that threatens mid-tier formulation economics. For New Entrants and Emerging Players: Regional toll compounders in India's Maharashtra and Karnataka states represent the most penetrable channel partner type for establishing just-in-time replenishment relationships. Target corrugated converters upgrading automated case-sealing lines in organized retail expansion corridors. Pursue white-space in debondable adhesive technologies serving EU Packaging and Packaging Waste Directive recyclability mandates. For Investors and Strategic Acquirers: Re-rating potential sits with formulation specialists possessing regulatory dossier depth given ECHA enforcement acceleration on SVHC candidate list substances. Long-term viability favors compounders with demonstrated antioxidant migration documentation and established medical-device packaging certifications. Monitor FDA food-contact substance notification review cycle durations as inflection indicator for bio-based feedstock transition commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrocarbon Resin Supply | Captive feedstock production buffers naphtha cracking margin volatility for European compounders. |
| Certification-Driven R&D Partnership | Collaboration with Swissmedic-registered facilities accelerates pharmaceutical-grade adhesive qualification. |
| Regional Toll Compounding Expansion | Guangdong province facilities compress lead times for Asia-Pacific corrugated converter replenishment. |
| Low-Temperature Formulation Development | Metallocene polyolefin elastomers protect heat-sensitive printed substrates in e-commerce fulfillment. |
| Bio-Based Tackifier Transition | REACH Annex XVII compliance redirects hydrocarbon resin substitution toward renewable feedstocks. |
Research Methodology
Multi-period observation of adhesive formulation patent filings, regulatory notification timelines, and corrugated packaging equipment installation rates anchored the trend analysis, supplemented by interviews with adhesive compounder technical directors, pharmaceutical packaging engineers, dairy processor procurement managers, and e-commerce fulfillment operations heads. Secondary validation drew from ECHA SVHC candidate list updates, FDA food-contact substance notification databases, Chinese customs trade data, and European corrugated board association production statistics. Bottom-up volume estimates triangulated against top-down spending allocation models across end-use verticals.
Segment-weighting applied product type, end-user industry, application method, and material chemistry dimensions across the modeling period. CAGRs derived from regression analysis of historical formulation adoption curves and forward projection of regulatory compliance cost trajectories. Forecast inputs incorporated MEE enforcement intensity on volatile organic compound emissions and cold-chain infrastructure buildout rates for vaccine distribution.
Caveats apply where crude oil derivative volatility, REACH substance restriction expansions, or FDA notification review delays could materially shift the outlook. Practitioners should monitor ECHA guidance evolution on polymer registration and FSSAI compliance timeline extensions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Packaging Inserts Market
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Corrugated Wraps Market
Packaging Materials
France Packaging Market
Packaging Materials
Window Packaging Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Floppy Disk Liner Market
Packaging Materials
Construction Films Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Chemical Packaging Market
Packaging Materials
Global Strapping Market
Packaging Materials
New Packages and Materials for Power Devices Market