
 Shrink Packaging Market | 2026-2036
Shrink Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink Packaging Market Outlook
Multi-source procurement among brand owners is consolidating around film converters with captive resin capabilities. Amcor Plc leverages its global manufacturing footprint to sustain supply security for beverage clients. Sealed Air anchors its position through integrated equipment-and-materials offerings. Berry Global competes on scale in polyethylene roll film for retail distribution networks.
Shrink packaging comprises heat-shrinkable polymer films that contract 30-70% when exposed to controlled thermal energy, forming a tight protective layer around products. The process typically employs blown or cast extrusion followed by biaxial orientation to impart shrink memory, serving primary functions of unitization, tamper evidence, and moisture barrier protection. Polyolefin dominates material selection for food contact applications due to its clarity and seal strength, while shrink sleeves represent the fastest-growing product category driven by 360-degree graphics demand in personal care. Roll film occupies the mature volume position in industrial bundling, where margin pools concentrate among converters with backward integration into resin compounding.
The EPA regulates volatile organic compound emissions from solvent-based printing processes used in sleeve decoration, pushing converters toward water-based ink systems. FDA compliance for food-contact polyolefin films shapes material formulation decisions, particularly for lidding applications in ready-meal packaging. REACH restrictions on phthalate plasticizers in PVC films redirect European demand toward polyethylene alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in mechanical recycling infrastructure or chemical recycling partnerships for post-consumer film recovery.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is compressing converter margins while accelerating capital redeployment toward recyclable film platforms and chemical recycling partnerships across member states.
Growth Catalysts
- Food and beverage shelf differentiation:Brand owners in ready-meal and beverage categories are expanding shrink sleeve adoption for 360-degree graphics coverage, pulling demand from conventional label formats.
- REACH phthalate restrictions:ECHA's redirection of European demand away from PVC films toward polyethylene alternatives is expanding addressable market for polyolefin converters with compliant formulations.
- Germany's industrial corridor concentration:Bundling demand from automotive component and building materials distribution networks is concentrating volume procurement among film converters with captive resin capabilities.
Market Restraints
- Resin input volatility:Ethylene and propylene feedstock exposure creates margin compression for converters lacking backward integration into polymer compounding operations.
- Equipment lock-in effects:Legacy heat-tunnel infrastructure at beverage and personal care packaging lines slows material switching cycles and extends payback periods for film transitions.
- Solvent-based printing phase-out:EPA VOC emission regulations are forcing capital-intensive ink system conversions at sleeve decorators with limited water-based technology experience.
Strategic Opportunities
- India food retail modernization:Organized retail expansion and cold chain infrastructure buildout is creating first-time shrink film demand for protein and dairy unitization previously served by loose distribution.
- Extended producer responsibility frameworks:Emerging EPR mandates in multiple jurisdictions are creating service revenue streams for converters offering post-consumer film collection and mechanical recycling programs.
- Digital printing convergence:Integration of inkjet decoration with shrink sleeve production is enabling short-run customization for craft beverage and specialty personal care brands.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with biaxial orientation process expertise are concentrated among a narrow set of legacy film producers, constraining new entrant scale-up.
- Food-contact certification timelines:FDA compliance documentation for novel polyolefin formulations extends commercialization cycles by 18-24 months versus industrial non-contact applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink Packaging Market |
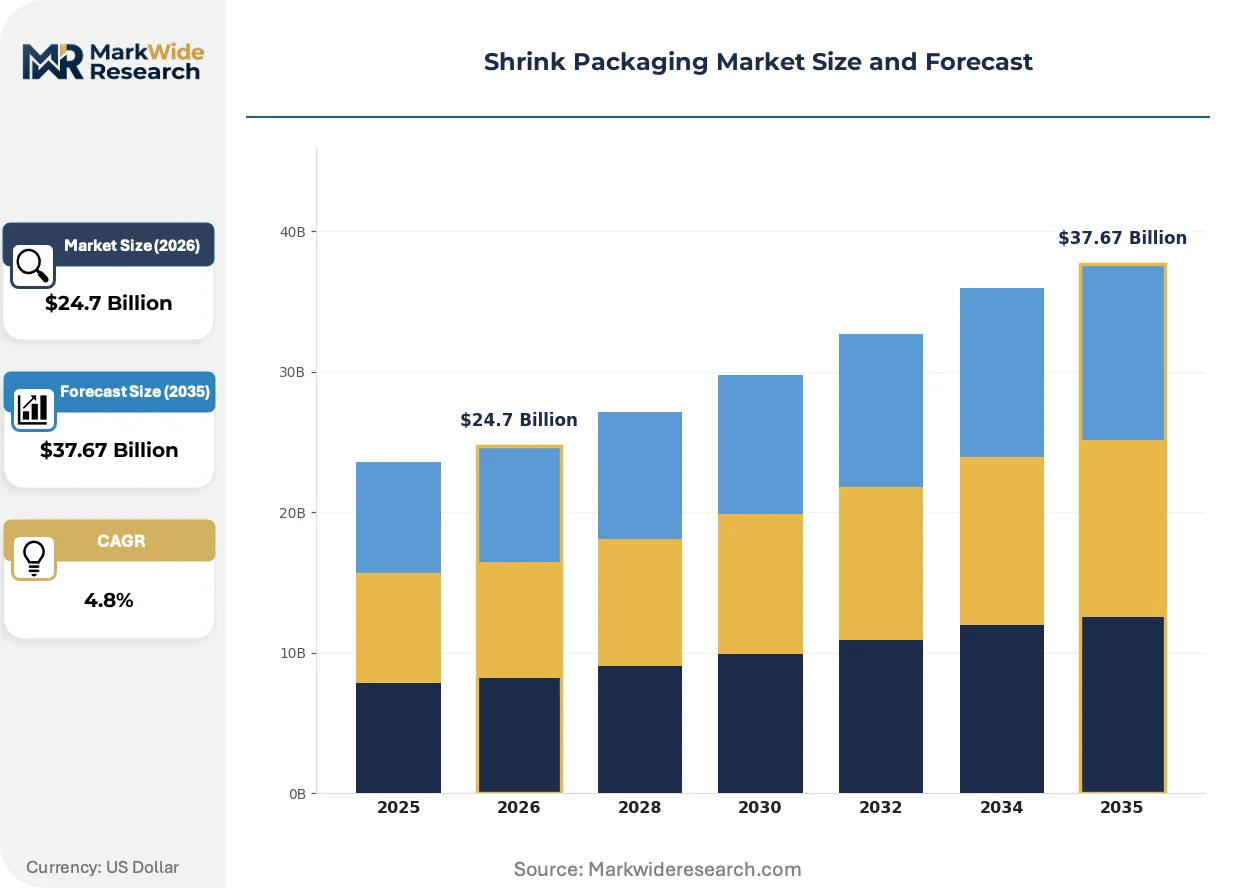
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $37.67 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll Film, Shrink Sleeves, Lidding Film, Bundling Film Material: Polyethylene, Polyvinyl Chloride, Polyolefin, BOPP End User: Food & Beverage, Personal Care, Electronics, Household Products Application: Retail Packaging, Industrial Packaging, Unit Packaging, Promotional Packaging |
| Companies Covered | Bonset America Corporation, Clondalkin Group Holdings, Amcor Plc, ProAmpac, Allen Plastic Industries, Sealed Air, Coveris Holdings, Printpack, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink Packaging Market Strategic Shifts
Active thermal processing controls, regulatory chemistry restrictions, and procurement consolidation are restructuring how film specifications get set and who captures margin across the value chain.
Polyolefin shrink film with controlled shrink-force profiles is modularizing equipment compatibility across mixed-material packaging lines. Beverage co-packers in North America are adopting these films to reduce changeover downtime between PET and glass container formats. The technology is modularizing converter-customer relationships from transactional supply toward integrated line-performance partnerships.
REACH restrictions on phthalate plasticizers in PVC films are accelerating polyethylene formulation investments among European sleeve producers. Industrial consequence includes elevated R&D spend for clarity and seal-strength parity with legacy PVC. Personal care and household chemical brands are most affected, with several reformulating around polyethylene shrink sleeves ahead of 2025 compliance deadlines.
Buyer consolidation among multinational beverage and personal care corporations is compressing supplier rosters toward converters with multi-continental manufacturing footprints. Direct procurement from film producers is displacing distributor intermediaries in North America and Western Europe. This pattern is most visible in Germany and the US, where three beverage brand owners now represent over forty percent of regional shrink sleeve volume.
Shrink Packaging Market Segmentation
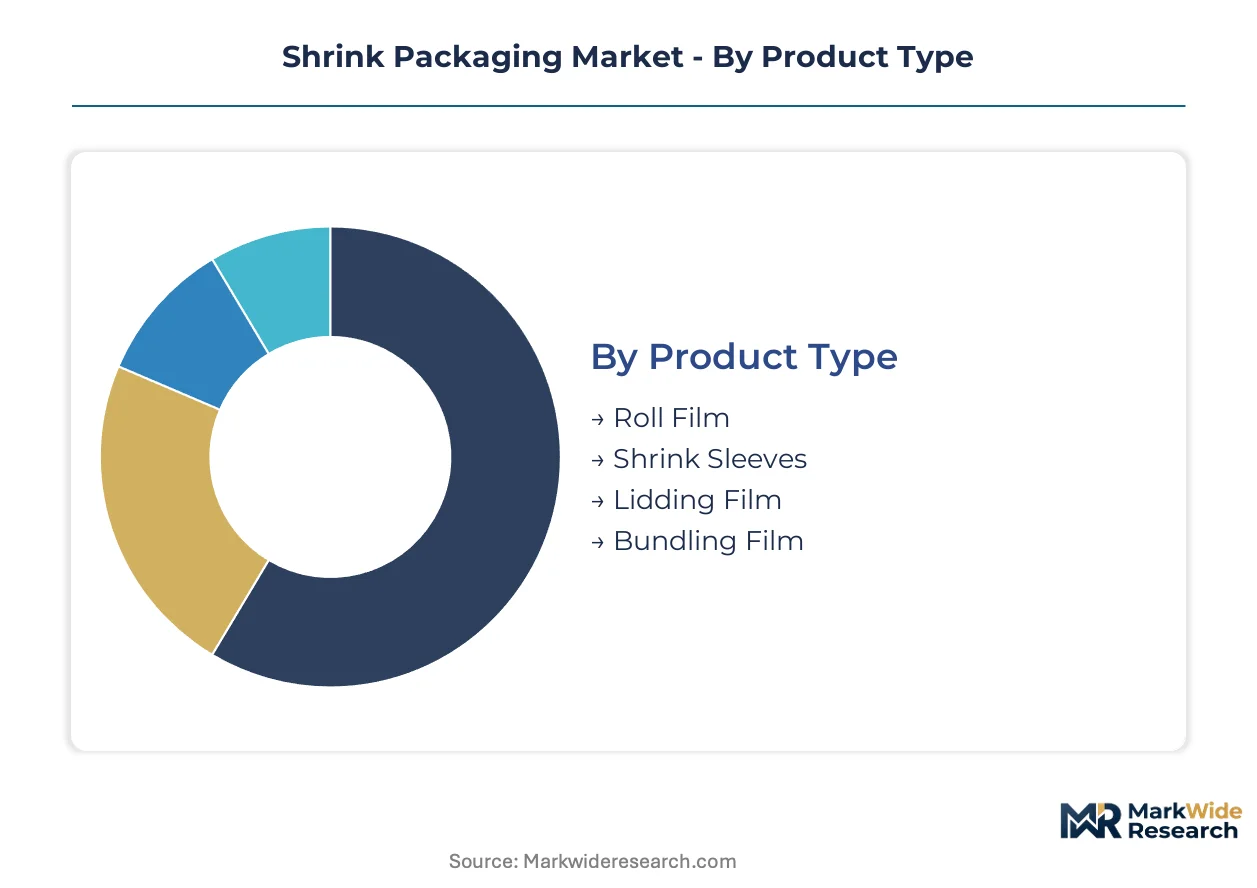
Film specification decisions in shrink packaging hinge on thermal processing infrastructure, regulatory compliance pathways, and end-use performance requirements. Each segment category carries distinct capital commitments and margin profiles that reshape converter investment priorities.
Product Type:
Capital intensity peaks with biaxial orientation lines for shrink sleeves, where multi-layer coextrusion and controlled stretching demand the steepest upfront equipment outlays.
- Roll Film:Blown or cast extrusion produces continuous sheeting for automated wrapping lines. Demand concentrates in Germany's automotive component distribution networks, where high-throughput bundling of brake pads and filtration units requires consistent gauge tolerance.
- Shrink Sleeves:Tubular film with pre-engineered shrink memory enables 360-degree decoration on irregular container geometries. Beverage brand owners in North America are expanding sleeve adoption for craft spirits and functional waters, pulled by shelf differentiation imperatives and tamper-evidence requirements.
- Lidding Film:Seal-peel polyolefin constructions serve ready-meal tray applications with controlled oxygen transmission.
- Bundling Film:High-strength polyethylene formulations unitize multi-pack beverages and building materials for pallet stability.
Most installed capacity flows through roll film. Expansion is steepest in shrink sleeves.
Material:
Resin selection determines compliance pathways, with food-contact polyolefin commanding formulation R&D premiums versus industrial-grade alternatives.
- Polyethylene:Linear low-density and metallocene grades deliver puncture resistance and clarity for protein unitization. India's organized retail modernization is creating first-time polyethylene demand for dairy and meat packaging previously handled through loose distribution.
- Polyvinyl Chloride:Legacy sleeve material with superior shrink force and gloss, now constrained by ECHA phthalate restrictions across EU member states. REACH compliance deadlines are accelerating converter migration toward polyethylene alternatives.
- Polyolefin:Cross-linked and non-cross-linked variants balance seal strength with controlled shrink initiation temperature.
- BOPP:Biaxially oriented polypropylene serves high-clarity lidding with lower shrink force than polyolefin alternatives.
Polyethylene holds the broadest installed base. Polyolefin is climbing the fastest on food-contact certification expansion.
End User:
Customer concentration patterns vary sharply, with multinational beverage corporations consolidating supplier rosters while household products retain fragmented procurement.
- Food & Beverage:Largest volume sink spanning protein unitization, ready-meal lidding, and beverage multipacks. FDA compliance documentation for novel polyolefin formulations extends commercialization cycles, favoring incumbent converters with established food-contact dossiers.
- Personal Care:Shrink sleeve demand for 360-degree branding on shampoo and cosmetics bottles. Three multinational brand owners now represent over forty percent of regional shrink sleeve volume in Germany and the US.
- Electronics:Anti-static formulations for circuit board and component protection.
- Household Products:Industrial bundling of cleaning chemical multipacks and aerosol can collation.
Food and beverage absorbs the majority of resin throughput. Personal care is gaining share fastest on premiumization and decoration upgrade cycles.
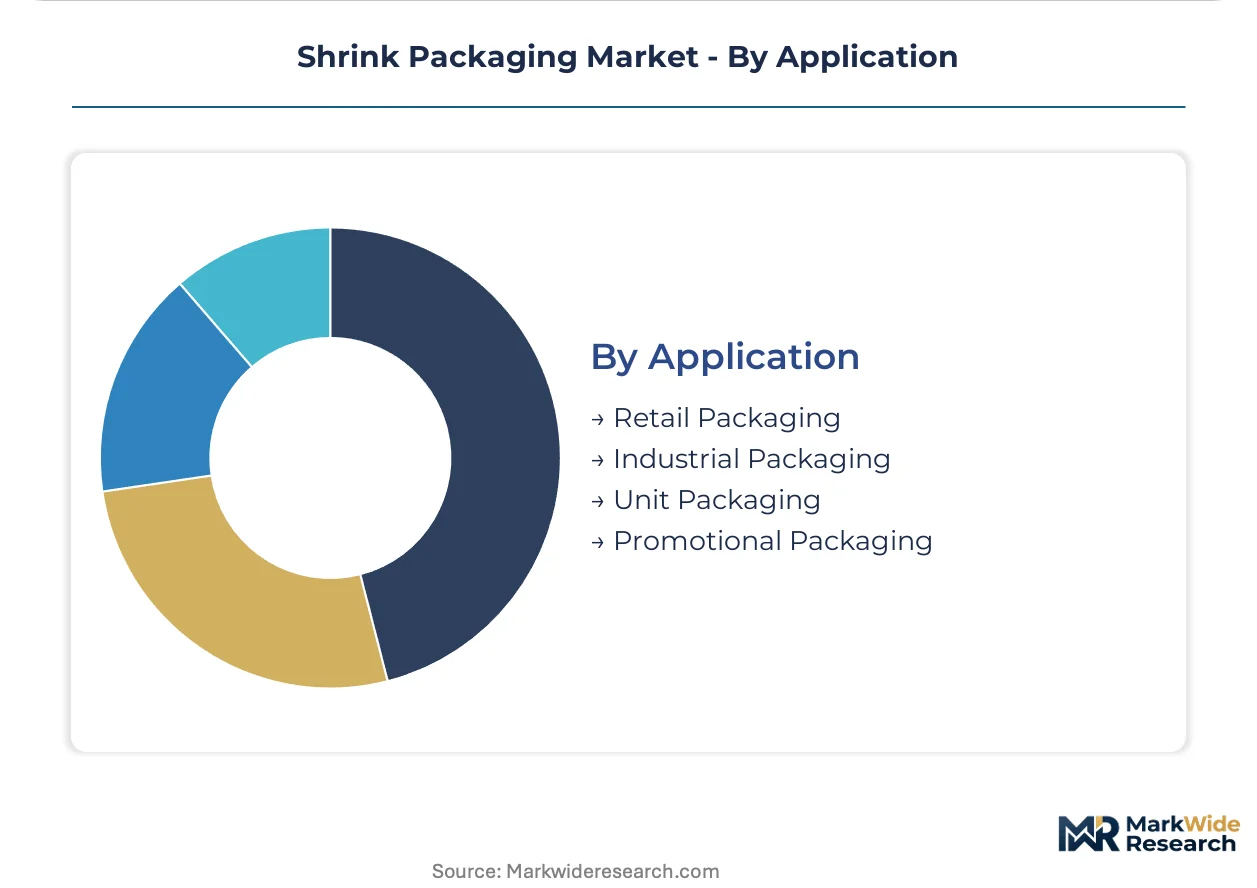
Application:
Application scope defines equipment compatibility requirements, with retail-facing formats demanding print decoration capability that industrial bundling can bypass.
- Retail Packaging:Printed sleeves and lidding films with high-definition graphics for consumer-facing shelf presence. Digital inkjet convergence is enabling short-run customization for craft beverage and specialty personal care brands.
- Industrial Packaging:Unprinted roll film for pallet unitization and distribution protection. Legacy heat-tunnel infrastructure at automotive component lines slows material switching cycles.
- Unit Packaging:Individual product containment with tamper-evidence features.
- Promotional Packaging:Limited-edition sleeve decoration for seasonal marketing campaigns.
Industrial packaging commands the greatest tonnage. Retail packaging shows the steepest value-per-kilogram expansion on decoration technology upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping converter location decisions as REACH compliance costs in the EU push some film production toward jurisdictions with less stringent chemical registration requirements. Producers with multi-continental footprints leverage this gap to optimize margin while maintaining market access.
United States
EPA VOC regulations on solvent-based printing are forcing sleeve decorators toward water-based ink conversions. FDA food-contact certification timelines extend commercialization cycles for novel polyolefin formulations. Beverage co-packers in the Southeast are adopting controlled shrink-force films to reduce changeover downtime between PET and glass formats.
Germany
Industrial bundling demand from automotive component distribution networks concentrates procurement among converters with captive resin capabilities. ECHA phthalate restrictions under REACH accelerate converter migration from PVC toward polyethylene alternatives. The industrial packaging corridor in North Rhine-Westphalia anchors high-throughput film consumption for brake pad and filtration unit collation.
China
Organized retail expansion and cold chain infrastructure buildout create first-time shrink film demand for protein and dairy unitization. GB standards for food-contact materials shape formulation decisions for converters serving domestic brands. The Yangtze River Delta houses the densest concentration of biaxial orientation lines serving both export and domestic beverage markets.
India
Modern retail formats and cold chain investments displace loose distribution with unitized packaging for meat and dairy products. FSSAI compliance requirements for food-contact films favor converters with established testing protocols. Maharashtra's organized retail corridor generates concentrated demand for polyethylene roll film in protein unitization applications.
Brazil
Multipack beverage collation drives polyethylene bundling film consumption amid expanding retail distribution networks. ANVISA food-contact regulations shape material selection for converters serving processed protein exporters. São Paulo's industrial belt concentrates sleeve decoration capacity for personal care brands serving Latin American markets.
Shrink Packaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital printing convergence and short-run customization services. The vendor base clusters around three strategic archetypes: integrated resin-to-film converters with backward integration into polymer compounding, equipment-and-materials bundlers, and specialized sleeve decorators with decoration technology differentiation. Dominant competitive moves include geographic footprint expansion to serve consolidated multinational buyers and selective capacity additions in high-growth jurisdictions with emerging EPR frameworks.
Within the integrated converter tier, Amcor Plc and Berry Global exemplify scale-driven positioning through multi-continental manufacturing networks. Sealed Air anchors the equipment-and-materials bundler archetype with integrated offerings that reduce line-performance risk for beverage clients. Among specialized decorators, Bonset America Corporation and Clondalkin Group Holdings occupy positions tied to regional sleeve demand concentration in North America and Europe respectively.
| Leading Market Players |
|---|
| Bonset America Corporation |
| Clondalkin Group Holdings |
| Amcor Plc |
| ProAmpac |
| Allen Plastic Industries |
| Sealed Air |
| Coveris Holdings |
| Printpack |
| Berry Global |
| Others |
Value Chain & Pricing Dynamics
Backward integration into resin compounding anchors pricing power for film converters serving multinational beverage and personal care brands, compressing margins for non-integrated competitors while elevating procurement leverage for buyers with consolidated volume positions. The EU's Packaging and Packaging Waste Regulation intensifies this dynamic by forcing capital redeployment toward recyclable platforms, widening cost gaps between integrated and merchant suppliers.
Pricing Analysis
Distributor margin compression is accelerating as direct procurement from film producers displaces intermediary channels in North America and Western Europe. Three-tier pricing structure across premium, standard, and economy levels stratifies by food-contact certification tier and volume scale, with FDA-compliant polyolefin formulations commanding sustained premiums over industrial-grade alternatives. Pricing pressure stems from ethylene and propylene feedstock volatility, squeezing converters lacking captive resin capabilities. Beverage brand owners exhibit the highest price sensitivity due to consolidated procurement rosters, while personal care segments absorb premium decoration costs for shelf differentiation.
Supply Chain Analysis
Domestic-content mandates under India's FSSAI framework and China's GB standards are reshaping sourcing patterns for converters serving organized retail expansion in Asia-Pacific. Resin supply concentrates in Saudi Arabia, South Korea, and the United States, with metallocene polyethylene and ethylene-vinyl acetate copolymers serving as critical formulation inputs. Single-source vulnerability in biaxial orientation equipment creates bottleneck risk for sleeve production expansion. Distribution runs through converter-direct relationships with multinational brand owners, displacing traditional distributor networks in mature markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shrink packaging market functions as a stable compounder, with regulatory-driven material transitions sustaining replacement demand across beverage and personal care end-uses.
For Market Incumbents: Acquire biaxial orientation line capacity in Germany's North Rhine-Westphalia corridor to anchor automotive bundling demand. Invest in water-based ink system conversion ahead of EPA VOC enforcement timelines. Defensive consolidation around chemical recycling partnerships offsets margin compression from REACH compliance costs. For New Entrants and Emerging Players: Launch via digital inkjet sleeve decoration services targeting craft beverage short-run customization in North America. Exploit white-space in India's protein unitization segment as cold chain infrastructure displaces loose distribution. Penetrate through equipment-and-materials bundling partnerships with regional co-packers lacking in-house film expertise. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap sleeve decorators with regional decoration technology differentiation because buyer consolidation among multinational brand owners is compressing viable supplier counts. Five-to-ten year viability hinges on EPR framework participation enabling service revenue streams. Monitor chemical recycling partnership announcements as inflection signal for integrated converter positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply secures margin stability against ethylene feedstock volatility for beverage clients. |
| Water-Based Ink System Conversion | EPA VOC compliance enables sustained sleeve decoration capacity without regulatory shutdown risk. |
| Chemical Recycling Partnership | Extended producer responsibility frameworks in Germany and France create service revenue from post-consumer film recovery. |
| Digital Inkjet Decoration Deployment | Short-run customization capability captures craft beverage and specialty personal care brand switching. |
| Multi-Continental Manufacturing Footprint | Geographic diversification serves consolidated multinational buyers with single-source procurement mandates. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with film converter plant managers, procurement leads at beverage and personal care OEMs, distribution channel partners, and technical R&D directors informed supply-side and demand-side assessments. Secondary sources include customs and trade data, SEC filings, EPA regulatory dockets, ECHA registration databases, and industry association reports. Bottom-up capacity and consumption estimates were triangulated against top-down macroeconomic indicators.
Rate-of-change decomposition across the analysis window separates volume growth from value expansion, with segmentation modeling across product type, material grade, end-use industry, and regional production hub. CAGRs were derived from fitted trend analysis incorporating equipment installation cycles, regulatory compliance timelines, and brand owner procurement consolidation patterns. Forecast inputs include biaxial orientation line capacity expansion announcements and REACH phthalate restriction implementation schedules.
Several conditions sit outside the modeled scope, including unannounced mergers or acquisitions, abrupt feedstock price shocks, and delays in EPR framework implementation. Forecasts reflect documented assumptions about regulatory enforcement continuity and equipment technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Window Packaging Market
Packaging Materials
Thermal Transfer Roll Market
Packaging Materials
PET Strap Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Europe Paint Packaging Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Packaging Reel Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Wooden and Plywood Packaging Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Cardboard Trays Market
Packaging Materials
Production Page Volume Market
Packaging Materials
Floppy Disk Liner Market