
 North America Single-Use Medical Device Reprocessing Market | 2026-2036
North America Single-Use Medical Device Reprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Single-Use Medical Device Reprocessing Market Outlook
Consolidation among United States hospital purchasing alliances is repositioning procurement leverage toward reprocessing contracts with fewer, larger vendors. Stryker Corporation leverages its established reprocessing infrastructure to sustain volume commitments across multi-hospital systems. Medline Industries anchors its position through private-label distribution channels that compete directly with independent reprocessors. Innovative Health specializes in cardiac catheter reprocessing, occupying a niche that larger diversified suppliers navigate less aggressively.
Single-use medical device reprocessing encompasses the cleaning, functional testing, sterilization, and repackaging of devices originally labeled for one patient use, requiring validated processes that restore devices to substantially equivalent performance parameters. The practice reduces per-procedure supply costs by fifty to eighty percent compared to original device purchase while maintaining sterility assurance levels of ten to the negative six. Catheters dominate the device type segment due to high unit volumes in cardiac and electrophysiology procedures, though endoscopic devices represent the fastest-growing category as gastrointestinal reprocessing protocols mature. Hospitals remain the primary end user channel, but ambulatory surgical centers are expanding reprocessing adoption fastest as site-of-care migration accelerates procedural volume outside traditional inpatient settings.
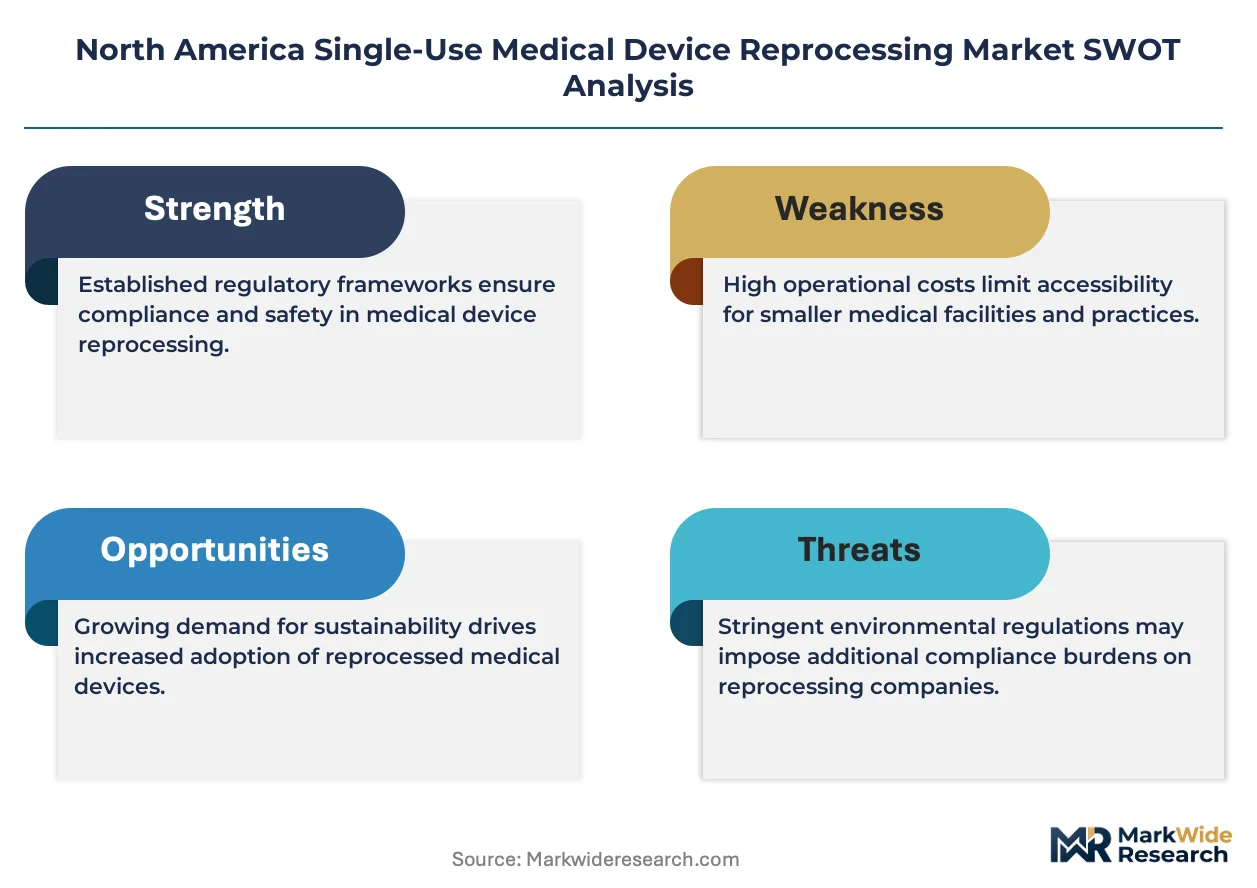
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern reprocessor market access, with the FDA's 2015 guidance on reprocessing validation establishing benchmark testing protocols that shape competitive barriers to entry. The Centers for Medicare & Medicaid Services reimbursement stance on reprocessed devices influences hospital adoption economics, particularly as Medicare Advantage penetration shifts payment risk toward providers. Stakeholders must monitor evolving FDA enforcement discretion letters and state-level reprocessing consent requirements to anticipate compliance cost trajectories.
Market Dynamics
Hospital purchasing alliance consolidation across the United States is compressing vendor rosters and awarding multi-year reprocessing contracts to scaled third-party providers with proven FDA 510(k) track records.
Growth Catalysts
- Medicare Advantage penetration:Risk-bearing provider organizations in the southeastern United States face acute cost-containment pressure. Reprocessed cardiac catheters cut per-procedure supply expenditures without altering clinical outcomes.
- ISO 13485 quality mandates:Third-party reprocessors with certified quality management systems capture procurement contracts from hospital systems seeking liability insulation. Certification acts as a competitive filter.
- Ambulatory surgical center expansion:Site-of-care migration from inpatient to outpatient settings accelerates reprocessing adoption. ASCs operate on thinner margins and prioritize supply cost reduction.
Market Restraints
- Polymer feedstock volatility:Medical-grade thermoplastics used in catheter manufacturing experience price swings tied to petrochemical markets. Input cost instability squeezes reprocessor margins.
- FDA validation protocol tightening:The agency's 2015 reprocessing guidance and subsequent enforcement discretion letters extend clearance timelines. Smaller reprocessors lack capital to sustain prolonged regulatory review.
- Original equipment manufacturer substitution:Device makers deploy pricing discounts and disposable bundling to defend catheter market position. OEM commercial tactics threaten reprocessor volume commitments.
Strategic Opportunities
- Mexican healthcare infrastructure:Private hospital chains in Monterrey and Guadalajara lack established reprocessing programs. Early entrants can anchor supply contracts before local competitors mature.
- Electrophysiology catheter specialization:Complex mapping and ablation devices command premium reprocessing margins. Technical barriers deter generalist competitors.
- State-level reprocessing consent harmonization:Legislative alignment across southeastern states would reduce compliance fragmentation. Uniform disclosure requirements lower multi-state operator costs.
Industry Challenges
- Sterilization validation engineering:Demonstrating ten to the negative six sterility assurance levels for luminal devices demands specialized microbiological expertise. Talent scarcity constrains reprocessor expansion.
- Legacy hospital inventory systems:Reprocessed device tracking requires serialization integration with existing supply chain software. IT retrofit costs delay program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Single-Use Medical Device Reprocessing Market |
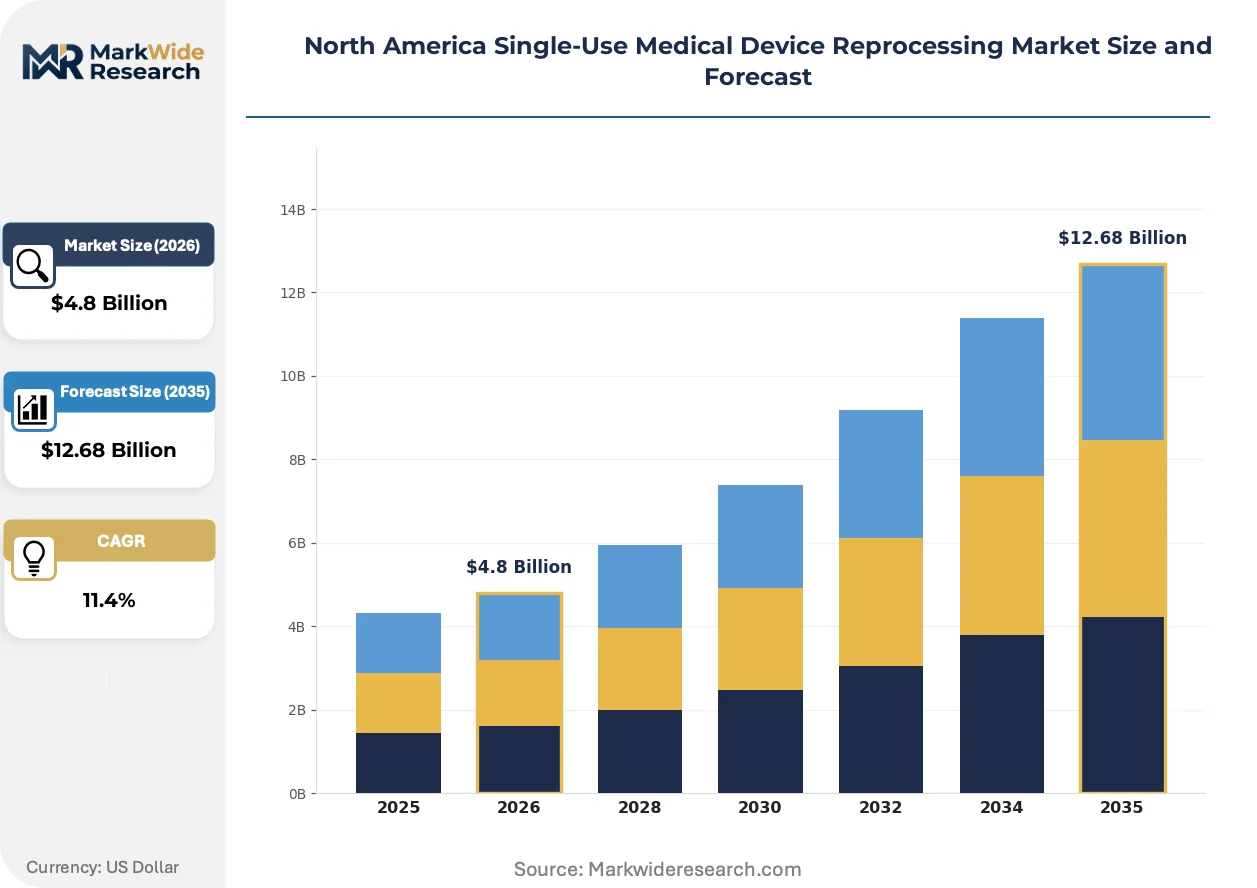
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Catheters, Surgical Instruments, Endoscopic Devices, Electrosurgical Tools End User: Hospitals, Ambulatory Surgical Centers, Clinics, Diagnostic Labs Methodology: Steam Sterilization, Ethylene Oxide, Radiation, Chemical Sterilization Regulatory Status: FDA Approved, ISO Certified, CE Marked, Other |
| Companies Covered | Stryker Corporation, Johnson & Johnson, Medline Industries, Inc., SureTek Medical, ReNu Medical, NEScientific, Inc., SterilMed, Inc., Innovative Health, Vanguard AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Single-Use Medical Device Reprocessing Market Strategic Shifts
Automated cleaning and inspection systems are replacing manual reprocessing workflows, compressing unit economics while tightening quality consistency across high-volume catheter categories.
Low-temperature hydrogen peroxide gas plasma sterilization is consolidating market preference for heat-sensitive electrophysiology devices. Academic medical centers in Boston and Cleveland have adopted the technology for complex catheter reprocessing. The shift is consolidating technical leadership among reprocessors with capital-intensive sterilization infrastructure.
FDA enforcement discretion letters are reshaping competitive access for cardiovascular device reprocessors. The agency's heightened scrutiny of validation data packages extends clearance timelines by twelve to eighteen months. Cardiac catheter specialists with established 510(k) portfolios are absorbing market share from entrants caught in regulatory backlog.
Integrated delivery networks are unbundling reprocessing contracts from broad medical-surgical supply agreements. Procurement officers in Texas and Florida health systems now negotiate reprocessing as a standalone category with dedicated performance metrics. The separation is compressing pricing opacity and accelerating vendor switching cycles.
North America Single-Use Medical Device Reprocessing Market Segmentation
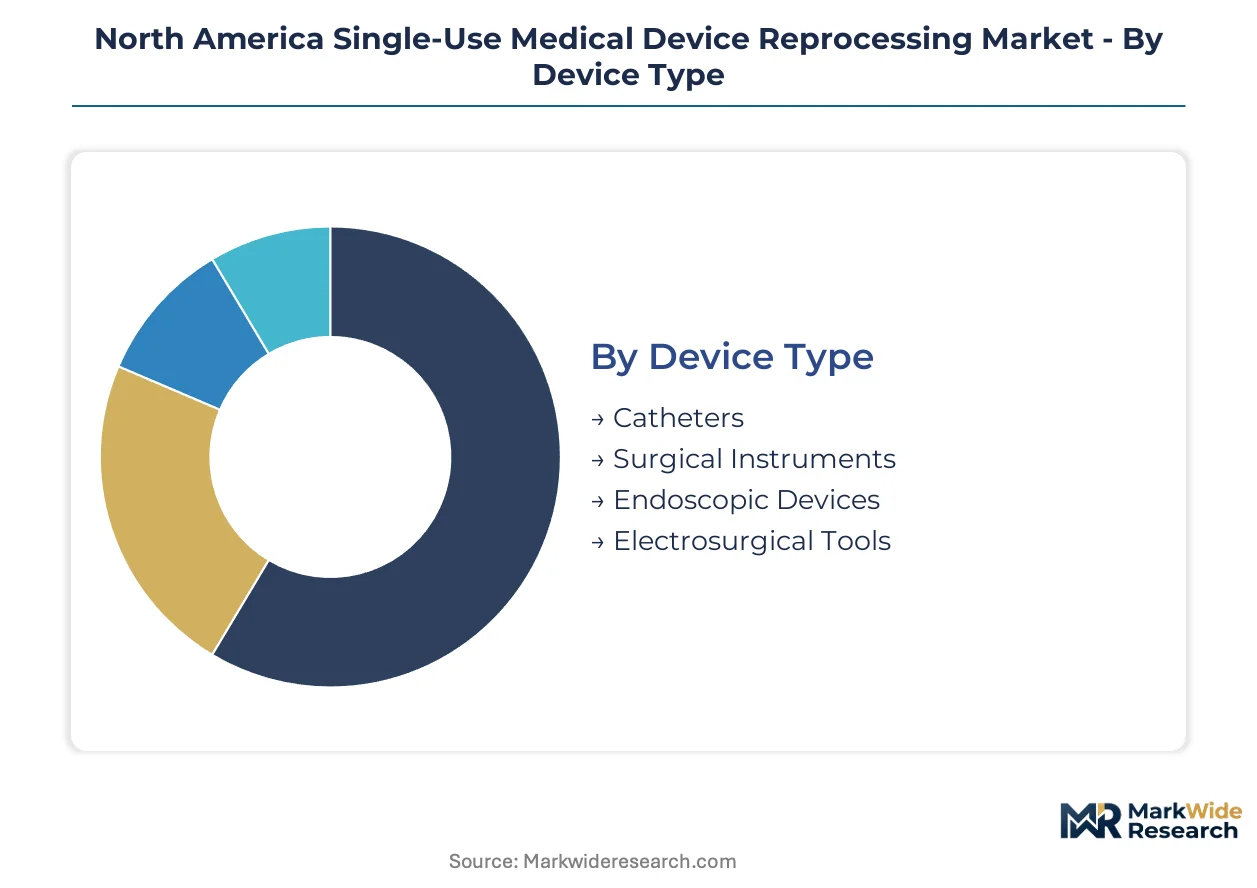
Segmentation in single-use medical device reprocessing determines which device categories justify the capital investment in validated cleaning and sterilization infrastructure. Hospital procurement officers evaluate segments based on procedural volume density, regulatory clearance complexity, and per-unit cost savings potential.
Device Type:
Some device categories operate as standalone reprocessing programs with dedicated facility footprints, while others embed within broader surgical supply workflows as secondary cost-reduction layers.
- Catheters:Luminal structures in cardiac and electrophysiology applications require validated cleaning protocols that restore interior channel patency. Demand concentrates in southeastern United States integrated delivery networks operating high-volume cardiac labs, where FDA 510(k) clearance requirements for reprocessed devices have tightened validation protocols. Reprocessed cardiac catheters cut per-procedure supply expenditures without altering clinical outcomes.
- Endoscopic Devices:Flexible gastrointestinal scopes with complex channel architectures demand specialized drying and sterilization cycles. Ambulatory surgical centers in Texas and Florida health systems are expanding adoption fastest as site-of-care migration accelerates procedural volume outside traditional inpatient settings. Gastrointestinal reprocessing protocols are maturing fastest in this category.
- Surgical Instruments:Metal forceps, scissors, and clamps with simpler geometries embed within general surgical reprocessing workflows. ISO 13485 quality mandates filter competitive access.
- Electrosurgical Tools:Energy-delivery devices with insulated components require functional testing for electrical integrity. OEM substitution tactics threaten volume commitments.
Catheters lead volumes today; endoscopic devices are gaining share fastest.
End User:
Customer type determines contract structure, with high-volume purchasers extracting multi-year commitments and smaller operators accepting spot pricing.
- Hospitals:Inpatient facilities with cardiac catheterization laboratories and electrophysiology suites anchor reprocessing program economics. Hospital purchasing alliance consolidation across the United States compresses vendor rosters and awards multi-year contracts to scaled third-party providers. Procurement officers now negotiate reprocessing as a standalone category with dedicated performance metrics.
- Ambulatory Surgical Centers:Outpatient surgical facilities operate on thinner margins and prioritize supply cost reduction. ASCs in the southeastern United States face acute cost-containment pressure from Medicare Advantage penetration. The segment is expanding reprocessing adoption fastest.
- Clinics:Lower-volume settings embed reprocessing within broader medical-surgical supply agreements rather than standalone programs.
- Diagnostic Labs:Specialized testing facilities with limited procedural scope represent niche demand concentration.
Hospitals dominate contract value today; ambulatory surgical centers are climbing the fastest.
Methodology:
Sterilization technology selection tracks device heat sensitivity and material compatibility constraints.
- Steam Sterilization:High-temperature saturated steam penetrates non-luminal metal instruments with established lethality assurance. Academic medical centers in Boston and Cleveland have adopted the technology for standard surgical instrument reprocessing.
- Ethylene Oxide:Low-temperature gas diffusion sterilizes heat-sensitive polymers and electronic components. The method extends clearance timelines due to aeration requirements.
- Radiation:Gamma and electron beam processing penetrates packaging for terminal sterilization of disposable assemblies. Capital intensity limits adoption to high-volume reprocessors.
- Chemical Sterilization:Low-temperature hydrogen peroxide gas plasma consolidates market preference for heat-sensitive electrophysiology devices. The shift is consolidating technical leadership among reprocessors with capital-intensive sterilization infrastructure.
Steam sterilization leads installed base today; chemical sterilization is expanding most quickly.
Regulatory Status:
Certification tier determines market access and pricing power in hospital procurement.
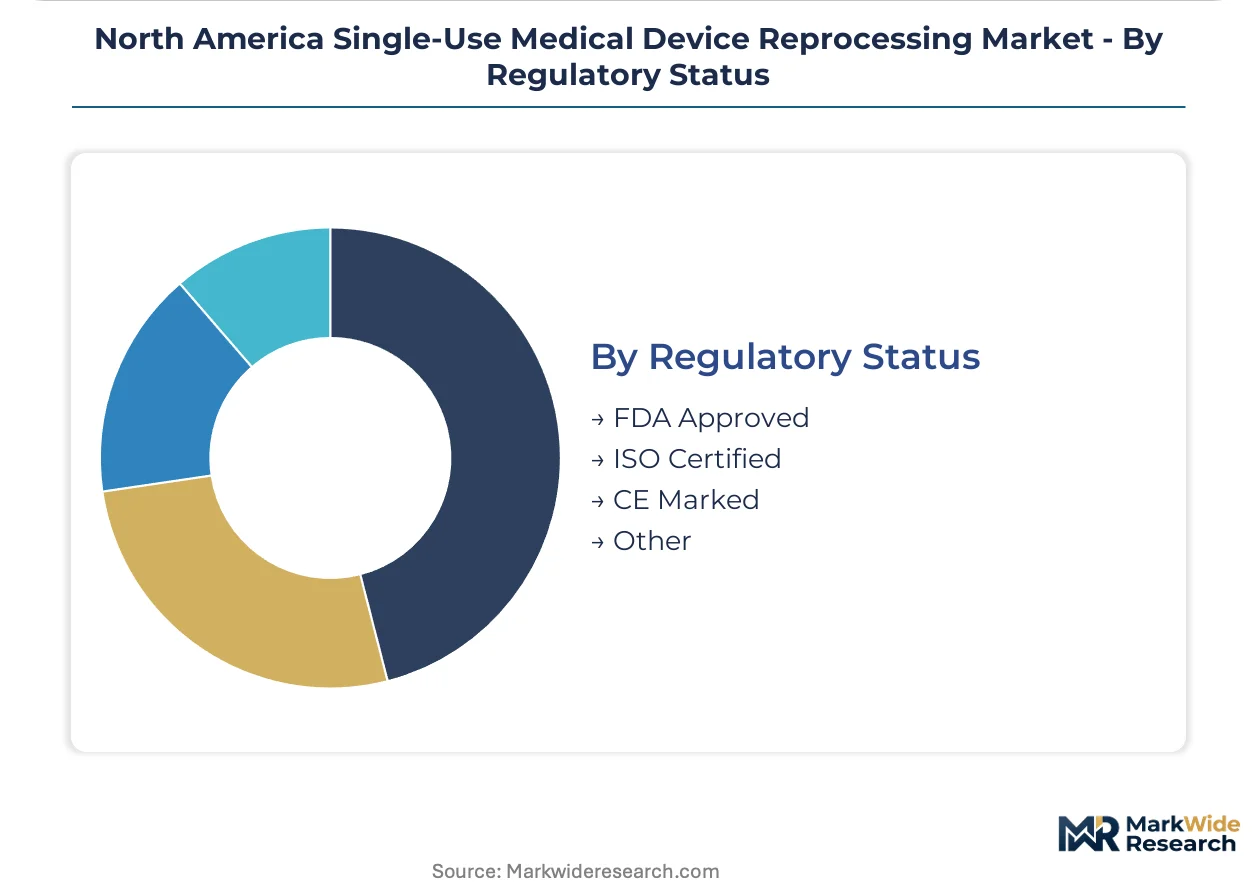
- FDA Approved:510(k) clearance establishes substantial equivalence to predicate devices and enables commercial distribution. The FDA's 2015 guidance on reprocessing validation shapes competitive barriers to entry.
- ISO Certified:ISO 13485 quality management system certification acts as a competitive filter for procurement contracts from hospital systems seeking liability insulation.
- CE Marked:European conformity marking holds limited relevance in North American commercial negotiations.
- Other:State-level reprocessing consent requirements create compliance fragmentation across southeastern United States jurisdictions.
FDA approved status leads procurement preference today; ISO certification is gaining contractual weight fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates reprocessing volume while Canada maintains tighter procurement centralization; Mexico's private hospital sector presents untapped contract opportunities for validated third-party providers.
United States
Integrated delivery networks in Texas and Florida operate high-volume cardiac catheterization laboratories that anchor regional demand. FDA 510(k) clearance requirements shape competitive access, with enforcement discretion letters extending validation timelines for new entrants. The southeastern United States concentrates procurement activity where Medicare Advantage penetration pressures cost-containment strategies.
Canada
Provincial health authorities in Ontario and Quebec consolidate purchasing through centralized supply agreements that favor ISO 13485-certified reprocessors. Health Canada oversight aligns with FDA validation protocols while maintaining distinct quality management expectations. Academic medical centers in Toronto and Montreal pilot low-temperature sterilization technologies for complex electrophysiology devices.
Mexico
Private hospital chains in Monterrey and Guadalajara lack established reprocessing infrastructure despite expanding cardiac procedure volumes. COFEPRIS regulatory frameworks for medical device reprocessing remain less prescriptive than FDA standards, creating compliance interpretation variability. Early third-party entrants can anchor supply contracts before local competitors achieve validated quality systems.
North America Single-Use Medical Device Reprocessing Market Competitive Environment
United States producers anchor one tier; Canadian and Mexican specialists hold peripheral positions with limited scale. The market structure concentrates around diversified medical device conglomerates with established reprocessing infrastructure alongside niche cardiac catheter specialists. Three archetypes dominate: integrated device manufacturers with captive reprocessing divisions, independent third-party reprocessors with FDA 510(k) portfolios, and private-label distributors competing on procurement channel access. Competitive moves center on multi-year hospital purchasing alliance contracts and sterilization capacity expansion for heat-sensitive electrophysiology devices.
Within the diversified conglomerate tier, Stryker Corporation and Johnson & Johnson occupy positions defined by vertical integration into hospital supply chains and established regulatory track records. Among independent specialists, Innovative Health exemplifies the cardiac catheter-focused archetype that larger diversified suppliers navigate less aggressively. Medline Industries anchors the private-label distribution segment, competing through procurement channel density rather than device-specific technical specialization.
| Leading Market Players |
|---|
| Stryker Corporation |
| Johnson & Johnson |
| Medline Industries, Inc. |
| SureTek Medical |
| ReNu Medical |
| NEScientific, Inc. |
| SterilMed, Inc. |
| Innovative Health |
| Vanguard AG |
| Others |
Value Chain & Pricing Dynamics
Medical-grade thermoplastic resin indices cascade through North American reprocessing supply chains, compressing margins at independent operators while insulating vertically integrated conglomerates with captive polymer sourcing. Price stratification across premium, standard, and economy tiers tracks directly to sterilization validation depth and FDA 510(k) clearance status.
Pricing Analysis
Capacity additions in Mexico are reshaping price floors for standard-tier reprocessed catheters, forcing incumbent US operators toward premium electrophysiology specialization. Three-tier pricing structure across premium, standard, and economy levels differentiates by ISO 13485 certification tier and sterilization technology sophistication. Cost compression in the standard tier intensifies because OEM bundling discounts defend original device market position. Ambulatory surgical centers exhibit acute price sensitivity; academic medical centers with risk-bearing Medicare Advantage contracts prioritize liability insulation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements embedded in Texas and Florida health system contracts mandate multi-supplier qualification for cardiac catheter reprocessing programs. Manufacturing concentration centers on the United States, Mexico, and Costa Rica for sterilization equipment assembly; polymer feedstock draws from Gulf Coast petrochemical corridors and Canadian resin distributors. Supply chain risk hinges on single-source vulnerability for hydrogen peroxide gas plasma sterilization chambers. Distribution runs through group purchasing organization contracts and direct hospital system agreements, bypassing traditional medical-surgical distributors for high-volume catheter categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American single-use device reprocessing functions as a geographic-arbitrage play: FDA validation costs in the United States run substantially higher than COFEPRIS compliance expenses in Mexico, creating margin expansion potential for cross-border operators.
For Market Incumbents: Anchor multi-year purchasing alliance contracts through sterilization capacity expansion in Monterrey and Guadalajara, exploiting regulatory cost differentials. Deepen backward integration into polymer recycling streams to offset feedstock volatility. Prioritize electrophysiology catheter specialization where technical barriers deter generalist competitors and OEM substitution tactics lose effectiveness. For New Entrants and Emerging Players: The premium-to-economy price gap in cardiac catheter reprocessing opens white-space entry through mid-tier ISO certification investment. Target ambulatory surgical centers in southeastern United States Medicare Advantage penetration zones, where cost-containment pressure exceeds brand loyalty. Pursue hospital-at-home and outpatient migration corridors as procedural volume shifts accelerate reprocessing adoption outside traditional inpatient settings. For Investors and Strategic Acquirers: Asymmetric upside sits with independent reprocessors holding established FDA 510(k) portfolios amid enforcement discretion letter backlogs that freeze new entrant access. Long-term viability favors specialists with capital-intensive sterilization infrastructure and validated electrophysiology protocols. Watch FDA clearance timeline normalization as the inflection signal; accelerated review would erode incumbent regulatory moats.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortened clearance timelines would compress competitive moats for established reprocessors. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and Florida anchor volume commitments. |
| Low-Temperature Sterilization Capacity Expansion | Hydrogen peroxide gas plasma infrastructure captures premium electrophysiology reprocessing margins. |
| Geographic Manufacturing Footprint | Monterrey facilities exploit COFEPRIS-FDA cost differentials for margin expansion. |
| Reimbursement Strategy | Medicare Advantage risk-bearing contracts prioritize reprocessed device economics. |
Study Parameters
Multiple input streams — hospital procurement database analysis, GPO contract documentation, and CMS Medicare claims data — were reconciled against primary interviews with biomedical engineers, hospital purchasing committee members, and third-party reprocessor operations directors. Secondary validation drew from FDA 510(k) clearance databases, ISO 13485 certification registries, and hospital supply chain software integration records. Bottom-up unit volume modeling and top-down market sizing triangulated across these sources.
Historical reprocessing adoption curves were cross-referenced against panel input from cardiac catheterization laboratory directors to calibrate penetration assumptions across the projection horizon. Segmentation dimensions modeled include device type complexity, end-user facility scale, sterilization methodology, and regulatory certification tier. CAGRs were derived from procedure volume growth trajectories and reprocessing penetration rate elasticity. Forecast inputs incorporated Medicare Advantage enrollment shifts and ambulatory surgical center expansion pipelines.
The model assumes a particular technology adoption path; alternative pathways for low-temperature hydrogen peroxide gas plasma sterilization would alter the outlook if academic medical center adoption accelerates beyond baseline assumptions. Deviation in FDA enforcement discretion letter volume or COFEPRIS regulatory harmonization timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Otoscope Market
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
Orthodontic Headgear Market
Medical Devices
Breast Localization System Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Syringeless Injector Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Knee Walkers Market
Medical Devices
EEG Electrodes Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Hemodynamic Flow Alteration Devices Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Epilepsy Devices Market