
 Removable Partial Dentures Market | 2026-2036
Removable Partial Dentures Market Size, Share, and Industry Trends Forecast 2026-2036
Removable Partial Dentures Market Analytics
The price-performance gap between premium and commodity tiers is expanding. Dentsply Sirona leverages its digital workflow ecosystem to dominate high-margin segments. Glidewell anchors the North American laboratory channel through centralized manufacturing scale. Modern Dental Group Limited competes on cost-optimized acrylic frameworks across Asian export markets.
Removable partial dentures are dental prostheses replacing one or more missing teeth, typically fabricated from cobalt-chromium frameworks with acrylic saddles and artificial teeth, retained by clasps engaging remaining natural abutments. Metal frameworks sustain premium positioning due to biocompatibility and thin-profile strength, while flexible thermoplastic segments capture aesthetic-sensitive cases seeking clasp-free designs. Dental clinics represent the dominant end-user channel, though dental laboratories increasingly intermediate through outsourcing relationships with chairside practices.
FDA 510(k) pathways govern polymer and metal biocompatibility standards for U.S. market entry, while ISO 22674 specifies metallic materials for fixed and removable restorations internationally. The EU Medical Device Regulation intensifies conformity assessment burdens for titanium framework imports. Stakeholders must monitor reimbursement code revisions by national health authorities, as these directly determine patient out-of-pocket exposure and laboratory case volumes.
Market Dynamics
Digital dentistry workflows are compressing fabrication timelines from weeks to days, forcing traditional dental laboratories to restructure technician staffing and capital deployment around intraoral scanning and chairside milling capabilities.
Growth Catalysts
- Aging Demographics in Germany and Japan:Prosthodontic clinics in these markets face surging edentulous patient volumes. Cobalt-chromium framework demand tracks directly with 65-plus population expansion.
- FDA 510(k) Pathway Clarity:Polymer biocompatibility standards for 3D-printed denture bases have streamlined market entry. Domestic manufacturers leverage this regulatory predictability to accelerate product iterations.
- Flexible Thermoplastic Materials:Aesthetic-sensitive patients reject visible metal clasps. Nylon-based frameworks capture this preference shift in private-pay dental segments.
Market Restraints
- Cobalt-Chromium Alloy Volatility:Mining concentration in South African platinum group metal belts exposes framework costs to supply disruption. Laboratories pass through price swings unpredictably.
- EU Medical Device Regulation Conformity:Titanium framework imports face intensified notified body scrutiny. Extended assessment timelines freeze product launches for 12-18 months.
- Dental Implant Substitution:Endosseous fixtures displace RPDs in partially edentulous cases with sufficient bone volume. Implant-supported prostheses command higher reimbursement in fee-for-service markets.
Strategic Opportunities
- India's Underpenetrated Laboratory Channel:Organized dental laboratory networks remain fragmented. Centralized digital production hubs can aggregate case volume from dispersed chairside practices.
- Japan's PMDA Streamlined Review:Revised pharmaceutical and medical device agency pathways for 3D-printed dental devices reduce premarket notification burdens. Early entrants capture technician training relationships.
- Tele-dentistry Workflow Integration:Remote impression validation and digital design review compress patient chair time. Hybrid models merge clinical examination with laboratory-centric production.
Industry Challenges
- Digital Workflow Certification Gaps:Master dental technicians trained in wax-and-cast methods require 6-12 month reskilling for CAD/CAM software stacks. Workforce transition lags capital investment.
- Legacy Practice Management System Integration:Intraoral scanners from Dentsply Sirona, 3Shape, and Medit export incompatible file formats. Laboratories maintain multiple software licenses or reject case types.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Removable Partial Dentures Market |
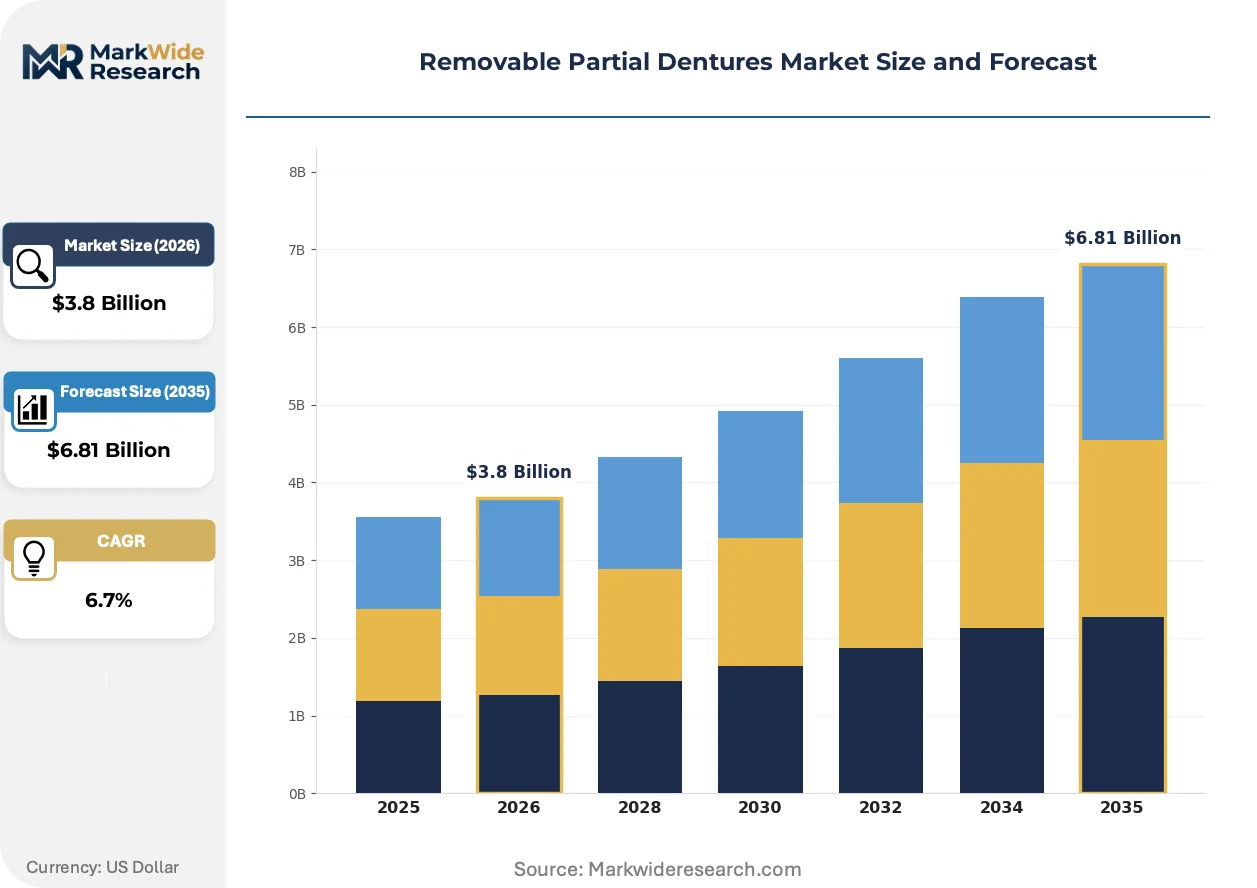
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Metal, Flexible, Combination Application: Reconstructive Dentistry, Aesthetic Restoration, Functional Restoration, Tooth Loss Management End User: Dental Clinics, Hospitals, Research Institutes, Dental Laboratories Material: Polymer, Cobalt-Chromium, Titanium, Thermoplastic |
| Companies Covered | Dentsply Sirona, Glidewell, Ivoclar Vivadent, Aspen Dental Management, VITA Zahnfabrik, Modern Dental Group Limited, H. Rauter GmbH & Co. KG, Yamahachi Dental Products, Kanfit 3D Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Removable Partial Dentures Market Evolving Landscape
Chairside digital fabrication is collapsing the traditional laboratory intermediary role. Three parallel developments are restructuring how removable partial dentures are designed, produced, and delivered to patients.
PEEK polymer frameworks are absorbing aesthetic case volume previously captured by flexible nylon alternatives. Prosthodontic clinics in the United States adopt PEEK for its bone-like radiopacity and biocompatibility profile. The material is absorbing premium positioning in clasp-free partial denture segments as laboratories market its CT-scan compatibility to implant planning workflows.
ISO 22674 metallic material specifications are harmonizing international framework standards. The European Union's MDR cross-references this standard for titanium alloy conformity assessment. Asian export manufacturers align production to ISO 22674 grades to access German and French laboratory procurement channels without duplicate testing.
Subscription-based design software is displacing perpetual license models among dental laboratories. 3Shape and exocad now price CAD modules on monthly per-technician tiers. This procurement pattern shift lowers entry barriers for mid-sized laboratories in Spain and Italy while locking users into ecosystem-specific hardware pairings.
Removable Partial Dentures Market Segmentation
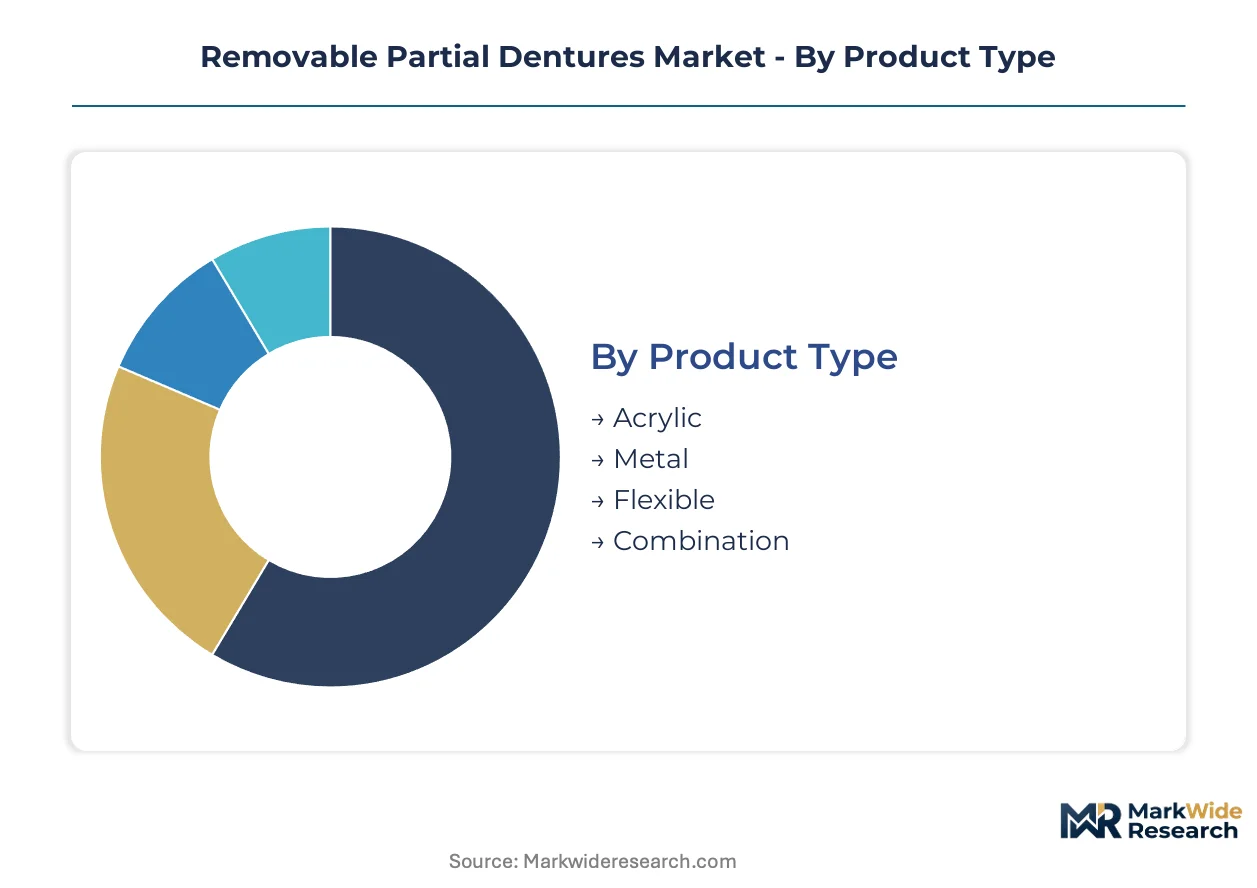
Removable partial dentures serve distinct clinical and economic niches that shape procurement patterns across dental supply chains. Segmentation reveals how material selection, end-user channel, and application intent determine margin structures and regulatory exposure for manufacturers.
Product Type:
Supply concentration in cobalt-chromium casting and thermoplastic injection molding creates divergent cost-to-performance profiles across fabrication methods.
- Metal:Cobalt-chromium frameworks deliver thin-profile strength and biocompatibility for long-span edentulous cases. German prosthodontic clinics specify metal for patients with sufficient posterior abutment support, though South African mining concentration exposes costs to supply disruption.
- Flexible:Nylon-based thermoplastic frameworks eliminate visible clasps through gum-colored baseplates. Private-pay segments in the United States absorb premium positioning for aesthetic-sensitive patients rejecting metal visibility.
- Acrylic:Economical option for interim prostheses and short-term tooth replacement needs.
- Combination:Hybrid designs merge metal substructures with acrylic saddles for customized strength-to-aesthetics ratios.
Metal frameworks absorb the bulk of installed capacity in European laboratory channels; flexible alternatives are expanding most quickly in North American private-pay segments.
Application:
Clinical intent separates high-margin reconstructive cases from commodity replacement workflows.
- Reconstructive Dentistry:Complex cases involving multiple missing teeth and compromised occlusal schemes demand precision frameworks with cast clasps. Japanese prosthodontic clinics drive volume for cobalt-chromium solutions in geriatric patient populations.
- Aesthetic Restoration:Anterior tooth replacement prioritizes clasp-free designs and tissue-matched baseplates. Thermoplastic and PEEK polymer frameworks capture this preference shift in urban U.S. practices.
- Functional Restoration:Masticatory efficiency drives posterior segment replacement with emphasis on occlusal load distribution.
- Tooth Loss Management:Interim solutions bridge extraction-to-definitive restoration timelines with cost-optimized acrylic options.
Reconstructive applications command the highest laboratory fees per unit; aesthetic restoration shows the steepest expansion trajectory as patient preference shifts toward invisible prosthodontics.
End User:
Channel structure determines whether production flows through centralized laboratory networks or chairside digital workflows.
- Dental Clinics:Chairside practices generate case volume through direct patient relationships. U.S. fee-for-service models sustain higher RPD utilization than single-payer systems, with intraoral scanning compressing traditional laboratory intermediation.
- Dental Laboratories:Centralized production hubs aggregate cases from dispersed practices. Glidewell anchors North American volume through scale manufacturing and digital design services.
- Hospitals:Academic medical centers and oral surgery departments handle complex trauma and oncologic reconstruction cases.
- Research Institutes:Biomaterials development and clinical validation studies drive experimental framework testing.
Dental clinics channel the majority of case volume; dental laboratories are gaining share fastest as digital workflows enable remote production models.
Material:
Biocompatibility certification tiers separate premium framework supply from commodity acrylic segments.
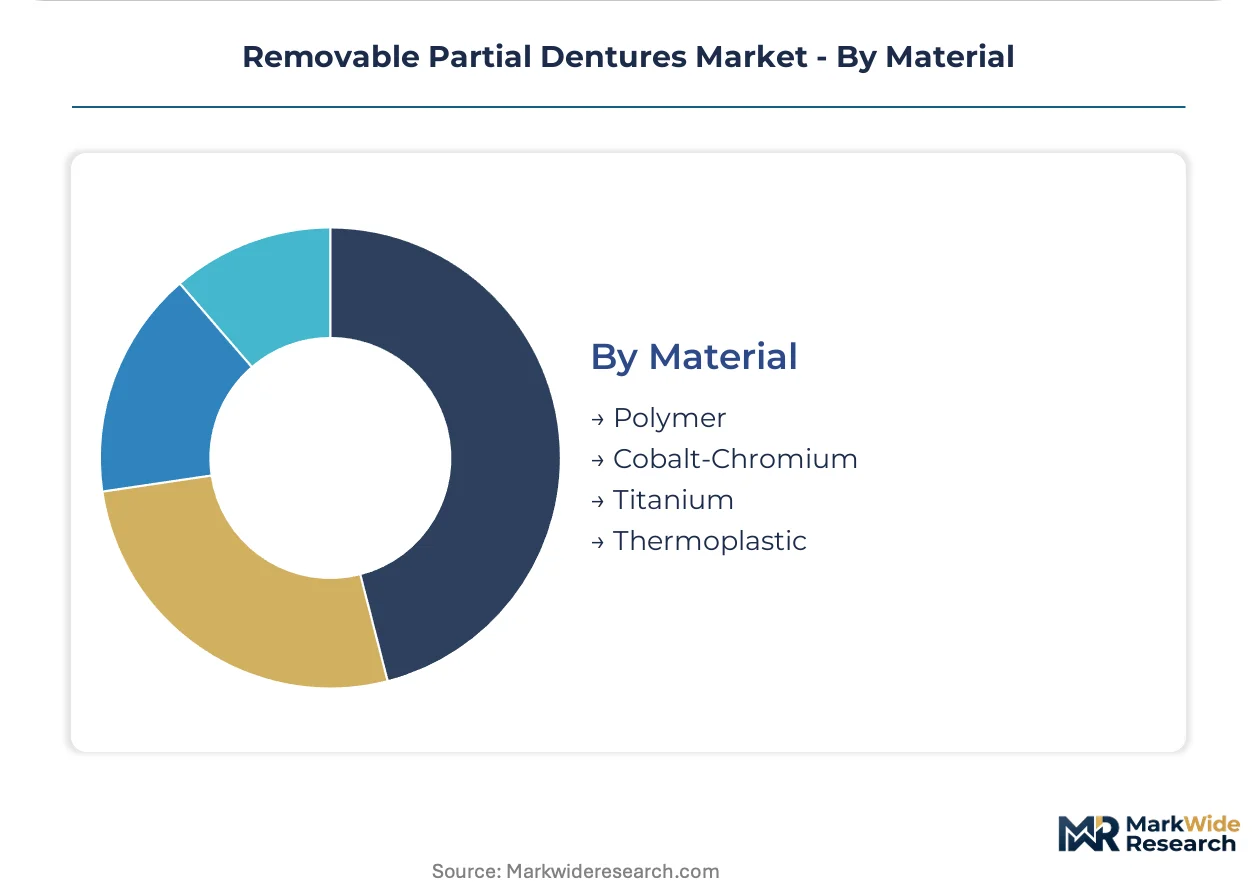
- Cobalt-Chromium:ISO 22674-compliant alloys dominate premium framework production. German and French laboratory procurement channels require documented conformity to metallic material specifications for titanium and cobalt-chrome imports.
- Thermoplastic:Nylon and PEEK polymers absorb aesthetic-case volume previously captured by flexible alternatives. FDA 510(k) pathway clarity for polymer biocompatibility has streamlined domestic U.S. market entry.
- Polymer:Conventional acrylic resins serve interim and economy segments with established processing protocols.
- Titanium:Lightweight biocompatibility targets patients with metal sensitivity concerns, though EU MDR intensifies notified body scrutiny for framework imports.
Cobalt-chromium retains the largest share of definitive prosthesis production; thermoplastic materials are climbing the fastest as CAD/CAM fabrication matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Charlotte, North Carolina anchors North American laboratory consolidation through centralized digital production hubs serving dispersed chairside practices across the Southeast and Mid-Atlantic corridors.
United States
Fee-for-service dental models sustain higher RPD utilization than single-payer alternatives, with prosthodontic clinics in Florida and Texas driving cobalt-chromium framework volume. FDA 510(k) pathway clarity for polymer biocompatibility accelerates domestic 3D-printed denture base approvals. Glidewell's Costa Mesa facility aggregates case volume from thousands of practices through scale manufacturing and digital design services.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia expand edentulous patient populations seeking precision frameworks. EU Medical Device Regulation cross-references ISO 22674 for titanium alloy conformity assessment, intensifying notified body scrutiny. Stuttgart's dental laboratory cluster specializes in cobalt-chromium casting for geriatric reconstructive cases requiring long-span strength.
Japan
Prosthodontic clinics in Tokyo and Osaka face surging demand from 65-plus populations rejecting visible metal clasps. PMDA streamlined review pathways for 3D-printed dental devices reduce premarket notification burdens. Nagoya's technician training centers capture early-entrant relationships as digital workflows displace wax-and-cast methods.
India
Organized dental laboratory networks remain fragmented across Maharashtra and Gujarat, creating aggregation opportunities for centralized digital production. The country's national pharmaceutical regulator maintains biocompatibility standards for imported framework materials. Mumbai's dental cluster serves as the primary import channel for European cobalt-chromium alloys.
China
Export manufacturers in Guangdong and Zhejiang align production to ISO 22674 grades for German and French laboratory procurement. NMPA governs polymer and metal biocompatibility standards for domestic market entry. Shenzhen's digital dentistry equipment corridor supplies intraoral scanners to laboratories across Southeast Asia.
Removable Partial Dentures Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across fabrication workflows. Foundry-dependent laboratories maintain cobalt-chromium casting infrastructure while digital-native competitors outsource framework production to centralized hubs. Three archetypes dominate: integrated dental equipment conglomerates controlling chairside-to-laboratory workflows, scale-focused laboratory networks aggregating case volume through geographic density, and specialized framework fabricators serving export markets through cost-optimized acrylic production. Competitive moves concentrate on M&A for digital workflow capabilities and strategic partnerships bridging scanner hardware with design software ecosystems.
Among integrated equipment conglomerates, Dentsply Sirona occupies a position exemplifying ecosystem control across premium-tier digital workflows. Glidewell anchors North American volume through scale laboratory networks serving dispersed practices. Modern Dental Group Limited represents the export-specialist archetype, competing on cost-optimized framework production for Asian laboratory procurement channels.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Glidewell |
| Ivoclar Vivadent |
| Aspen Dental Management |
| VITA Zahnfabrik |
| Modern Dental Group Limited |
| H. Rauter GmbH & Co. KG |
| Yamahachi Dental Products |
| Kanfit 3D Ltd. |
| Others |
Value Network & Pricing Analysis
Captive cobalt-chromium foundry operations among German and Japanese framework manufacturers anchor both supply security and premium-tier pricing power. Laboratories with in-house casting capacity command higher margins on precision frameworks while insulating patient fees from South African mining volatility.
Pricing Analysis
Throughput-based pricing anchors laboratory procurement contracts, with per-unit framework fees scaling to case complexity and turnaround speed. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22674-certified cobalt-chromium from FDA-cleared thermoplastic and unbranded acrylic interim solutions. Cost compression in flexible nylon segments is intensifying because Asian export manufacturers scale injection-molding capacity. Dental clinics in single-payer systems exhibit highest price sensitivity; U.S. fee-for-service practices absorb premium positioning for aesthetic-sensitive patients.
Supply Chain Analysis
Refurbishment flows for cobalt-chromium frameworks remain minimal given biocompatibility requirements and patient-specific fitting constraints. Mining concentration in South Africa, alloy processing in Germany, and precision casting in Japan create geographic dependencies across the value chain. Raw material exposure centers on platinum group metal belts, chromium ore grades, and polymer resin feedstocks. Single-source vulnerability in South African mining districts threatens framework cost stability. Distribution runs through centralized laboratory networks aggregating cases from dispersed chairside practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master dental technician capacity constraints prop pricing power for laboratories retaining wax-and-cast expertise. Foundry-dependent production methods face reskilling bottlenecks that limit competitive entry.
For Market Incumbents: Cement ecosystem control through CAD/CAM software-hardware bundling that locks laboratories into proprietary file formats. Deepen backward integration into cobalt-chromium alloy supply through long-term offtake agreements with South African processors. Defend against digital-native competitors by acquiring chairside milling capabilities that compress patient chair time.
For New Entrants and Emerging Players: FDA 510(k) pathway clarity in the United States opens a window for polymer framework specialists to capture aesthetic-restoration volume from metal-averse patient segments. Target India's fragmented laboratory channel through centralized digital production hubs aggregating case volume from Maharashtra and Gujarat practices. Lead with tele-dentistry workflow integration that merges remote impression validation with laboratory-centric fabrication.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by dental equipment conglomerates seeking digital workflow capabilities. Five-to-ten-year viability hinges on reskilling velocity for technician workforces transitioning from analog to CAD/CAM methods. Target acquisition archetype: mid-scale laboratories with established clinician relationships and unconverted digital infrastructure. Monitor PMDA streamlined review implementation in Japan for early-entrant signal generation.
| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Software Ecosystem Lock-in | Proprietary file formats from 3Shape and exocad prevent laboratory multi-homing. |
| Cobalt-Chromium Alloy Supply Agreement | Long-term offtake with South African processors insulates against platinum group metal volatility. |
| Chairside Digital Fabrication Deployment | Intraoral scanning and milling capabilities collapse traditional laboratory intermediation timelines. |
| PEEK Polymer Framework Certification | FDA 510(k) clearance for bone-like radiopacity captures aesthetic-sensitive patient volume. |
| Technician Reskilling Program | Nagoya training centers convert wax-and-cast expertise to CAD/CAM software proficiency. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with prosthodontic clinic directors, dental laboratory owners, biomedical engineers at framework manufacturers, and GPO contracts managers validated demand-side assumptions. FDA 510(k) databases, PMDA submission records, EU MDR notified body assessments, and ISO 22674 conformity documentation supplied regulatory context. Bottom-up case volume estimates from dental laboratory networks triangulated against top-down spending data from national health authorities.
Granularity-level modeling tracked framework production by material certification tier, end-user channel structure, and application intent across the projection horizon. Segmentation dimensions included product type, clinical application, procurement channel, and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to base-year volume estimates, with cross-validation against demographic edentulism projections and dental workforce expansion rates. Implant substitution rates and digital adoption curves served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for chairside 3D printing would alter the outlook for laboratory intermediary roles. Forecasts reflect assumptions regarding FDA review timelines, EU MDR conformity assessment durations, and technician reskilling velocities that could shift with regulatory or educational policy changes. Practitioners should monitor PMDA implementation guidance, South African mining labor actions, and dental school curriculum revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Heart Defect Closure Devices Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Breathing Exercise Devices Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
Pressure Ulcer Devices Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Intrasaccular Embolization Systems Market
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
Jet Nebulizers Market