
 Americas Flash Memory Market | 2026-2036
Americas Flash Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Flash Memory Market Insights
Foundry expansion in Arizona and Texas is realigning regional supply chains for advanced NAND fabrication. Micron Technology Inc. anchors domestic wafer output with massive fabrication investments in Boise and Phoenix. Samsung Electronics competes through its Taylor, Texas complex, leveraging vertical integration from wafer to module assembly. SK Hynix positions itself through specialized HBM and enterprise SSD development targeting North American cloud infrastructure.
Americas Flash Memory encompasses non-volatile solid-state storage devices utilizing floating-gate or charge-trap transistor cells, typically manufactured through lithographic processes at nodes below 15nm with layer counts exceeding 200 in 3D NAND architectures, retaining data without power for industrial, consumer, and enterprise applications. SSD deployments dominate enterprise storage revenue pools as cloud providers displace mechanical drives, while embedded flash segments sustain momentum from automotive ECU and telematics integration. Memory modules serving data center OEMs concentrate margin capture through validated supply agreements with server manufacturers.
FCC equipment authorization requirements govern wireless-enabled flash devices, while EPA hazardous substance rules constrain material selection and end-of-life processing across the value chain. NHTSA cybersecurity guidelines for connected vehicles are reshaping embedded flash specifications for automotive qualification tiers. Stakeholders must monitor how BIS export control refinements affect equipment sourcing for domestic advanced node expansion.
Market Dynamics
Data center operators across the United States are accelerating NAND flash procurement for AI training infrastructure, creating concentrated demand pull that is reshaping foundry capacity allocation toward enterprise SSD wafer starts.
Growth Catalysts
- AI Training Infrastructure:Cloud hyperscalers in Texas and Arizona are commissioning exabyte-scale storage arrays for large language model workloads, pulling forward 200-layer 3D NAND wafer commitments.
- Automotive ECU Integration:NHTSA cybersecurity guidelines for connected vehicles are mandating embedded flash with hardware root-of-trust capabilities across Tier 1 supplier qualification tiers.
- EPA E-Waste Pressure:Evolving hazardous substance rules are forcing module manufacturers toward longer-lifecycle designs that extend replacement intervals in enterprise storage deployments.
Market Restraints
- Wafer Input Concentration:Advanced lithography equipment for sub-15nm nodes depends on captive supply from a concentrated base of Japanese and Dutch equipment vendors, creating single-source vulnerability.
- Fab Capital Intensity:Greenfield 3D NAND fabrication requires multi-billion-dollar cleanroom investments with five-year depreciation schedules that compress margin recovery windows.
- Flash-DRAM Substitution:CXL-enabled memory expansion is allowing data center operators to displace capacity-optimized NAND tiers with byte-addressable alternatives in latency-sensitive tiers.
Strategic Opportunities
- Edge AI Inference:Industrial automation corridors in Mexico are generating unmet demand for ruggedized embedded flash modules with extended temperature specifications.
- IRA Clean Energy Credits:Domestic content requirements for semiconductor manufacturing equipment are creating procurement preference for fabs with certified U.S. wafer output.
- Computational Storage Convergence:Integration of in-situ processing capabilities with NAND arrays is opening white space in database acceleration and real-time analytics workloads.
Industry Challenges
- Process Engineering Talent:Shortages of 3D NAND etch and deposition specialists are extending yield ramp timelines at new Arizona and Texas fabrication facilities.
- Automotive Qualification Cycles:AEC-Q100 stress testing protocols require 18-24 month validation windows that misalign with cloud hyperscaler procurement cadences.
- Cross-Domain IP Licensing:Patent thickets spanning charge-trap cell architectures and controller firmware are complicating module vendor go-to-market strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Flash Memory Market |
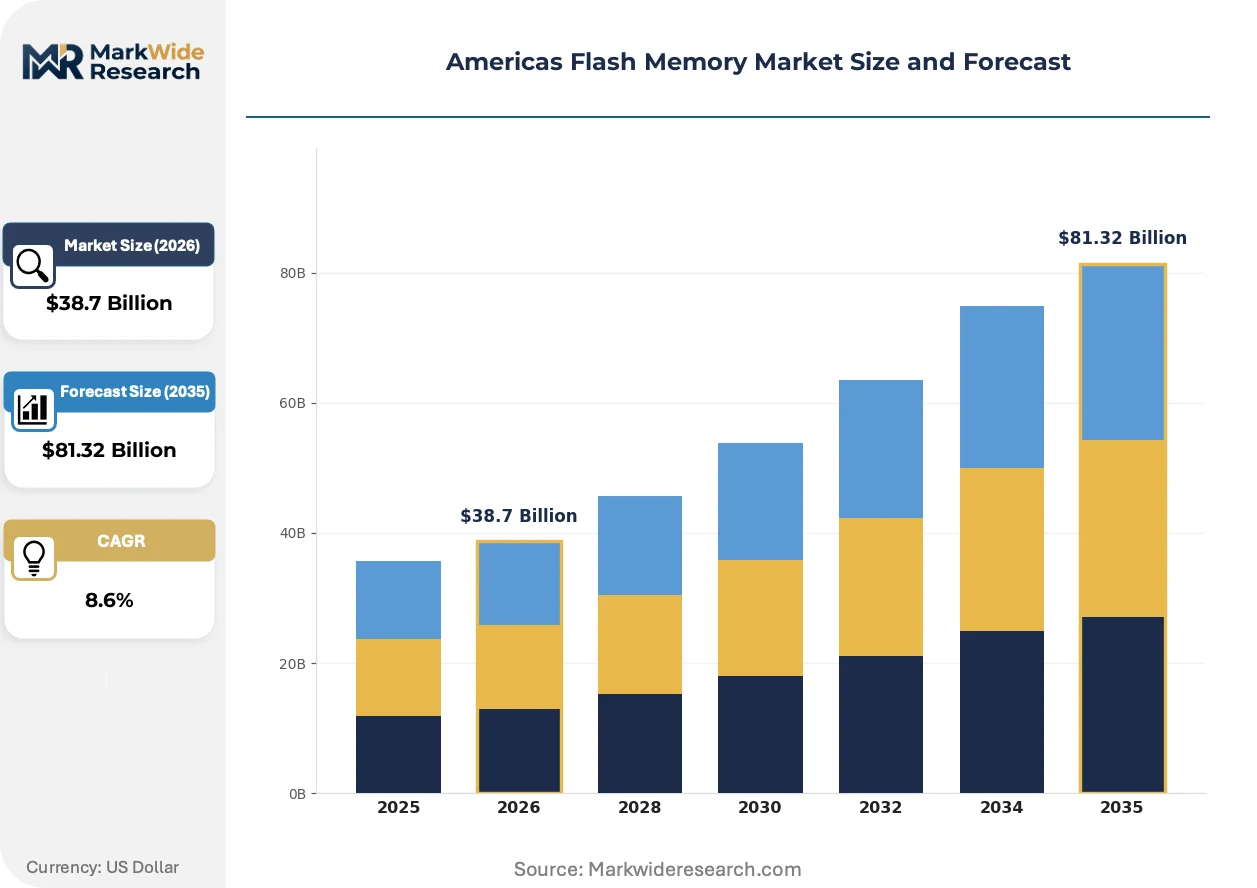
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SD Cards, USB Flash Drives, SSD, Memory Modules Application: Consumer Electronics, Automotive, Industrial, Enterprise Storage Technology: 3D NAND, 2D NAND, Flash-as-a-Service, Embedded Flash End User: Retail, OEMs, Data Centers, Telecom |
| Companies Covered | Infineon Technologies AG, Micron Technology Inc., Samsung Electronics, Kioxia Corporation, Western Digital Corporation, Intel Corporation, SK Hynix, Kingston Technology, SanDisk Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Flash Memory Market Trends and Innovations
Storage-class memory architectures are fragmenting traditional NAND segmentation boundaries as buyers prioritize workload-optimized configurations over generic capacity tiers. This evolution is compressing supplier margins while rewarding specialized integration capabilities.
QLC NAND with 1,000+ layer vertical stacking is modularizing enterprise storage procurement by allowing hyperscalers to disaggregate compute and capacity scaling independently. Cloud operators in Arizona and Texas are deploying QLC-based disaggregated storage pools for warm-tier AI training datasets. This modularity is compressing traditional array refresh cycles from five years to eighteen-month incremental expansions.
FCC equipment authorization requirements for wireless-enabled flash modules are tightening electromagnetic compatibility testing protocols for industrial IoT gateway applications. Module vendors serving North American utilities must now pre-certify integrated cellular modems before field deployment. Automotive telematics suppliers are absorbing additional six-month lead times to satisfy concurrent NHTSA cybersecurity and FCC radio compliance.
Hyperscale procurement teams are consolidating qualified supplier lists to three dominant module vendors per capacity tier, compressing second-tier manufacturer access to enterprise validation programs. This concentration is displacing distributor-led fulfillment models with direct foundry-to-OEM contracts. The shift is most visible in Texas and Arizona data center clusters where cloud operators negotiate multi-year wafer supply agreements.
Americas Flash Memory Market Segmentation
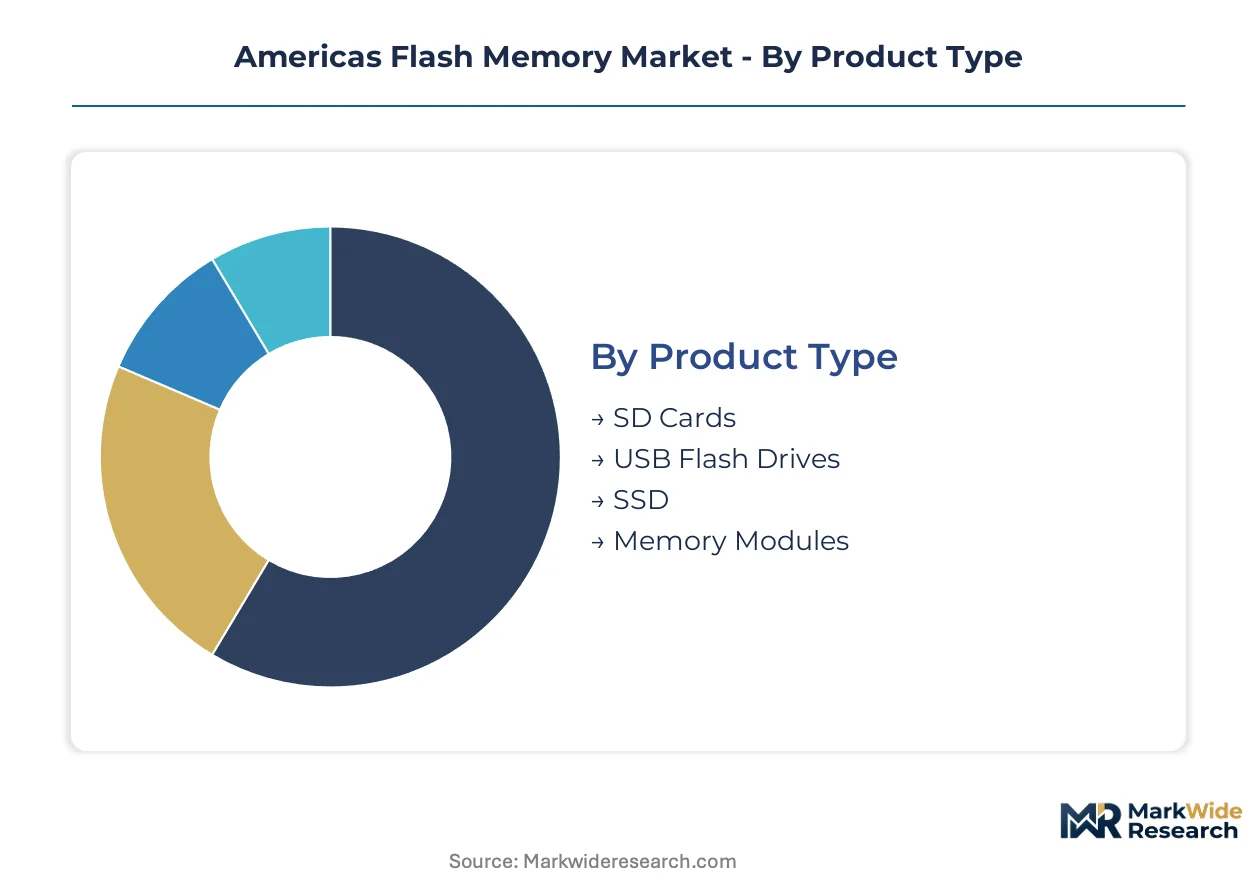
Flash memory segmentation in the Americas reveals divergent margin structures between standalone storage devices and embedded system integrations. Understanding these integration depths helps suppliers calibrate R&D allocation between high-volume consumer modules and specialized industrial qualifications.
Product Type:
Standalone storage products dominate aftermarket sales channels, while embedded flash modules penetrate deeper into system-level BOMs with longer design-in cycles.
- SSD:Solid-state drives utilizing 3D NAND architectures with PCIe and NVMe interfaces deliver enterprise-grade endurance and throughput. Cloud hyperscalers in Texas and Arizona are commissioning exabyte-scale SSD deployments for AI training infrastructure, pulling forward 200-layer NAND wafer commitments from domestic foundries.
- Memory Modules:DIMM and M.2 form-factor modules integrate NAND flash with controller firmware for server and workstation applications. Data center OEMs in the United States concentrate procurement through validated supply agreements that compress second-tier vendor access to enterprise qualification programs.
- SD Cards:Removable flash storage in standardized form factors serves consumer imaging and mobile expansion applications.
- USB Flash Drives:Portable plug-and-play storage devices rely on cost-optimized NAND controllers for file transfer and backup use cases.
SSD leads volumes today; Memory Modules is gaining share fastest through direct foundry-to-OEM contracting.
Application:
Application segmentation tracks how flash endurance specifications and operating temperature ranges align with environmental stress requirements.
- Enterprise Storage:Hyperscale data center deployments displace mechanical drives with NAND-based arrays for primary and warm-tier workloads. Cloud operators across the United States are consolidating qualified supplier lists to three dominant module vendors per capacity tier, reshaping distribution channels.
- Automotive:Embedded flash modules for ECU and telematics systems must satisfy AEC-Q100 stress testing protocols with hardware root-of-trust capabilities. NHTSA cybersecurity guidelines are mandating extended qualification windows that misalign with cloud hyperscaler procurement cadences.
- Consumer Electronics:Smartphones, tablets, and gaming devices integrate soldered-down flash packages with density-optimized layer stacking.
- Industrial:Ruggedized embedded modules with extended temperature specifications serve factory automation and utility infrastructure in Mexican manufacturing corridors.
Enterprise Storage commands margin concentration; Automotive is climbing the fastest as electrification multiplies ECU counts per vehicle platform.
Technology:
Technology segmentation distinguishes between planar legacy architectures and vertically stacked 3D implementations that dominate new capacity additions.
- 3D NAND:Vertically stacked charge-trap cell architectures with 200+ layer counts enable terabit-scale die densities. Foundry clusters in Arizona and Texas are realigning regional supply chains toward advanced 3D NAND fabrication serving North American cloud infrastructure.
- Embedded Flash:System-in-package integrations combine NAND die with MCUs for space-constrained automotive and IoT endpoints. Industrial automation corridors in Mexico are generating unmet demand for ruggedized embedded flash with extended temperature specifications.
- 2D NAND:Planar floating-gate architectures persist in cost-sensitive, low-density applications with relaxed endurance requirements.
- Flash-as-a-Service:Consumption-based storage procurement models allow enterprises to align flash capacity payments with actual utilization patterns.
3D NAND anchors wafer output today; Embedded Flash is expanding most quickly through automotive ECU integration and edge AI inference workloads.
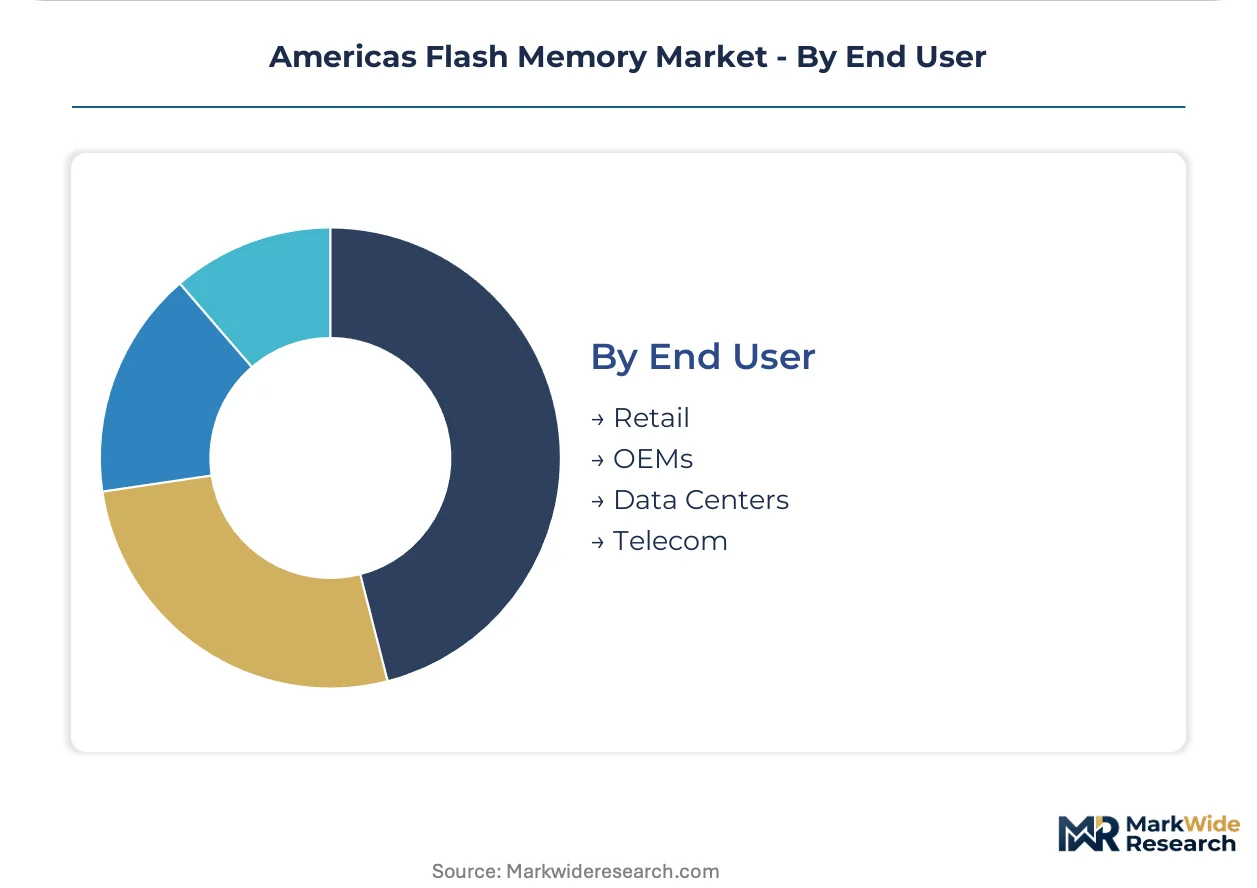
End User:
End user segmentation captures procurement pattern differences between direct OEM integration and aftermarket retail fulfillment.
- Data Centers:Hyperscale and colocation operators negotiate multi-year wafer supply agreements with foundry operators. EPA evolving e-waste guidelines are pressuring data center operators toward longer-lifecycle SSD designs that extend replacement intervals.
- OEMs:Server, automotive, and industrial equipment manufacturers qualify flash modules through 18-24 month validation windows. FCC equipment authorization requirements govern wireless-enabled flash devices in OEM system integrations.
- Telecom:Network infrastructure operators deploy flash for edge computing and content delivery caching layers.
- Retail:Consumer-facing channels distribute removable storage through distributor-led fulfillment models.
Data Centers dominate absolute consumption; OEMs is gaining share fastest as automotive and industrial design-ins accumulate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States foundry investments outpace Canadian module assembly by an order of magnitude, while Mexico's industrial corridors absorb embedded flash demand that neither northern neighbor serves directly.
United States
Cloud hyperscalers in Texas and Arizona are commissioning exabyte-scale SSD arrays for AI training workloads, pulling forward 200-layer 3D NAND wafer commitments. EPA hazardous substance rules are forcing module manufacturers toward longer-lifecycle designs that extend enterprise storage replacement intervals. Foundry clusters in Phoenix and Boise anchor domestic wafer output serving North American cloud infrastructure.
Canada
Telecom operators in Ontario and Quebec deploy edge computing infrastructure with flash-based content delivery caching layers. The country's national telecommunications regulator enforces electromagnetic compatibility standards for wireless-enabled storage modules. Toronto-Waterloo corridor startups specialize in computational storage software that integrates with imported NAND hardware.
Mexico
Industrial automation corridors in Nuevo León and Baja California generate unmet demand for ruggedized embedded flash with extended temperature specifications. Federal environmental regulations govern hazardous substance handling in electronics manufacturing zones. Guadalajara's electronics assembly cluster concentrates automotive Tier 1 module integration for export to United States vehicle plants.
Brazil
Data center operators in São Paulo and Rio de Janeiro expand colocation capacity with NAND-based storage displacing mechanical drives. ANVISA medical device regulations constrain flash integration in healthcare imaging equipment with strict electromagnetic compatibility requirements. Campinas technology park hosts regional distribution hubs for enterprise SSD imports serving South American cloud infrastructure.
Americas Flash Memory Market Competitive Landscape
United States-based producers anchor the domestic wafer fabrication tier; South Korean and Japanese specialists hold module integration and memory component positions. The vendor structure concentrates around vertically integrated foundry operators and specialized memory houses. Three archetypes dominate: captive foundry operators with in-house wafer-to-module pipelines, fabless module vendors sourcing NAND die from merchant markets, and industrial embedded specialists qualifying for automotive AEC-Q100 tiers. Capacity expansion and direct foundry-to-OEM contracting represent the dominant competitive vectors reshaping distribution channels.
Within the captive foundry tier, Micron Technology Inc. and Samsung Electronics exemplify geographic concentration strategies, with the former anchoring Boise and Phoenix fabrication complexes and the latter operating its Taylor, Texas facility. SK Hynix occupies a specialized position targeting high-bandwidth memory and enterprise SSD development for North American cloud infrastructure. These three entities represent the core competitive anchors around which module vendor qualification programs and hyperscale procurement consolidation revolve.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Micron Technology Inc. |
| Samsung Electronics |
| Kioxia Corporation |
| Western Digital Corporation |
| Intel Corporation |
| SK Hynix |
| Kingston Technology |
| SanDisk Corporation |
| Others |
Pricing and Supply Chain Analysis
Spot wafer pricing indices for 200-layer 3D NAND cascade through contract manufacturing tiers into three distinct procurement brackets serving hyperscalers, enterprise OEMs, and industrial integrators. The concentration of captive foundry output in Arizona and Texas compresses spot-market liquidity, amplifying price volatility transmission into long-term offtake negotiations. EPA hazardous substance compliance costs embed into module-level pricing through extended-lifecycle design requirements that lengthen depreciation schedules.
Pricing Analysis
Direct-to-OEM volume discounts dominate enterprise SSD procurement, displacing distributor-led fulfillment models in Texas and Arizona data center clusters. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive-qualified modules from enterprise endurance tiers and consumer-grade alternatives. Cost compression in consumer USB and SD segments is intensifying because Chinese module vendors are absorbing margin erosion to maintain volume share. Industrial automation buyers in Mexico exhibit highest price sensitivity due to peso-denominated procurement budgets, while cloud hyperscalers leverage multi-year wafer commitments for least-sensitive positioning.
Supply Chain Analysis
Regional distribution centers in Phoenix, Austin, and Guadalajara orchestrate hub-and-spoke fulfillment patterns for NAND modules across North American industrial corridors. Wafer fabrication concentrates in the United States, South Korea, and Japan, with Japanese and Dutch equipment vendors anchoring lithography supply. Raw material dependencies span silicon wafers, specialty gases for etch processes, and controller ASICs from Taiwanese foundries. Single-source vulnerability in extreme ultraviolet lithography systems creates structural risk for sub-15nm node expansion. Distribution runs through direct foundry-to-OEM contracts for enterprise tiers, while aftermarket channels persist for consumer removable storage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas Flash Memory Market functions as a stable compounder anchored by irreversible displacement of mechanical drives in enterprise storage infrastructure. Data center procurement cycles provide predictable demand baselines that smooth cyclical memory pricing volatility.
For Market Incumbents: Hedge against CXL-enabled memory substitution by accelerating computational storage firmware development for database acceleration workloads. Defensive consolidation through captive controller ASIC design protects margin capture as merchant controller vendors consolidate. Capacity addition in Boise and Phoenix reinforces supply security for hyperscaler qualification programs.
For New Entrants and Emerging Players: Industrial system integrators represent the most penetrable channel partner type for specialized embedded flash modules in Mexican automation corridors. White-space targets include ruggedized edge AI inference storage with extended temperature specifications and automotive telematics modules satisfying NHTSA cybersecurity tiers. Go-to-market execution should prioritize direct qualification with Tier 1 automotive suppliers bypassing traditional distribution.
For Investors and Strategic Acquirers: Asymmetric upside sits with fabless module vendors holding validated enterprise SSD qualifications and automotive AEC-Q100 certifications. Long-term viability centers on procurement consolidation trends that compress qualified supplier lists to three dominant vendors per tier. Watch hyperscaler capex disclosure patterns as the inflection indicator for wafer demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| 200-Layer 3D NAND Capacity Expansion | Phoenix and Boise foundry investments anchor domestic wafer supply for hyperscaler procurement. |
| Computational Storage Firmware Development | In-situ processing integration opens database acceleration workloads beyond traditional capacity tiers. |
| Automotive AEC-Q100 Certification Investment | Hardware root-of-trust capabilities satisfy NHTSA cybersecurity mandates for connected vehicle ECUs. |
| Direct Foundry-to-OEM Contracting | Multi-year wafer supply agreements displace distributor-led fulfillment in enterprise SSD channels. |
| Extended Temperature Industrial Module Qualification | Ruggedized specifications capture unmet demand in Mexican automation corridors for edge AI inference. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply estimates for the Americas Flash Memory Market. Primary fieldwork engaged foundry operations executives, data center procurement officers at hyperscalers, automotive Tier 1 supplier engineering directors, and industrial automation system integrators in Mexico. Secondary validation drew from SEC 10-K filings of memory manufacturers, EPA hazardous substance rulemaking dockets, FCC equipment authorization databases, and hyperscaler capex disclosure statements. Bottom-up module shipment estimates triangulated against top-down wafer capacity allocations across the analysis window.
Segment-weighting approaches distributed total market value across product type, application, technology, and end-user dimensions with regional coefficients for United States, Canada, Mexico, and Brazil. The modeling framework applied growth rate derivation from historical shipment trajectories, foundry capacity expansion announcements, and procurement pattern shifts in cloud infrastructure. Forecast inputs incorporated AI training workload storage density requirements, automotive ECU proliferation per electrified vehicle platform, and IRA domestic content thresholds for semiconductor manufacturing equipment.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CXL memory technology substitution rates, BIS export control refinements affecting equipment sourcing, and automotive qualification cycle compressions. Outputs reflect documented assumptions about foundry yield ramp timelines and hyperscaler procurement consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Recordable Optical Disc Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Enterprise Flash Storage Market
Data Storage
Digital Recording System Market
Data Storage
Storage Class Memory Market
Data Storage
Ireland Data Center Storage Market
Data Storage
Hardware Storage Market
Data Storage
Global Digital Storage Devices Market
Data Storage
Flash-Based Array Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
Australia Data Center Storage Market
Data Storage
External Storage Market
Data Storage
Transparent Caching Market
Data Storage
Tape Storage Market