
 Middle East and Africa SSD Caching Market | 2026-2036
Middle East and Africa SSD Caching Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa SSD Caching Market Foresight
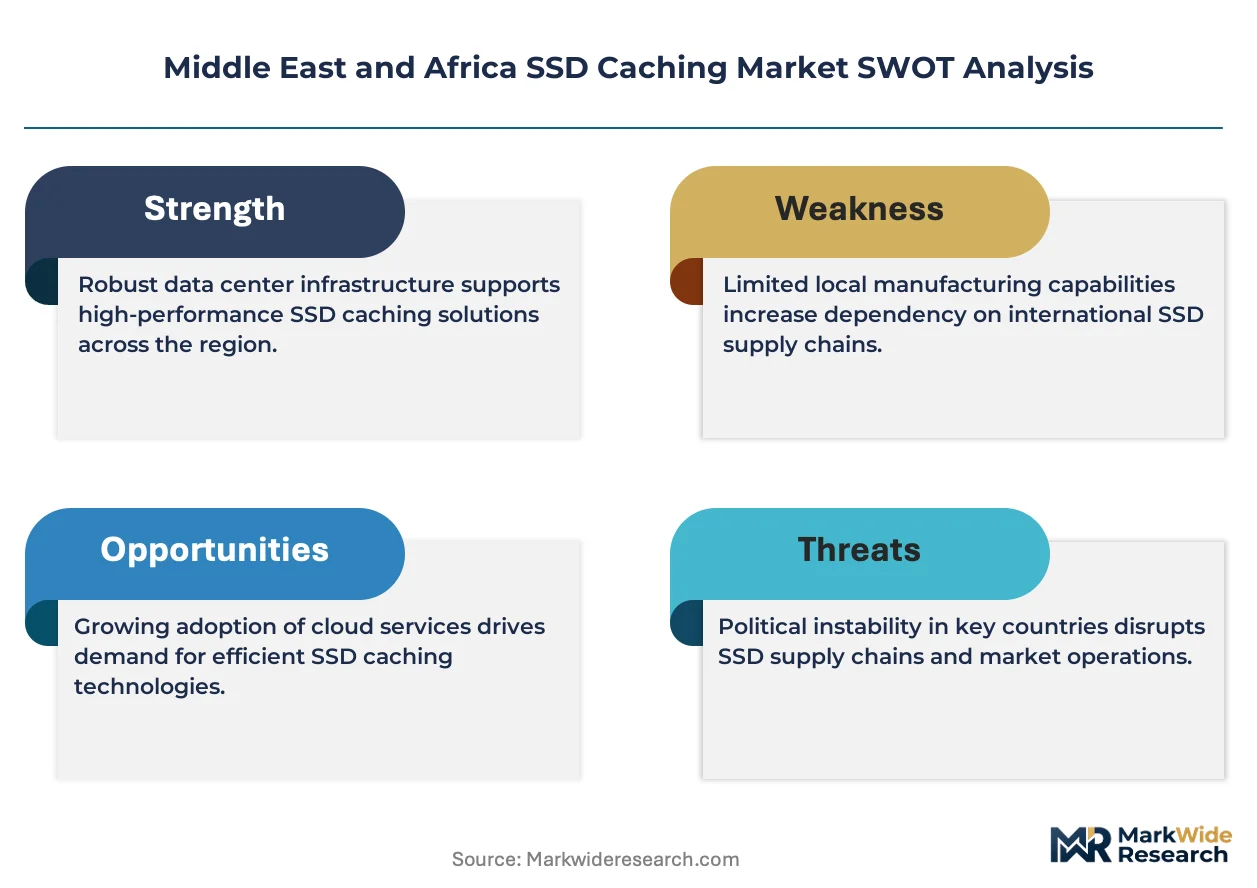
Modular appliance bundling is recalibrating procurement patterns across enterprise buyers in the Middle East and Africa SSD Caching Market. Intel Corporation leverages its vertically integrated NAND and controller silicon to sustain pricing power in PCIe-based configurations. Samsung Electronics Co Ltd anchors regional supply through its dedicated distributor networks serving Gulf data center operators. Micron Technology Inc differentiates on high-endurance enterprise-grade modules designed for sustained write-intensive workloads in African mining and logistics IT environments.
SSD caching employs high-speed solid-state storage as an intermediary buffer between DRAM and mechanical hard drives, typically using NAND flash with sub-millisecond latency to accelerate read-heavy workloads and reduce storage-area network congestion. The technology serves commercial purposes by collapsing I/O bottlenecks in virtualized database environments, transactional systems, and real-time analytics clusters where spinning disk latency degrades application performance. PCIe SSDs command premium positioning in Gulf financial services deployments where NVMe protocol throughput supports high-frequency trading platforms and regulatory reporting databases. Hybrid deployment architectures spanning on-premises flash tiers with cloud burst capacity are expanding fastest among South African retail chains modernizing point-of-sale and inventory systems. SATA SSDs retain volume relevance in cost-sensitive East African healthcare digitization programs where USB and SAS interconnects suffice for picture archiving and communication systems.
Saudi Arabia's Communications and Information Technology Commission enforces data sovereignty certification for storage appliances processing citizen records, compelling vendors to localize firmware validation and support operations. South Africa's Protection of Personal Information Act mandates encryption-at-rest standards that filter SSD caching procurement specifications across healthcare and retail verticals. The UAE's National Electronic Security Authority publishes critical infrastructure cybersecurity frameworks influencing flash storage hardening requirements for telecommunications and energy operators. Stakeholders must monitor evolving Gulf data residency decrees and PoPIA enforcement timelines to align product roadmaps with compliance-driven refresh cycles.
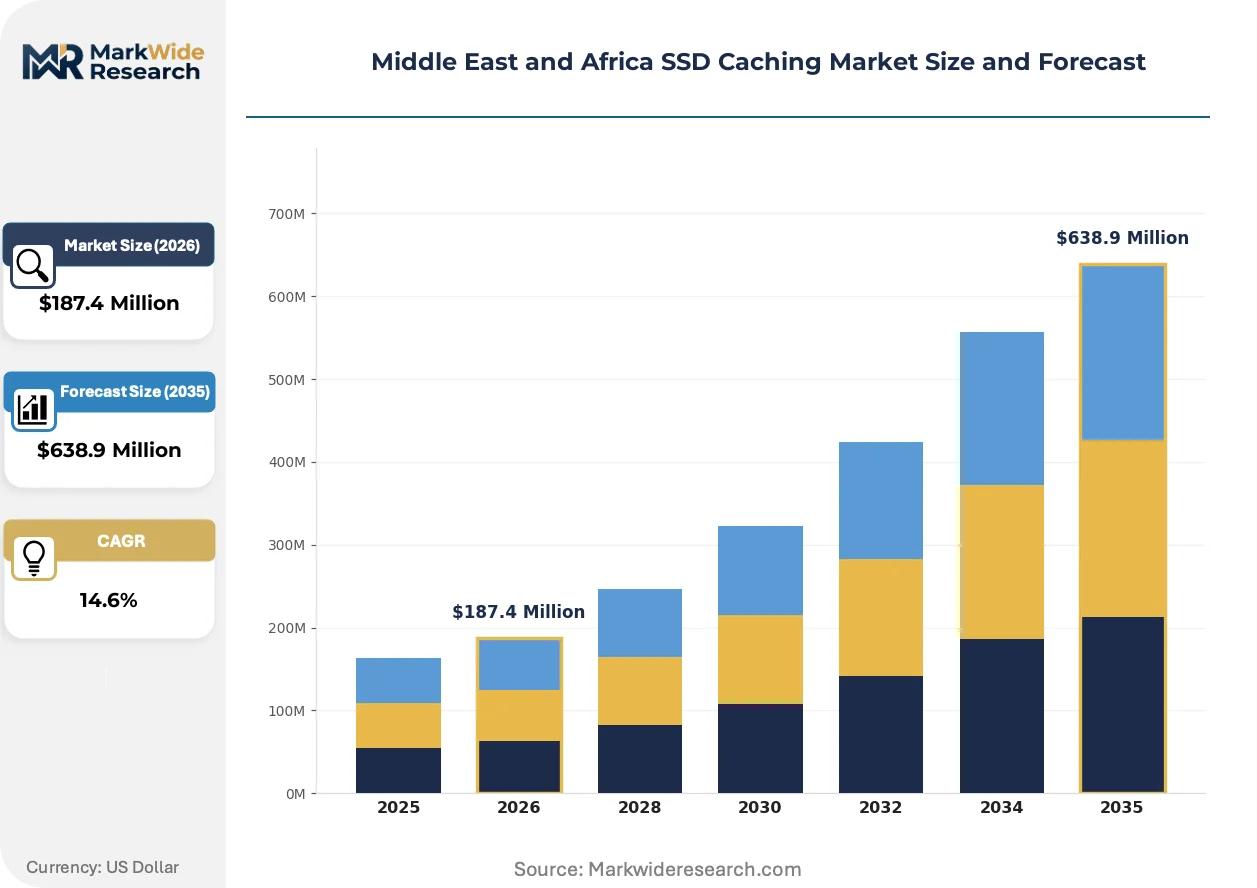
Market Dynamics
PCIe NVMe protocol adoption is compressing refresh cycles across Gulf financial services and telecommunications infrastructure, as sub-millisecond latency requirements displace SAS-based caching tiers in high-frequency trading and real-time regulatory reporting environments.
Growth Catalysts
- Edge Computing Workloads:Gulf telecommunications operators are deploying flash-based caching at distributed points of presence to support low-latency 5G services and IoT data aggregation.
- POPIA Compliance Mandates:South Africa's Protection of Personal Information Act is compelling healthcare and retail enterprises to retain sensitive data on-premises with encrypted-at-rest SSD tiers.
- Dubai Smart City Initiatives:Municipal digitization programs across the United Arab Emirates are driving enterprise storage upgrades in government and transportation verticals.
Market Restraints
- NAND Flash Supply Concentration:Regional dependence on Asian controller and memory chip suppliers exposes procurement to geopolitical logistics disruptions and allocation constraints.
- Data Sovereignty Certification Costs:Saudi Arabia's Communications and Information Technology Commission mandates localized firmware validation, adding operational overhead for non-domestic vendors.
- Mechanical Disk Substitution Inertia:Cost-sensitive East African healthcare and education sectors continue prioritizing SATA HDD arrays over flash caching for non-critical workloads.
Strategic Opportunities
- Nigerian Fintech Expansion:Lagos-based payment processors and digital banks represent underpenetrated demand for low-latency transactional caching infrastructure.
- Hybrid Cloud Burst Architectures:South African retail chains are integrating on-premises flash tiers with cloud elasticity for seasonal inventory and point-of-sale spikes.
- UAE Critical Infrastructure Hardening:National Electronic Security Authority cybersecurity frameworks are mandating encrypted caching for energy and telecommunications operators.
Industry Challenges
- NVMe Fabric Expertise Scarcity:Gulf data center operators face recruitment gaps for storage architects capable of designing RDMA-over-Converged-Ethernet caching clusters.
- Legacy SAN Integration Complexity:South African mining and logistics enterprises encounter friction bridging Fibre Channel storage area networks with modern NVMe-oF caching layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa SSD Caching Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Drives, Flash Drives, PCIe SSDs, SATA SSDs End User: Telecommunications, Automotive, Healthcare, Retail Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized Technology: NVMe, SAS, USB, SATA |
| Companies Covered | Intel Corporation, Samsung Electronics Co Ltd, Micron Technology Inc, Western Digital Corporation, QNAP Systems Inc, NetApp Inc, Kioxia, SK Hynix Inc, Seagate Technology LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa SSD Caching Market Shifts & Advancements
Intelligent caching algorithms and software-defined storage orchestration are displacing hardware-centric deployment models across Middle East and Africa enterprise infrastructure.
Computational storage drives with in-situ processing capabilities are automating data reduction and encryption operations at the device level. Saudi financial services institutions are piloting these architectures for regulatory analytics workloads. This compression of host CPU overhead is automating compliance reporting pipelines while reducing data movement across network fabrics.
The UAE's National Electronic Security Authority has issued mandatory encryption-at-rest specifications for critical infrastructure storage appliances. These frameworks are filtering procurement specifications toward FIPS-validated caching modules with hardware root-of-trust. Telecommunications and energy operators in Abu Dhabi and Dubai are accelerating refresh cycles to meet certification deadlines.
Enterprise buyers across the Gulf are consolidating vendor relationships through managed infrastructure contracts that bundle hardware, firmware maintenance, and compliance monitoring. Systems integrators are displacing direct procurement channels for mid-market healthcare and retail deployments. South African hospital groups and retail chains represent the most visible adoption of this consolidated sourcing model.
Middle East and Africa SSD Caching Market Segmentation
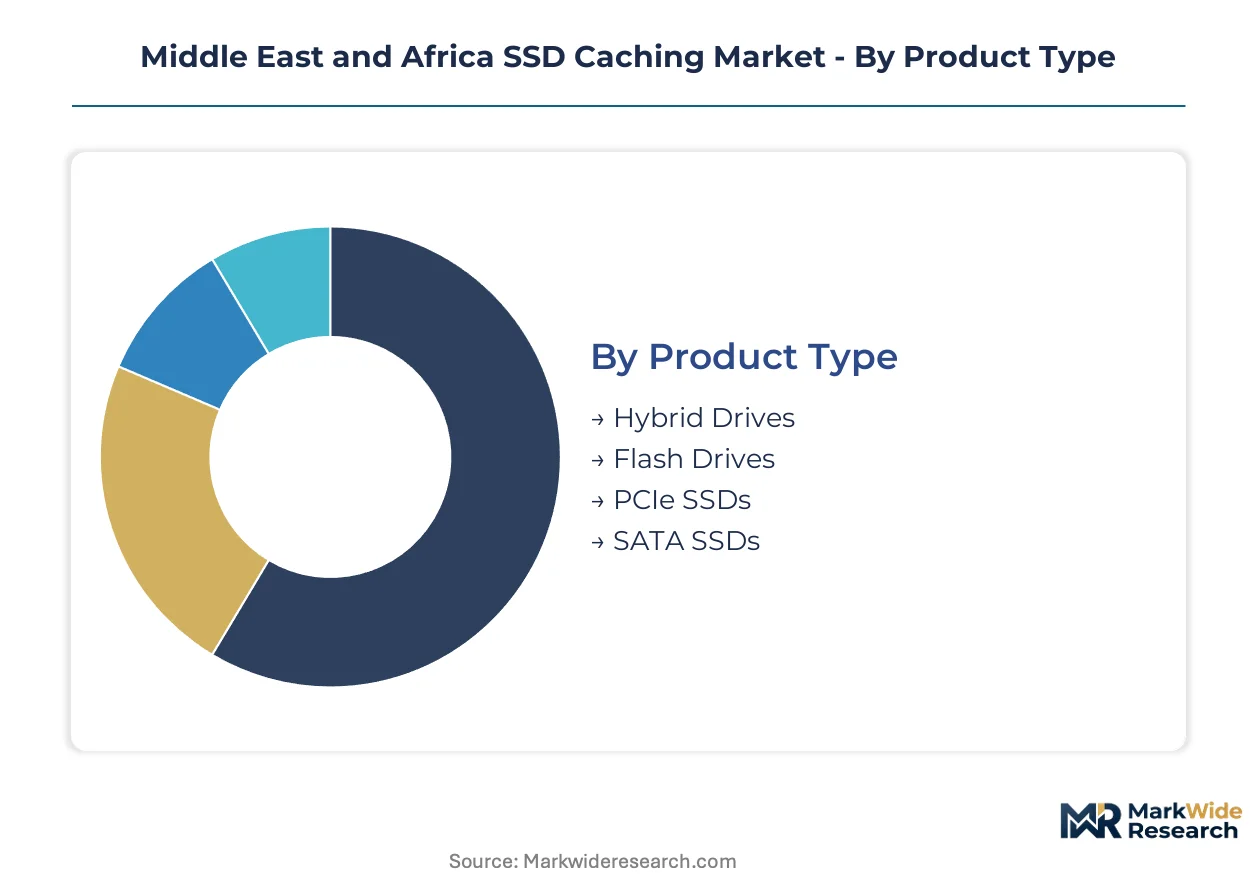
SSD caching procurement across the Middle East and Africa fragments across performance tiers, regulatory environments, and infrastructure maturity levels. Certification requirements from Saudi Arabia's Communications and Information Technology Commission and South Africa's Protection of Personal Information Act reshape segment prioritization for enterprise buyers.
Product Type:
Saudi Arabia's data sovereignty certification mandates localized firmware validation, creating divergent compliance burdens across flash storage form factors. PCIe SSDs and NVMe-based configurations face heightened scrutiny for critical infrastructure deployments.
- PCIe SSDs:NVMe protocol devices deliver sub-millisecond latency through direct CPU interconnects. Abu Dhabi's financial services digitization and Dubai's high-frequency trading platforms concentrate demand for these premium configurations. The UAE's National Electronic Security Authority encryption mandates filter procurement toward FIPS-validated modules.
- SATA SSDs:Legacy interconnect technology retains cost advantages for read-intensive caching workloads. East African healthcare digitization programs in Kenya and Ethiopia prioritize these units for picture archiving systems where USB and SAS bandwidth suffice. Mechanical disk substitution inertia constrains upgrade velocity in education and rural clinic deployments.
- Hybrid Drives:Integrated flash-HDD configurations bridge budget constraints in South African retail modernization.
- Flash Drives:Compact NAND-based units serve edge computing points of presence for Gulf telecommunications operators.
Leading the category by volume: SATA SSDs. Growing fastest: PCIe SSDs.
End User:
Vertical-specific latency requirements and data residency obligations segment demand across regulated industries. Telecommunications and financial services drive premium tier procurement; healthcare and retail navigate cost-performance trade-offs under POPIA compliance timelines.
- Telecommunications:5G edge infrastructure and IoT data aggregation demand flash caching at distributed points of presence. Gulf Cooperation Council operators deploy NVMe tiers to collapse latency for real-time subscriber analytics. Saudi Arabia's CITC sovereignty requirements compel localized appliance validation.
- Healthcare:South Africa's POPIA encryption-at-rest mandates reshape storage procurement for hospital groups and diagnostic chains. On-premises flash tiers retain patient imaging and electronic records under data localization requirements. Nigerian and Kenyan clinic networks face capital constraints favoring SATA-based hybrid architectures.
- Automotive:Connected vehicle data pipelines and autonomous testing fleets in Dubai and Riyadh generate edge caching demand.
- Retail:South African chains integrate flash tiers with cloud burst capacity for seasonal inventory spikes.
Telecommunications captures the largest share of premium-tier spending. Healthcare exhibits the steepest compliance-driven refresh trajectory.
Deployment:
Infrastructure architecture choices reflect data gravity patterns and regulatory jurisdiction boundaries. Sovereignty mandates in Saudi Arabia and South Africa privilege on-premises control; cloud elasticity attracts hybrid configurations where latency permits.
- On-Premises:Dedicated flash tiers satisfy Saudi CITC certification and South African POPIA encryption mandates for citizen records and patient data. Abu Dhabi energy operators and Dubai government entities deploy these configurations under critical infrastructure hardening requirements. Firmware localization overhead elevates total cost of ownership for non-domestic vendors.
- Hybrid:Flash-to-cloud burst architectures gain traction among South African retail chains modernizing point-of-sale and inventory systems. Seasonal demand spikes leverage cloud elasticity while core transactional data remains on encrypted local tiers. Network latency to European and Asian cloud regions constrains workload placement.
- Cloud-Based:Pure cloud caching serves non-sensitive analytics workloads where data residency permits.
- Virtualized:Software-defined storage pools abstract physical flash resources across enterprise data centers.
On-premises deployments dominate regulated vertical spending. Hybrid architectures are climbing fastest among commercial enterprises.
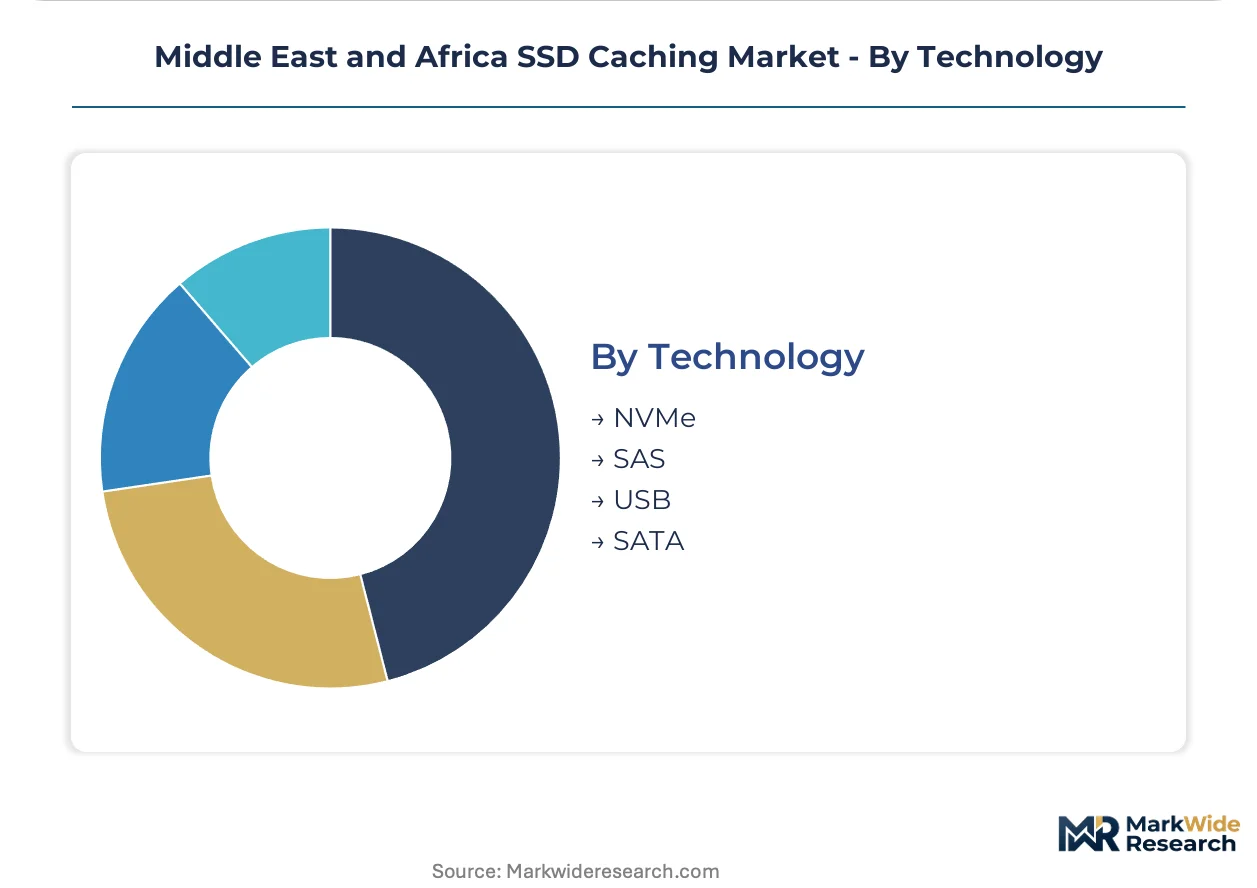
Technology:
Protocol selection determines throughput ceilings and integration complexity with legacy storage area networks. NVMe displaces SAS in performance-sensitive deployments; SATA and USB retain relevance where interconnect bandwidth is not constraining.
- NVMe:PCIe-based protocol delivers parallel queue depth and reduced command latency for high-frequency trading and real-time regulatory reporting. Dubai financial services and Abu Dhabi sovereign wealth operations mandate these configurations. NVMe-oF expertise scarcity across Gulf data centers impedes fabric-scale deployments.
- SAS:Serial-attached SCSI persists in South African mining and logistics enterprises with Fibre Channel storage area network heritage. Legacy SAN integration complexity creates friction bridging to modern caching layers. Gradual displacement by NVMe protocols compresses refresh cycles in competitive sectors.
- SATA:Cost-optimized interconnect for East African healthcare and education digitization programs.
- USB:Peripheral connectivity for portable and edge caching appliances in distributed deployments.
NVMe leads technology spending growth. SAS retains installed base volume in industrial legacy environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East and Africa SSD Caching Market concentrates demand within Gulf Cooperation Council special economic zones and South African industrial corridors, where data sovereignty mandates and smart city investments create differentiated procurement environments across national boundaries.
United Arab Emirates
Dubai's smart city infrastructure and Abu Dhabi's financial services digitization anchor regional demand for low-latency flash storage. The National Electronic Security Authority mandates FIPS-validated encryption modules for critical infrastructure operators. Dubai Internet City and Abu Dhabi Global Market host concentrated deployments among telecommunications and sovereign wealth entities.
Saudi Arabia
Riyadh's fintech expansion and NEOM's cognitive city infrastructure generate sustained enterprise storage procurement. The Communications and Information Technology Commission enforces data sovereignty certification requiring localized firmware validation. Eastern Province energy operators and Riyadh-based financial institutions drive premium-tier NVMe adoption under regulatory deadlines.
South Africa
Johannesburg's retail modernization and Cape Town's healthcare digitization sustain hybrid cloud caching architectures. The Protection of Personal Information Act mandates encryption-at-rest standards filtering procurement specifications. Mining and logistics enterprises in Gauteng encounter legacy SAN integration complexity when bridging Fibre Channel networks with modern flash tiers.
Nigeria
Lagos-based payment processors and digital banking platforms represent underpenetrated demand for transactional caching infrastructure. The country's national data protection regulator is developing localization frameworks influencing enterprise storage decisions. Victoria Island and Ikoyi financial districts concentrate fintech infrastructure investment requiring low-latency database acceleration.
Kenya
Nairobi's healthcare digitization programs and M-Pesa mobile payment ecosystem sustain cost-optimized SATA SSD deployments. National information and communications technology policy prioritizes domestic data hosting for public sector records. East African logistics corridors connecting Mombasa port to regional markets generate edge caching requirements for supply chain visibility systems.
Middle East and Africa SSD Caching Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Middle East and Africa SSD Caching Market, creating a tiered structure where vertically integrated memory manufacturers hold pricing power in premium segments while systems integrators capture mid-market service bundling opportunities. Market concentration reflects NAND flash supply chain geography, with Asian-headquartered memory fabricators dominating controller and module supply. Three archetypes define competitive positioning: captive silicon producers with in-house NAND and controller production, branded systems vendors bundling hardware with compliance monitoring services, and regional distributors anchoring local support networks. Dominant competitive moves include managed infrastructure contract consolidation and firmware localization partnerships to satisfy Saudi and South African certification requirements.
Within the silicon-integrated tier, Intel Corporation and Samsung Electronics Co Ltd occupy positions reflecting vertically integrated controller and memory chip capabilities, while Micron Technology Inc exemplifies high-endurance module specialization for write-intensive industrial workloads. These entities anchor supply relationships with Gulf data center operators and African mining IT environments through dedicated regional distributor networks. Western Digital Corporation and Kioxia sit within the branded storage systems archetype, serving enterprise buyers seeking consolidated hardware and firmware maintenance contracts. Systems integrators across Dubai and Johannesburg increasingly intermediate procurement for mid-market healthcare and retail deployments, displacing direct vendor channels.
| Leading Market Players |
|---|
| Intel Corporation |
| Samsung Electronics Co Ltd |
| Micron Technology Inc |
| Western Digital Corporation |
| QNAP Systems Inc |
| NetApp Inc |
| Kioxia |
| SK Hynix Inc |
| Seagate Technology LLC |
| Others |
Supply & Pricing Matrix
Gulf data center operators and South African hospital procurement committees concentrate demand for flash storage, anchoring a contract-based pricing model where long-term offtake agreements dominate premium-tier NVMe procurement while spot-market transactions serve cost-optimized SATA deployments.
Pricing Analysis
Short lead-time premiums command substantial markups in Saudi Arabia's CITC-certified appliance segment, where localized firmware validation extends procurement cycles. Three-tier pricing structure across FIPS-validated premium, enterprise-standard, and economy SATA tiers separates compliance-grade modules from basic healthcare digitization units. Cost compression in the SATA segment is intensifying because East African clinic networks prioritize mechanical disk substitution over flash upgrades. Healthcare procurement committees exhibit the highest price sensitivity, while Abu Dhabi sovereign wealth funds accept premium positioning for sub-millisecond latency guarantees.
Supply Chain Analysis
Saudi Arabia's domestic-content mandates for firmware validation and South Africa's POPIA encryption-at-rest requirements are reshaping sourcing toward regional assembly partnerships. NAND flash fabrication concentrates in South Korea, Taiwan, and Japan, with controller silicon production anchored in the same geographies. Regional procurement draws from NAND wafers, PCIe controllers, and DRAM buffers, exposing distributors to single-source vulnerability when Asian allocation constraints tighten. Distribution runs through Dubai-based systems integrators and Johannesburg channel partners serving mid-market healthcare and retail verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa SSD Caching Market functions as a vertical-integration race where captive NAND supply and in-house controller design determine pricing power across Gulf financial services deployments.
For Market Incumbents: Extend firmware localization partnerships to satisfy Saudi CITC certification timelines and South African POPIA encryption mandates. Deepen backward integration into NAND supply to defend margin position against Asian memory fabricators expanding direct regional sales. Prioritize managed infrastructure contract consolidation to displace systems integrators in mid-market healthcare procurement.
For New Entrants and Emerging Players: Computational storage drives with in-situ processing capabilities offer a technology-first wedge into Saudi regulatory analytics workloads. Nigerian fintech payment processors in Lagos represent the most penetrable geography, with Victoria Island infrastructure investment outpacing established vendor coverage. Pursue channel partnerships with Dubai Internet City colocation operators to bypass direct enterprise sales cycles.
For Investors and Strategic Acquirers: The window for entry favors regional systems integrators with compliance monitoring capabilities and established CITC validation relationships. Long-term viability hinges on firmware localization assets rather than hardware distribution scale. Watch Saudi NEOM cognitive city infrastructure tenders as the inflection indicator for premium-tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Localization Partnership | Satisfies Saudi CITC data sovereignty mandates for citizen record processing appliances. |
| NVMe-oF Fabric Expertise Development | Addresses Gulf data center operator recruitment gaps for RDMA-over-Converged-Ethernet clusters. |
| Hybrid Cloud Burst Integration | Captures South African retail chain demand for seasonal inventory elasticity. |
| Computational Storage Pilot Programs | Automates regulatory analytics pipelines for Saudi financial services institutions. |
| Managed Infrastructure Contract Consolidation | Displaces direct procurement channels in Johannesburg hospital group flash tier deployments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across data center procurement officers, storage architects, healthcare IT directors, and systems integrator account managers. Saudi CITC certification databases, South African POPIA compliance registries, UAE National Electronic Security Authority frameworks, and Gulf Cooperation Council telecommunications capex disclosures supplied validation benchmarks. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment flows across the analysis window.
Granularity-level modeling deployed product-type splits across PCIe, SATA, and NVMe protocol tiers, end-user segmentation for telecommunications, healthcare, and financial services verticals, and deployment architecture distinctions between on-premises, hybrid, and cloud-based configurations. CAGRs derived from fitted growth curves incorporating edge computing workload expansion rates, regulatory deadline impacts, and mechanical disk substitution elasticity. NAND flash supply allocation constraints and sovereign certification timeline assumptions shaped regional trajectory divergence.
Several conditions sit outside the modeled scope, including geopolitical logistics disruptions affecting Asian controller supply, unannounced data residency decree revisions, and hyperscaler cloud caching service launches targeting African markets. Forecasts reflect documented assumptions regarding CITC enforcement consistency and POPIA compliance interpretation stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Storage Class Memory Market
Data Storage
Zoned Flash Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Universal Flash Storage Market
Data Storage
Wi-Fi SD Cards Market
Data Storage
Data Storage Devices Market
Data Storage
OTG Pen Drive Market
Data Storage
Ethernet Storage Market
Data Storage
Enterprise Flash Storage Market
Data Storage
Europe Flash Memory Market
Data Storage
Middle East and Africa Data Storage Market
Data Storage
Digital Recording System Market
Data Storage
Data Center Storage Solutions Market
Data Storage
Tape Storage Market
Data Storage
Storage Area Network Market