
 United States Chemical Sensors Market | 2026-2036
United States Chemical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
United States Chemical Sensors Market Analytics
Market Context
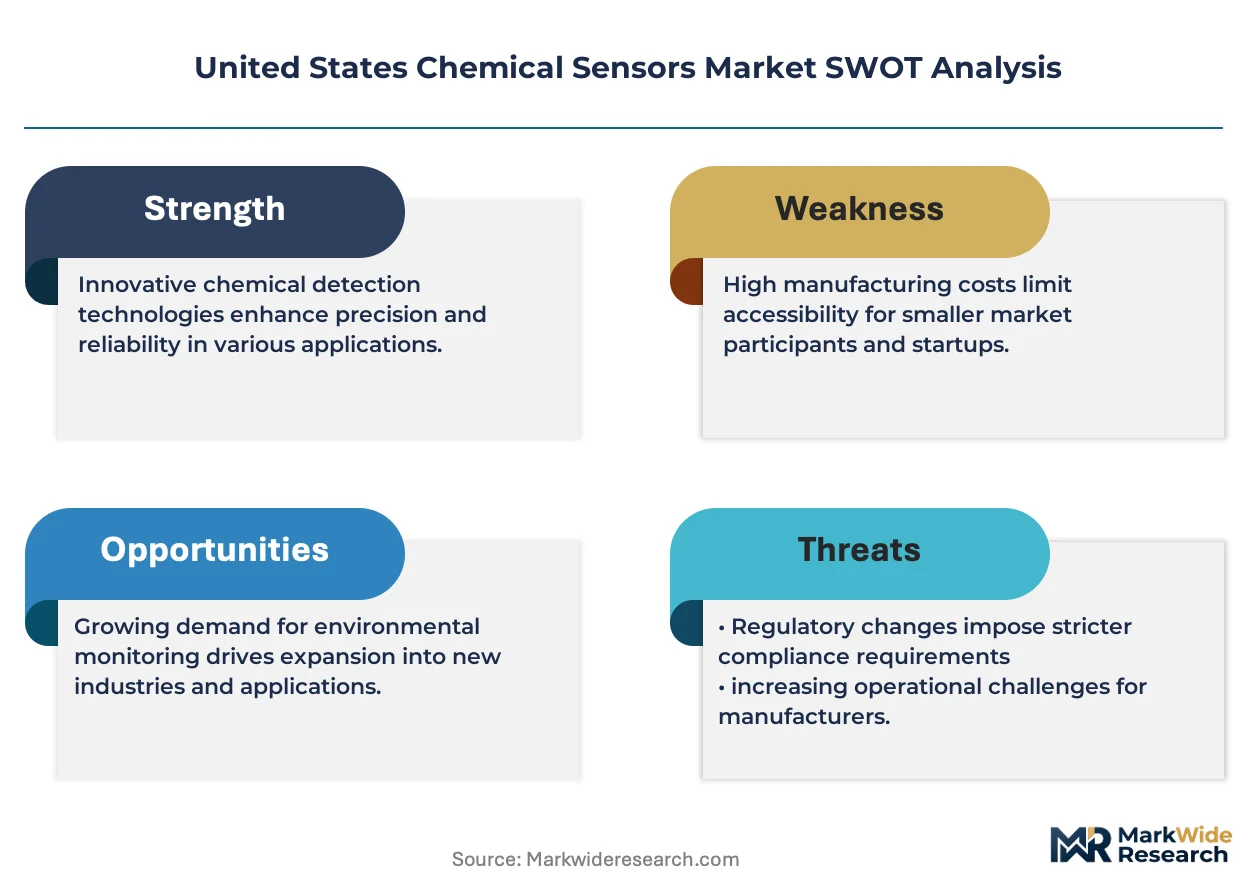
OSHA's updated permissible exposure limits for industrial chemicals is consolidating the competitive landscape around vendors with certified calibration infrastructure and service networks. Honeywell International Inc. leverages its distributed field-service footprint to lock in multi-year maintenance contracts with refinery operators. Emerson Electric Co. competes through embedded sensor-to-control-system architectures that reduce integration costs for process manufacturers. Thermo Fisher Scientific Inc. specializes in laboratory-grade reference standards that anchor regulatory compliance workflows for environmental consultants.
Technical Definition and Segment Structure
Chemical sensors are transducer-based devices that detect and quantify specific analyte concentrations through electrochemical, optical, or semiconductor mechanisms, typically achieving detection thresholds in parts-per-million or parts-per-billion ranges for gases, liquids, and volatile organic compounds. Their primary purpose spans industrial safety monitoring, emissions compliance verification, and real-time process optimization across hazardous material handling operations. Electrochemical sensors dominate unit volume in safety monitoring applications due to mature manufacturing economics and established replacement protocols, while optical segments capture premium positioning in emission detection where selectivity requirements are stringent. Semiconductor-based architectures are displacing legacy configurations in automotive cabin-air and battery-ventilation systems, driven by miniaturization trends and solid-state reliability improvements.
Regulatory Framework
EPA enforcement of Clean Air Act amendments and OSHA process safety management standards directly shape sensor procurement specifications, calibration frequencies, and data-logging requirements for covered facilities. FDA oversight of medical-grade gas delivery systems and NHTSA cabin-air quality guidelines for electric vehicle battery compartments create parallel compliance pathways that fragment vendor certification burdens. Stakeholders must monitor how overlapping federal mandates interact with state-level air district rules in California and Texas, as divergence in enforcement intensity creates arbitrage opportunities for regionally specialized service providers.
Market Dynamics
OSHA's updated permissible exposure limits for industrial chemicals are compressing replacement cycles and forcing facility operators to retire legacy detection hardware ahead of depreciation schedules.
Growth Catalysts
- EPA ambient air quality tightening:Lower detection thresholds mandated under Clean Air Act amendments are compelling petrochemical clusters across Texas and Louisiana to deploy next-generation fixed-site networks.
- Semiconductor fab expansion:Process gas monitoring requirements in Arizona and Oregon fabs are accelerating sensor procurement for bulk specialty gas distribution systems.
- Electric vehicle battery ventilation:NHTSA cabin-air guidelines for lithium-ion thermal runaway detection are creating embedded sensor demand across Michigan and Ohio assembly plants.
Market Restraints
- Precious metal input volatility:Platinum and palladium price swings in electrochemical sensor electrodes compress margin stability for safety monitoring OEMs.
- Calibration infrastructure concentration:Certified reference gas supply chains cluster in Gulf Coast industrial corridors, creating geographic vulnerability for Midwest environmental agencies.
- Optical sensor cost premiums:Selective detection for volatile organic compounds requires tunable diode laser architectures that price out smaller municipal air districts.
Strategic Opportunities
- Appalachian shale basin monitoring:Underpenetrated upstream oil and gas operations in Pennsylvania and West Virginia lack continuous emissions surveillance infrastructure.
- Carbon capture verification:Emerging 45Q tax credit eligibility rules are creating demand for CO2 leak detection at Illinois and North Dakota sequestration sites.
- Wireless mesh convergence:Integration of low-power wide-area networks with solid-state chemiresistors enables retrofit deployments without conduit installation.
Industry Challenges
- Cross-trained technician scarcity:Field service roles requiring both electrochemical calibration expertise and IT networking skills face recruitment gaps in rural monitoring stations.
- Multi-agency compliance timelines:Facilities must synchronize EPA reporting protocols with OSHA process safety management audits, creating documentation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Chemical Sensors Market |
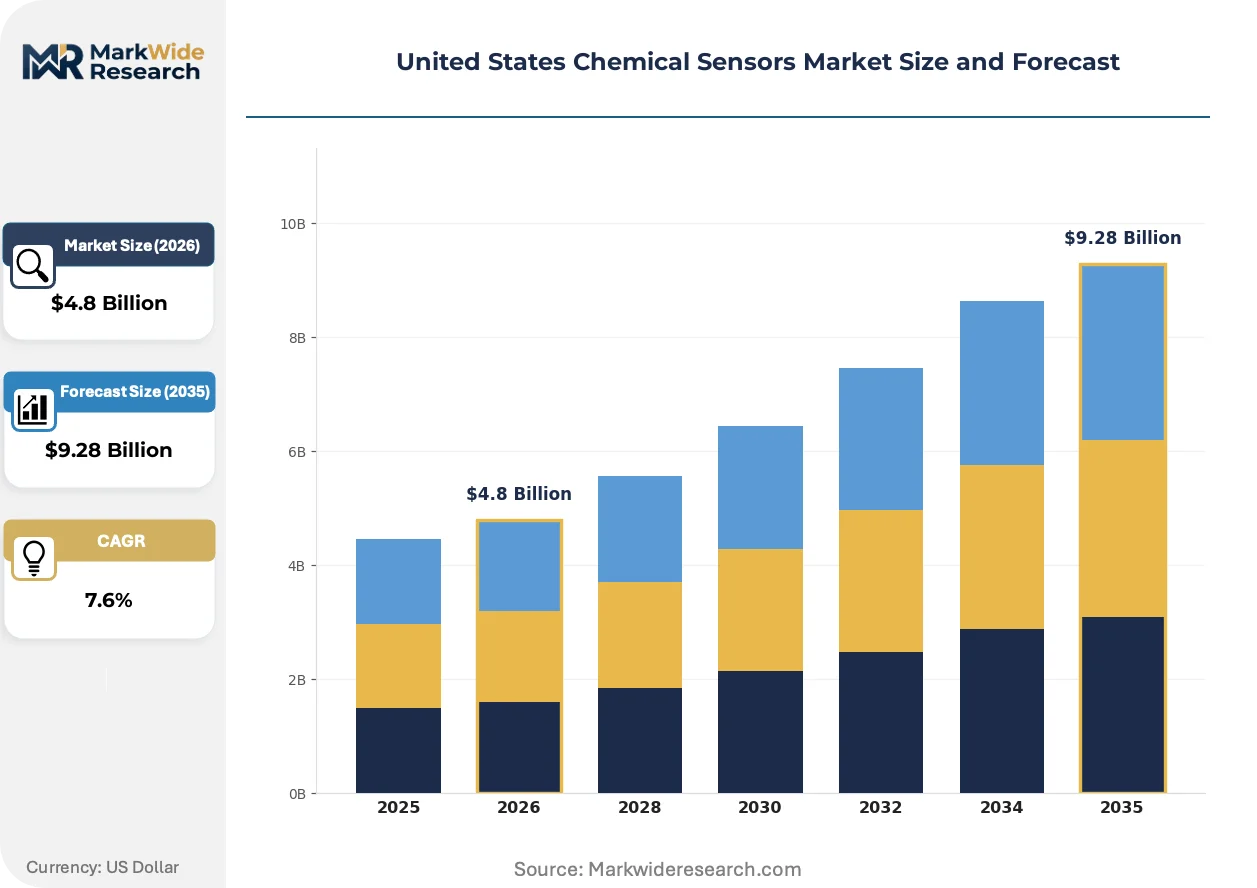
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical, Optical, Semiconductor, Infrared End User: Healthcare, Environmental Monitoring, Food Industry, Automotive Technology: Biochemical, Amperometric, Conductometric, Potentiometric Application: Safety Monitoring, Quality Control, Process Control, Emission Detection |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., Thermo Fisher Scientific Inc., ABB Ltd., Siemens AG, General Electric Co., MSA Safety Incorporated, Teledyne Technologies Incorporated, Amphenol Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Chemical Sensors Market Evolving Landscape
Digital integration and solid-state architectures are compressing the traditional divide between laboratory-grade reference instruments and field-deployable safety monitors.
Photonic integrated circuits are decentralizing optical detection capabilities previously confined to centralized analytical laboratories. Midstream gas processors in Oklahoma and Kansas are adopting chip-scale spectrometers for real-time pipeline composition analysis. This diffusion is compressing the price-performance gap between electrochemical and optical modalities.
EPA's enforcement prioritization under the revised National Ambient Air Quality Standards is mandating continuous monitoring for previously exempt smaller sources. Refinery operators in the Houston Ship Channel are deploying fenceline sensor arrays to demonstrate compliance with benzene action levels. California's South Coast Air Quality Management District is requiring parallel data validation protocols that exceed federal minimums.
Refinery procurement departments are unbundling sensor hardware from multi-year maintenance contracts that previously locked in vendor relationships. Texas and Louisiana operators are soliciting separate bids for equipment, calibration gas supply, and field service. This disaggregation is exposing price transparency gaps and compressing incumbent service margins.
United States Chemical Sensors Market Segmentation
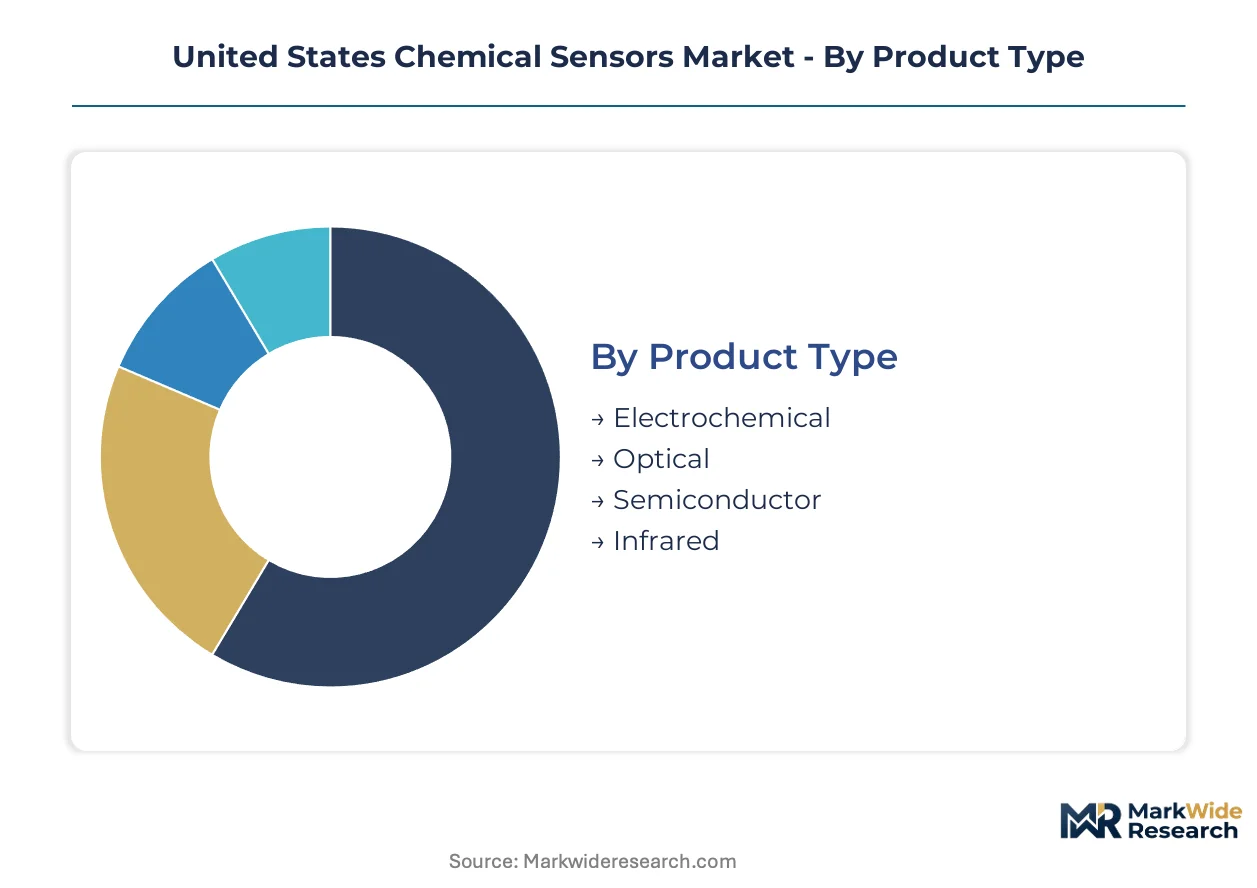
Chemical sensor procurement in the United States fragments across four distinct category axes. Product type determines the detection threshold and calibration burden. End-user concentration in Texas petrochemical corridors and Arizona semiconductor fabs shapes regional demand patterns.
Product Type:
Electrochemical and optical variants dominate standalone industrial safety deployments, while semiconductor architectures embed increasingly into automotive and consumer electronics systems.
- Electrochemical:Platinum or palladium electrode assemblies detect gases through oxidation-reduction reactions at parts-per-million thresholds. Gulf Coast refinery operators in Texas and Louisiana specify these for fixed-site benzene monitoring under EPA fenceline rules. Replacement cycles compress as OSHA exposure limits tighten.
- Optical:Tunable diode laser and nondispersive infrared architectures achieve parts-per-billion selectivity for volatile organic compound discrimination. California air districts mandate these for South Coast emission inventory verification. Unit premiums constrain adoption outside major metropolitan monitoring networks.
- Semiconductor:Metal-oxide chemiresistors integrate into battery management systems and cabin-air modules. Michigan EV assembly plants embed solid-state configurations for thermal runaway detection per NHTSA guidance.
- Infrared:Non-dispersive absorption spectroscopy targets hydrocarbon leak detection in midstream gas processing. Oklahoma and Kansas pipeline operators deploy these for real-time composition analysis.
Electrochemical configurations lead volumes today; semiconductor architectures are gaining share fastest.
End User:
Customer procurement sophistication varies sharply—healthcare and automotive buyers demand embedded integration, while environmental agencies prioritize calibration traceability.
- Healthcare:FDA-regulated anesthesia gas delivery and respiratory monitoring systems require medical-grade reference standards. Hospital purchasing consortiums in Massachusetts and Minnesota consolidate procurement around certified suppliers.
- Environmental Monitoring:EPA grant funding flows to Midwest state agencies expanding fixed-site networks. Illinois and Ohio environmental departments face calibration infrastructure gaps relative to Gulf Coast reference gas supply chains.
- Food Industry:Modified atmosphere packaging and cold-chain spoilage detection drive demand. Wisconsin dairy processors and California Central Valley packers deploy portable units for quality verification.
- Automotive:NHTSA cabin-air guidelines and battery ventilation mandates reshape OEM specifications. Ohio and Michigan assembly plants integrate solid-state sensors for lithium-ion thermal management.
Environmental monitoring commands the largest installed base; automotive applications show the steepest expansion trajectory.
Technology:
Transduction mechanism selection determines power consumption, miniaturization potential, and susceptibility to interferent species.
- Biochemical:Enzyme-functionalized electrodes target specific metabolite detection in medical and food safety contexts. Complexity limits deployment to laboratory and point-of-care settings.
- Amperometric:Current measurement at fixed potential dominates industrial gas detection. Mature manufacturing economics support high-volume safety monitor production.
- Conductometric:Resistance change upon analyte adsorption enables solid-state miniaturization. Emerging deployments in wireless mesh environmental networks.
- Potentiometric:Ion-selective electrodes measure solution-phase concentrations. Water quality monitoring in Great Lakes watershed agencies employs these for nutrient load tracking.
Amperometric methods anchor current revenue; conductometric platforms are climbing the fastest.
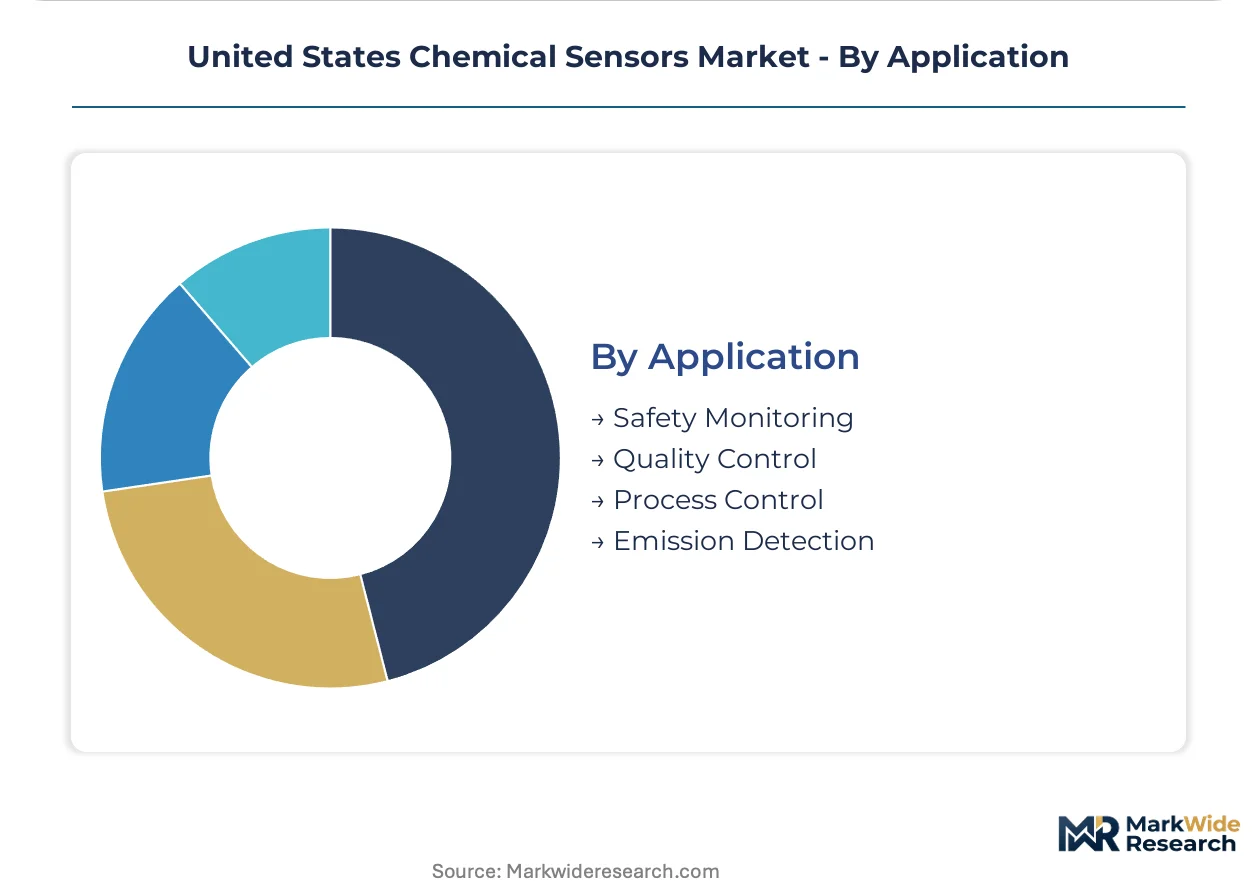
Application:
Use-case specificity dictates sensor specification, data-logging requirements, and compliance documentation burdens.
- Safety Monitoring:OSHA process safety management mandates drive continuous deployment in Texas and Louisiana petrochemical facilities. Fixed-site and personal protective equipment configurations require quarterly calibration.
- Quality Control:Semiconductor fabs in Arizona and Oregon monitor bulk specialty gas purity to prevent wafer contamination. Sub-parts-per-billion detection thresholds command optical architectures.
- Process Control:Real-time feedback loops optimize chemical reactor yields. Gulf Coast integrated producers embed sensors directly into distributed control systems.
- Emission Detection:EPA enforcement of Clean Air Act amendments compels fenceline monitoring. California South Coast Air Quality Management District imposes validation protocols exceeding federal minimums.
Safety monitoring retains the largest footprint; emission detection is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial chemical detection technology first achieved commercial scale in the United States during the 1970s Clean Air Act implementation, establishing the country as the foundational market for fixed-site monitoring infrastructure and calibration standardization.
Texas Gulf Coast
Petrochemical corridor operators deploy fenceline benzene sensor arrays under EPA enforcement protocols. The Texas Commission on Environmental Quality administers air permit programs that mandate continuous monitoring at Houston Ship Channel refineries. Corpus Christi and Beaumont process plants are replacing electrochemical units ahead of OSHA exposure limit compressions.
California South Coast
Semiconductor fabs and air quality districts drive optical sensor premiums for volatile organic compound discrimination. The South Coast Air Quality Management District imposes validation protocols exceeding federal minimums for emission inventory verification. San Jose and Irvine process gas monitoring installations command laboratory-grade reference standards.
Midwest Manufacturing Belt
Illinois and Ohio environmental agencies face calibration infrastructure gaps relative to Gulf Coast reference gas supply chains. EPA grant funding flows to fixed-site network expansion in Chicago and Cleveland metropolitan areas. Wisconsin dairy processors deploy portable units for modified atmosphere packaging quality verification.
Pacific Northwest
Arizona and Oregon semiconductor fabs accelerate sensor procurement for bulk specialty gas distribution systems. Sub-parts-per-billion detection thresholds in Phoenix and Hillsboro wafer fabrication facilities command tunable diode laser architectures. Process gas purity monitoring prevents contamination in advanced node production.
Great Lakes Region
Water quality monitoring agencies employ potentiometric ion-selective electrodes for nutrient load tracking in watershed protection programs. Michigan EV assembly plants integrate solid-state sensors for lithium-ion thermal management per NHTSA guidance. Detroit and Grand Rapids battery ventilation mandates reshape OEM specifications.
United States Chemical Sensors Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with certified calibration infrastructure and multi-decade field service footprints. Three archetypes dominate: integrated safety systems providers leveraging distributed maintenance networks, analytical instrumentation specialists anchoring regulatory compliance workflows, and embedded sensor architects reducing integration costs for process manufacturers. Consolidation pressure intensifies through unbundling of hardware from multi-year service contracts and vertical integration into reference gas supply chains.
Among diversified industrial conglomerates, Honeywell International Inc. and Emerson Electric Co. exemplify scale-driven archetypes with embedded sensor-to-control-system architectures. Thermo Fisher Scientific Inc. occupies a position within the laboratory-grade reference standards tier. These three anchors represent the competitive spectrum from field-service-intensive safety monitoring through analytical instrumentation specialization.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| Thermo Fisher Scientific Inc. |
| ABB Ltd. |
| Siemens AG |
| General Electric Co. |
| MSA Safety Incorporated |
| Teledyne Technologies Incorporated |
| Amphenol Corporation |
| Others |
Value Network & Pricing Analysis
Texas and Louisiana refinery procurement departments concentrate demand for multi-year maintenance contracts, locking pricing power with vendors possessing certified calibration infrastructure and Gulf Coast field-service footprints. This buyer concentration rewards bundled hardware-service offerings while pressuring standalone equipment margins.
Pricing Analysis
Three-tier pricing structure across laboratory-grade reference, industrial safety, and embedded semiconductor tiers dominates procurement patterns. Certification grade under EPA and OSHA protocols and volume scale through refinery consortium purchasing drive price differentiation. Cost compression in electrochemical safety monitors intensifies as precious metal electrode volatility squeezes OEM margins. Municipal air districts exhibit highest price sensitivity due to grant-funded budgets, while semiconductor fabs show lowest sensitivity given sub-parts-per-billion performance requirements.
Supply Chain Analysis
Freight costs for hazardous reference gas cylinders concentrate supply chain vulnerability in Gulf Coast industrial corridors relative to Midwest environmental agencies. Platinum and palladium electrode materials draw from South Africa and Russia; photonic integrated circuits source from Taiwan and Germany. Single-source vulnerability in certified calibration gas production creates geographic concentration risk. Distribution runs through authorized service networks requiring EPA protocol certification rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in solid-state semiconductor architectures displacing legacy electrochemical units, as miniaturization trends reduce bill-of-material costs while NHTSA and EPA mandates sustain premium pricing power.
For Market Incumbents: Anchor defensive positioning through captive supply of certified reference gases and backward integration into platinum-group metal electrode sourcing. Electrochemical sensor commoditization from Asian competitors threatens replacement-cycle revenue. Lock in multi-year calibration contracts with Texas and California petrochemical operators before procurement departments complete unbundling transitions. For New Entrants and Emerging Players: The gap between tunable diode laser optical premiums and electrochemical economy pricing opens white-space at mid-tier selectivity levels. Appalachian shale basin emissions monitoring lacks continuous surveillance infrastructure. Wisconsin dairy and food packaging applications favor portable conductometric units with wireless mesh integration. Pursue EPA grant-funded procurement channels for Midwest environmental agency network expansion. For Investors and Strategic Acquirers: Industrial conglomerates with distributed field-service footprints are the most active acquirers in this space, consolidating calibration infrastructure and reference standard capabilities. Long-term viability hinges on regulatory enforcement intensity sustaining replacement cycle compression. Monitor OSHA permissible exposure limit revision timelines as inflection indicators for hardware refresh demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reference Gas Production | Captive supply of EPA-certified calibration standards locks in maintenance contract renewals with Gulf Coast refineries. |
| Solid-State Semiconductor Platform Launch | Miniaturized chemiresistor architectures penetrate NHTSA-mandated EV battery ventilation specifications across Michigan assembly plants. |
| Wireless Mesh Network Partnership | Low-power wide-area integration enables retrofit deployments without conduit installation for Midwest environmental monitoring stations. |
| Optical Sensor Cost Reduction Program | Photonic integrated circuit manufacturing scale compresses price-performance gaps against electrochemical alternatives in emission detection. |
| Multi-Agency Compliance Software Development | Synchronized EPA and OSHA reporting protocols reduce documentation bottlenecks for Texas process safety management audits. |
Research Methodology
Multiple input streams — primary interviews with refinery process safety managers, EPA regional enforcement officers, and semiconductor fab gas distribution engineers; secondary validation through EPA enforcement databases, OSHA inspection records, and SEC filings from diversified industrial conglomerates — were reconciled through bottom-up unit deployment tracking and top-down market sizing triangulation.
Data-stream reconciliation anchored volume projections across product type, end-use vertical, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from replacement cycle compression analysis under tightened exposure limits and semiconductor fab expansion pipelines. Forecast inputs incorporated precious metal price volatility assumptions and EPA grant funding allocation patterns.
Caveats apply where OSHA enforcement intensity shifts or EPA ambient air quality standard revisions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
Safety Laser Scanner Market
Sensors and Controls
Blue-Green Algae Sensors Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
US Occupancy Sensors Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Photoelectric Sensor Market