
 Data Center Ssds Market | 2026-2036
Data Center Ssds Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Ssds Market Outlook
Hyperscale data center operators is realigning procurement priorities toward NVMe-based storage fabrics to minimize latency for artificial intelligence inference clusters. Samsung Electronics leverages vertical integration from NAND wafer fabrication to controller silicon to secure supply continuity for cloud-scale deployments. SK Hynix anchors high-bandwidth memory adjacent SSD architectures that reduce data movement overhead in GPU-accelerated servers. Micron Technology competes through advanced 232-layer NAND yields that improve cost-per-terabyte economics for enterprise rack-density targets.
Data center SSDs constitute solid-state storage devices engineered with NAND flash memory cells, PCIe or SAS/SATA host interfaces, and wear-leveling firmware to deliver sub-millisecond access latency for mission-critical workloads. These devices replace mechanical hard drives in server environments where input-output operations per second and thermal efficiency determine total cost of ownership. NVMe SSD commands premium positioning in cloud storage and hyperscale data center applications where parallel command queues exploit PCIe bandwidth. SATA SSD retains residual share in on-premises deployment configurations where legacy controller compatibility postpones infrastructure refresh cycles. Edge computing represents the fastest-growing application segment as content delivery networks distribute inference models closer to endpoint users.
FCC equipment authorization requirements govern electromagnetic emissions for SSDs deployed in US telecom operator facilities, while EPA ENERGY STAR specifications shape procurement criteria for federal data center consolidation programs. The EU F-Gas Regulation indirectly affects cooling system design that determines allowable thermal envelopes for high-density NAND modules in European colocation facilities. ECHA REACH compliance obligations restrict certain substrate materials in controller board assemblies, compelling foundry partners to certify alternative halogen-free laminates. Stakeholders must monitor interface protocol transitions from PCIe 4.0 to 5.0 architectures and assess whether controller firmware investments align with emerging computational storage standards.
Market Dynamics
Hyperscale cloud operators are compressing refresh cycles for storage infrastructure to support AI training clusters, forcing NAND suppliers to align wafer output with quarterly capacity expansion schedules rather than traditional annual procurement rhythms.
Growth Catalysts
- EU AI Act compliance deadlines:European data center operators face mandatory energy efficiency reporting requirements that favor high-density NAND configurations over legacy mechanical storage. This accelerates replacement demand in Frankfurt, Amsterdam, and Dublin colocation clusters.
- GPU-accelerated server architectures:AI inference workloads require storage subsystems capable of saturating PCIe 5.0 bandwidth. NVMe SSD deployments in training clusters now outpace general-purpose compute storage by a factor of three in petabytes shipped.
- Edge content delivery networks:Streaming platforms distribute machine learning models to metropolitan points of presence, creating distributed storage demand that favors compact, thermally efficient SSD form factors over centralized hard drive arrays.
Market Restraints
- NAND wafer supply concentration:Foundry output for advanced nodes concentrates in South Korea and Taiwan, exposing procurement schedules to geopolitical friction and export control uncertainty.
- Controller silicon shortage:Arm-based SSD controller availability constrains module production independently of NAND flash supply, creating bottlenecks for enterprise-qualified drives.
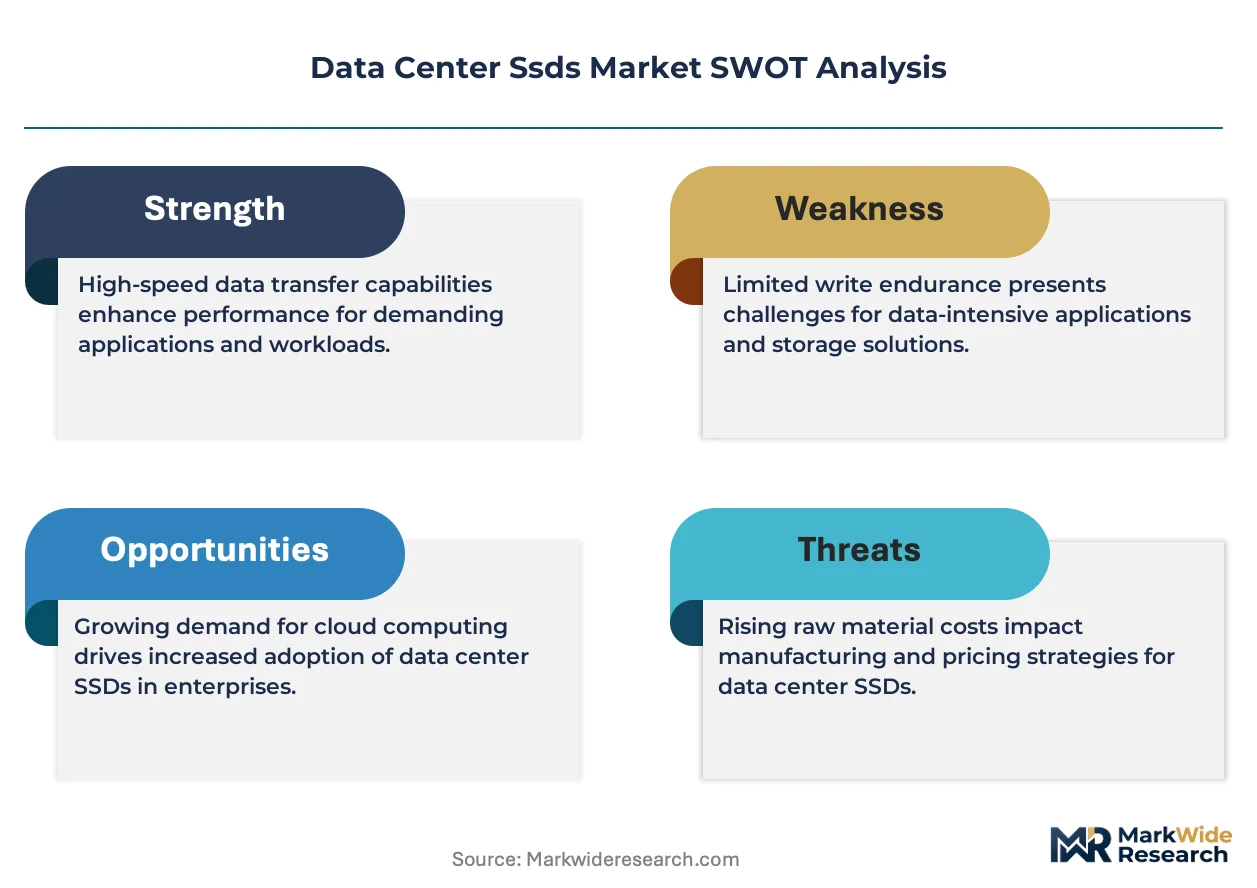
- QLC endurance limitations:Quad-level cell NAND exhibits reduced write endurance compared to TLC alternatives, restricting deployment in write-heavy logging and caching applications without overprovisioning penalties.
Strategic Opportunities
- Computational storage standardization:SNIA computational storage specifications enable processing-in-storage architectures that reduce data movement overhead for analytics workloads. Early adopters in financial services pilot FPGA-accelerated SSDs for risk modeling.
- India data center buildout:PLI scheme incentives for electronics manufacturing attract module assembly investments serving domestic cloud and telecom operators. Mumbai and Chennai emerge as regional distribution hubs.
- Federal consolidation mandates:US EPA ENERGY STAR procurement criteria for federal data centers create preferential purchasing pathways for qualified SSD vendors in government integrator channels.
Industry Challenges
- Firmware qualification timelines:Hyperscale operators require twelve-to-eighteen-month validation cycles for controller firmware revisions, delaying adoption of density-improving NAND generations.
- Legacy SAS controller integration:Enterprise storage arrays with twelve-gigabit SAS backplanes resist NVMe retrofit, forcing dual-interface module development that increases bill-of-materials complexity.
- Thermal envelope management:PCIe 5.0 SSD power consumption exceeds fifteen watts under sustained load, requiring chassis redesigns that accommodate enhanced heat spreaders without compromising rack density targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Ssds Market |
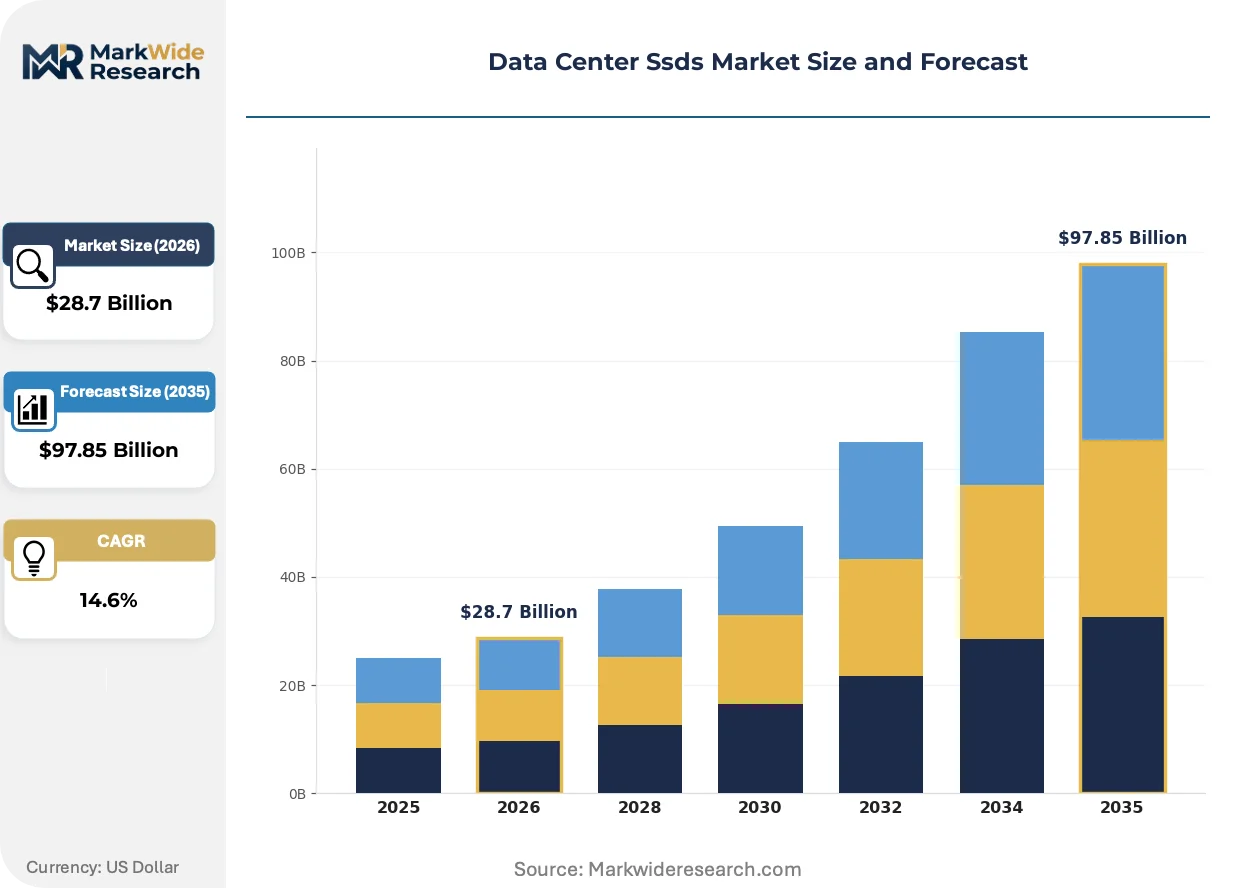
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $97.85 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SATA SSD, SAS SSD, NVMe SSD, PCIe SSD Application: Cloud Storage, Hyperscale Data Centers, Edge Computing, Content Delivery Networks Deployment: On-Premises, Colocation, Hybrid, Managed Services End User Industry Vertical: Telecom Operators, Financial Institutions, E-commerce Platforms, Scientific Research Labs |
| Companies Covered | Samsung Electronics, Western Digital, Micron Technology, Intel, Toshiba, Kioxia, Seagate Technology, SK Hynix, Kingston Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Ssds Market Strategic Shifts
Storage architecture is fragmenting along workload-specific lines, with AI inference, real-time analytics, and archival compliance each demanding distinct NAND configurations, interface protocols, and endurance specifications.
PCIe 5.0 NVMe controllers are converging with CXL memory expansion fabrics to create unified memory-storage hierarchies in GPU servers. Cloud operators deploying NVIDIA H100 clusters adopt these converged subsystems to eliminate CPU-mediated data copies. The structural consequence is collapsing the historical boundary between DRAM and flash tiers, forcing SSD vendors to develop firmware that exposes byte-addressable semantics.
The EU F-Gas Regulation restricts hydrofluorocarbon-based cooling agents in data centers above five-hundred-kilowatt capacity. European operators in the Netherlands and Germany retrofit facilities with liquid cooling loops that enable higher thermal envelopes for dense NAND modules. Module suppliers now qualify extended-temperature SKUs specifically for direct-to-chip cooling configurations.
Hyperscale procurement committees now separate storage purchases from server chassis contracts, creating direct relationships with NAND module vendors that bypass traditional OEM integrators. Amazon Web Services, Microsoft Azure, and Google Cloud negotiate annual volume commitments with Samsung and SK Hynix that specify custom firmware features and failure-rate thresholds. This disintermediation concentrates in the United States, where cloud capital expenditure exceeds European and Asian-Pacific markets combined.
Data Center Ssds Market Segmentation
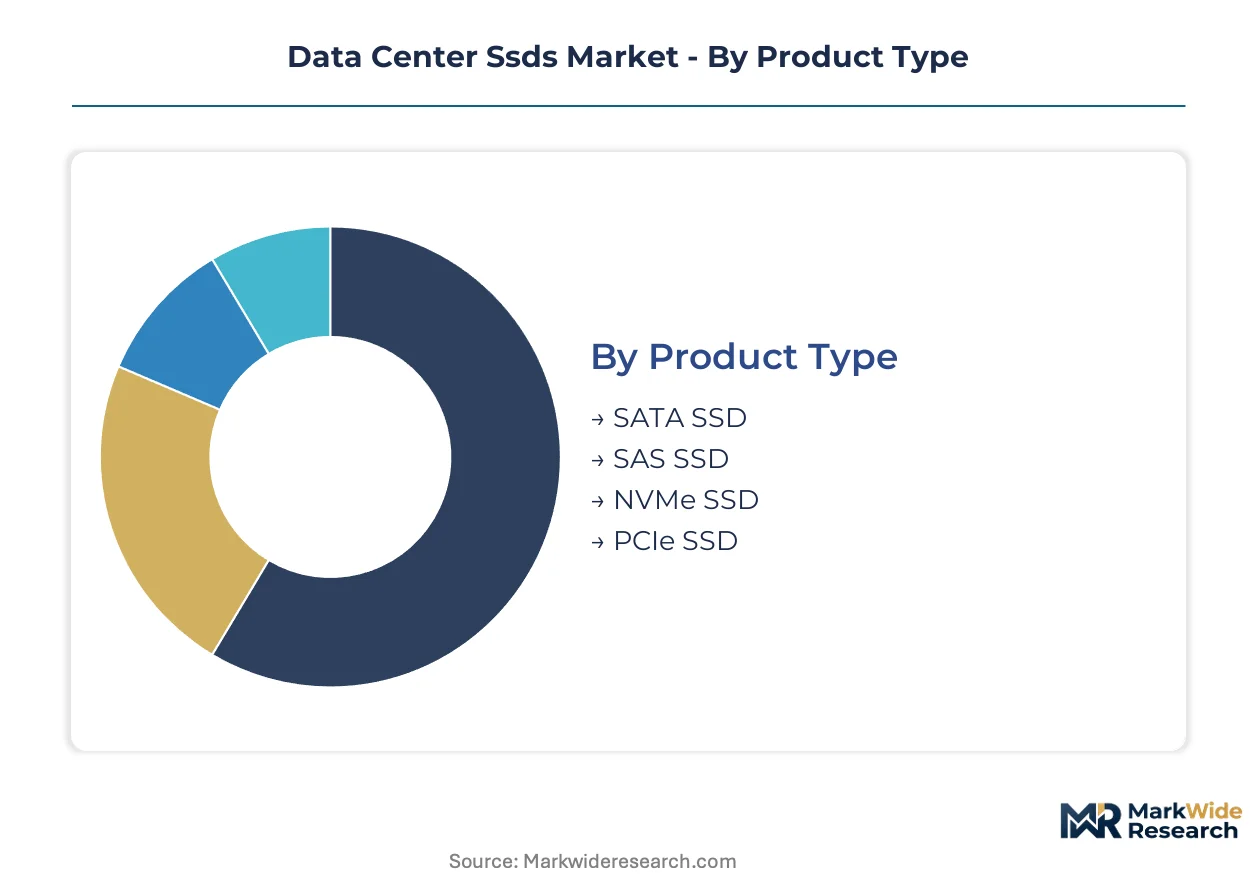
Data center SSD segmentation reveals divergent procurement patterns across interface generations and deployment architectures. Cloud operators optimize for throughput density while edge deployments prioritize thermal envelope and form factor constraints.
Product Type:
Volume shipments concentrate in legacy interfaces, yet premium positioning and margin capture align with next-generation protocols.
- NVMe SSD:PCIe-attached controllers exploit parallel command queues to saturate host bandwidth for GPU-accelerated training clusters. Hyperscale operators in the United States now specify NVMe-native backplanes for new server chassis, displacing legacy controller compatibility requirements.
- SATA SSD:Mature AHCI protocol retains residual share in on-premises refresh cycles where controller firmware stability outweighs bandwidth limitations. Federal data center consolidation programs specify SATA-qualified modules for backward compatibility with existing storage arrays.
- SAS SSD:Dual-port twelve-gigabit interface serves enterprise storage arrays requiring redundant controller paths. Financial institutions in Frankfurt specify SAS-qualified drives for trading floor latency requirements.
- PCIe SSD:Direct-attached controllerless designs integrate into CXL memory expansion fabrics for unified memory-storage hierarchies. Cloud operators pilot these configurations in NVIDIA H100 server deployments.
Today's leader: NVMe SSD. Tomorrow's challenger: PCIe SSD.
Application:
Workload-specific storage architectures fragment procurement specifications across bandwidth, endurance, and thermal dimensions.
- Hyperscale Data Centers:AI training clusters demand petabyte-scale NVMe deployments with custom firmware features negotiated directly with NAND suppliers. Amazon Web Services, Microsoft Azure, and Google Cloud specify failure-rate thresholds independent of traditional OEM channels.
- Edge Computing:Metropolitan points of presence distribute inference models closer to endpoint users, favoring compact M.2 and E1.S form factors over centralized drive arrays. Content delivery networks in Mumbai and Chennai specify thermally efficient modules for uncontrolled ambient environments.
- Cloud Storage:Object storage tiers utilize QLC NAND for read-heavy archival workloads with reduced write endurance requirements. European operators align configurations with EU AI Act energy efficiency reporting mandates.
- Content Delivery Networks:Streaming platforms cache machine learning models at network edge nodes, requiring low-latency access for personalized recommendation engines. Netflix and Disney+ specify firmware-optimized drives for video transcoding pipelines.
Hyperscale Data Centers command current procurement volume. Edge Computing exhibits the steepest expansion trajectory as inference workloads decentralize.
Deployment:
Capital expenditure ownership models determine interface selection and qualification timelines.
- Colocation:Third-party facility operators in Amsterdam and Dublin specify high-density NAND configurations to meet EU F-Gas Regulation cooling constraints. Direct liquid cooling enables fifteen-watt PCIe 5.0 modules in retrofitted chassis.
- On-Premises:Enterprise IT organizations maintain twelve-to-eighteen-month firmware validation cycles, delaying adoption of density-improving NAND generations. Legacy SAS backplanes resist NVMe retrofit without complete array replacement.
- Hybrid:Split workloads across owned and leased infrastructure complicate unified storage management. Financial institutions pilot computational storage standards to reduce data movement overhead between premises and cloud tiers.
- Managed Services:Outsourced infrastructure operators aggregate demand across multiple tenants, negotiating volume commitments with module vendors. Indian PLI scheme incentives attract assembly investments serving domestic cloud operators.
Colocation captures premium pricing for thermal-managed density. On-Premises retains the largest installed base awaiting refresh triggers.
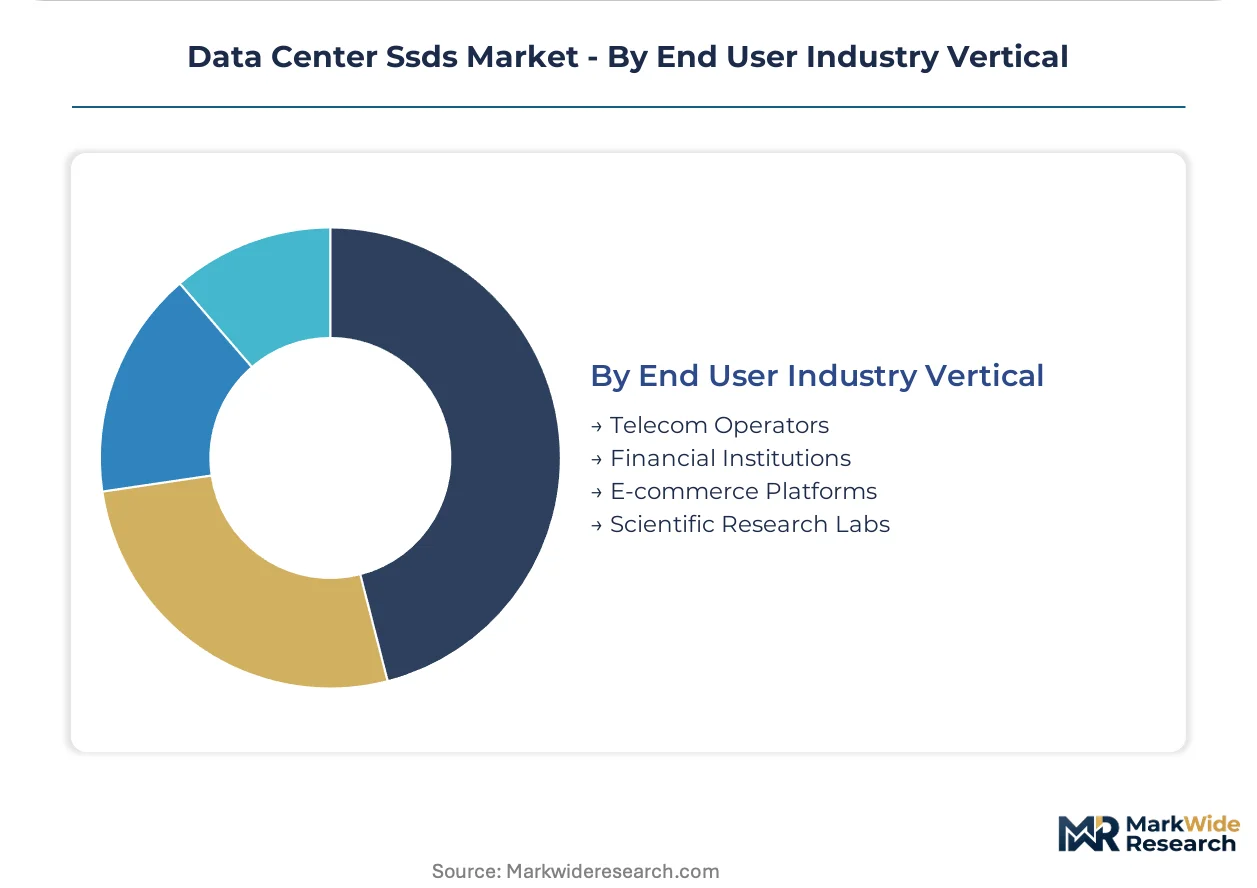
End User Industry Vertical:
Sector-specific compliance and latency requirements drive interface protocol selection.
- Telecom Operators:FCC equipment authorization governs electromagnetic emissions for SSDs deployed in 5G edge facilities. Verizon and AT&T specify NVMe modules for network function virtualization infrastructure.
- Financial Institutions:Risk modeling workloads pilot FPGA-accelerated computational storage for in-place analytics. Frankfurt trading floors specify sub-millisecond latency guarantees in procurement contracts.
- E-commerce Platforms:Recommendation engine inference requires rapid model weight access at scale. Alibaba and JD.com deploy high-bandwidth memory-adjacent SSD architectures in GPU servers.
- Scientific Research Labs:Climate modeling and genomics workloads generate petabyte-scale datasets with irregular access patterns. CERN and Oak Ridge National Laboratory specify custom firmware for write-heavy logging applications.
Telecom Operators anchor current demand volume. Scientific Research Labs are gaining share fastest as federal AI initiatives expand infrastructure budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting NAND module assembly toward jurisdictions with streamlined electronics manufacturing incentives and lower energy compliance costs, compressing traditional procurement timelines for hyperscale operators.
United States
Hyperscale cloud capital expenditure in Virginia, Oregon, and Arizona drives petabyte-scale NVMe procurement for AI training clusters. EPA ENERGY STAR specifications govern federal data center consolidation programs, creating preferential purchasing pathways for qualified vendors. Northern Virginia's Loudoun County hosts the densest concentration of cloud storage deployments globally.
South Korea
Advanced NAND wafer fabrication concentrates in Gyeonggi Province and Seoul Capital Area, supplying cloud operators with quarterly-aligned capacity expansion schedules. The country's national industrial regulator enforces export control protocols that shape foundry output allocation. Samsung Electronics and SK Hynix anchor captive supply chains from wafer to module assembly.
China
Domestic cloud operators Alibaba and Tencent expand flash storage deployments for inference workloads across Beijing-Tianjin-Hebei and Yangtze River Delta clusters. MIIT standards govern data center energy efficiency reporting for facilities above five-hundred-kilowatt capacity. Yangtze Memory Technologies accelerates domestic NAND production in Wuhan to reduce import dependency.
Germany
Frankfurt and Berlin colocation operators retrofit facilities with liquid cooling to accommodate EU F-Gas Regulation constraints on hydrofluorocarbon agents. The EU AI Act mandates energy efficiency reporting that favors high-density NAND over mechanical storage. Hesse's Frankfurt Rhine-Main region anchors European financial services storage demand for sub-millisecond latency trading infrastructure.
India
PLI scheme incentives for electronics manufacturing attract module assembly investments serving domestic cloud and telecom operators in Mumbai and Chennai. TRAI spectrum allocation policies accelerate 5G edge facility deployment requiring FCC-equipment-authorized storage modules. Tamil Nadu's Sriperumbudur electronics corridor emerges as a regional distribution hub for South Asian hyperscale procurement.
Data Center Ssds Market Competitive Environment
Capacity expansion dominates the current landscape as NAND suppliers align wafer output with hyperscale quarterly procurement rhythms rather than traditional annual cycles. The vendor base concentrates among integrated memory manufacturers with captive foundry access, creating tiered competition between full-stack producers and fabless module assemblers. Three archetypes define positioning: vertically integrated memory houses controlling wafer-to-module supply chains; legacy hard drive manufacturers pivoting toward flash through acquisition; and specialist module integrators serving regional compliance requirements. Competitive intensity centers on controller silicon availability and custom firmware qualification timelines.
Among integrated memory manufacturers, Samsung Electronics, SK Hynix, and Micron Technology exemplify the full-stack archetype with in-house NAND fabrication and controller development capabilities. These entities occupy positions where supply continuity negotiations with hyperscale operators bypass traditional OEM channels. Western Digital and Kioxia represent the pivot archetype, with corporate structures reflecting storage industry consolidation dynamics. Kingston Technology anchors the specialist integrator tier, serving procurement channels where regional certification and logistics responsiveness outweigh captive wafer supply.
| Leading Market Players |
|---|
| Samsung Electronics |
| Western Digital |
| Micron Technology |
| Intel |
| Toshiba |
| Kioxia |
| Seagate Technology |
| SK Hynix |
| Kingston Technology |
| Others |
Value Chain & Pricing Dynamics
Captive wafer-to-module integration anchors supply continuity and pricing power for integrated memory manufacturers serving hyperscale cloud operators. Samsung Electronics and SK Hynix leverage in-house NAND fabrication in South Korea to negotiate direct annual volume commitments with Amazon Web Services, Microsoft Azure, and Google Cloud, bypassing traditional OEM integrator markups that compress margins for fabless assemblers.
Pricing Analysis
Distributor margins collapse where hyperscale procurement committees negotiate direct contracts with NAND suppliers, compressing the traditional two-step channel structure. Contract-based long-term offtake dominates, with pricing stratifying across enterprise-qualified, cloud-customized, and residual SATA tiers based on firmware qualification investment and failure-rate thresholds. Cost compression in QLC modules intensifies because hyperscale operators prioritize cost-per-terabyte over write endurance for read-heavy archival tiers. Federal data center consolidation programs exhibit highest price sensitivity due to ENERGY STAR procurement constraints, while GPU-accelerated training clusters show least sensitivity given bandwidth saturation requirements.
Supply Chain Analysis
FCC equipment authorization and ECHA REACH compliance obligations gate module qualification timelines, extending validation cycles for controller firmware revisions. NAND wafer output concentrates in South Korea, Taiwan, and the United States, while controller silicon depends on Arm-based designs from Taiwan foundries and substrate laminates from Japanese suppliers. Single-source vulnerability runs through advanced node foundry concentration in Gyeonggi Province, exposing procurement schedules to export control friction. Distribution runs through direct vendor-managed inventory programs at hyperscale facilities, supplemented by regional logistics hubs in Northern Virginia and Frankfurt for qualified spare pooling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Module assembly investments gravitate toward jurisdictions with streamlined electronics manufacturing incentives and lower energy compliance costs, creating arbitrage between India's PLI scheme subsidies and the EU F-Gas Regulation's cooling infrastructure mandates.
For Market Incumbents: Hedge against controller silicon shortage by securing multi-source qualification for Arm-based SSD controllers from Taiwan and domestic alternatives. Samsung Electronics and SK Hynix should deepen backward integration into controller silicon to reduce dependency on external foundry allocation. Capacity addition in Tamil Nadu's Sriperumbudur corridor captures Indian domestic cloud procurement growth while mitigating geopolitical exposure in Taiwan Strait logistics. For New Entrants and Emerging Players: The EU AI Act in Germany and the Netherlands opens a window for thermally efficient module designs qualified for direct liquid cooling configurations. Edge computing in Mumbai and Chennai presents the most penetrable geography, with content delivery networks distributing inference models to uncontrolled ambient environments. A go-to-market angle anchored in FCC-equipment-authorized compact form factors serves Verizon and AT&T 5G edge facility deployment timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where controller firmware qualification timelines stretch twelve-to-eighteen months, favoring acquirers with existing hyperscale relationships over greenfield entrants. Long-term viability across the next decade hinges on computational storage standardization adoption in financial services risk modeling. The signal to watch is CXL memory expansion fabric penetration in NVIDIA H100 server deployments, indicating firmware architecture transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Computational Storage Standardization | SNIA specifications enable processing-in-storage architectures that reduce data movement overhead for analytics workloads. |
| Direct Liquid Cooling Qualification | Extended-temperature SKUs for EU F-Gas Regulation compliance capture Frankfurt and Amsterdam colocation retrofit demand. |
| Controller Silicon Multi-Sourcing | Arm-based alternative qualification mitigates supply bottlenecks independently of NAND flash availability constraints. |
| India PLI Scheme Assembly Investment | Mumbai and Chennai regional hubs serve domestic cloud operators and telecom infrastructure expansion programs. |
| PCIe 5.0 Firmware Optimization | Custom firmware features negotiated with hyperscale operators saturate bandwidth for GPU-accelerated training clusters. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hyperscale procurement executives, NAND supplier product managers, colocation facility operators, and controller firmware engineers with secondary validation. SEC 10-K filings from integrated memory manufacturers, hyperscaler capex disclosures, FCC equipment authorization databases, and ECHA REACH substance restriction notifications anchored supply-side assessment. Bottom-up module shipment aggregation and top-down cloud infrastructure investment analysis triangulated market sizing.
Historical reference periods spanning installed base refresh cycles and NAND generation transitions anchored projection modeling across the analysis window. Segmentation dimensions included interface protocol generation, deployment architecture, workload application, and regional regulatory cluster. CAGRs derived from capacity expansion schedules aligned with hyperscale quarterly procurement rhythms rather than traditional annual patterns. Forecast inputs incorporated foundry yield improvement trajectories and PCIe protocol transition adoption curves.
Revisions become necessary when export control protocols disrupt controller silicon or NAND wafer supply allocation, or when computational storage standards accelerate beyond current firmware development timelines. Forecasts reflect documented assumptions regarding hyperscale capital expenditure continuity and edge facility deployment pacing. A model refresh is warranted upon material change in EU AI Act enforcement timelines or India PLI scheme incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Blu-Ray Drive Market
Data Storage
Middle East Data Center Storage Market
Data Storage
South Korea Data Center Storage Market
Data Storage
Multiprotocol Storage Market
Data Storage
OTG Pen Drive Market
Data Storage
Americas Flash Memory Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
NAND Flash Market
Data Storage
External Storage Market
Data Storage
Object-Based Storage Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Global Portable Data Storage Market
Data Storage
AI Powered Storage Market
Data Storage
USB 3.1 Flash Drive Market
Data Storage
NAND Flash Memory Market
Data Storage
Asia Pacific Transparent Caching Market