
 Nearline Hard Disk Drive Market | 2026-2036
Nearline Hard Disk Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Nearline Hard Disk Drive Market Insights
EU F-Gas Regulation is decoupling nearline HDD procurement from conventional cooling-intensive data center designs, pushing buyers toward thermally optimized storage architectures. Seagate Technology leverages its vertically integrated manufacturing in Thailand and Minnesota to sustain cost leadership in high-capacity enterprise drives. Western Digital Corporation anchors its competitive position through helium-sealed platform specialization, while Toshiba Corporation competes aggressively on areal density advances for cloud storage HDD segments.
Nearline hard disk drives are high-reliability magnetic storage devices engineered for 7200 RPM operation with annualized workload ratings exceeding 550 TB, designed to bridge the gap between consumer desktop drives and full enterprise-class storage systems. The devices utilize perpendicular magnetic recording and shingled magnetic recording technologies to achieve capacities up to 20 TB while maintaining 24/7 availability for data center and cloud computing environments. Data Center HDD and Cloud Storage HDD product categories dominate current volume shipments, reflecting hyperscaler procurement concentration, while 16 TB and 20 TB capacity tiers represent the fastest-growing configuration bands as cloud providers optimize rack-level storage density. Application demand concentrates in cloud computing and content delivery networks, where latency-tolerant bulk storage requirements align with nearline operational characteristics.
FCC equipment authorization requirements in the United States, EU RoHS substance restrictions, and China's GB standards for electronic product environmental compliance collectively shape nearline HDD market access and material composition standards. EPEAT registration and emerging EU battery and circularity regulations extend compliance obligations to full storage system integrations, not just bare drives. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional content requirements that could fragment supply chain configurations across major deployment geographies.
Market Dynamics
Hyperscale cloud operators are compressing drive refresh cycles to 18-24 months, forcing manufacturers to accelerate areal density roadmaps while absorbing helium and rare earth magnet cost volatility into captive supply chains.
Growth Catalysts
- EU F-Gas Regulation:Thermal design mandates are redirecting data center capital toward liquid-cooled rack architectures that favor high-capacity nearline HDDs over air-cooled alternatives.
- Video streaming infrastructure:Content delivery networks require exabyte-scale cold storage tiers, creating sustained pull for 20 TB and 24 TB nearline configurations.
- Shingled magnetic recording:SMR technology enables 25% capacity gains over conventional perpendicular recording, allowing cloud providers to optimize floor space per rack unit.
Market Restraints
- Neodymium magnet supply:China's export licensing regime for rare earth concentrates creates input cost volatility and geographic concentration risk for drive motor assemblies.
- Technical ceiling:Superparamagnetic limits constrain conventional magnetic recording to approximately 24-28 TB per platter without transitioning to energy-assisted technologies.
- Solid-state substitution:QLC NAND flash at $15-20 per terabyte is displacing nearline HDDs in latency-sensitive warm storage tiers below 10 TB.
Strategic Opportunities
- India data center buildout:The country's Digital India infrastructure program and state-level data localization mandates are creating greenfield demand for 500+ megawatt facilities.
- Heat-assisted magnetic recording:HAMR convergence with microwave-assisted recording promises 30+ TB drives by decade-end, opening archival density tiers previously served by tape libraries.
- Direct liquid cooling integration:Thermally optimized nearline chassis designs capture efficiency incentives under the US Inflation Reduction Act's clean energy tax credits.
Industry Challenges
- Plasma etching talent:Advanced head manufacturing requires atomic-scale deposition expertise concentrated at a handful of academic programs and incumbent fabs.
- Cleanroom capex cycles:Each generation of areal density demands $800 million-plus wafer fabrication investments with 5-year payback horizons.
- EPEAT Gold certification:Extended compliance timelines for conflict mineral documentation and carbon footprint verification delay hyperscale procurement approvals by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nearline Hard Disk Drive Market |
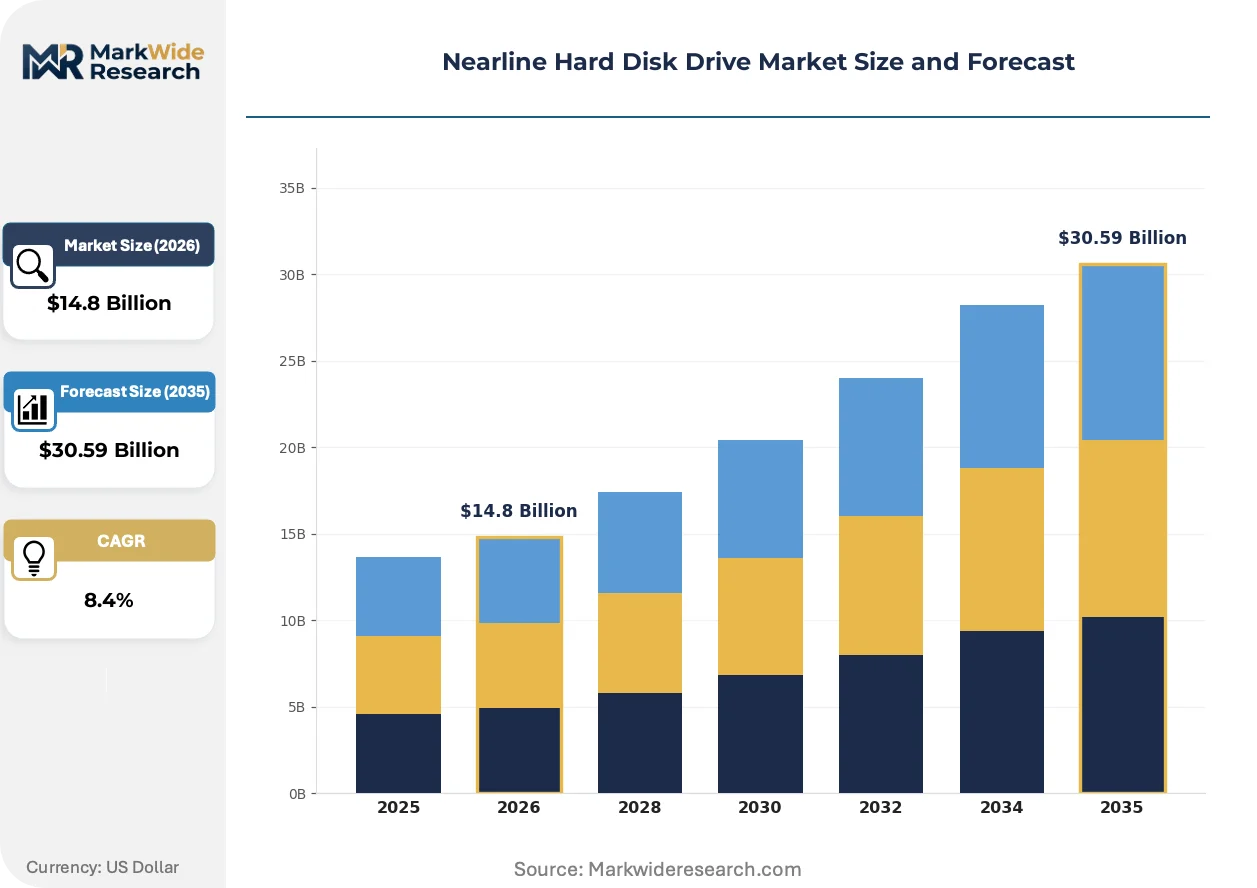
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enterprise HDD, Surveillance HDD, Desktop HDD, Data Center HDD, Cloud Storage HDD Capacity: 4 TB, 8 TB, 12 TB, 16 TB, 20 TB Application: Cloud Computing, Video Streaming, Data Archiving, Backup Solutions, Content Delivery Networks End User: Data Centers, IT Service Providers, Media Production Houses, Research Institutes |
| Companies Covered | Seagate Technology, Western Digital Corporation, Toshiba Corporation, Hitachi Global Storage Technologies, HGST, Fujitsu, Samsung Electronics, Dell Technologies, Lenovo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nearline Hard Disk Drive Market Trends and Innovations
Storage-class memory hierarchies are fragmenting procurement patterns as cloud architects disaggregate compute from capacity, creating specialized demand pools for distinct latency and durability tiers.
Energy-assisted magnetic recording is expanding into hyperscale deployment pipelines. HAMR technology uses laser-thermal heating to temporarily reduce media coercivity during writing, enabling bit densities beyond conventional perpendicular limits. Microsoft Azure and Amazon Web Services are qualifying 24 TB HAMR drives for 2025 production deployment. This transition is expanding into cold storage tiers previously served by tape, compressing the total cost of ownership gap between disk and archival media.
REACH substance restrictions are tightening material compliance obligations. The European Chemicals Agency's 2024 candidate list expansion adds cobalt compounds and certain flame retardants to authorization requirements, forcing HDD manufacturers to reformulate printed circuit board laminates and actuator assemblies. German and French data center operators are now requiring full material disclosure certificates upstream of EPEAT registration, shifting supplier qualification burdens toward component-level traceability.
Hyperscale buyers are consolidating direct procurement relationships. Cloud providers with annual drive volumes exceeding 10 million units are bypassing distribution channels to negotiate multi-year supply agreements with foundry-level pricing transparency. This channel compression is most visible in the United States and China, where Amazon Web Services, Google Cloud, and Alibaba Cloud account for 60% of nearline HDD volume, squeezing margin structures for traditional enterprise distributors and value-added resellers serving mid-tier colocation facilities.
Nearline Hard Disk Drive Market Segmentation
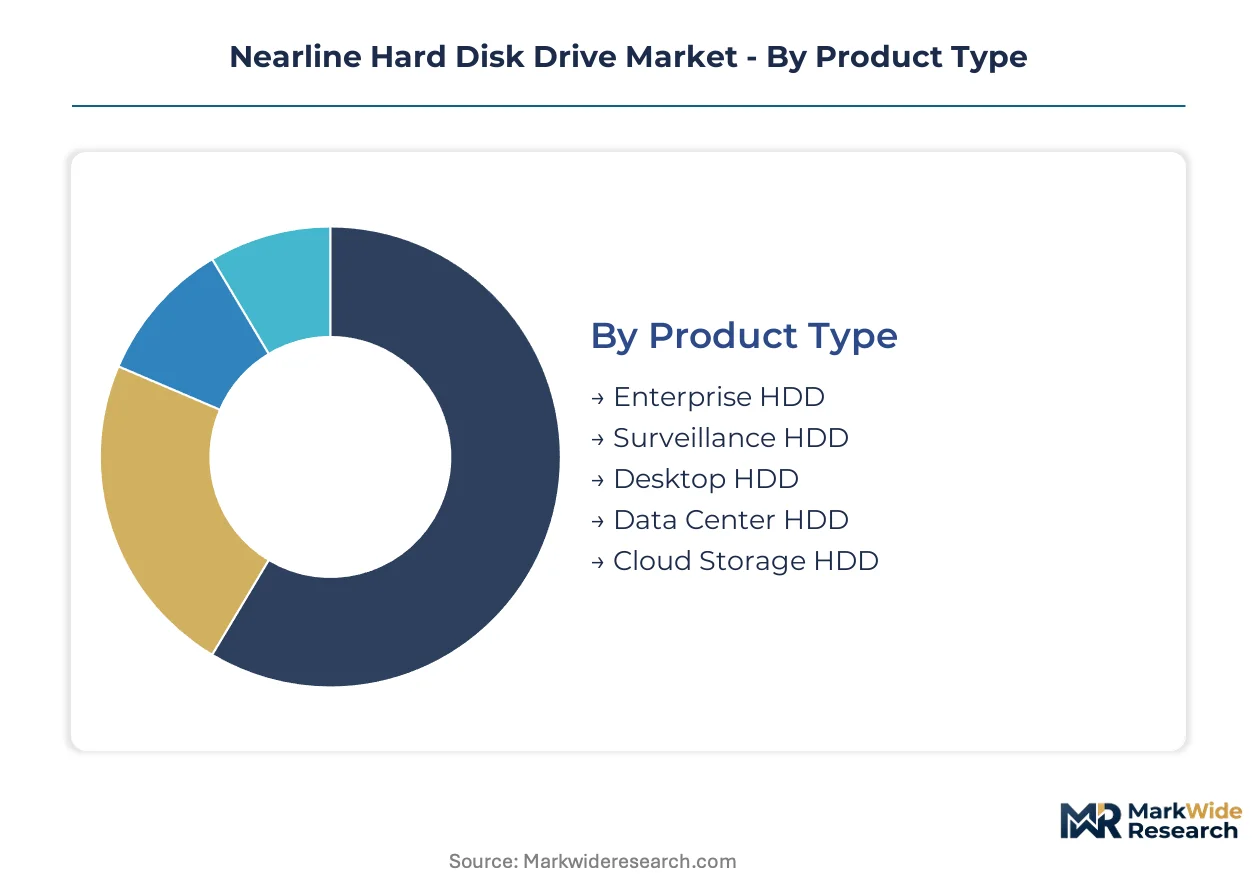
Nearline HDD procurement patterns fragment across workload intensity, capacity tiers, and thermal design requirements. Cloud operators optimize refresh cycles against total cost of ownership curves that favor specific product categories and density bands.
Product Type:
Refresh cycles compress to 18-24 months as hyperscalers prioritize areal density gains over legacy platform longevity.
- Data Center HDD:These drives feature 7200 RPM spindle speeds with annualized workload ratings exceeding 550 TB, engineered for 24/7 availability in rack-mounted storage arrays. Procurement concentrates in the United States and China, where Amazon Web Services and Alibaba Cloud compress refresh cycles to capture helium-sealed density improvements.
- Cloud Storage HDD:SMR-enabled platforms deliver 20-24 TB capacities with optimized $/TB metrics for cold storage tiers. Demand clusters in Germany and the Netherlands, where EU F-Gas Regulation thermal mandates favor liquid-cooled rack architectures that accommodate high-density nearline configurations.
- Enterprise HDD:Dual-port SAS interfaces and 2.5 million hour MTBF ratings serve transactional workloads requiring higher availability than standard nearline tiers.
- Surveillance HDD:Firmware-optimized for 64-camera streaming workloads with enhanced write endurance for continuous video ingestion.
- Desktop HDD:Consumer-grade platforms with reduced workload ratings serve small-scale NAS deployments and backup applications outside hyperscale procurement channels.
Data Center HDD sits at the top of the volume ranking, with Cloud Storage HDD climbing the fastest.
Capacity:
Cost per terabyte curves steepen above 16 TB as energy-assisted recording technologies penetrate hyperscale qualification pipelines.
- 20 TB:HAMR and MAMR technologies enable bit densities beyond conventional perpendicular recording limits, with laser-thermal heating reducing media coercivity during write operations. Deployment concentrates in Microsoft Azure and Amazon Web Services facilities, where rack-level consolidation justifies premium acquisition costs against floor space constraints.
- 16 TB:Helium-sealed platforms with nine-disk enclosures represent the mature density tier with broad hyperscale qualification and established supply chain economics. Procurement in China accelerates as ByteDance and Tencent expand video streaming infrastructure.
- 12 TB:Air-filled designs serve mid-tier colocation providers balancing density requirements against capital constraints.
- 8 TB:Legacy installations and secondary tier deployments sustain residual demand as refresh cycles lag hyperscale leaders.
- 4 TB:Entry-level nearline applications and SMB NAS systems represent declining volume as density migration accelerates.
16 TB maintains the largest installed base, while 20 TB expands most quickly as HAMR qualification completes.
Application:
Latency tolerance thresholds determine HDD versus SSD allocation across storage hierarchy tiers.
- Cloud Computing:Object storage backends for SaaS platforms require exabyte-scale capacity with 99.9% availability SLAs and optimized $/TB metrics. Demand concentrates in the United States, where Google Cloud and Oracle Cloud Infrastructure expand regional availability zones.
- Video Streaming:Content delivery networks ingest petabyte-scale daily uploads with sequential write patterns matching SMR operational characteristics. Netflix and Disney+ infrastructure in Germany and France drives 20 TB nearline adoption for cold content tiers.
- Data Archiving:Compliance retention policies favor write-once read-occasionally economics over tape library latency trade-offs.
- Backup Solutions:Deduplication appliances and disaster recovery targets sustain demand for 12-16 TB air-filled platforms.
- Content Delivery Networks:Edge caching nodes balance capacity against power constraints in distributed PoP architectures.
Cloud Computing commands the highest absolute volumes, with Video Streaming gaining share fastest as short-form content proliferation accelerates storage ingestion rates.
End User:
Direct procurement consolidation bypasses traditional distribution channels for annual volumes exceeding 10 million units.
- Data Centers:Hyperscale operators with captive infrastructure engineering teams negotiate multi-year supply agreements with foundry-level pricing transparency. Concentration in the United States and China produces geographic demand bifurcation around FCC equipment authorization and GB standards compliance requirements.
- IT Service Providers:Managed service and colocation intermediaries aggregate fragmented enterprise demand through value-added reseller channels with extended EPEAT Gold certification timelines.
- Media Production Houses:4K/8K post-production workflows generate high-capacity nearline demand for active project archives.
- Research Institutes:Scientific computing and genomic data repositories sustain specialized procurement for petabyte-scale datasets.
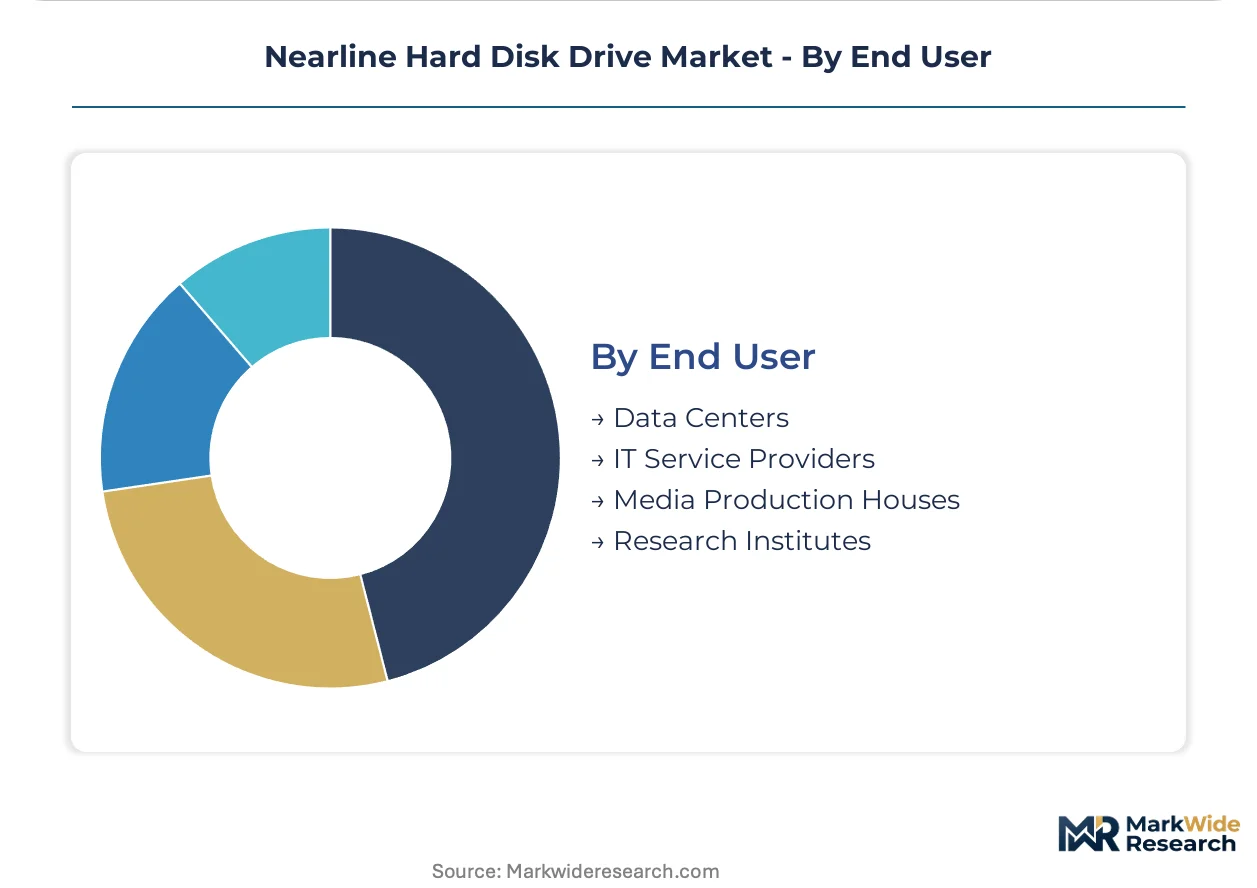
Data Centers dominate procurement volumes, with IT Service Providers expanding most quickly as mid-market cloud migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The nearline hard disk drive industry traces its mass manufacturing lineage to the United States, where IBM pioneered magnetic storage technologies in San Jose during the 1950s before production gravity shifted toward Asia-Pacific assembly corridors. Today, demand concentrates in three distinct geographies governed by divergent regulatory frameworks and data localization imperatives.
United States
Hyperscale cloud operators in Northern Virginia and Oregon's Columbia River corridor consume 20 TB and 24 TB HAMR drives for exabyte-scale object storage backends. FCC equipment authorization requirements govern market access for all imported storage hardware. Microsoft's Azure expansion in Phoenix and Meta's Prineville facilities anchor Pacific Northwest procurement concentration.
China
ByteDance and Tencent drive 16 TB helium-sealed platform demand for video streaming infrastructure under the country's GB standards for electronic product environmental compliance. MIIT dual carbon goals accelerate liquid-cooled rack adoption in Yangtze River Delta facilities. Alibaba Cloud's Zhangjiakou campus anchors northern hyperscale deployment.
Germany
EU F-Gas Regulation thermal mandates redirect Frankfurt and Berlin data center capital toward liquid-cooled architectures favoring high-density nearline configurations. ECHA REACH substance restrictions tighten cobalt compound documentation for printed circuit board laminates. Hesse's Rhine-Main cluster hosts Deutsche Telekom and SAP cloud infrastructure expansion.
Japan
METI industrial policy supports domestic HDD component manufacturing for precision spindle motor and head stack assembly. JIS standards compliance underpins enterprise storage procurement by financial services and automotive sectors. Tokyo-Osaka corridor facilities supply regional cloud providers with 18 TB and 20 TB platforms.
India
Digital India infrastructure program and state-level data localization mandates generate greenfield demand for 500+ megawatt facilities requiring 12-16 TB entry-level nearline tiers. BIS certification requirements govern imported storage hardware market access. Maharashtra's Mumbai-Pune corridor anchors initial hyperscale buildout.
Nearline Hard Disk Drive Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a consolidated three-player structure where captive wafer fabrication and helium supply chains determine cost position. Seagate Technology, Western Digital Corporation, and Toshiba Corporation command the nearline HDD segment through distinct technology specializations. Strategic archetypes separate helium-sealed platform specialists from areal density innovators and vertically integrated manufacturing operators. Competitive moves concentrate on multi-year supply agreements with hyperscale direct procurement teams and foundry-level pricing transparency negotiations.
Within the vertically integrated manufacturing tier, Seagate Technology exemplifies cost leadership through captive Thailand and Minnesota production assets. Western Digital Corporation occupies a position as helium-sealed platform specialist, while Toshiba Corporation anchors the areal density innovation vector for cloud storage segments. These three manufacturers collectively negotiate foundry-level agreements with Amazon Web Services, Microsoft Azure, and Google Cloud procurement teams that bypass traditional distribution channels entirely.
| Leading Market Players |
|---|
| Seagate Technology |
| Western Digital Corporation |
| Toshiba Corporation |
| Hitachi Global Storage Technologies |
| HGST |
| Fujitsu |
| Samsung Electronics |
| Dell Technologies |
| Lenovo |
| Others |
Pricing and Supply Chain Analysis
Atomic-scale plasma etching specialists concentrated in Northern California and Hokkaido command wage premiums that widen spreads between premium HAMR-qualified drives and standard helium-sealed tiers, compressing mid-market margins as cloud direct procurement consolidates volume leverage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and volume scale. Premium tiers capture HAMR-enabled 24 TB platforms with EPEAT Gold documentation and direct hyperscale contracting, while economy tiers serve air-filled 8-12 TB drives through distributor channels. Price differentiation hinges on areal density tier and thermal design integration, with hyperscale buyers extracting steepest discounts. Cost compression in standard helium-sealed tiers is intensifying because ByteDance and Tencent consolidate 16 TB procurement into multi-year agreements, squeezing traditional enterprise resellers.
Supply Chain Analysis
Workforce availability for precision head-stack assembly constrains expansion in Thailand, Minnesota, and the Philippines, where cleanroom technician pipelines feed captive fabrication. Manufacturing draws from rare earth concentrate streams subject to China's export licensing regime, helium purification from Qatar and Algeria, and silicon wafer substrates from Japan and Taiwan. Single-source vulnerability concentrates in neodymium magnet motor assemblies, with 80% of refined output controlled through state-level allocation. Distribution runs through direct procurement channels for hyperscale volumes exceeding 10 million units annually, bypassing legacy value-added reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nearline HDD market reads as a late-cycle quality story where hyperscale buyers are paying premiums for HAMR-qualified densities and liquid-cooled thermal integration, shifting procurement away from commodity air-filled tiers.
For Market Incumbents: Anticipate QLC NAND encroachment below 10 TB by accelerating HAMR and MAMR roadmaps toward 30 TB archival densities, while locking helium supply through captive offtake agreements with Qatar and Algeria to insulate against rare earth magnet volatility. Defensive consolidation around wafer fabrication in Thailand and Minnesota preserves cost position against margin compression in standard tiers. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and the Netherlands opens a window for liquid-cooled chassis integration specialists who can bundle thermally optimized nearline configurations with clean energy tax credit documentation. White-space targets cluster in India's 500+ megawatt greenfield facilities and mid-tier European colocation providers lagging hyperscale refresh cycles. A direct-to-hyperscale engineering services model bypasses channel margin extraction. For Investors and Strategic Acquirers: Valuations sit cheapest among component-level specialists with atomic-scale deposition expertise and captive cleanroom assets, as capital intensity and talent scarcity erect barriers against commoditization. Long-term viability hinges on energy-assisted recording convergence and archival-tier displacement of tape libraries. The signal to watch is Microsoft Azure and Amazon Web Services qualification timelines for 30 TB HAMR platforms, which would compress tape-to-disk TCO gaps and re-rate density-leader equity.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Assisted Magnetic Recording Scale-Up | Microsoft Azure qualification of 24 TB HAMR drives validates laser-thermal writing for hyperscale deployment. |
| Helium Supply Captive Integration | Qatar and Algeria offtake agreements insulate motor assembly costs against rare earth concentrate volatility. |
| Liquid-Cooled Chassis Development | German data center operators under EU F-Gas Regulation mandate thermal optimization for rack density gains. |
| Direct Procurement Channel Compression | Amazon Web Services and Google Cloud bypass distributors for foundry-level pricing transparency on 10M+ unit volumes. |
| EPEAT Gold Certification Acceleration | Conflict mineral documentation timelines delay hyperscale approvals, favoring early compliance investments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hyperscale procurement officers, data center engineering directors, HDD manufacturing operations leads, and rare earth supply chain specialists with secondary validation against SEC 10-K filings, hyperscaler capex disclosures, and customs trade data. Bottom-up shipment aggregation by capacity tier and application cross-checked against top-down TAM modeling.
Comparable historical periods anchored volume and value projections across the analysis window, with segmentation dimensions spanning product type, capacity tier, application workload intensity, and thermal design requirement. CAGRs derived from elasticity modeling against cloud infrastructure investment cycles and areal density roadmap milestones, incorporating energy-assisted recording adoption curves and EU thermal regulation compliance timelines as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under neodymium export license restrictions or accelerated QLC NAND price erosion. Forecasts reflect documented assumptions around hyperscale refresh cycle compression and HAMR qualification velocity. Material deviation in cloud provider capital allocation or energy-assisted recording yield rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Blu-Ray Optical Disk Market
Data Storage
Data Storage Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Enterprise Hard Drive Market
Data Storage
Flash Memory Market
Data Storage
Optical Disk Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
OTG Pen Drive Market
Data Storage
Distributed Storage System Market
Data Storage
Hardware Storage Market
Data Storage
Asia Pacific Transparent Caching Market
Data Storage
North America SSD Caching Market
Data Storage
Europe Next Generation Storage Market
Data Storage
Transparent Caching Market