
 Public Safety in-Building Wireless Distributed Antenna System (DAS) Market | 2026-2036
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market Size, Share, and Industry Trends Forecast 2026-2036
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market Analytics
Healthcare facilities are reorganizing their procurement priorities around public safety DAS as hospital accreditation standards tighten emergency communication requirements. CommScope leverages its broadband infrastructure portfolio to extend into integrated public safety solutions for large campuses. Corning Incorporated anchors its position through optical fiber backbones that reduce signal loss in multi-building deployments. Ericsson competes on radio access network convergence, positioning 5G NR and legacy public safety bands within unified hardware platforms.
Public Safety in-Building Wireless Distributed Antenna Systems are radio frequency distribution networks comprising head-end equipment, coaxial or fiber-optic cabling, and remote antenna units that amplify and propagate 700 MHz and 800 MHz public safety signals throughout structures with minimum -95 dBm coverage thresholds. These systems ensure uninterrupted two-way radio communication for police, fire, and emergency medical personnel inside buildings where exterior signals cannot penetrate. Active DAS dominates in structures exceeding 500,000 square feet where fiber-optic transport overcomes coaxial distance limitations. Hybrid DAS is gaining fastest in mid-rise commercial buildings that balance cost constraints with multi-carrier support requirements. Small Cells occupy a niche at the premium edge, serving venues where capacity augmentation must coexist with public safety mandate compliance.
The National Fire Protection Association's NFPA 1221 standard and the International Fire Code's Section 510 shape product design by specifying 99% area coverage and 95% elevator and stairwell penetration requirements across jurisdictions. The Federal Communications Commission's Part 90 licensing framework governs spectrum allocation for public safety bands, while local Authority Having Jurisdiction officials enforce installation certification before occupancy permits issue. Stakeholders must monitor evolving FirstNet band plans and building electrification codes that may redefine backup power requirements for in-building systems.
Market Dynamics
FirstNet band expansion is compressing deployment timelines as public safety agencies demand unified LTE and LMR coverage from single infrastructure investments, forcing DAS vendors to re-architect head-end equipment for multi-band convergence.
Growth Catalysts
- NFPA 1221 coverage mandates:United States jurisdictions now require 99% in-building radio coverage for occupancy permits, accelerating retrofit demand in legacy commercial structures.
- Healthcare emergency accreditation:Joint Commission standards for hospital emergency preparedness now explicitly reference redundant communication pathways, driving DAS procurement in acute care facilities.
- 700 MHz narrowbanding completion:FCC-mandated spectrum reconfiguration has standardized public safety radio frequencies, simplifying multi-jurisdictional system design and reducing equipment fragmentation.
Market Restraints
- Optical fiber cost volatility:Remote antenna unit deployment depends on fiber transport infrastructure, with pricing fluctuations in Corning-grade single-mode cable compressing margins on fixed-bid municipal contracts.
- Licensed integrator concentration:California, Texas, and Florida each maintain fewer than twelve FCC-certified in-building radio system contractors, creating bottlenecks for simultaneous multi-site rollouts.
- Active DAS power requirements:NFPA 72 standby power mandates for 24-hour battery backup add substantial electrical infrastructure costs that passive systems avoid.
Strategic Opportunities
- FirstNet Band 14 integration:AT&T's nationwide public safety broadband network creates demand for hybrid DAS architectures supporting both 700 MHz LMR and 700 MHz LTE on common antenna infrastructure.
- Mid-rise commercial underpenetration:Structures between 100,000 and 500,000 square feet in Florida remain below 40% DAS penetration despite IFC 510 adoption, representing white space for cost-optimized hybrid systems.
- Building electrification code alignment:California's Title 24 energy standards are creating bundled procurement opportunities where DAS backup power integrates with EV charging infrastructure and solar storage.
Industry Challenges
- BICSI RTP certification scarcity:Registered Telecommunications Project Managers with public safety DAS specialization number fewer than 800 nationwide, constraining project management capacity for complex multi-building campuses.
- AHJ interpretation variance:Authority Having Jurisdiction officials in Texas apply IFC 510 elevator coverage requirements inconsistently, forcing redesign cycles and permitting delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Safety in-Building Wireless Distributed Antenna System (DAS) Market |
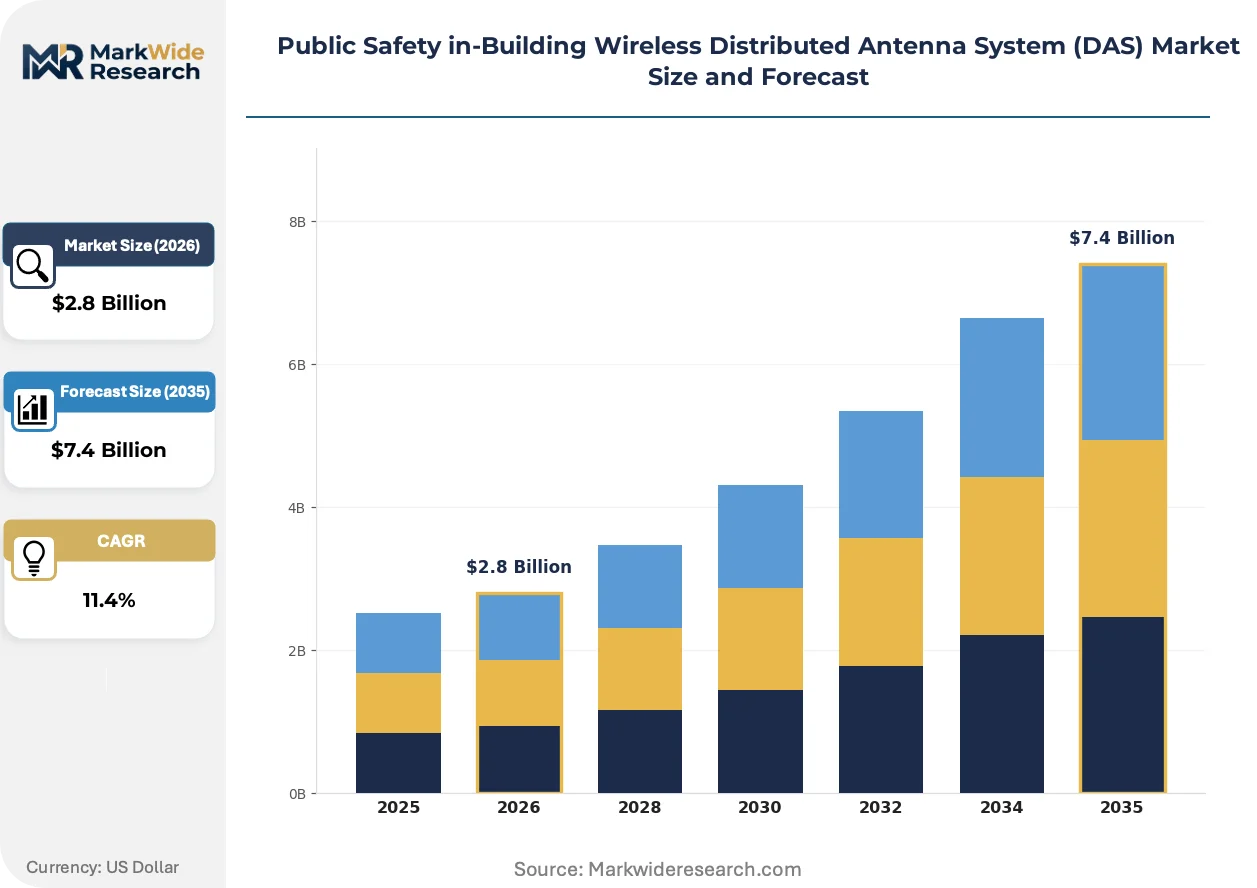
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active DAS, Passive DAS, Hybrid DAS, Small Cells Installation Type: Indoor, Outdoor, Temporary, Permanent End User: Commercial Buildings, Educational Institutions, Healthcare Facilities, Industrial Sites Technology: 4G LTE, 5G NR, Wi-Fi, Legacy Systems |
| Companies Covered | CommScope, Corning Incorporated, Ericsson, Verizon Communications, AT&T, SOLiD, Cobham, TE Connectivity, JMA Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market Evolving Landscape
Software-defined radio architectures are fragmenting the traditional hardware-centric DAS value chain, enabling remote reconfiguration of frequency bands without physical equipment swaps and compressing upgrade cycles from years to months.
Virtualized baseband processing is decomposing the traditional head-end equipment stack, allowing hospital networks and university campuses to host signal processing on standard IT infrastructure rather than proprietary RF hardware. Texas Medical Center members in Houston are piloting this architecture to consolidate public safety and cellular DAS management under common network operations centers. The shift is decomposing vendor lock-in by enabling multi-manufacturer remote antenna unit interoperability.
California's Office of the State Fire Marshal has issued technical bulletins clarifying NFPA 1221 application to existing buildings undergoing major renovation, triggering wave of pre-emptive DAS installation ahead of formal code adoption cycles. The interpretation extends coverage mandates to structures previously exempt under grandfathering provisions. Healthcare REITs with California portfolios are accelerating capital planning to front-run enforcement.
Consolidated facility management procurement is displacing siloed telecommunications contracting, with Texas-based property groups bundling DAS design, installation, and maintenance into multi-year service agreements with single accountability. The model transfers certification liability from building owners to integrators. Florida's largest retail mall operators have adopted this structure for portfolio-wide compliance management.
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market Segmentation
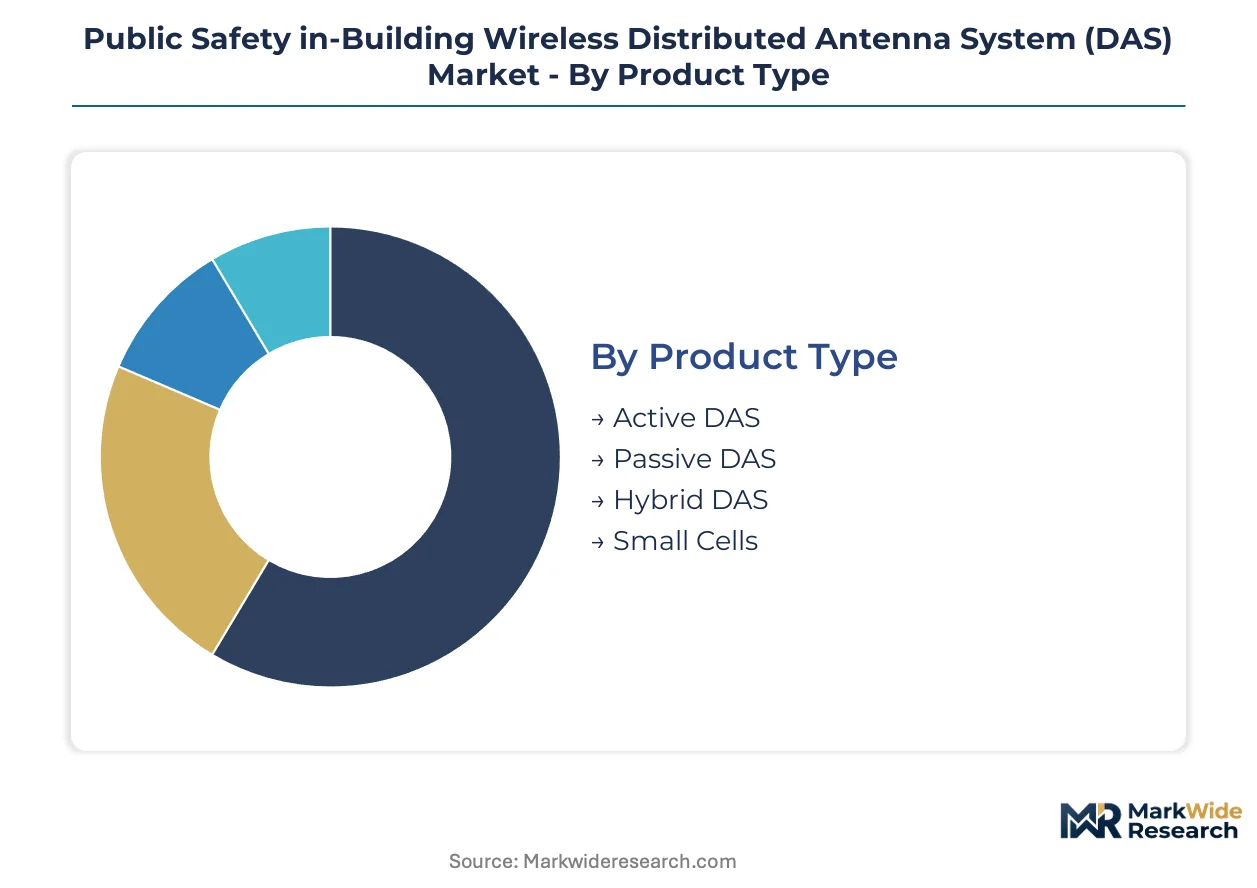
Public safety DAS procurement varies sharply by building typology and infrastructure maturity. Product selection hinges on square footage thresholds, while end-user verticals face distinct code enforcement timelines and budget cycles.
Product Type:
Active DAS faces substitution pressure from hybrid architectures in mid-rise commercial buildings where fiber-to-the-edge costs prove prohibitive.
- Active DAS:Fiber-optic transport infrastructure feeds remote antenna units with digitized RF signals, eliminating coaxial distance limitations. Demand concentrates in Texas healthcare campuses exceeding 500,000 square feet where NFPA 1221 mandates 99% coverage across sprawling structures.
- Passive DAS:Coaxial cable distribution with bi-directional amplifiers propagates signals without active electronics in the RF path. California school districts favor this architecture for budget-constrained retrofit projects under Title 24 energy compliance deadlines.
- Hybrid DAS:Combines fiber backbone transport with passive coaxial distribution to remote units, balancing performance against installation complexity.
- Small Cells:Compact base stations with integrated antennas serve discrete coverage zones for venues requiring capacity augmentation alongside public safety mandate compliance.
Active DAS retains volume leadership; Hybrid DAS holds the steepest expansion curve.
Installation Type:
Permanent installations dominate capital planning, though temporary deployments gain traction in disaster response infrastructure.
- Indoor:In-building antenna distribution ensures first responder radio penetration through concrete, steel, and low-E glass. Florida hospital construction mandates indoor DAS prior to occupancy permit issuance under IFC 510.
- Outdoor:Campus-wide coverage extends public safety communications across parking structures, loading docks, and pedestrian corridors. Texas medical center expansions require outdoor DAS for ambulance bay and helipad communication continuity.
- Temporary:Rapid-deploy systems serve emergency operations centers and field hospitals during wildfire or hurricane events.
- Permanent:Hardened infrastructure with 24-hour battery backup meets NFPA 72 standby power requirements for certified installations.
Permanent installations anchor revenue; Temporary deployments are expanding most quickly in disaster-prone jurisdictions.
End User:
Healthcare facilities command premium pricing due to Joint Commission accreditation requirements that specify redundant communication pathways.
- Commercial Buildings:Office towers and retail complexes face retrofit pressure as grandfathering exemptions expire under California Office of the State Fire Marshal technical bulletins.
- Educational Institutions:K-12 campuses and university systems balance bond-funded new construction against deferred maintenance backlogs for legacy buildings.
- Healthcare Facilities:Acute care hospitals and outpatient surgical centers require 99% coverage with 95% elevator and stairwell penetration. California healthcare REITs accelerate capital planning to front-run enforcement of NFPA 1221 on renovation-triggered mandates.
- Industrial Sites:Manufacturing plants and petrochemical facilities contend with hazardous area classifications that constrain antenna placement and cable routing.
Healthcare Facilities command the highest specification tiers; Commercial Buildings offer the deepest retrofit backlog.
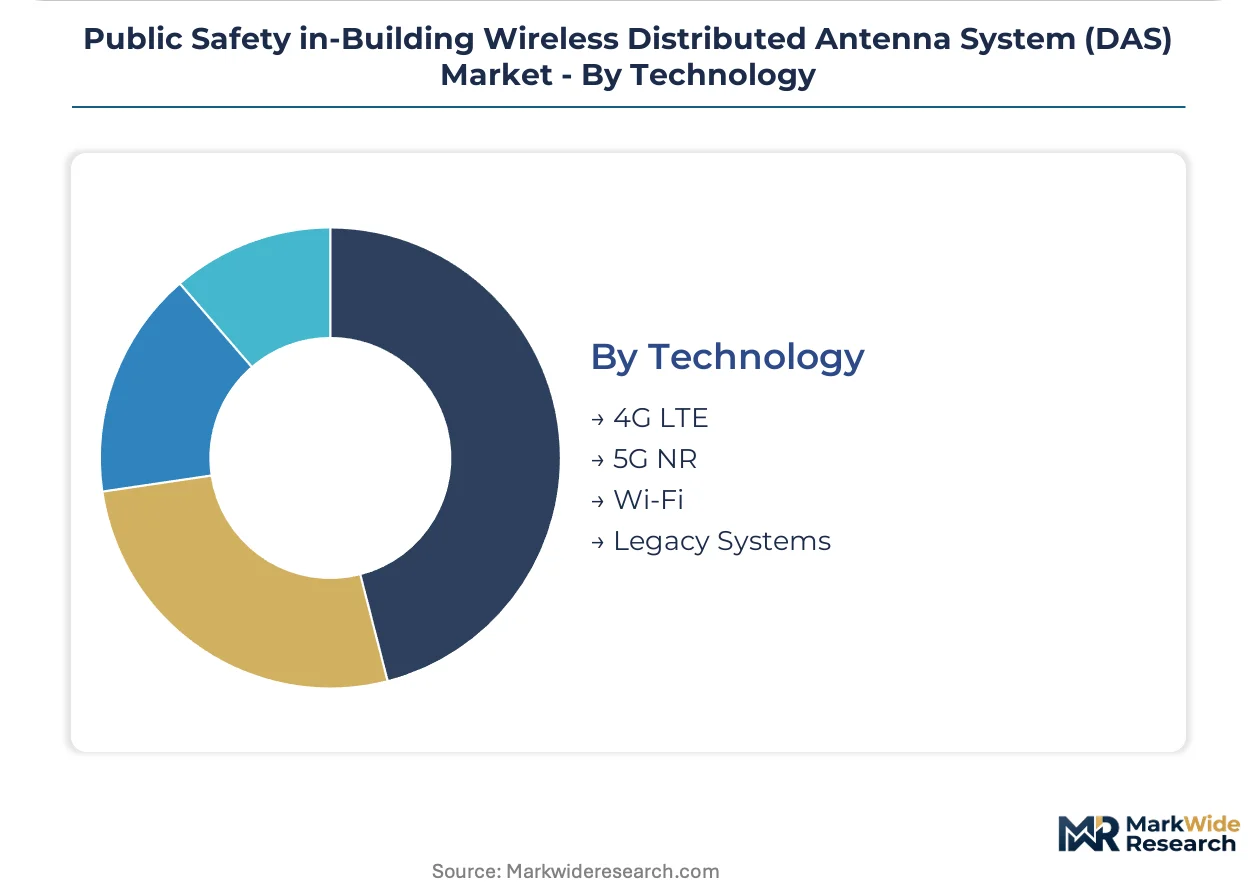
Technology:
5G NR integration is compressing equipment refresh cycles as FirstNet Band 14 deployment accelerates multi-band convergence requirements.
- 4G LTE:FirstNet public safety broadband network operates on 700 MHz Band 14, requiring compatible head-end equipment and antenna infrastructure.
- 5G NR:New radio interfaces support enhanced mission-critical push-to-talk and video streaming for emergency responders. Texas Medical Center pilots virtualized baseband processing to consolidate 5G NR and legacy LMR management.
- Wi-Fi:Unlicensed spectrum complements but does not substitute for licensed public safety bands in code-compliant installations.
- Legacy Systems:700 MHz and 800 MHz narrowband LMR remains mandatory for backward compatibility with existing fire and police radio fleets.
Legacy Systems retain installed base dominance; 5G NR is gaining share fastest through FirstNet-mandated upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States DAS vendors export turnkey public safety systems to Canada and Mexico under USMCA procurement frameworks, with cross-border installation crews mobilizing for Toronto healthcare campuses and Monterrey industrial parks.
United States
California healthcare REITs and Texas medical centers drive procurement volume as Joint Commission accreditation tightens emergency communication standards. The FCC's Part 90 licensing framework governs 700 MHz and 800 MHz spectrum allocation for first responder bands. Houston's Texas Medical Center pilots virtualized baseband processing to consolidate public safety and cellular DAS management under unified network operations.
Canada
Municipal fire departments in Ontario and British Columbia accelerate retrofit mandates for legacy commercial structures exceeding 100,000 square feet. Health Canada's national building code harmonization pushes provinces toward NFPA 1221-equivalent coverage standards. Toronto's hospital construction pipeline requires indoor DAS certification prior to occupancy permit issuance under provincial fire safety regulations.
Germany
Industrial facility operators in North Rhine-Westphalia demand hazardous-area-certified DAS for petrochemical and manufacturing sites. The country's national telecommunications regulator enforces CE marking and EMC compliance for in-building radio infrastructure. Düsseldorf's corporate campus developments integrate public safety DAS with Building Information Modeling workflows to compress commissioning timelines.
United Kingdom
London's commercial real estate sector faces retrofit pressure as the Building Safety Regulator extends emergency communication requirements to existing high-rise structures. The country's national building standards body references ETSI harmonized standards for critical communications coverage. The Canary Wharf financial district mandates redundant radio pathways for trading floor continuity during civil emergencies.
Australia
Sydney and Melbourne hospital networks expand DAS deployment as state health departments specify 99% coverage for emergency preparedness accreditation. The country's national communications authority manages spectrum licensing for public safety mobile broadband. Perth's mining headquarters buildings adopt hybrid DAS architectures to support both legacy LMR and LTE-based mission-critical communications.
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market Competitive Landscape
Player mix skews toward diversified telecommunications infrastructure suppliers with RF engineering heritage. Market structure concentrates around vendors possessing integrated fiber-optic transport capabilities and FCC-certified installation partnerships. Three archetypes dominate: broadband infrastructure conglomerates extending into public safety verticals, optical fiber specialists leveraging backbone expertise for signal distribution, and radio access network vendors converging legacy and 5G NR platforms. Competitive moves center on multi-band head-end equipment re-architecture and virtualized baseband processing partnerships with hospital network operators.
Within the infrastructure conglomerate tier, CommScope and Corning Incorporated exemplify players anchoring positions through integrated fiber-cable-antenna portfolios. Ericsson occupies a position on the network convergence vector, representing vendors unifying 5G NR and legacy public safety bands within common hardware platforms. These three entities sit within a competitive set where differentiation hinges on fiber transport depth, software-defined reconfiguration capabilities, and Authority Having Jurisdiction certification relationships across California, Texas, and Florida enforcement zones.
| Leading Market Players |
|---|
| CommScope |
| Corning Incorporated |
| Ericsson |
| Verizon Communications |
| AT&T |
| SOLiD |
| Cobham |
| TE Connectivity |
| JMA Wireless |
| Others |
Value Network & Pricing Analysis
FCC-certified integrator scarcity gates both vendor qualification and project pricing tiers simultaneously, concentrating margin capture among the twelve licensed contractors serving California, Texas, and Florida while forcing building owners toward multi-year service agreements that bundle certification liability.
Pricing Analysis
Legacy 700 MHz LMR infrastructure commands 40-60% price premiums over next-generation 5G NR-ready head-end equipment as hospitals prioritize backward compatibility with existing fire and police radio fleets. Three-tier pricing structure across premium active DAS, standard hybrid architectures, and economy passive systems tracks fiber transport depth and AHJ certification bundling. Cost compression in mid-rise commercial segments is intensifying because hybrid DAS vendors are racing to capture the 100,000-500,000 square foot white space in Florida. Municipal buyers exhibit highest price sensitivity due to fixed-bid contracting constraints, while healthcare REITs demonstrate lowest sensitivity as Joint Commission accreditation deadlines override procurement cost optimization.
Supply Chain Analysis
Corning-grade single-mode fiber availability from domestic manufacturing plants in North Carolina and South Carolina represents a critical chokepoint for active DAS deployment timelines across large healthcare campuses. Remote antenna unit production draws from optical fiber backbones, gallium nitride RF components, and lithium-ion battery backup systems. Single-source vulnerability concentrates in specialized BICSI RTP-certified project management capacity, with fewer than 800 qualified managers nationwide. Distribution runs through FCC-certified installation partnerships rather than open channel sales, tying equipment procurement to integrator relationships in each Authority Having Jurisdiction zone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of BICSI RTP-certified project managers with public safety DAS specialization constrains deployment velocity and creates asymmetric returns for stakeholders who can secure or develop this scarce credential.
For Market Incumbents: Shield market position by acquiring FCC-certified installation partnerships in California, Texas, and Florida before AHJ bottlenecks worsen, while simultaneously investing in virtualized baseband processing R&D to reduce hardware refresh cycle dependency. Software-defined radio architectures threaten traditional equipment-centric revenue streams. For New Entrants and Emerging Players: BICSI RTP certification fast-track programs unlock mid-rise commercial buildings in Florida, where IFC 510 enforcement has outpaced integrator supply and structures between 100,000-500,000 square feet remain below 40% penetrated. Target this segment with cost-optimized hybrid DAS bundled into multi-year facility management contracts that transfer certification liability from building owners. For Investors and Strategic Acquirers: FirstNet Band 14 nationwide deployment completion reshapes the acquisition landscape by privileging vendors with proven LTE-LMR convergence architectures over legacy LMR-only players. Long-term viability centers on multi-band head-end equipment capabilities. Acquisition targets should demonstrate virtualized baseband processing partnerships with hospital network operators. Monitor AT&T's FirstNet coverage expansion announcements as the primary inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FirstNet Band 14 Integration | AT&T's public safety broadband network mandates unified LTE-LMR hardware platforms across new installations. |
| Virtualized Baseband Processing Partnership | Texas Medical Center pilots consolidate public safety and cellular DAS management under common network operations centers. |
| BICSI RTP Certification Acquisition | Scarce project management credentials unlock complex multi-building campus deployments in enforcement-heavy jurisdictions. |
| Hybrid DAS Architecture Development | Florida's mid-rise commercial white space demands cost-optimized systems balancing fiber performance with passive distribution economics. |
| Multi-Year Service Agreement Structuring | Texas property groups transfer NFPA 1221 certification liability from building owners to integrators through bundled procurement. |
Research Methodology
Operator-level perspectives from DAS integration firm principals, hospital facility managers, Authority Having Jurisdiction fire marshals, and telecommunications procurement officers anchored the qualitative base. Primary interviews combined with secondary validation against FCC Part 90 licensing databases, NFPA 1221 technical bulletins, and municipal building permit records. Bottom-up project pipeline analysis triangulated against top-down market sizing from equipment vendor shipment disclosures.
Sensitivity analysis tested forecast robustness across alternative scenarios for FirstNet deployment pacing, fiber cost volatility, and AHJ enforcement intensity. Segmentation modeling spanned product architecture, installation permanence, end-user vertical, and technology generation dimensions throughout the forecast period. CAGRs derived from weighted average of historical deployment trajectories and code-mandated retrofit acceleration curves, with specific adjustment for California healthcare REIT capital planning front-running behavior.
Decision-makers should treat outputs as directional under base assumptions of sustained NFPA 1221 enforcement and stable FirstNet band plans; material deviation in AHJ interpretation consistency or building electrification code alignment would warrant model refresh. Practitioners should keep alternative scenarios live as optical fiber pricing and BICSI RTP certification throughput evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Asia-Pacific Public Safety Market
Public Safety
Europe Public Infrastructure Safety Market
Public Safety
Public Safety LTE Market
Public Safety
Middle East Crime and Combat Market
Public Safety
US Mass Notification Systems Market
Public Safety
Public Safety Drones Market
Public Safety
Global Public Safety Solution for Smart City Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Public Safety Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Global Public Safety and Security Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market
Public Safety
North America Road Safety Market
Public Safety
AI for Public Security and Safety Market
Public Safety
Global Public Safety Analytics Market