
 GCC Firefighting Foam Market | 2026-2036
GCC Firefighting Foam Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Firefighting Foam Market Insights
EU REACH restrictions on per- and polyfluoroalkyl substances is realigning procurement criteria across GCC petrochemical operators. Johnson Controls leverages its integrated fire protection platform to anchor long-term service contracts with Saudi Aramco-affiliated facilities. NAFFCO competes aggressively on Civil Defence pre-approval breadth across Emirates and Qatar. Angus Fire specializes in fluoroprotein formulations for marine tanker protection, sustaining premium positioning in Kuwaiti and Bahraini ports.
Firefighting foam comprises synthetic or protein-based surfactant solutions that generate stable, low-expansion bubbles for suppressing flammable liquid fires through oxygen exclusion and fuel vapor suppression. Aqueous film-forming foam dominates volume flows into airport crash rescue operations across Dubai International and King Khalid International, though fluorine-free alternatives are gaining specification share under emerging environmental mandates. Oil refineries represent the deepest margin pool, with industrial facilities driving fastest volume growth as Saudi Vision 2030 manufacturing zones expand fire safety infrastructure requirements.
Saudi Standards, Metrology and Quality Organization (SASO) and UAE Civil Defence now enforce updated foam performance benchmarks that reference NFPA 11 and EN 1568 testing protocols, effectively filtering non-compliant imports from Asian suppliers. The Saudi General Authority for Civil Defence mandates third-party certification for all foam concentrates deployed in hydrocarbon facilities, tightening market access for unverified products. Stakeholders must monitor the trajectory of Gulf Cooperation Council harmonized chemical regulations, as unified PFAS restrictions would reshape formulation R&D priorities and supplier qualification timelines across all six member states.
Market Dynamics
EU REACH restrictions on per- and polyfluoroalkyl substances are forcing GCC petrochemical operators to realign procurement criteria toward fluorine-free foam concentrates. This regulatory pressure from European markets is cascading into Gulf supply chains through multinational operator standards and export compliance requirements.
Growth Catalysts
- SASO Certification Mandates:Saudi Standards, Metrology and Quality Organization now enforces updated foam performance benchmarks referencing NFPA 11 and EN 1568 testing protocols. This filters non-compliant imports and elevates verified domestic and regional suppliers.
- Fluorine-Free Formulation Advances:Protein-based and synthetic surfactant solutions are achieving hydrocarbon fire suppression parity with legacy AFFF chemistries. Oil refineries across the Eastern Province industrial corridor are expanding procurement of these alternatives.
- Saudi Vision 2030 Manufacturing Zones:New industrial cities under the economic transformation program mandate comprehensive fire safety infrastructure. This creates sustained demand for foam concentrate deployment across greenfield petrochemical and manufacturing facilities.
Market Restraints
- Fluoroprotein Input Cost Volatility:Specialized protein hydrolysates and fluorinated surfactant precursors face supply concentration from limited European and North American chemical manufacturers. Price swings compress margin predictability for formulation blenders.
- Third-Party Certification Bottlenecks:The Saudi General Authority for Civil Defence mandates independent verification for all foam concentrates deployed in hydrocarbon facilities. Testing capacity constraints at accredited laboratories extend supplier qualification timelines.
- AFFF Stockpile Inertia:Existing inventories of aqueous film-forming foam at major airport and marine facilities create substitution friction. Capital recovery cycles and disposal regulations delay fluorine-free conversion despite environmental mandates.
Strategic Opportunities
- Qatar Industrial Expansion:North Field gas development and downstream petrochemical projects are constructing new fire protection infrastructure. Early supplier qualification with Qatar Civil Defence creates entrenched positions before capacity comes online.
- Service Contract Unbundling:Integrated fire protection platforms are separating foam concentrate supply from system maintenance and testing services. This creates standalone chemical procurement opportunities for specialized formulation suppliers.
- Kuwaiti Port Modernization:Marine tanker protection standards at Mina Al-Ahmadi and Shuwaikh terminals are tightening under environmental compliance frameworks. Fluoroprotein specialists can anchor premium positioning in this specification-driven segment.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in surfactant chemistry for fire suppression applications concentrates among aging specialists in Europe and North America. GCC-based manufacturers face recruitment friction for R&D and quality control functions.
- Legacy System Integration Complexity:Fluorine-free concentrates require proportioner recalibration and storage tank cleaning during conversion. Facility downtime costs deter rapid AFFF replacement even where regulations permit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Firefighting Foam Market |
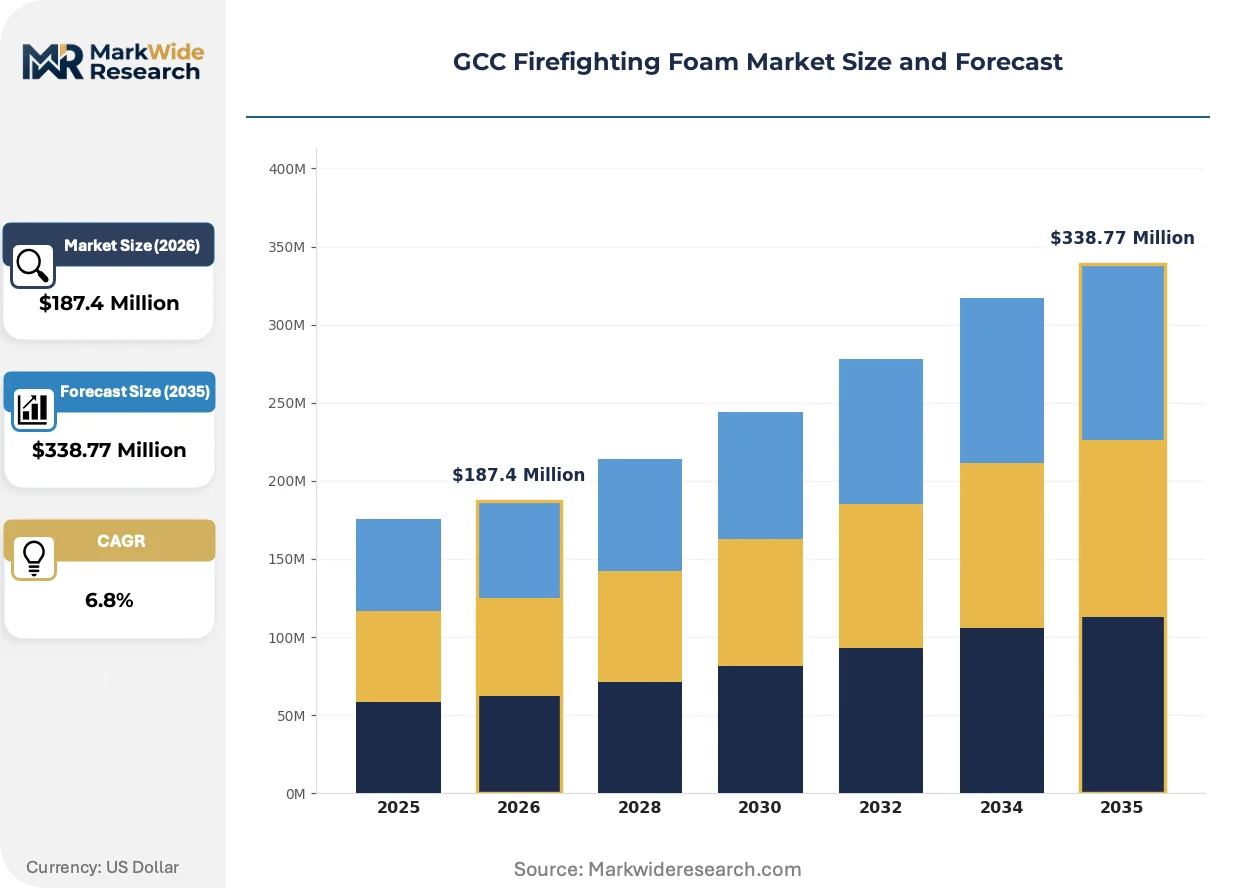
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Film-Forming Foam, Alcohol-Resistant Foam, Protein Foam, Film-Forming Fluoroprotein Foam Application: Oil Refineries, Industrial Facilities, Airports, Marine Applications End User: Fire Departments, Military, Industrial Users, Commercial Users Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Stores |
| Companies Covered | SFFECO Global, FIREX, NAFFCO, Johnson Controls, National Foam, Angus Fire, Buckeye Fire Equipment Company, Dafo Fomtec AB, Albilad Fighting Systems Ltd, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Firefighting Foam Market Trends and Innovations
Formulation chemistry is fragmenting as environmental compliance pressures collide with performance requirements. Suppliers are engineering modular surfactant platforms that can be tuned to specific fuel types and application methods.
Fluorine-free foam concentrate technology is modularizing around interchangeable surfactant packages. Oil refineries in Saudi Arabia's Eastern Province are piloting these platforms for gasoline, diesel, and crude storage applications. The approach enables rapid reformulation without full product requalification, compressing R&D cycles for regional blenders.
UAE Civil Defence certification requirements for environmentally compliant foams are tightening product standards through reference to EN 1568 testing protocols. This elevates performance benchmarks for low-expansion foam concentrates in aviation and marine applications. Airport crash rescue operations at Dubai International are responding by specifying pre-approved concentrate lists in procurement tenders.
Buying patterns are consolidating around Civil Defence pre-approval breadth as a primary selection criterion. Facility operators are displacing fragmented multi-supplier arrangements with single-source contracts covering concentrate supply, equipment compatibility verification, and annual recertification support. This concentration is most visible among Emirates-based petrochemical terminal operators managing multi-site portfolios.
GCC Firefighting Foam Market Segmentation
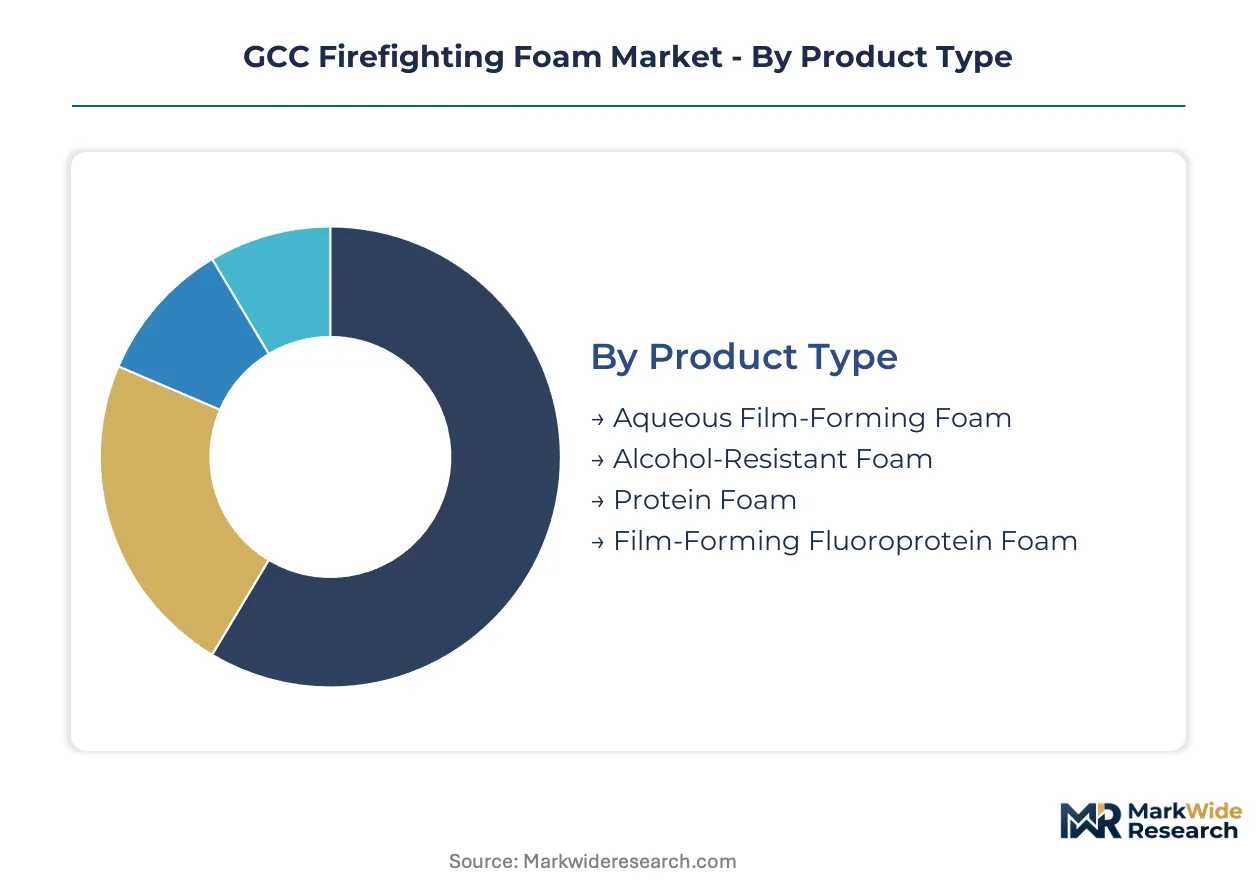
Firefighting foam procurement across the Gulf Cooperation Council diverges sharply by hazard type and regulatory jurisdiction. Product chemistry, application environment, and certification requirements create distinct purchasing workflows that suppliers must navigate separately.
Product Type:
Aqueous film-forming foam commands volume share while fluorine-free alternatives capture expanding specification share at premium price points.
- Aqueous Film-Forming Foam:Synthetic surfactant solutions form a vapor-sealing film on hydrocarbon surfaces. King Khalid International and Dubai International airports maintain substantial AFFF inventories for aircraft rescue firefighting, though SASO and UAE Civil Defence environmental mandates are accelerating substitution timelines.
- Alcohol-Resistant Foam:Polymer-thickened formulations suppress polar solvent fires through a cohesive polymer barrier. Petrochemical terminals at Jubail Industrial City specify these concentrates for ethanol and methanol storage protection, with procurement rising alongside Saudi Vision 2030 downstream chemical investments.
- Protein Foam:Hydrolyzed protein surfactants derived from animal byproducts provide heat-resistant foam blankets for crude oil storage.
- Film-Forming Fluoroprotein Foam:Hybrid chemistry combining fluorinated surfactants with protein hydrolysates delivers extended drain times on deep fuel fires.
Today's leader: Aqueous film-forming foam. Tomorrow's challenger: Protein foam.
Application:
Industrial concentration in Saudi Arabia's Eastern Province drives disproportionate revenue capture, with aviation and marine segments exhibiting tighter specification compliance requirements.
- Oil Refineries:Hydrocarbon processing facilities at Ras Tanura and Yanbu generate the deepest margin pool through bulk concentrate procurement and integrated fire protection system contracts. SASO certification mandates and fluorine-free conversion programs are restructuring supplier qualification requirements across Saudi Aramco-affiliated installations.
- Industrial Facilities:Manufacturing zones under Saudi Vision 2030 and Qatar's North Field expansion are constructing greenfield fire safety infrastructure. These projects specify Civil Defence pre-approved concentrates with accompanying equipment compatibility verification, creating bundled procurement opportunities.
- Airports:Aviation rescue firefighting operations require low-expansion foam concentrates meeting ICAO and NFPA 403 performance benchmarks.
- Marine Applications:Port terminals at Mina Al-Ahmadi and Shuwaikh deploy fluoroprotein formulations for tanker deck protection.
Oil refineries anchor current procurement value. Industrial facilities are climbing the fastest as manufacturing capacity expands.
End User:
Military and fire department procurement operates through centralized tender processes, while industrial users negotiate direct supply agreements with formulation blenders.
- Fire Departments:Municipal civil defence authorities across Emirates, Qatar, and Kuwait specify pre-approved concentrate lists. UAE Civil Defence certification requirements filter supplier access through EN 1568 testing protocol compliance.
- Military:Defence ministry procurement for airbase and naval facility protection emphasizes stockpile standardization and long-term supply security.
- Industrial Users:Petrochemical operators and terminal managers negotiate direct contracts covering concentrate supply, proportioner maintenance, and annual recertification support.
- Commercial Users:Warehousing, logistics, and fuel retail operators purchase through distributor networks with limited technical specification involvement.
Industrial users dominate negotiated contract value. Fire departments are consolidating procurement around pre-approval breadth.
Distribution Channel:
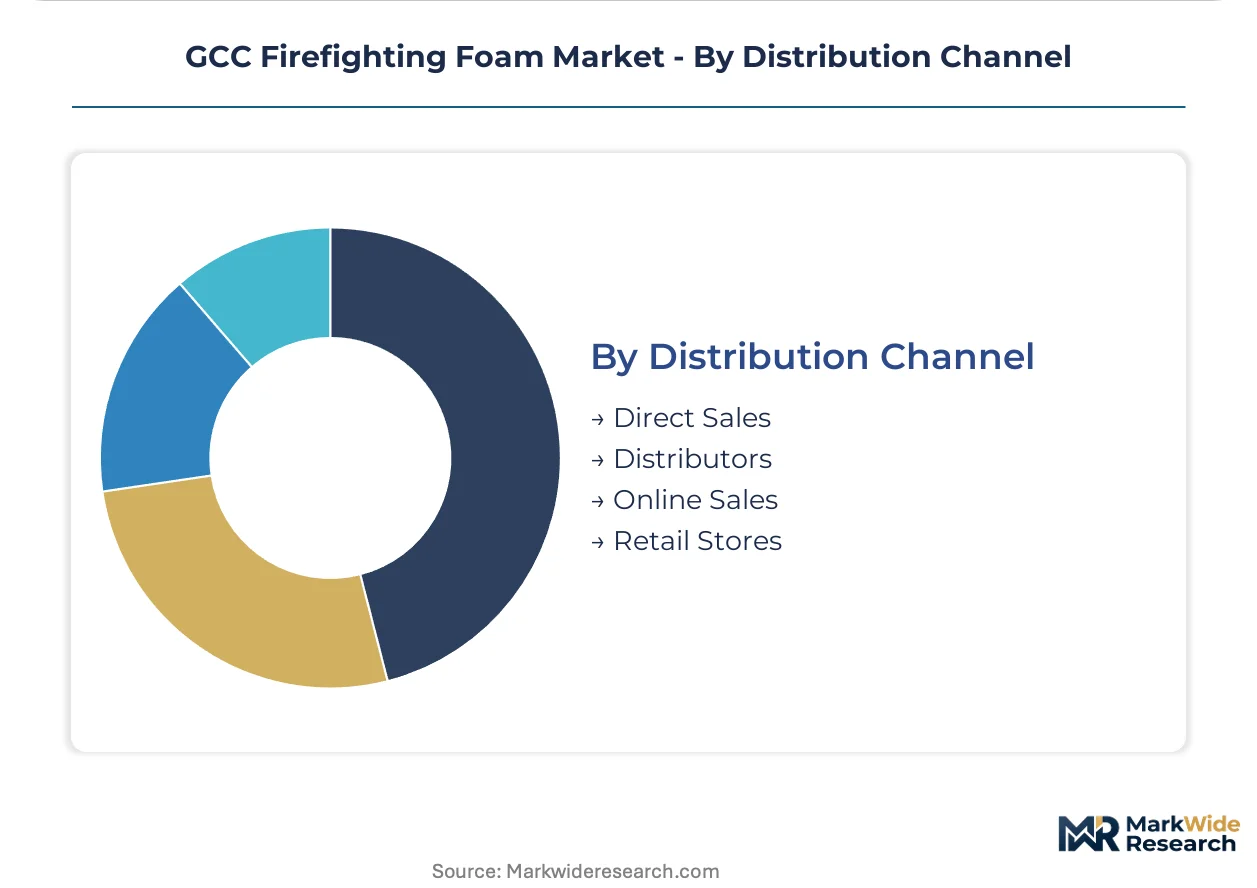
Direct sales concentrate in high-volume hydrocarbon facilities, while distributor networks serve fragmented commercial and small industrial accounts.
- Direct Sales:Formulation blenders maintain dedicated account teams for Saudi Aramco, ADNOC, and QatarEnergy facilities. These relationships span concentrate supply, system integration, and regulatory compliance support.
- Distributors:Regional chemical distributors stock Civil Defence pre-approved concentrates for rapid deployment to construction sites and facility maintenance programs.
- Online Sales:E-commerce penetration remains minimal due to hazardous material shipping restrictions and certification documentation requirements.
- Retail Stores:Limited to small-format portable extinguishers and consumer-grade foam equipment for vehicle and marine recreational use.
Direct sales capture the premium tier. Distributors are expanding share through service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists concentrate in European and North American chemical clusters, creating recruitment friction for GCC-based manufacturers seeking R&D and quality control talent.
Saudi Arabia
Oil refineries at Ras Tanura and Yanbu generate concentrated procurement demand through bulk concentrate contracts. SASO enforces updated foam performance benchmarks referencing NFPA 11 and EN 1568 testing protocols. The Eastern Province industrial corridor anchors fluorine-free conversion programs across Saudi Aramco-affiliated installations.
United Arab Emirates
Airport crash rescue operations at Dubai International and aviation facilities across Emirates drive specification-grade concentrate demand. UAE Civil Defence certification requirements tighten product standards through EN 1568 protocol alignment. Petrochemical terminal operators in Abu Dhabi consolidate procurement around Civil Defence pre-approved supplier lists.
Qatar
North Field gas development and downstream petrochemical projects construct new fire protection infrastructure. Qatar Civil Defence qualification processes create entrenched supplier positions before capacity comes online. Ras Laffan Industrial City facilities specify pre-approved concentrates with equipment compatibility verification.
Kuwait
Marine tanker protection standards at Mina Al-Ahmadi and Shuwaikh terminals tighten under environmental compliance frameworks. The country's national civil defence authority mandates third-party certification for hydrocarbon facility deployments. Port modernization programs anchor premium positioning for fluoroprotein formulation specialists.
GCC Firefighting Foam Market Competitive Landscape
Capital-heavy integrated fire protection platforms compete with asset-light specialized concentrate blenders across the GCC procurement landscape. The supplier base stratifies around certification breadth, with Civil Defence pre-approval status filtering market access more than manufacturing scale. Three archetypes dominate: integrated multinational platforms anchoring long-term service contracts, regional specialists competing on qualification speed, and European formulation blenders commanding premium positioning in marine and aviation specifications. Competitive moves concentrate on strategic partnership formation with national oil companies and certification portfolio expansion across multiple Gulf jurisdictions.
Among UAE-based specialists, NAFFCO occupies a position exemplifying aggressive Civil Defence pre-approval breadth across Emirates and Qatar. Johnson Controls represents the integrated platform archetype, leveraging fire protection system integration to anchor service relationships with Saudi Aramco-affiliated facilities. Angus Fire sits within the European specialist tier, sustaining premium positioning in Kuwaiti and Bahraini port applications through marine-focused formulation expertise.
| Leading Market Players |
|---|
| SFFECO Global |
| FIREX |
| NAFFCO |
| Johnson Controls |
| National Foam |
| Angus Fire |
| Buckeye Fire Equipment Company |
| Dafo Fomtec AB |
| Albilad Fighting Systems Ltd |
| Others |
Pricing and Supply Chain Analysis
Fluorine-free formulation transitions are redrawing cost structures across GCC foam concentrate procurement. Saudi Aramco-affiliated refineries and UAE Civil Defence-certified facilities now demand surfactant packages that eliminate fluorinated precursors, compressing margins for legacy AFFF blenders while rewarding early movers with pricing power in premium environmental compliance tiers.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between Saudi Aramco, ADNOC, and QatarEnergy facilities and their approved concentrate suppliers. Price differentiation separates Civil Defence pre-approved concentrates from uncertified imports, with SASO and UAE Civil Defence certification status commanding substantial premiums. Cost compression in standard-grade synthetic surfactants is intensifying because Asian import competition filters through distributor networks. Industrial users negotiating direct supply agreements show lowest price sensitivity, while commercial warehousing operators purchasing through distributors exhibit highest elasticity.
Supply Chain Analysis
Hazardous material freight costs from European and North American specialty chemical manufacturers constrain GCC-based formulation blenders. Surfactant precursor supply concentrates in Germany, the United States, and Belgium, with fluorinated surfactant chemistry drawing from limited REACH-compliant European producers. Protein hydrolysate inputs for fluoroprotein formulations rest on agricultural byproduct supply chains in Argentina and Australia. Single-source vulnerability in fluorine-free surfactant intellectual property creates qualification bottlenecks. Distribution runs through regional chemical distributors stocking pre-approved concentrates for rapid deployment to Saudi Vision 2030 construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in GCC firefighting foam concentrates rests on fluorine-free formulation premiums displacing commoditized AFFF volumes. Procurement consolidation around Civil Defence pre-approval breadth rewards suppliers with multi-jurisdiction certification portfolios.
For Market Incumbents: To counter emerging European formulation blenders seeking SASO certification, anchor long-term service contracts with Saudi Aramco through integrated fire protection platform bundling. Deepen backward integration into surfactant precursor supply by qualifying alternative fluorine-free chemistries with third-party laboratories before competitor entry accelerates. For New Entrants and Emerging Players: E-commerce-enabled technical documentation portals offer a route to bypass established distributor relationships for mid-sized industrial facilities seeking rapid certification verification. Qatar's North Field expansion and Ras Laffan Industrial City greenfield projects represent the most penetrable geography, with early Qatar Civil Defence qualification creating entrenched positions before capacity ramps. Target standalone concentrate supply unbundled from equipment maintenance contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors lacking Civil Defence pre-approval breadth but possessing established logistics networks across Emirates and Saudi Arabia. Long-term viability favors acquisition of formulation blenders with proven EN 1568 and NFPA 11 testing records and existing relationships with accredited third-party certification bodies. Monitor SASO announcements regarding unified GCC PFAS restrictions as the inflection signal for accelerated fluorine-free conversion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Civil Defence Pre-Approval Expansion | Multi-jurisdiction certification with Saudi General Authority for Civil Defence and UAE Civil Defence unlocks premium contract tiers. |
| Backward Integration into Surfactant Chemistry | In-house production of fluorine-free surfactant packages reduces dependency on European specialty chemical suppliers. |
| Long-term Supply Agreement with National Oil Companies | Direct contracts with Saudi Aramco and ADNOC anchor volume visibility across Saudi Vision 2030 industrial expansion. |
| Joint Venture with Third-Party Certification Laboratory | Partnership with EN 1568-accredited testing facilities compresses supplier qualification timelines for new concentrate formulations. |
| Green Manufacturing Transition | Protein-based and synthetic surfactant platforms aligned with REACH-compliant chemistry attract environmental mandate-driven procurement. |
Research Methodology
Direct dialogue with fire protection system integrators, Saudi Aramco procurement officers, UAE Civil Defence certification specialists, and Qatar Civil Defence technical reviewers grounded qualitative insights in operational reality. Secondary validation drew from SASO technical regulations, UAE Civil Defence circulars, EN 1568 testing protocol documentation, and SEC filings of listed fire protection equipment manufacturers. Bottom-up concentrate demand estimates by application and end-user segment triangulated against top-down petrochemical facility fire safety capital expenditure projections.
Bottom-up modeling segmented volume and value across the analysis window by product chemistry, application environment, and certification status. The analytical framework incorporated oil refinery storage tank counts, airport crash rescue vehicle fleet sizes, and marine terminal foam system capacities as demand proxies. CAGRs derived from facility expansion timelines under Saudi Vision 2030 and Qatar North Field development schedules. Forecast inputs included SASO regulatory adoption trajectories and fluorine-free formulation performance parity milestones.
The model assumes a particular technology adoption path; alternative pathways for protein-based surfactant platforms achieving hydrocarbon fire suppression parity would alter the outlook. Forecasts reflect assumptions regarding Civil Defence certification timeline compression and European REACH restriction spillover into GCC procurement criteria. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fire and Rescue Helmets Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
North America Fire Extinguisher Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Fire Hose Market