
 Fire Door Market | 2026-2036
Fire Door Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Door Market Analysis
Fire-rated door maintenance contracts and inspection subscriptions is pivoting how suppliers monetize installed bases. JELD-WEN, Inc. leverages its North American dealer network to bundle annual certification services with hardware sales. Sanwa Holdings Corp. anchors its position through in-house production of intumescent seals and proprietary core materials. Buyang Group competes on manufacturing scale across steel and wood product lines in Asia-Pacific markets.
A fire door is an engineered passive fire protection assembly constructed with fire-resistant cores, intumescent seals, and certified hardware designed to compartmentalize buildings and maintain structural integrity during thermal exposure for rated durations. Steel fire doors dominate commercial and industrial applications due to superior durability and higher fire ratings, while wood products sustain demand in residential retrofits where aesthetic integration matters. Double leaf configurations command premium positioning in healthcare and institutional corridors requiring wider egress paths, and 120-minute rated products concentrate margin pools in high-rise and critical infrastructure verticals.
Underwriters Laboratories (UL) and the National Fire Protection Association (NFPA) set testing protocols and installation standards that determine product eligibility across North American projects. The EU Construction Products Regulation and harmonized EN 1634 standards enforce CE marking and consistent fire resistance classification for market access across member states. China's Ministry of Emergency Management and Ministry of Housing and Urban-Rural Development coordinate building code enforcement that escalates fire door specification in new construction. Stakeholders must monitor evolving multi-jurisdiction certification requirements and decide whether to pursue redundant testing or pursue mutual recognition agreements.
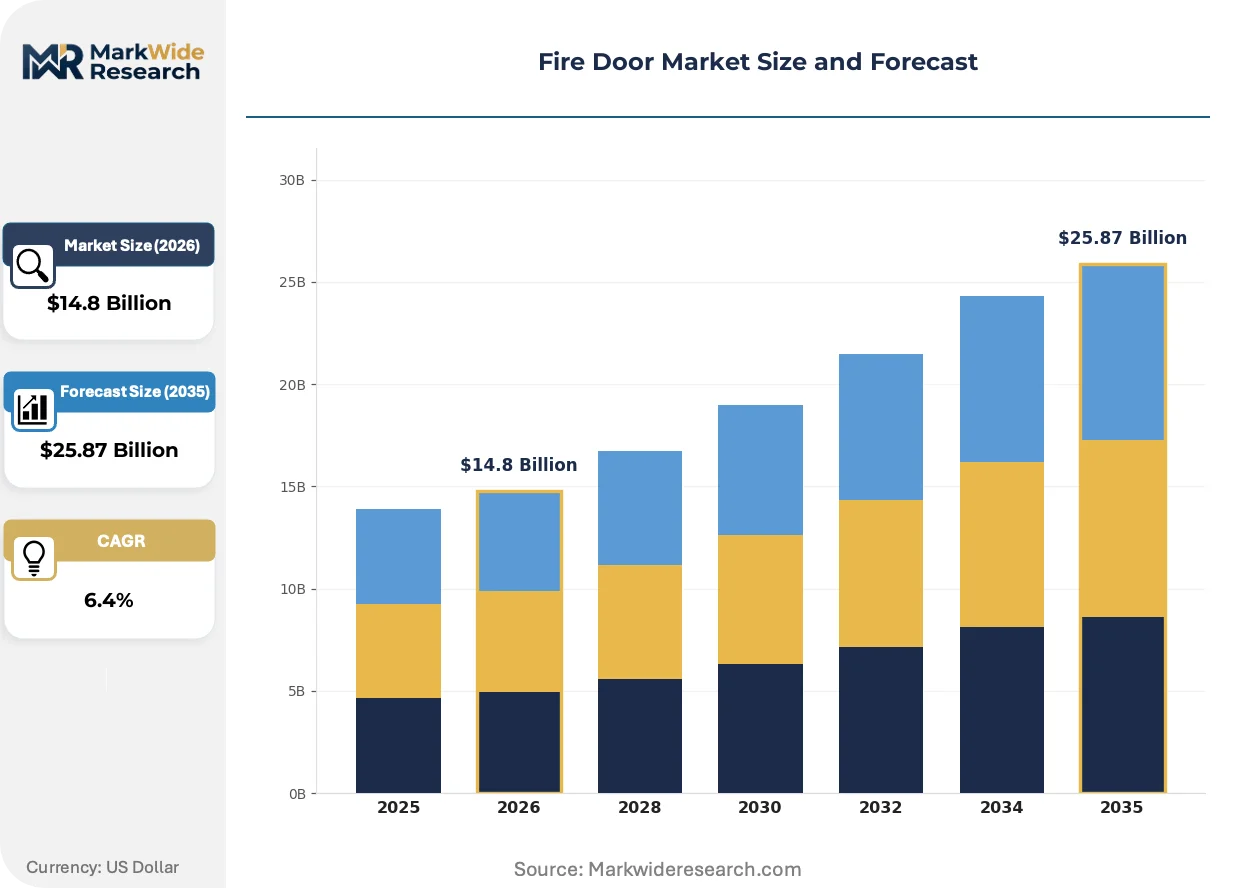
Market Dynamics
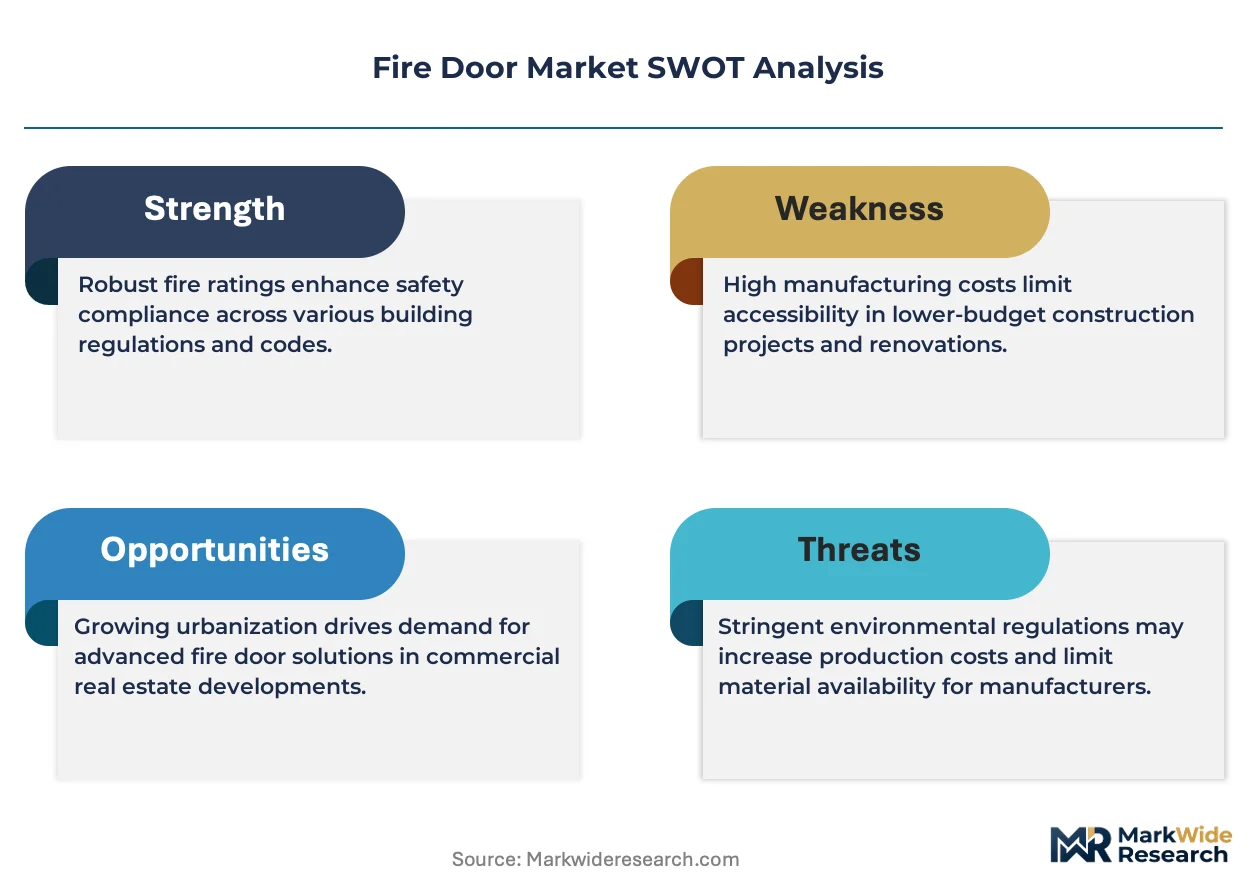
The fire door market is experiencing structural compression between tightening multi-jurisdiction certification requirements and the commoditization of standard steel products. Suppliers must now choose between pursuing redundant testing protocols across UL, EN, and GB standards or negotiating mutual recognition agreements that remain institutionally incomplete.
Growth Catalysts
- Healthcare Facility Construction:Hospital and aged-care facility expansion across China's tier-one cities is accelerating procurement of 120-minute rated double-leaf configurations for corridor compartmentalization.
- EU Construction Products Regulation:Mandatory CE marking and harmonized EN 1634 testing protocols are consolidating demand toward certified manufacturers with in-house testing capabilities.
- Intumescent Seal Technology:Advanced graphite-based intumescent materials are enabling slimmer door profiles that maintain fire ratings while reducing structural load requirements in high-rise retrofits.
Market Restraints
- Steel Input Cost Volatility:Galvanized steel coil prices fluctuate with energy-intensive smelting costs, compressing margins on standard commercial-grade fire doors where pricing is most transparent.
- Supply Concentration in Core Materials:Mineral wool and vermiculite board production clusters in Shandong Province create geographic single-point vulnerability for Asia-Pacific door assemblers.
- Technical Limitation of Wood Products:Solid timber cores cannot achieve 120-minute ratings without excessive thickness, restricting wood fire doors to residential and light commercial applications.
Strategic Opportunities
- India's Urban Infrastructure Buildout:Smart Cities Mission and metro rail expansion in Mumbai, Bangalore, and Delhi are creating first-time specification demand for certified fire-rated assemblies in transit-oriented development.
- Digital Certification Platforms:Blockchain-verified inspection records and IoT-enabled door monitoring systems are creating recurring revenue streams through subscription-based compliance management.
- EU Green Deal Alignment:EPD-certified low-carbon fire doors using recycled steel content and bio-based intumescent coatings qualify for green public procurement preference in member state tenders.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Parallel UL 10C, EN 1634-1, and GB 12955 testing cycles extend product launch timelines by 18-24 months for global suppliers.
- Fire Door Inspector Skill Scarcity:Qualified third-party inspectors capable of assessing intumescent seal degradation and hardware alignment remain under-supplied relative to installed base maintenance requirements.
- Legacy Building Retrofit Integration:Non-standard frame openings in pre-1990s construction require custom fabrication workflows that disrupt scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Door Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Leaf, Double Leaf, Hinged, Rolling Material: Steel, Wood, Fiberglass, Composite Application: Commercial Buildings, Residential Properties, Industrial Facilities, Educational Institutions Fire Rating: 30 Minutes, 60 Minutes, 90 Minutes, 120 Minutes |
| Companies Covered | WONLY Security, Mexin Group, JELD-WEN, Inc., Buyang Group, SEEYES, Sanwa Holdings Corp., PANPAN Security Doors, KKD, Yuankai Door Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Door Market Emerging Trajectories
Material science advances and regulatory digitization are compressing traditional product lifecycles while opening service-based revenue models. Manufacturers are repositioning from component vendors to compliance partners.
Glass-reinforced gypsum and calcium silicate composite cores are expanding into high-rise residential applications where weight reduction matters. Developers in Shanghai and Shenzhen specify these materials for super-tower projects above 300 meters where structural load constraints intensify. The technology is expanding into mid-rise commercial retrofits as facade engineers prioritize lighter curtain wall integration.
China's Ministry of Emergency Management has tightened enforcement coordination with Ministry of Housing and Urban-Rural Development on GB 50016 compliance in mixed-use developments. Local fire bureaus now require stamped approval for fire door submittals before construction permit issuance. High-rise residential towers in Beijing and Guangzhou face the steepest compliance timeline compression as authorities clear permit backlogs.
Building owners are unbundling hardware procurement from inspection and recertification services. Institutional buyers in US healthcare and education verticals now contract multi-year maintenance subscriptions separately from initial door supply. This pattern concentrates in California and Texas where state-level fire marshal inspection frequency exceeds national baselines.
Fire Door Market Segmentation
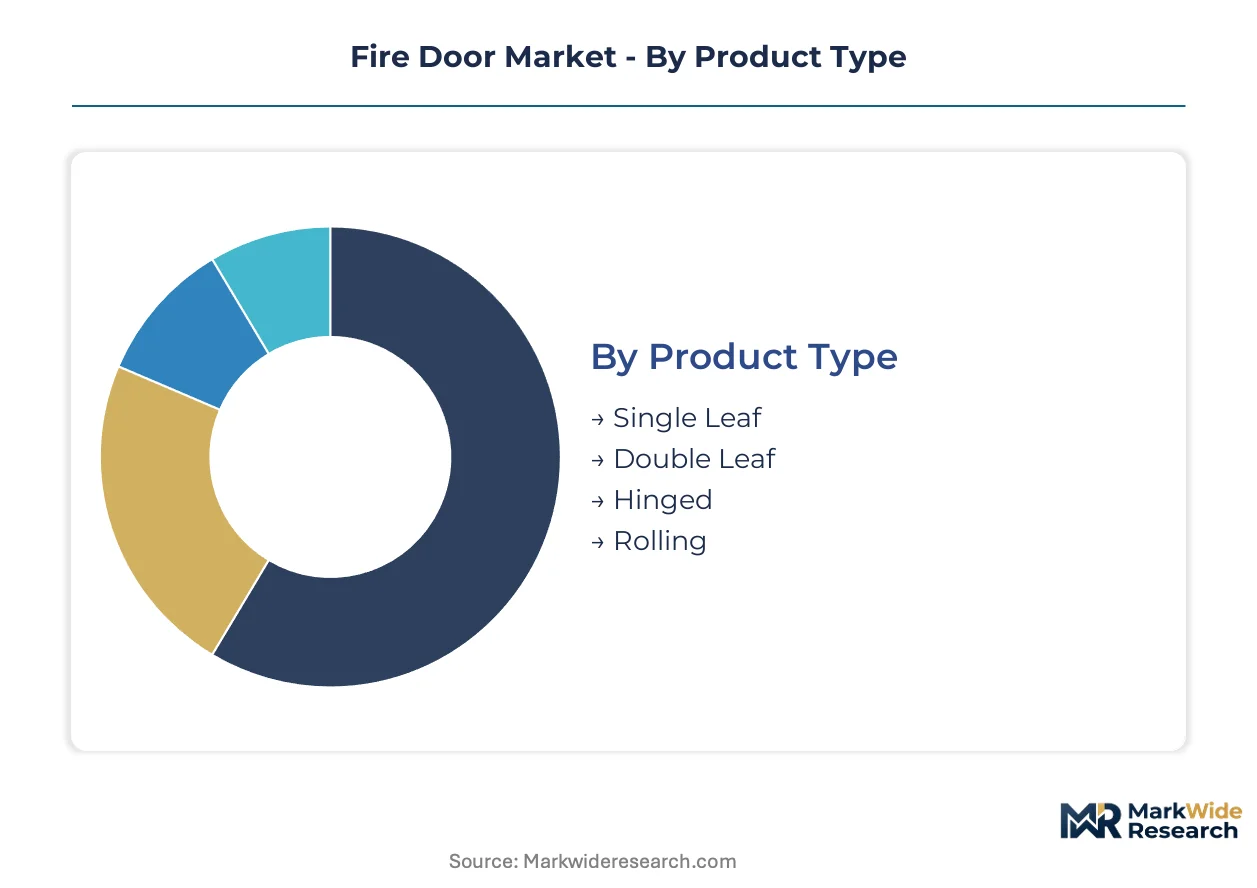
Fire door procurement patterns diverge sharply across building typologies and regulatory jurisdictions. Specification decisions hinge on fire rating requirements, structural load constraints, and aesthetic integration demands that vary by end-use.
Product Type:
Architects and facility managers select configurations based on corridor width, traffic volume, and emergency egress capacity requirements.
- Single Leaf:Standard swing doors with one active panel dominate residential retrofits and standard commercial office suites. Demand concentrates in China's tier-one cities where high-rise residential towers require mass installation of 90-minute rated units for unit entry doors.
- Double Leaf:Paired active panels spanning wider openings command specification in hospital corridors and institutional buildings. Healthcare facility construction across Beijing and Shanghai is accelerating procurement of 120-minute rated configurations for critical compartmentalization zones.
- Hinged:Traditional pivot-mounted assemblies remain the default for retrofit applications where frame conditions limit hardware options. Specifiers in older European building stock favor these for compatibility with historic masonry openings.
- Rolling:Coiling steel curtains deploy in industrial and warehouse settings where vertical clearance allows overhead mounting. Manufacturing facilities in Germany's automotive corridor specify these for production floor separation.
Single leaf configurations lead volumes today; double leaf products are gaining share fastest.
Material:
Raw material selection trades off fire performance, weight, and surface finish requirements against structural engineering constraints.
- Steel:Galvanized or stainless steel skins with mineral wool cores deliver the highest fire ratings and impact resistance. Commercial and industrial buyers in the United States specify these for 120-minute applications where durability outweighs first cost.
- Wood:Solid timber or engineered cores with intumescent facing satisfy residential aesthetic preferences. Wood products sustain demand in European heritage building retrofits where surface appearance must match original joinery.
- Fiberglass:Glass-reinforced polymer skins offer corrosion resistance for coastal and chemical processing environments. Marine facilities in South Korea specify these for salt-air exposure conditions.
- Composite:Calcium silicate or gypsum-based cores with thin metal or laminate facings reduce structural load in super-tower construction. Developers in Shenzhen and Dubai specify these for buildings exceeding 300 meters where weight reduction is critical.
Steel dominates current procurement volumes; composite materials are climbing the fastest.
Application:
End-use verticals impose distinct certification, maintenance, and performance monitoring requirements that shape supplier relationships.
- Commercial Buildings:Office towers, retail centers, and hospitality properties require standardized 60-90 minute ratings with emphasis on hardware durability. Property managers in London and New York are unbundling initial supply from multi-year inspection subscriptions.
- Residential Properties:Multi-family housing and single-family retrofits prioritize aesthetic integration and cost efficiency. China's Ministry of Housing and Urban-Rural Development enforcement is tightening fire door specification in new high-rise residential permits.
- Industrial Facilities:Manufacturing plants, warehouses, and energy infrastructure demand maximum fire ratings and impact resistance. Petrochemical complexes on the US Gulf Coast specify 120-minute rolling configurations for process area separation.
- Educational Institutions:Schools and universities balance fire safety with high-frequency daily use and vandalism resistance. State-level fire marshal inspection frequency in California and Texas exceeds national baselines, driving maintenance contract demand.
Commercial buildings anchor current demand; educational institutions are expanding procurement most rapidly.
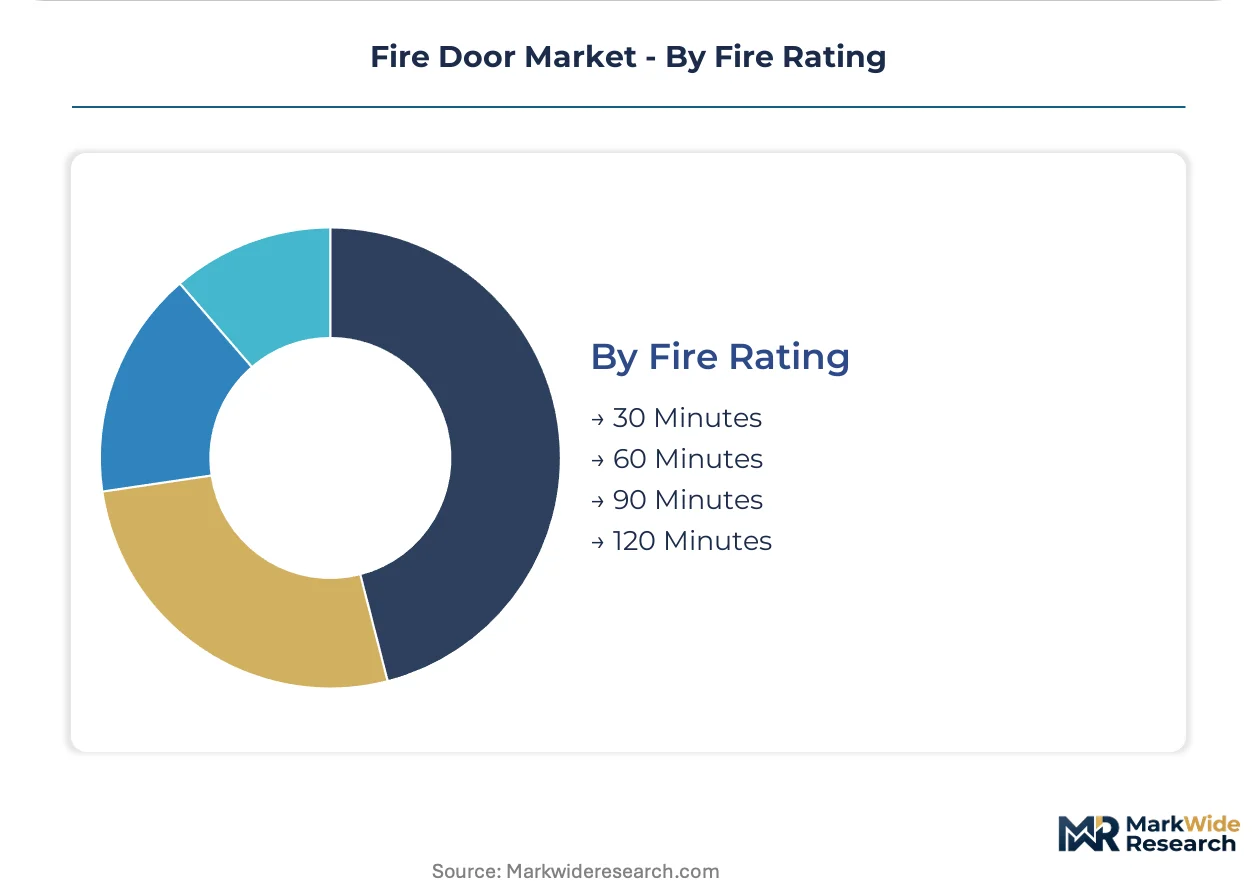
Fire Rating:
Regulatory minimums and insurance underwriting requirements determine rating selection across building codes and occupancy types.
- 30 Minutes:Basic containment for low-occupancy spaces and residential unit separation. These satisfy minimum code requirements in light commercial and residential retrofits where cost sensitivity is highest.
- 60 Minutes:Standard specification for general commercial corridors and office compartmentalization. This rating captures the largest volume of non-residential construction in mid-rise buildings across developed markets.
- 90 Minutes:Enhanced protection for high-occupancy assembly spaces and residential high-rise unit entry doors. China's tier-one city building codes are escalating toward this threshold for new residential towers.
- 120 Minutes:Maximum containment for critical infrastructure, healthcare, and super-tower applications. These concentrate margin pools where testing certification costs and technical complexity limit supplier participation.
Sixty-minute ratings lead installation volumes today; 120-minute products are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's fire door procurement volumes outpace Germany's by a factor reflecting divergent urbanization trajectories, yet both markets enforce stringent certification regimes that shape supplier participation.
China
High-rise residential towers in Beijing and Shanghai drive 120-minute rated double-leaf specifications as the Ministry of Housing and Urban-Rural Development tightens GB 50016 enforcement. Local fire bureaus now mandate stamped submittal approval before construction permit issuance. The Yangtze River Delta corridor concentrates manufacturing capacity for mineral wool cores and intumescent seal production.
United States
Healthcare and education verticals in California and Texas unbundle hardware procurement from multi-year inspection subscriptions as state fire marshal inspection frequency exceeds national baselines. Underwriters Laboratories and NFPA testing protocols determine product eligibility across commercial and industrial projects. The Gulf Coast petrochemical corridor sustains demand for maximum-rated rolling configurations in process area separation.
Germany
Automotive manufacturing facilities along the Baden-Württemberg corridor specify coiling steel curtains for production floor separation as industrial fire safety standards tighten. The EU Construction Products Regulation and harmonized EN 1634 standards enforce CE marking requirements that consolidate demand toward certified manufacturers. Historic building retrofits in older European masonry stock sustain specification of hinged configurations for frame compatibility.
India
Smart Cities Mission infrastructure and metro rail expansion in Mumbai, Bangalore, and Delhi generate first-time specification demand for certified fire-rated assemblies in transit-oriented development. The Bureau of Indian Standards and Ministry of Housing and Urban Affairs coordinate building code enforcement that escalates fire door requirements in new commercial construction. Western India's industrial corridor is emerging as a fabrication hub for standard steel commercial-grade products.
United Arab Emirates
Super-tower developments exceeding 300 meters in Dubai specify calcium silicate composite cores to reduce structural load as facade engineers prioritize lighter curtain wall integration. The country's civil defense authority mandates third-party certification for all passive fire protection assemblies in high-rise construction. Free zone manufacturing clusters are attracting regional headquarters for suppliers serving Gulf Cooperation Council markets.
Fire Door Market Vendor Landscape
Top-tier vendors anchor premium certification tiers, while mid-scale fabricators compete on manufacturing throughput and regional distribution density. The market structure reflects consolidation around testing-capable manufacturers with in-house EN 1634, UL 10C, and GB 12955 protocols, alongside fragmentation among local assemblers dependent on outsourced core materials. Three archetypes dominate: vertically integrated specialists controlling intumescent seal and core material production; scale-driven steel fabricators competing on commercial-grade volume; and regional champions leveraging local certification relationships. Competitive dynamics center on backward integration into core material supply and geographic expansion through mutual recognition agreement negotiation.
Within the vertically integrated specialist tier, Sanwa Holdings Corp. exemplifies upstream control over proprietary core materials and intumescent seal production. JELD-WEN, Inc. occupies a position as a North American-scale fabricator with established dealer network relationships. Buyang Group represents manufacturing-scale competition across multiple product lines in Asia-Pacific markets.
| Leading Market Players |
|---|
| WONLY Security |
| Mexin Group |
| JELD-WEN, Inc. |
| Buyang Group |
| SEEYES |
| Sanwa Holdings Corp. |
| PANPAN Security Doors |
| KKD |
| Yuankai Door Industrial |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between 120-minute premium assemblies and standard 60-minute commercial units manifests in pricing power concentration among EN 1634 and UL 10C certified manufacturers, while supply chain configurations track core material sourcing from Shandong Province mineral wool clusters and captive intumescent seal production.
Pricing Analysis
Capacity additions in India's western industrial corridor are reshaping price floors for standard steel commercial-grade products. Three-tier pricing structure across premium certified, standard code-compliant, and economy unbranded levels separates 120-minute healthcare specifications from 60-minute office installations from residential retrofit minimums. Price differentiation hinges on fire rating tier and in-house testing capability ownership. Margins are tightening due to galvanized steel coil volatility and energy-intensive smelting cost pass-through. Residential retrofits in China's tier-one cities exhibit highest price sensitivity; Gulf Coast petrochemical complexes show lowest sensitivity due to insurance-mandated specification rigidity.
Supply Chain Analysis
Dual-sourcing requirements from Dubai civil defense authority and US healthcare GPOs mandate multi-supplier qualification for intumescent seals and certified hardware. Geographic supply concentration centers on China for mineral wool cores and vermiculite board, Germany for precision hinge and closer assemblies, and South Korea for glass-reinforced polymer marine-grade skins. Raw material dependencies include galvanized steel coil, graphite-based intumescent compounds, and calcium silicate composite substrates. Single-source vulnerability concentrates in Shandong Province mineral wool production clusters. Distribution runs through certified dealer networks in North America, direct specification relationships with facade engineers in UAE super-tower projects, and municipal procurement channels in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire door procurement has shifted toward premium 120-minute specifications in healthcare and super-tower verticals, creating late-cycle quality dynamics where certification depth and testing capability ownership determine competitive survival.
For Market Incumbents: To counter margin compression from commoditized 60-minute steel products, incumbents should deepen backward integration into intumescent seal chemistry and pursue mutual recognition agreements between UL, EN, and GB testing protocols to compress 18-24 month certification timelines. For New Entrants and Emerging Players: Begin with India's Smart Cities Mission metro rail corridors and Mumbai transit-oriented development zones where first-time certified specification demand outpaces established supply relationships. Target digital certification platforms and IoT-enabled inspection subscriptions as the go-to-market wedge. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction testing capabilities overlap with in-house core material production. Long-term viability favors vertically integrated specialists with captive mineral wool or intumescent supply. Watch for GB 50016 enforcement intensity in Beijing and Shanghai permit backlogs as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Materials | Captive mineral wool and intumescent seal production shields margin from Shandong supply shocks. |
| Multi-Jurisdiction Certification Investment | Parallel UL 10C, EN 1634-1, and GB 12955 capability unlocks healthcare and super-tower premium tiers. |
| Digital Compliance Platform Launch | Blockchain-verified inspection records create recurring revenue from California and Texas education verticals. |
| EU Green Deal Alignment | EPD-certified low-carbon assemblies qualify for green public procurement preference in member state tenders. |
| India Manufacturing Footprint Establishment | Western India fabrication hub proximity serves Mumbai, Bangalore, and Delhi metro rail expansion demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fire door manufacturing executives, certified testing laboratory directors, healthcare facility procurement managers, and facade engineering consultants with secondary validation from UL certification databases, EN 1634 test reports, China's Ministry of Housing and Urban-Rural Development permit filings, and GB 50016 compliance records. Bottom-up volume aggregation across product type, material, application, and fire rating segments was cross-checked against top-down market sizing from construction permit data and installed base maintenance contract flows.
Segment-weighting approaches distributed value and volume across single versus double leaf configurations, steel versus composite materials, commercial versus healthcare applications, and 60-minute versus 120-minute fire ratings throughout the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns against construction spend forecasts and regulatory enforcement intensity indices. Industry-specific inputs included galvanized steel coil price volatility coefficients and intumescent seal technology adoption curves.
Several conditions sit outside the modeled scope, including abrupt shifts in China-India trade protocols, unforeseen mineral wool supply disruptions beyond Shandong Province, and accelerated mutual recognition agreement completion between UL and GB standards bodies. Deviation in GB 50016 enforcement coordination between China's Ministry of Emergency Management and Ministry of Housing and Urban-Rural Development would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
Global Flame Arrestors Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
Smoke Pressure System Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Fire Alarm and Detection System Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Europe Passive Fire Protection Market