
 Gas Detection Equipment Market | 2026-2036
Gas Detection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Detection Equipment Market Intelligence
The EU Green Deal's industrial emissions benchmarks are consolidating demand for next-generation gas detection infrastructure across European process industries. Honeywell International Inc. leverages its distributed sensor architecture to sustain leadership in integrated safety systems for refineries. Drägerwerk AG & Co. KGaA anchors its position through specialized breathing protection and detection portfolios for hazardous environments. MSA Safety Incorporated competes on wireless connectivity platforms that extend real-time monitoring capabilities across dispersed industrial sites.
Gas detection equipment comprises sensor-based instrumentation engineered to identify and quantify airborne hazardous substances through electrochemical reaction, infrared absorption, or catalytic oxidation principles, typically achieving detection thresholds measured in parts per million for toxic compounds and percentage levels for combustible gases. Fixed detector installations dominate capital allocation across oil and gas processing complexes where continuous perimeter monitoring remains non-negotiable. Infrared sensor technology leads premium product development due to its immunity to sensor poisoning and extended calibration intervals. Portable detectors represent the fastest-expanding category as maintenance crews and emergency responders require lightweight, multi-gas capability for confined space entry protocols.
OSHA permissible exposure limits and EPA air toxics standards shape product certification requirements and procurement specifications across US industrial facilities. REACH chemical registration obligations in Europe mandate substance-specific detection protocols that influence sensor portfolio design. Japan's METI industrial safety directives and JIS standards govern equipment performance benchmarks for domestic manufacturing and export qualification. Stakeholders must evaluate sensor interoperability standards and cloud platform integration roadmaps when selecting long-term detection architecture partners.
Market Dynamics
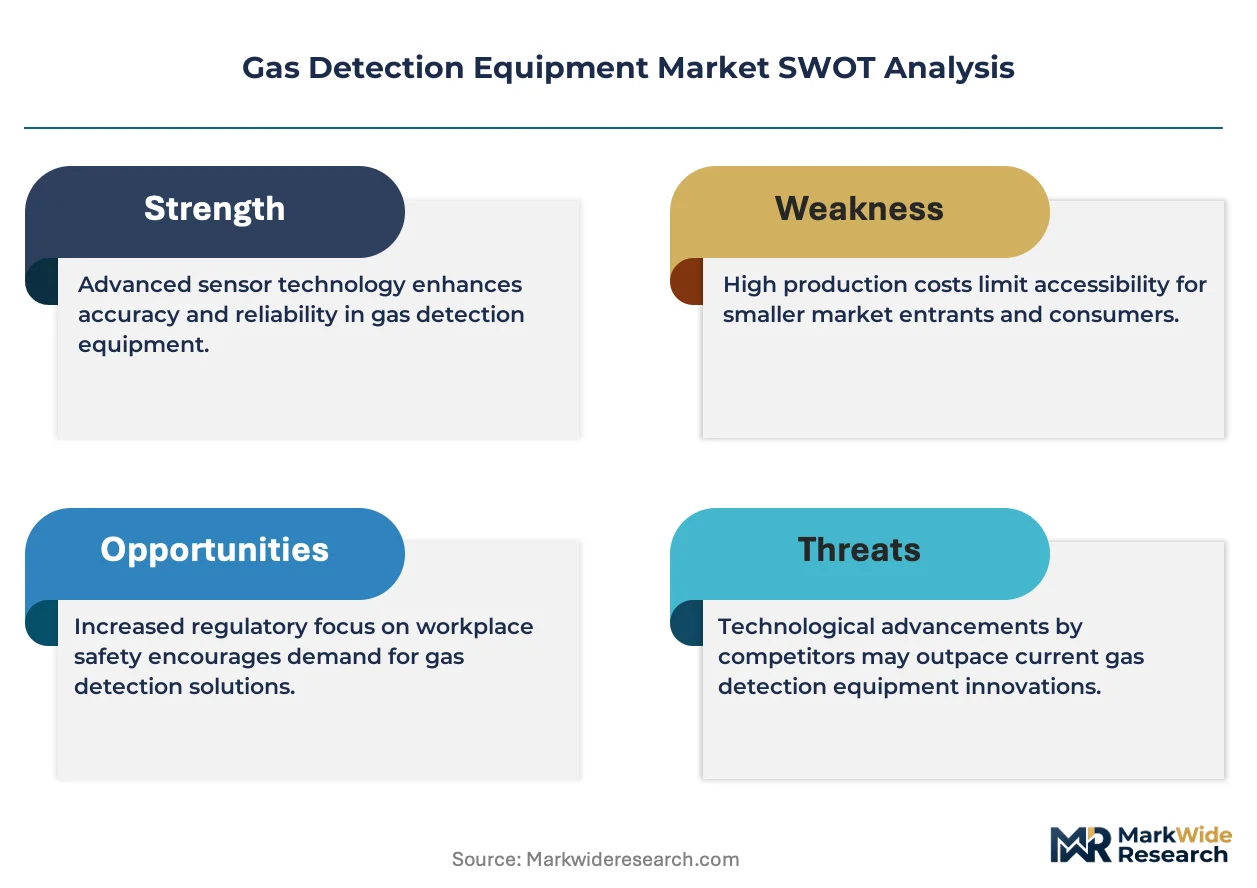
OSHA's tightening permissible exposure limits for benzene and hydrogen sulfide are forcing US petrochemical operators to replace legacy point detectors with networked sensor arrays capable of real-time perimeter mapping and predictive leak localization.
Growth Catalysts
- REACH chemical registration obligations:European manufacturers must maintain substance-specific detection protocols for imported feedstocks, expanding sensor portfolio requirements across German chemical parks.
- Semiconductor fabrication cleanrooms:Taiwan and South Korean fabs deploy infrared sensors for trace gas monitoring of arsine and phosphine during epitaxial deposition processes.
- Battery manufacturing expansion:German and Japanese cell plants mandate multi-gas detection for hydrogen fluoride and volatile organic compound surveillance during electrolyte mixing operations.
Market Restraints
- Sensor poisoning vulnerability:Catalytic oxidation detectors suffer irreversible degradation from silicone and sulfur compounds prevalent in refinery maintenance environments.
- Calibration service concentration:Factory-authorized calibration networks cluster in Texas, Rotterdam, and Singapore, creating logistical friction for Central European and Southeast Asian operators.
- Infrared sensor cost premiums:Photodetector arrays and optical path engineering sustain 40-60% price deltas versus electrochemical alternatives, constraining adoption in cost-sensitive municipal utilities.
Strategic Opportunities
- Indian industrial corridor buildout:Gujarat and Tamil Nadu petrochemical zones lack integrated gas detection infrastructure, presenting greenfield deployment potential for fixed detector networks.
- Cloud platform convergence:Edge computing and 5G private networks enable predictive maintenance models that compress unplanned downtime in offshore platform operations.
- EU Green Deal industrial emissions benchmarks:Process industry operators face mandatory monitoring upgrades for methane and nitrous oxide, consolidating demand for next-generation infrared analyzers.
Industry Challenges
- Functional safety certification timelines:IEC 61508 SIL 2/3 qualification for safety instrumented systems extends product development cycles by 14-18 months.
- Legacy system integration friction:4-20 mA analog outputs from installed detector bases resist seamless incorporation into digital twin architectures without signal converter middleware.
- Cross-domain expertise scarcity:Field technicians require simultaneous competence in optical physics, industrial networking protocols, and hazardous area electrical codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Detection Equipment Market |
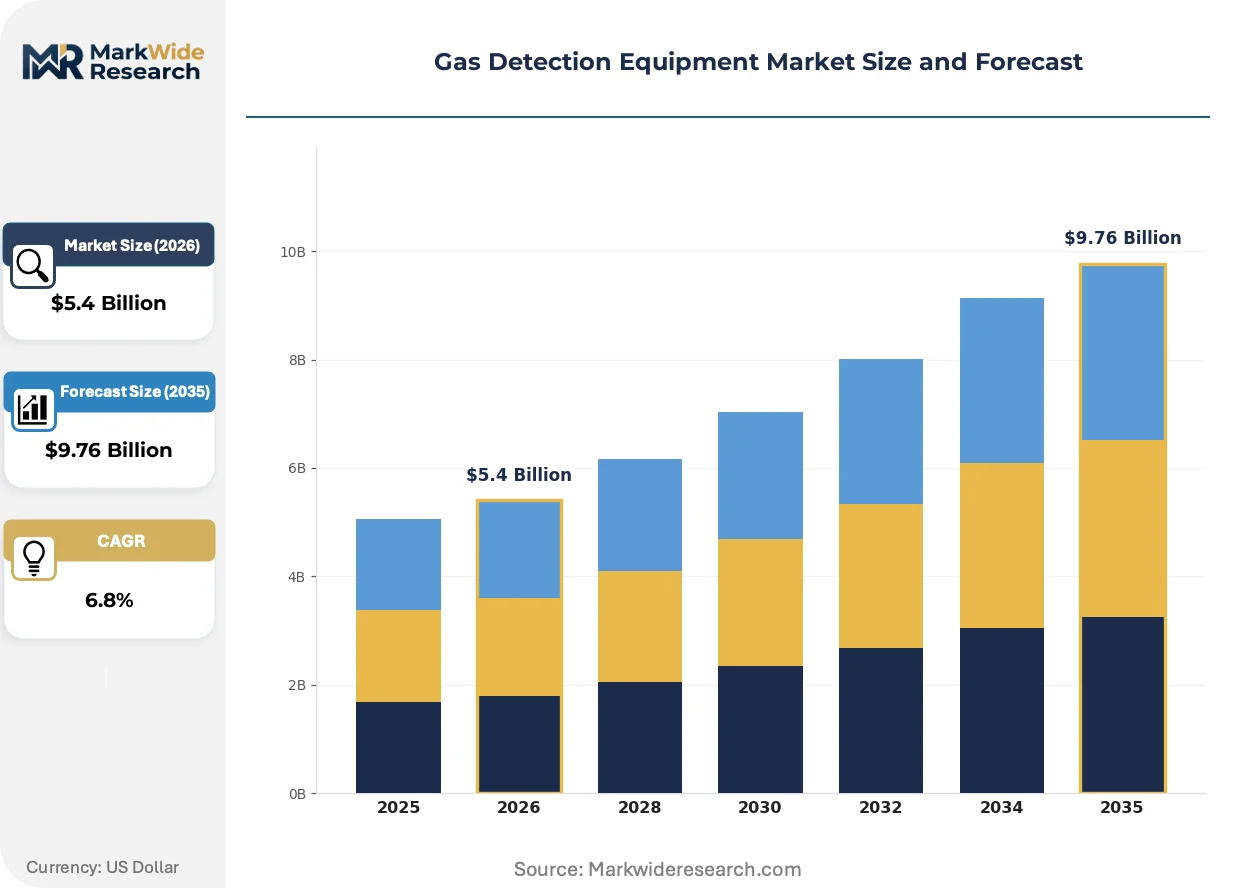
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Portable Detectors, Fixed Detectors, Multi-Gas Detectors, Single-Gas Detectors Technology: Catalytic Sensors, Electrochemical Sensors, Infrared Sensors, Photoionization Detectors Application: Oil & Gas, Mining, Chemical Processing, Fire Safety End User: Industrial Sector, Commercial Sector, Residential Sector, Government Agencies |
| Companies Covered | Honeywell International Inc., Drägerwerk AG & Co. KGaA, MSA Safety Incorporated, Industrial Scientific, RKI Instruments Inc., Siemens AG, Emerson Electric Co., Teledyne Technologies Incorporated, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Detection Equipment Market Strategic Shifts & Innovations
Tunable diode laser absorption spectroscopy and MEMS-based sensor miniaturization are compressing form factors while extending detection ranges, reshaping procurement criteria across confined space and perimeter monitoring applications alike.
Photonic integrated circuits are rewriting competitive economics for trace gas detection. These silicon-based platforms consolidate laser sources, waveguides, and detectors onto single substrates. Pharmaceutical manufacturers in Ireland and Switzerland adopt them for continuous emissions monitoring at fermentation facilities. The technology is compressing equipment footprints by 70% while eliminating alignment drift that plagued benchtop analyzers.
Japan's METI industrial safety directives now mandate redundant gas detection for hydrogen handling infrastructure, accelerating dual-sensor architecture adoption. Domestic equipment manufacturers must certify to revised JIS T 8201 performance benchmarks by March 2026. This regulatory compression is forcing importers from Germany and the United States to establish local calibration partnerships or surrender municipal utility contracts.
Maintenance crews increasingly reject bundled service contracts in favor of unbundled calibration subscriptions and on-demand technical support. This pattern is most visible in North Sea offshore operations where helicopter logistics amplify downtime costs. Independent service providers in Aberdeen and Stavanger capture detector maintenance volumes that incumbent manufacturers previously controlled through captive service agreements.
Gas Detection Equipment Market Segmentation
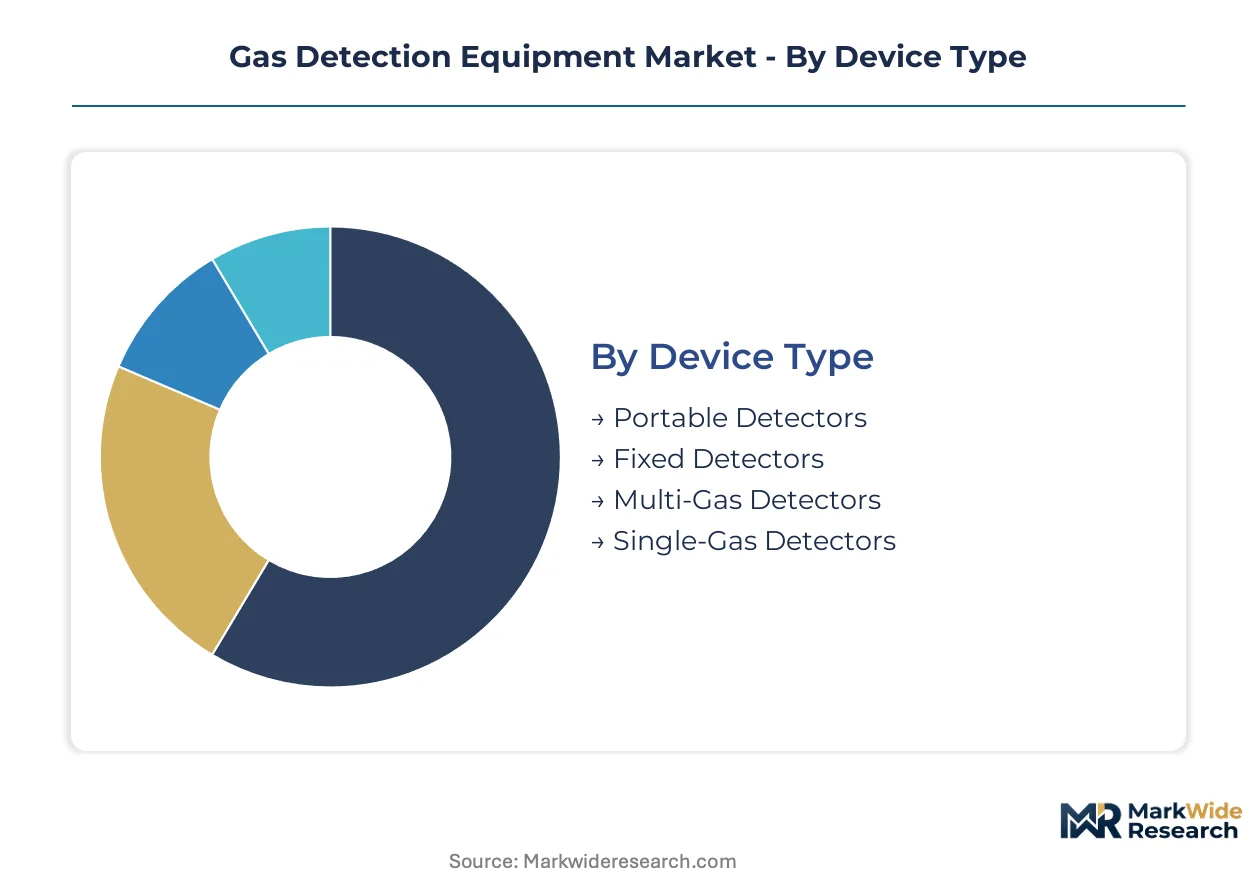
Gas detection equipment segmentation reveals distinct procurement patterns across device architectures, sensor technologies, and end-use environments. Each dimension carries specific certification requirements and lifecycle cost structures that shape vendor selection and deployment strategy.
Device Type:
Physical form factor determines calibration protocols, battery chemistry, and connectivity architecture across deployment scenarios.
- Fixed Detectors:Permanently installed sensor nodes integrate with safety instrumented systems through 4-20 mA or digital fieldbus protocols. US petrochemical facilities along the Gulf Coast deploy networked arrays for continuous perimeter monitoring of benzene and hydrogen sulfide under tightening OSHA permissible exposure limits. Fixed detectors lead on scale; portable detectors lead on momentum.
- Portable Detectors:Handheld or wearable units serve maintenance crews and emergency responders entering confined spaces. Semiconductor fabrication cleanrooms in Taiwan and South Korea specify lightweight multi-gas units for trace arsine and phosphine monitoring during equipment maintenance cycles.
- Multi-Gas Detectors:Simultaneous monitoring capability for four to six target compounds reduces equipment inventory for industrial safety departments.
- Single-Gas Detectors:Dedicated hydrogen sulfide or carbon monoxide units serve cost-sensitive municipal utility applications with predictable hazard profiles.
Capital allocation favors fixed installations where continuous monitoring is non-negotiable; operational flexibility drives portable unit procurement.
Technology:
Detection principle selection trades sensitivity, selectivity, and total cost of ownership against target gas chemistry and environmental conditions.
- Infrared Sensors:Non-dispersive infrared and tunable diode laser absorption spectroscopy achieve immunity to sensor poisoning and extended calibration intervals. Battery manufacturing plants in Germany and Japan specify infrared analyzers for hydrogen fluoride surveillance during electrolyte mixing operations. Infrared sensors lead on specification; electrochemical sensors lead on installed base.
- Electrochemical Sensors:Amperometric cells offer parts-per-million sensitivity for toxic gases at moderate cost points. Catalytic oxidation detectors suffer irreversible degradation from silicone and sulfur compounds prevalent in refinery maintenance environments.
- Catalytic Sensors:Wheatstone bridge configurations detect combustible gas concentrations through oxidation heat measurement on catalytic beads.
- Photoionization Detectors:Ultraviolet lamp ionization enables broad-spectrum volatile organic compound detection for hazmat response and environmental monitoring.
Technology migration favors photonic integration where drift stability and miniaturization justify premium positioning.
Application:
Industry-specific hazard profiles dictate sensor array configuration and alarm integration requirements.
- Oil & Gas:Upstream, midstream, and downstream operations require combined combustible and toxic gas coverage across drilling platforms, processing trains, and storage terminals. REACH chemical registration obligations in Europe mandate substance-specific detection protocols for imported feedstocks across German chemical parks.
- Chemical Processing:Batch and continuous reactors demand corrosion-resistant sensor housings and SIL-rated safety loops.
- Mining:Underground coal and hard-rock operations prioritize methane and carbon monoxide monitoring with intrinsic safety certification.
- Fire Safety:Smoke and combustion product detection integrates with building management systems for occupant evacuation protocols.
Oil and gas commands the largest equipment spend; battery manufacturing and semiconductor fabrication are climbing the fastest.
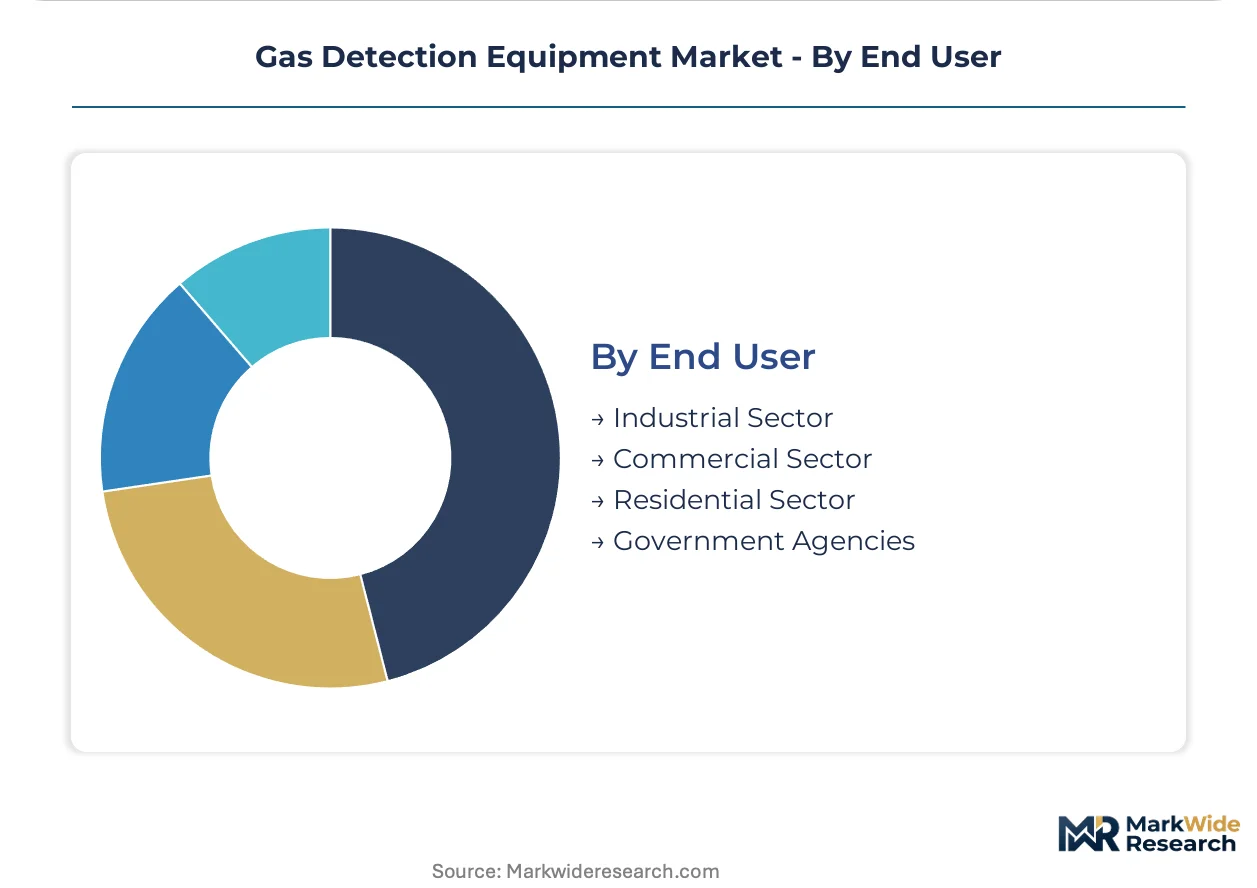
End User:
Purchasing authority and budget cycles vary substantially across organizational categories.
- Industrial Sector:Petrochemical, pharmaceutical, and manufacturing operators maintain captive safety engineering teams with technical specification authority. Japan's METI industrial safety directives mandate redundant gas detection for hydrogen handling infrastructure, accelerating dual-sensor architecture adoption among domestic manufacturers.
- Commercial Sector:Property management and facility services outsource detection system maintenance to specialized service providers.
- Government Agencies:Municipal utilities, defense installations, and environmental regulators specify equipment through formal procurement frameworks with extended vendor qualification timelines.
- Residential Sector:Carbon monoxide and natural gas alarms represent a price-sensitive mass market with retail distribution dominance.
Industrial buyers dominate technical specification; commercial and residential channels are expanding most quickly through distribution partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gas detection instrumentation first achieved industrial scale in German chemical parks during the 1960s, with BASF and Bayer facilities pioneering fixed detector networks for phosgene monitoring. This engineering heritage established calibration protocols and SIL certification frameworks that persist across European process industries today.
United States
Gulf Coast petrochemical complexes along the Texas-Louisiana corridor deploy networked sensor arrays for benzene and hydrogen sulfide perimeter mapping. OSHA permissible exposure limit revisions are forcing replacement of legacy point detectors with predictive leak localization systems. Houston-area refineries represent the densest concentration of safety instrumented system upgrades.
Germany
Battery manufacturing plants in Saxony and Baden-Württemberg mandate multi-gas detection for hydrogen fluoride surveillance during electrolyte operations. REACH chemical registration obligations require substance-specific detection protocols for imported feedstocks across Ludwigshafen and Leverkusen chemical parks. The EU Green Deal's industrial emissions benchmarks are consolidating demand for next-generation infrared analyzers.
Japan
Semiconductor fabrication cleanrooms in Kumamoto and Hiroshima prefectures deploy infrared sensors for trace arsine and phosphine monitoring during epitaxial deposition. METI industrial safety directives mandate redundant gas detection for hydrogen handling infrastructure, with revised JIS T 8201 benchmarks effective March 2026. Domestic manufacturers must certify locally or surrender municipal utility contracts.
South Korea
Memory and logic chip fabs in Pyeongtaek and Yongin specify lightweight multi-gas units for maintenance crew protection. MFDS-equivalent industrial safety standards govern cleanroom atmospheric monitoring during equipment service cycles. The concentration of semiconductor capital equipment spending drives premium sensor specification.
India
Gujarat and Tamil Nadu petrochemical zones lack integrated gas detection infrastructure, presenting greenfield deployment potential for fixed detector networks. The country's national industrial safety regulator is drafting mandatory leak detection requirements for hazardous chemical clusters. Reliance Industries' Jamnagar complex represents the largest prospective single-site installation.
Gas Detection Equipment Market Key Industry Players
Premium-margin players sit above commodity-margin players across sensor technology sophistication and calibration service density. The vendor base stratifies into three tiers: integrated safety system providers with distributed architectures, specialized breathing protection and detection portfolios, and wireless connectivity platform specialists. Consolidation pressure is accelerating through captive calibration network expansion and photonic integrated circuit licensing arrangements.
Within the integrated systems tier, Honeywell International Inc. and Siemens AG exemplify scale-driven positioning through distributed sensor architectures and process automation integration. Drägerwerk AG & Co. KGaA anchors the specialized protection segment with its German-engineered hazardous environment focus. These three occupy positions that reflect divergent strategic bets on service bundling versus technology licensing.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Drägerwerk AG & Co. KGaA |
| MSA Safety Incorporated |
| Industrial Scientific |
| RKI Instruments Inc. |
| Siemens AG |
| Emerson Electric Co. |
| Teledyne Technologies Incorporated |
| Thermo Fisher Scientific Inc. |
| Others |
Cost & Logistics Intelligence
Infrared-electrochemical sensor performance bifurcation separates premium detector lines from commodity alternatives, with calibration network density and SIL certification tiers determining both price positioning and supplier geographic reach across hazardous facility deployments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with infrared sensor immunity to poisoning and extended calibration intervals commanding certification-grade premiums while electrochemical alternatives serve cost-sensitive municipal utilities. Price differentiation rests on SIL 2/3 functional safety ratings and factory-authorized service bundling. Cost compression in economy electrochemical tiers is intensifying because unbundled calibration subscriptions displace captive manufacturer contracts. Municipal utilities exhibit highest price sensitivity; semiconductor fabs and battery plants show lowest.
Supply Chain Analysis
Freight costs for photodetector arrays and optical path assemblies from Germany, Japan, and the United States concentrate premium sensor sourcing, with calibration equipment and reference gas cylinders adding specialized logistics complexity. Raw material dependencies span indium phosphide substrates, palladium catalyst beads, and ultraviolet lamp filaments. Single-source vulnerability in tunable diode laser absorption spectroscopy components creates procurement risk. Distribution runs through factory-authorized service networks clustering in Texas, Rotterdam, and Singapore, with independent providers capturing offshore maintenance volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between German chemical park calibration premiums and Indian greenfield deployment costs creates margin expansion potential for equipment vendors with modular sensor architectures.
For Market Incumbents: To counter unbundled calibration subscription models from independent service providers in Aberdeen and Stavanger, Honeywell and Dräger must deepen captive service network control through backward integration into reference gas production and SIL-certified technician certification programs in Asia-Pacific growth corridors. For New Entrants and Emerging Players: Direct-to-end-user cloud platform licensing offers bypass around incumbent calibration network lock-in, with Indian petrochemical zones and Southeast Asian battery manufacturing presenting the most penetrable white-space for photonic integrated circuit-based trace gas monitors sold through unbundled technical support subscriptions. For Investors and Strategic Acquirers: Consolidation pressure builds where photonic integrated circuit licensing agreements and captive calibration network density determine long-term contract renewal rates. Target specialist firms with dual-sensor architecture patents and established JIS T 8201 certification partnerships for hydrogen handling infrastructure exposure. Watch METI enforcement timelines and EU Green Deal methane monitoring mandates as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Licensing | Silicon-based platforms compress equipment footprints by 70% for pharmaceutical fermentation monitoring in Ireland and Switzerland. |
| Captive Calibration Network Expansion | Factory-authorized service density in Central Europe and Southeast Asia addresses logistical friction for distributed industrial sites. |
| Dual-Sensor Architecture Certification | Redundant gas detection systems meet METI hydrogen handling mandates and JIS T 8201 benchmarks effective March 2026. |
| Cloud Platform Convergence Partnership | Edge computing and 5G private networks enable predictive maintenance models for offshore platform operations in the North Sea. |
| Greenfield Deployment in Industrial Corridors | Gujarat and Tamil Nadu petrochemical zones lack integrated gas detection infrastructure, presenting fixed detector network opportunities. |
Research Approach
Direct dialogue with plant safety engineers, maintenance directors at petrochemical facilities, calibration service technicians, and semiconductor fab atmospheric monitoring specialists grounded qualitative assessment, cross-referenced with OSHA enforcement records, EPA air toxics compliance databases, METI industrial safety directive filings, and REACH chemical registration obligations to achieve bottom-up and top-down triangulation.
Segmentation outputs across device architecture, sensor technology principle, end-use industry vertical, and regional regulatory cluster informed the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycles, tightening exposure limit timelines, and capital expenditure patterns across battery manufacturing and semiconductor fabrication buildouts.
Regulatory enforcement delays, photonic integrated circuit yield rates, and hydrogen economy infrastructure buildout pace are the dominant revision risks to modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
US Law Enforcement PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safety and Eyewash Shower Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market