
 Industrial Fall Protection Equipment Market | 2026-2036
Industrial Fall Protection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Fall Protection Equipment Market Analysis
China is fragmenting as domestic manufacturers expand capacity for polyester webbing and forged alloy hardware. Petzl Group leverages vertical integration from rope extrusion to finished harness assembly, sustaining margin control across European and North American distribution. MSA Safety Incorporated anchors its position through respiratory and fall protection cross-selling, while Honeywell International Inc. competes via integrated safety platform bundling that spans gas detection, head protection, and confined-space systems.
Industrial fall protection equipment comprises body-worn devices, connecting components, and anchorage systems engineered to arrest falls from elevated work surfaces. Harnesses distribute impact forces across the thighs, pelvis, chest, and shoulders through load-rated webbing stitched to minimum 5,000-pound tensile strength, while self-retracting lifelines employ centrifugal braking mechanisms that lock within 24 inches of fall initiation. Harnesses and lanyards together occupy the largest product share, though lifelines represent the fastest-expanding category as continuous-connection systems displace point-to-point configurations in wind turbine and telecommunications tower maintenance. Construction dominates application demand, yet oil and gas commands premium pricing due to corrosion-resistant specifications and third-party certification requirements for offshore platforms.
OSHA Subpart M mandates fall protection at elevations above six feet in construction and four feet in general industry, directly shaping product design and inspection protocols across the United States. ANSI Z359 standards and CSA Z259 in Canada impose dynamic performance testing that manufacturers must satisfy for market access, while EU Directive 89/391 and subsequent framework regulations drive CE-marked equipment adoption across member states. Stakeholders must monitor evolving state-level adoption of OSHA's updated walking-working surfaces rule and assess how European CSRD reporting requirements reshape corporate safety investment disclosure.
Market Dynamics
OSHA's updated walking-working surfaces rule and EU Directive 89/391 enforcement are compressing inspection cycles and accelerating replacement demand across construction and general industry verticals. Equipment manufacturers face simultaneous pressure to certify products under ANSI Z359, CSA Z259, and CE marking frameworks while managing raw material volatility in polyester webbing and forged alloy hardware.
Growth Catalysts
- Federal infrastructure spending:United States construction contractors are expanding fleet purchases of full-body harnesses and self-retracting lifelines to meet accelerated project timelines and OSHA Subpart M compliance deadlines.
- Wind turbine maintenance expansion:Continuous-connection lifeline systems are displacing point-to-point configurations in tower climbing applications, driving category growth as turbine installations proliferate across onshore and offshore sites.
- EU workplace safety framework:Directive 89/391 and subsequent regulations mandate employer-provided fall protection across member states, creating sustained institutional demand for CE-marked equipment replacement.
Market Restraints
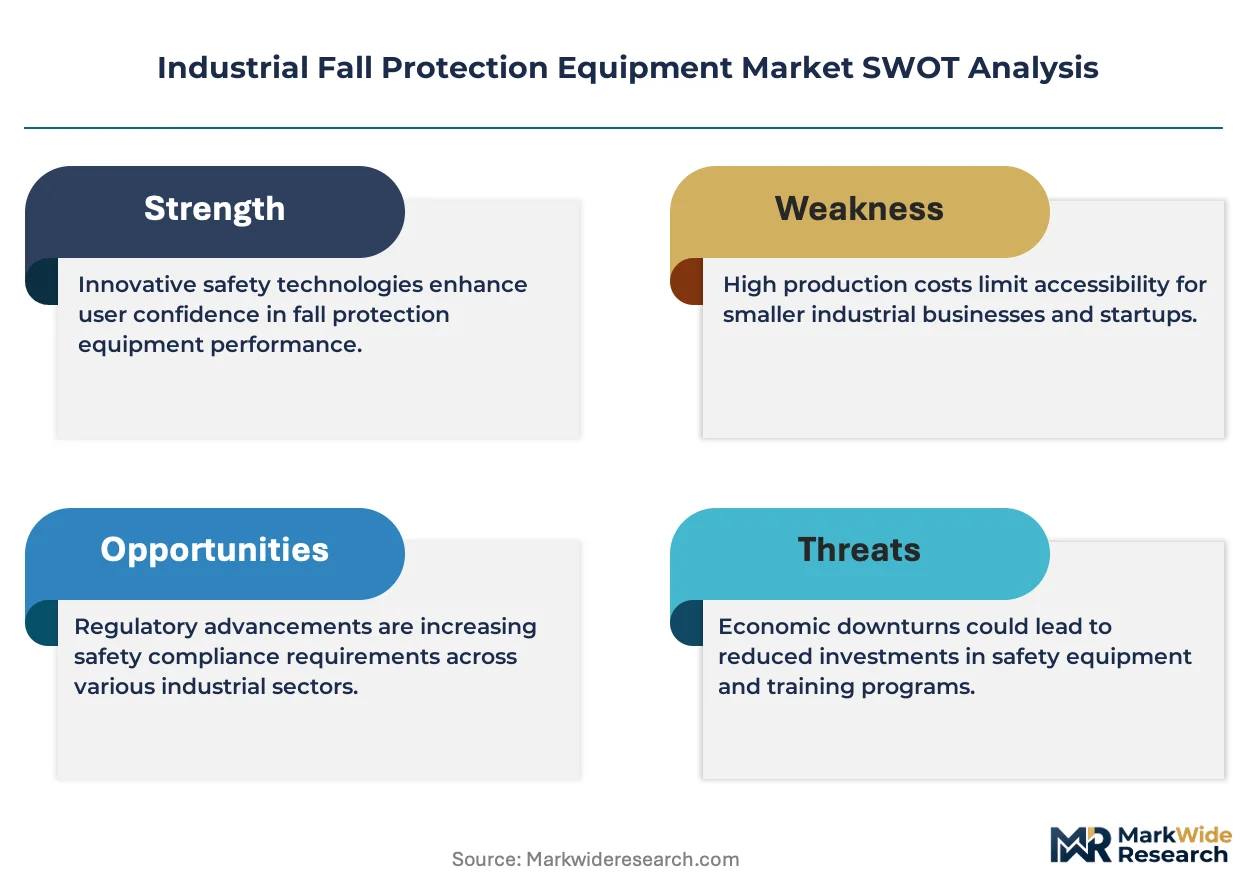
- Petrochemical input volatility:Polyester webbing and synthetic rope production faces cost pressure from crude oil derivative pricing swings, compressing margin stability for harness and lanyard manufacturers.
- Chinese manufacturing concentration:Domestic capacity expansion for forged alloy hardware and webbing assembly creates oversupply risk in mid-tier product segments, pressuring price realization for non-integrated competitors.
- Corrosion-resistant specification costs:Oil and gas offshore platforms require third-party certified equipment with marine-grade coatings, adding 15-25% material cost premiums that limit addressable market expansion.
Strategic Opportunities
- Telecommunications tower densification:5G infrastructure rollout across the United States and Germany is creating sustained demand for compact, lightweight climbing systems in urban and rural cell site maintenance.
- CSRD safety investment disclosure:European Corporate Sustainability Reporting Directive requirements are elevating fall protection expenditure visibility in corporate ESG filings, potentially accelerating budget allocation.
- Wearable sensor integration:Connected harnesses with fall-detection telemetry and geolocation tracking are hybridizing with traditional PPE, opening subscription-based monitoring revenue streams for equipment providers.
Industry Challenges
- Competent person training gaps:OSHA mandates qualified inspectors for harness and lifeline certification, yet construction and general industry employers report persistent shortages of certified safety personnel.
- Multi-standard certification timelines:Simultaneous ANSI Z359, CSA Z259, and CE marking testing extends product launch cycles by 8-14 months, delaying revenue recognition for new harness and connector designs.
- Legacy anchor system incompatibility:Existing building infrastructure often lacks engineered tie-off points rated for modern self-retracting lifeline loads, forcing costly structural retrofits or limiting equipment deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Fall Protection Equipment Market |
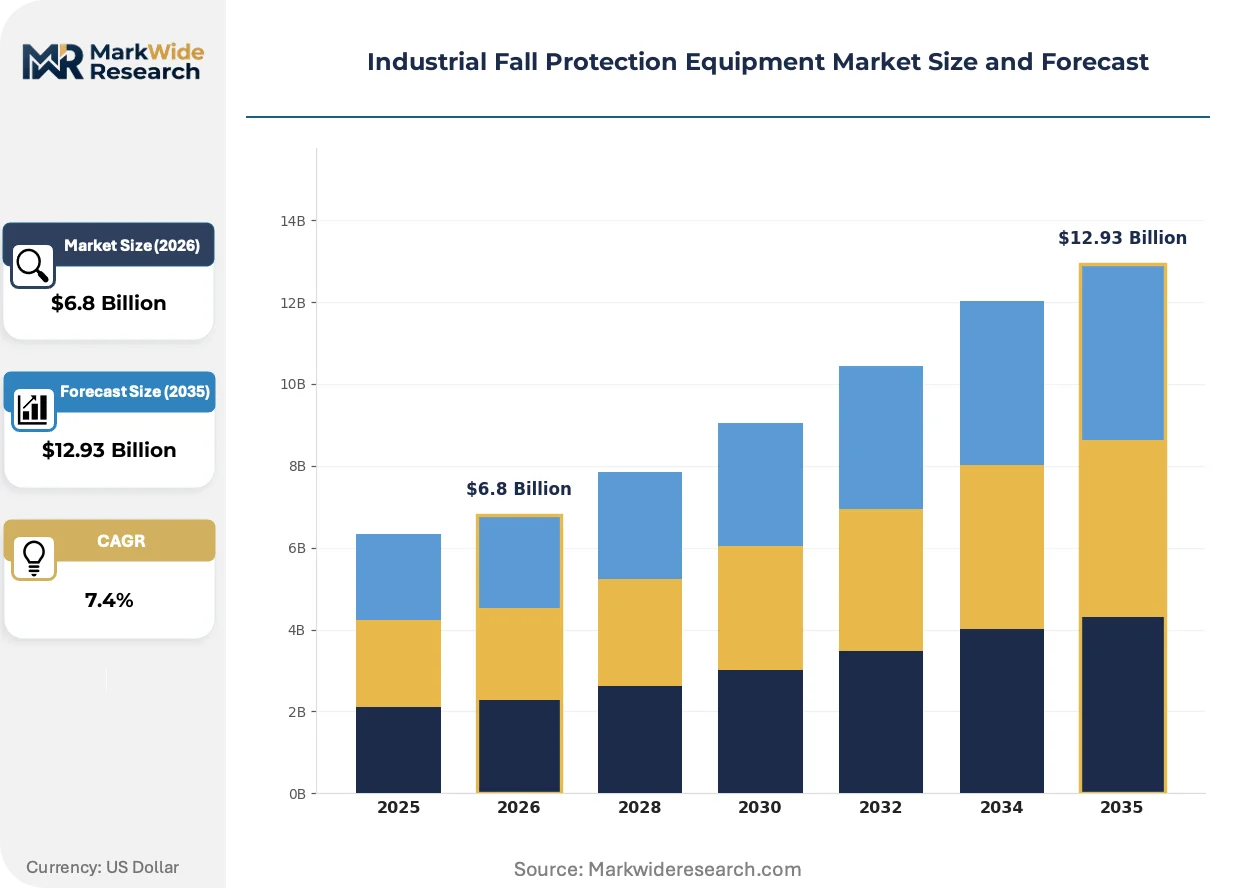
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harnesses, Lanyards, Lifelines, Anchor Points Application: Construction, Manufacturing, Maintenance, Oil & Gas End User: Contractors, Facility Managers, Oilfield Operators, Maintenance Personnel Regulatory Standard: OSHA, ANSI, CSA, EU Directive |
| Companies Covered | Petzl Group, FallTech, 3M Company, Skylotec GmbH, Guardian Fall Protection, Honeywell International Inc., WernerCo, Kee Safety Inc., MSA Safety Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Fall Protection Equipment Market Emerging Trajectories
Equipment design is converging around lighter materials, integrated connectivity, and modular component architectures that reduce worker fatigue while expanding compatibility across anchor configurations. These shifts are compressing traditional product lifecycles and reshaping supplier R&D priorities.
Advanced synthetic fibers including Dyneema and aramid blends are hybridizing with conventional polyester webbing in premium harness lines. Wind turbine technicians and telecommunications climbers are adopting these hybrid systems for their 40-50% weight reduction versus legacy designs. The structural consequence is tiered product stratification, with hybrid-equipped specialists commanding premium positioning while standard construction crews remain on conventional platforms.
EU Directive 89/391 and the updated CSRD disclosure framework are mandating documented fall protection investment in corporate sustainability reporting. Industrial employers across Germany, France, and the Netherlands must now quantify safety equipment expenditure in annual filings. Construction and logistics sectors are responding by consolidating vendor relationships to simplify audit trails and standardize procurement documentation.
Buyer organizations are compressing replacement cycles from annual to semi-annual inspection intervals for high-use harnesses and lanyards. Equipment rental channels and certified pre-owned programs are capturing share from direct manufacturer sales in the United States construction vertical. This behavioral shift is most visible among mid-sized contractors in Texas and Florida, where project volatility makes capital-light equipment access preferable to ownership.
Industrial Fall Protection Equipment Market Segmentation
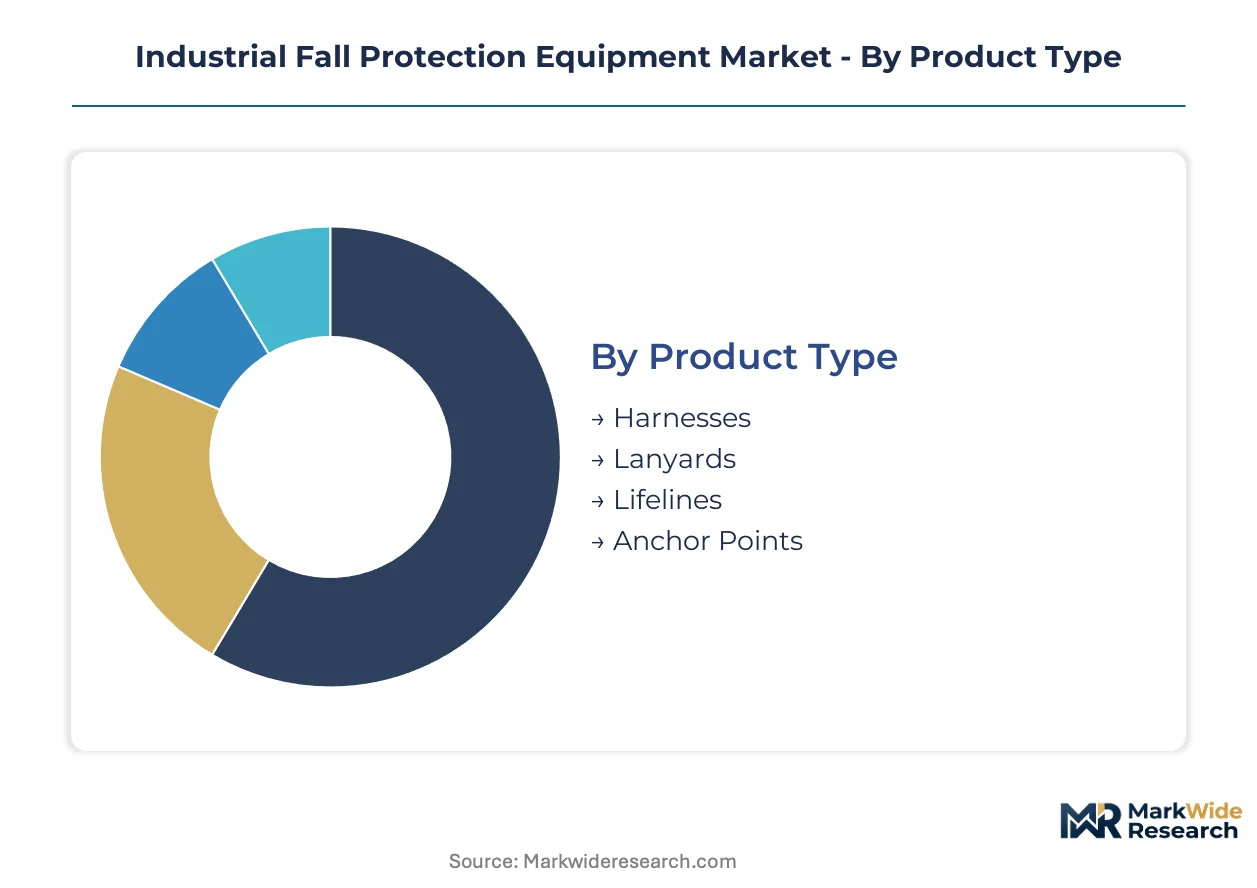
Equipment specification varies sharply across verticals, with construction contractors prioritizing durability cycles while oilfield operators demand corrosion-resistant certifications. Segmentation reveals how procurement patterns split between high-volume replacement markets and premium-specification niches.
Product Type:
Mature harness and lanyard platforms coexist with emerging lifeline technologies that displace point-to-point configurations in tower climbing applications.
- Harnesses:Full-body designs distribute impact forces across thighs, pelvis, chest, and shoulders through load-rated webbing stitched to minimum 5,000-pound tensile strength. United States construction contractors drive replacement cycles amid OSHA Subpart M enforcement and federal infrastructure project acceleration.
- Lifelines:Self-retracting systems employ centrifugal braking mechanisms that lock within 24 inches of fall initiation, with continuous-connection architectures gaining share in wind turbine and telecommunications tower maintenance. German and United States tower technicians are adopting these systems for their operational efficiency in vertical climbing sequences.
- Lanyards:Shock-absorbing webbing assemblies connect harnesses to anchor points, with energy-absorbing designs reducing peak arrest forces below 900 pounds.
- Anchor Points:Engineered tie-off devices rated for dynamic loads from self-retracting lifelines, often requiring structural retrofit in legacy building infrastructure.
Harnesses retain volume leadership; lifelines hold the steepest expansion curve.
Application:
Cost tier stratification separates high-frequency replacement markets from specification-intensive sectors commanding material premiums.
- Construction:General contractors and specialty trades consume the highest equipment volumes, with full-body harnesses and shock-absorbing lanyards dominating procurement. United States residential-commercial building activity sustains replacement cycles across union and non-union labor pools.
- Oil & Gas:Offshore platforms and onshore drilling operations require third-party certified equipment with marine-grade coatings, adding material cost premiums that limit supplier participation. North Sea and Gulf of Mexico operators enforce corrosion-resistant specifications through integrated safety contractor frameworks.
- Manufacturing:Assembly facilities and fabrication shops deploy fall protection for elevated platform work, with inspection intervals tied to production shift schedules.
- Maintenance:Industrial facility upkeep and infrastructure rehabilitation create episodic demand patterns, with rental channels capturing share from direct purchases.
Construction commands absolute volume; oil and gas delivers the highest margin realization per unit.
End User:
Customer type determines procurement channel preference, with large contractors consolidating vendor relationships while specialized operators demand technical support integration.
- Contractors:General and specialty construction firms purchase equipment through distributor networks or direct manufacturer relationships, with fleet standardization reducing inspection complexity. Texas and Florida mid-sized contractors increasingly favor rental programs over capital ownership.
- Facility Managers:Industrial plant operators maintain captive equipment inventories for maintenance personnel, with procurement decisions centralized through corporate safety departments.
- Oilfield Operators:Integrated petroleum companies and drilling contractors specify equipment through master service agreements, bundling fall protection with respiratory and gas detection systems.
- Maintenance Personnel:Individual technicians and small service firms acquire equipment through retail and e-commerce channels, with price sensitivity highest in this segment.
Contractors drive aggregate volume; oilfield operators concentrate spending in integrated safety platforms.
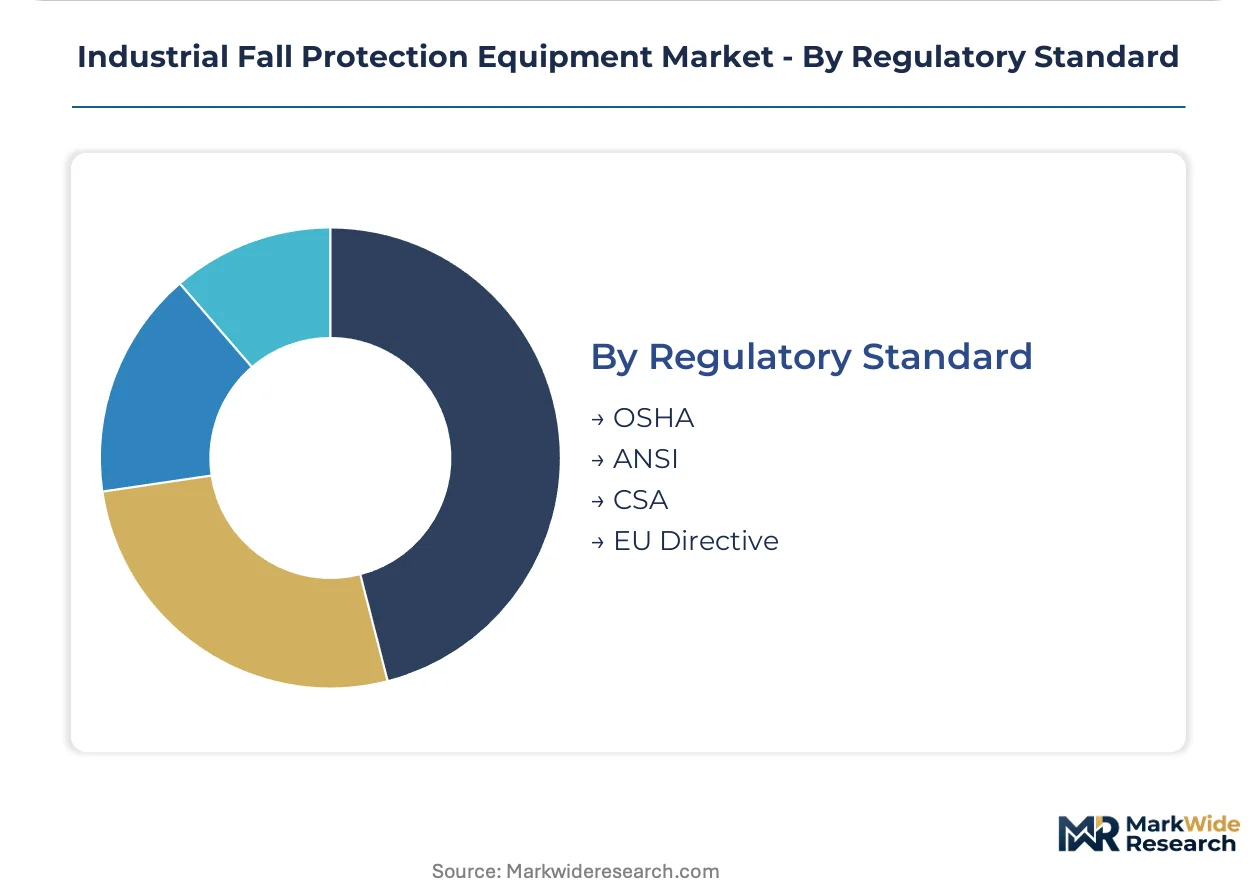
Regulatory Standard:
Geography dictates certification requirements, with multi-standard compliance extending product launch timelines and reshaping competitive access.
- OSHA:United States federal enforcement mandates fall protection at elevations above six feet in construction and four feet in general industry, directly shaping product design and inspection protocols. State-level adoption of updated walking-working surfaces rules compresses replacement cycles in California and New York.
- ANSI:Z359 standards impose dynamic performance testing that manufacturers must satisfy for United States market access, with third-party certification required for self-retracting lifeline assemblies.
- CSA:Z259 standards govern Canadian equipment approval, with harmonization gaps requiring separate testing protocols for cross-border suppliers.
- EU Directive:Framework regulations including Directive 89/391 mandate employer-provided fall protection across member states, with CE marking required for equipment distribution in Germany, France, and Netherlands markets.
OSHA governs the largest equipment volume; EU Directive compliance opens the most fragmented multi-country access pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for polyester webbing and forged alloy hardware concentrates in China, while specification-intensive design and certification activity clusters in Germany and the United States. Equipment procurement volumes align with construction spending intensity and regulatory enforcement rigor across national markets.
United States
Federal infrastructure spending and residential-commercial building activity sustain replacement cycles for full-body harnesses and self-retracting lifelines. OSHA Subpart M mandates fall protection at elevations above six feet in construction, compressing inspection intervals and accelerating fleet turnover. Texas and Florida mid-sized contractors increasingly favor rental programs over capital ownership amid project volatility.
Germany
Wind turbine maintenance operations drive demand for continuous-connection lifeline systems in tower climbing applications. EU Directive 89/391 mandates employer-provided fall protection across member states, with CE marking required for equipment distribution. Industrial employers in Bavaria and North Rhine-Westphalia must now quantify safety equipment expenditure in annual CSRD filings.
China
Domestic manufacturers expand capacity for polyester webbing and forged alloy hardware, fragmenting supply and creating oversupply risk in mid-tier product segments. GB standards govern equipment approval, though export-oriented producers seek ANSI Z359 and CE marking for North American and European market access. Production clusters concentrate in Zhejiang and Guangdong provinces.
Canada
CSA Z259 standards impose dynamic performance testing requirements that manufacturers must satisfy for market access, with harmonization gaps requiring separate testing protocols for cross-border suppliers. Oil and gas operations in Alberta command corrosion-resistant specifications with marine-grade coatings for offshore platforms. Ontario construction contractors anchor procurement volumes in the residential-commercial vertical.
France
EU Directive 89/391 enforcement drives sustained institutional demand for CE-marked equipment replacement across construction and general industry verticals. ANSM and labor inspectorates coordinate workplace safety audits, elevating compliance visibility in corporate procurement decisions. Industrial clusters in Île-de-France and Auvergne-Rhône-Alpes concentrate maintenance personnel demand for rental channel access.
Industrial Fall Protection Equipment Market Vendor Landscape
Vertically integrated specialists and diversified safety conglomerates split the market between margin-controlled premium positioning and cross-selling scale economies. The vendor base organizes around three archetypes: rope-to-harness integrators maintaining captive supply chains, respiratory-and-protection bundlers leveraging installed base relationships, and component-focused fabricators competing on volume throughput. Dominant competitive moves include backward integration into webbing extrusion and alloy forging, plus geographic expansion through distributor network consolidation.
Within the integration-focused tier, Petzl Group and Skylotec GmbH exemplify European-origin specialists with captive manufacturing control from fiber extrusion through finished assembly. MSA Safety Incorporated anchors the diversified conglomerate archetype, cross-selling fall protection with respiratory and gas detection systems through integrated safety contractor frameworks. Honeywell International Inc. occupies a position within the platform-bundling segment, spanning gas detection, head protection, and confined-space systems through unified procurement channels.
| Leading Market Players |
|---|
| Petzl Group |
| FallTech |
| 3M Company |
| Skylotec GmbH |
| Guardian Fall Protection |
| Honeywell International Inc. |
| WernerCo |
| Kee Safety Inc. |
| MSA Safety Incorporated |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Los Angeles freight corridor's rate volatility transmits directly into landed cost spreads for polyester webbing and forged alloy hardware, amplifying margin pressure for non-integrated distributors while rewarding manufacturers with captive extrusion and forging operations. This logistics tension concentrates pricing power among vertically controlled suppliers and forces tiered cost absorption strategies across import-dependent mid-tier competitors.
Pricing Analysis
OSHA Subpart M and ANSI Z359 certification tiers dictate the pricing tier structure across harness, lanyard, and lifeline categories. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European-origin equipment from domestic ANSI-certified platforms and unbranded import alternatives. Certification grade and volume scale serve as primary price differentiation drivers, with oil and gas buyers showing lowest price sensitivity due to third-party mandate requirements. Cost compression in mid-tier polyester webbing is intensifying because Chinese domestic capacity expansion feeds oversupply into export channels.
Supply Chain Analysis
Contract manufacturing for forged alloy hardware concentrates among Zhejiang and Guangdong province specialists serving Petzl Group, Skylotec GmbH, and MSA Safety Incorporated assembly operations. Geographic supply concentration centers on China for webbing extrusion and hardware forging, Germany for precision engineering and certification testing, and the United States for finished goods distribution. Raw material dependencies rest on petrochemical derivatives for synthetic fibers, zinc-aluminum alloys for corrosion-resistant connectors, and Dyneema fiber imports for premium hybrid harness lines. Single-source vulnerability in Chinese webbing capacity creates supply chain risk. Distribution runs through industrial safety distributors, direct OEM sales forces, and emerging rental channel platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defensive structure where ANSI Z359 and CE marking certification timelines create switching costs that entrench incumbent positions. Network effects concentrate among vertically integrated manufacturers with captive fiber extrusion and distributor relationships.
For Market Incumbents: Pre-empt Chinese import encroachment by accelerating backward integration into polyester webbing extrusion and establishing certified pre-owned equipment rental platforms. Threat from domestic Chinese manufacturers with GB-standard export capacity demands upstream control over raw material quality and inspection documentation. Certification investment in simultaneous ANSI Z359, CSA Z259, and CE marking testing protocols serves as the priority defensive lever.
For New Entrants and Emerging Players: Build out wearable sensor integration capabilities for connected harness telemetry, targeting telecommunications tower maintenance contractors in Texas and Florida as the most penetrable buyer segment. White-space opportunity exists in subscription-based fall-detection monitoring services bundled with hardware procurement. Go-to-market angle should emphasize geolocation tracking and incident response integration for 5G infrastructure rollout contractors.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized fall protection divisions lacking vertical integration into fiber extrusion or captive distribution channels. Long-term viability over the projection horizon rests on regulatory entrenchment and replacement cycle predictability. Acquisition target archetype: mid-tier harness assemblers with ANSI certification but without upstream webbing control. Signal to watch is OSHA state-level adoption pace of updated walking-working surfaces rules as inflection indicator for replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Webbing Extrusion | Captive polyester fiber production insulates Petzl Group and Skylotec GmbH from petrochemical input volatility. |
| Wearable Sensor Platform Development | Connected harness telemetry opens recurring revenue streams for MSA Safety Incorporated and Honeywell International Inc. |
| Certified Pre-Owned Rental Program Launch | Equipment-as-a-service models capture Texas and Florida contractor demand amid project volatility cycles. |
| Multi-Standard Certification Investment | Simultaneous ANSI Z359, CSA Z259, and CE marking testing accelerates revenue recognition across North American and European access pathways. |
| Telecommunications Tower Specialist Distribution | 5G infrastructure densification in Germany and the United States creates concentrated demand for compact climbing systems. |
Methodological Framework
A standing panel of safety directors at general contracting firms, fall protection equipment procurement managers, ANSI Z359 certification engineers, and industrial distributor account executives provided ongoing calibration across primary interview cycles. Secondary validation drew from OSHA enforcement action databases, ANSI standards revision documentation, SEC 10-K filings of listed safety equipment manufacturers, and EU CE marking notification body records. Bottom-up equipment unit economics triangulated against top-down construction spending and regulatory compliance cost estimates.
Scenario bracketing anchored the analytical framework across the projection horizon, with demand segmentation modeled by product type, application vertical, end-user procurement channel, and regulatory standard jurisdiction. CAGRs derived from replacement cycle frequency analysis, infrastructure project pipeline tracking, and enforcement intensity indexing. Industry-specific forecast inputs included wind turbine installation cadence and telecommunications tower climbing activity metrics.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic manufacturers with GB-standard export ambitions or integrated safety platform bundlers would shift outcomes. Quarterly review of OSHA state-level rule adoption, EU CSRD safety expenditure disclosure filings, and Chinese polyester webbing capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Rodent Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Digital Camlock Market
Safety Equipment and Personal Protective Equipment (PPE)
Anesthetic Gas Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
US Negative Pressure Escape Masks Market