
 UK Critical Infrastructure Protection Market | 2026-2036
UK Critical Infrastructure Protection Market Size, Share, and Industry Trends Forecast 2026-2036
UK Critical Infrastructure Protection Market Analytics
Cybersecurity talent scarcity is reorganizing how the UK Critical Infrastructure Protection Market structures its supplier base, pushing incumbents toward deeper automation and managed service models. BAE Systems PLC leverages its defence heritage to dominate high-assurance government contracts. Sophos Group PLC competes through cloud-native security architectures tailored to mid-tier utility operators. G4S PLC anchors physical security integration with its manned guarding infrastructure spanning transport and energy sites.
UK Critical Infrastructure Protection encompasses the coordinated deployment of surveillance, access control, fire suppression, and cyber defence systems to safeguard assets essential to national security, economic stability, and public safety. These systems typically integrate real-time threat detection with automated incident response protocols operating across both operational technology and information technology networks. Cybersecurity services command the strongest margin pools as ransomware attacks against utilities and transport operators intensify. Physical Security applications retain the largest revenue base but face slower growth as digitization shifts budget toward cyber-physical convergence. Consulting services around risk assessment are expanding fastest among service types as operators confront complex multi-vector threat environments.
The Centre for the Protection of National Infrastructure shapes procurement standards through its protective security guidance, mandating baseline resilience measures across government agencies and regulated utilities. The UK National Cyber Security Centre enforces incident reporting requirements that compel operators to invest in continuous monitoring and threat intelligence capabilities. The National Security and Investment Act empowers the government to block or unwind transactions involving critical infrastructure, altering foreign vendor market access and domestic supply chain composition. Stakeholders must weigh the trade-off between proprietary technology control and the interoperability demanded by integrated national resilience frameworks.
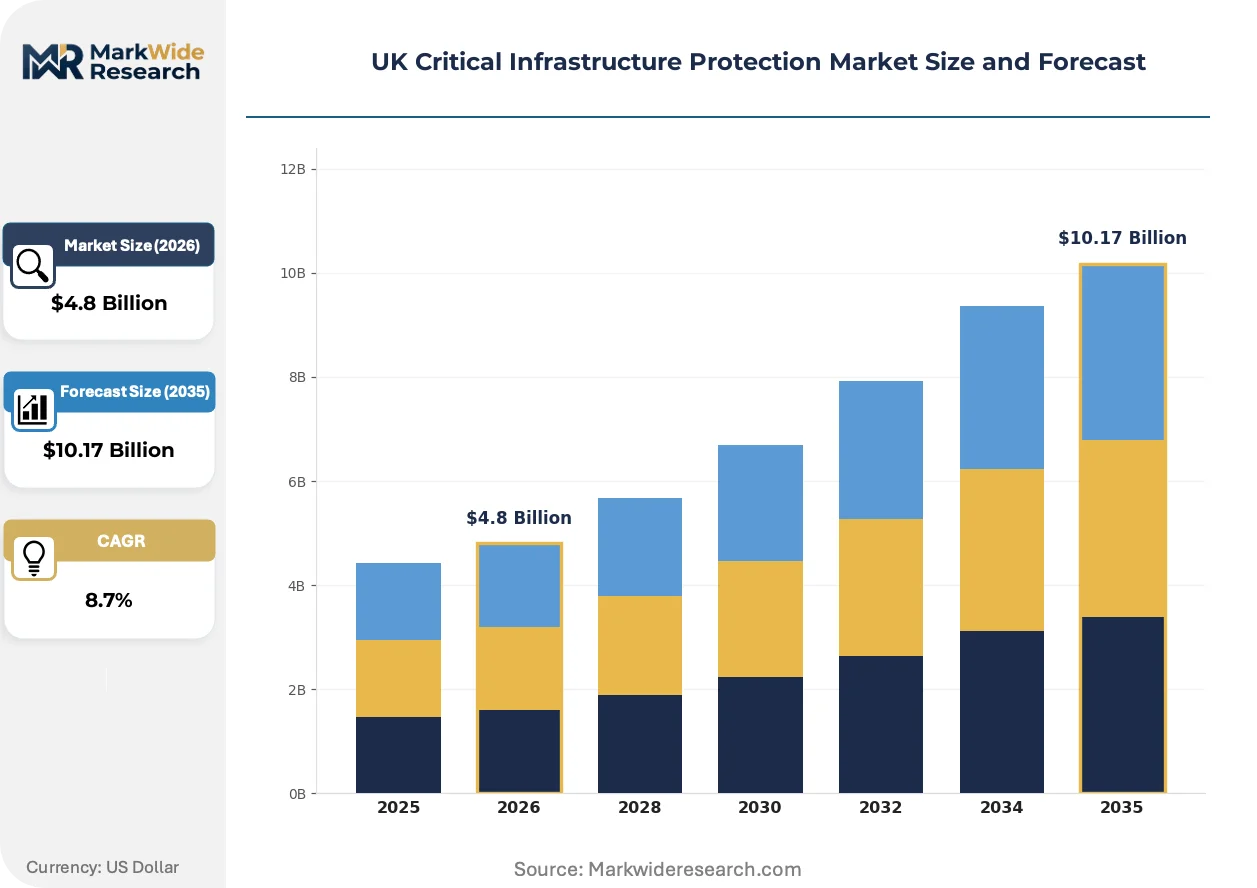
Market Dynamics
The UK Critical Infrastructure Protection Market is undergoing structural reconfiguration as the National Security and Investment Act tightens foreign ownership screening, forcing domestic supply chain consolidation and accelerating public-private security partnerships across energy, transport, and digital infrastructure nodes.
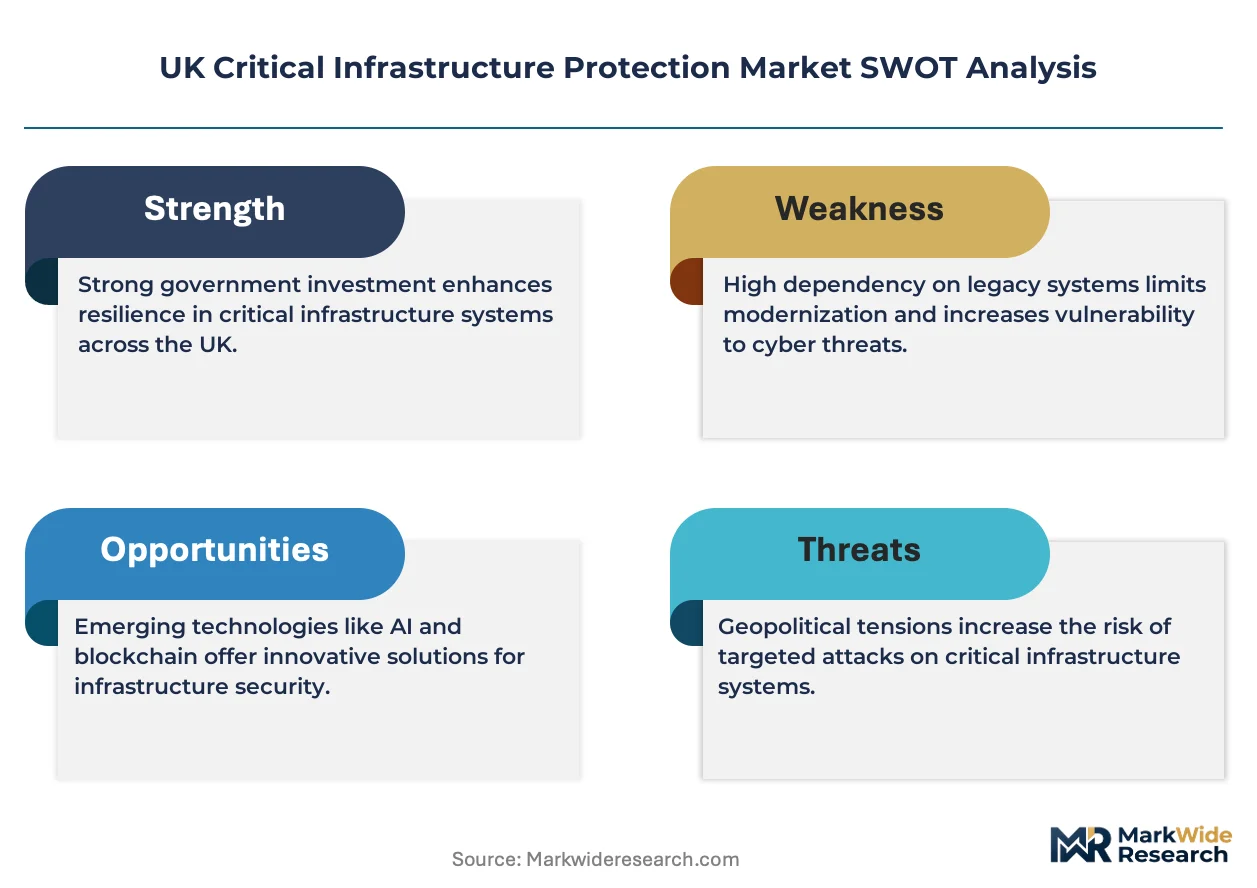
Growth Catalysts
- Regulatory Mandates:The Centre for the Protection of National Infrastructure's protective security guidance mandates baseline resilience measures across regulated utilities, compelling systematic security upgrades.
- Cyber-Physical Convergence:Operational technology and information technology network integration is creating unified procurement budgets for combined physical surveillance and cyber defence platforms.
- London Financial District Concentration:Critical data centre clustering in the City of London and Thames Valley corridor generates concentrated demand for high-assurance integrated security systems.
Market Restraints
- Specialised Engineering Talent Scarcity:Shortage of professionals credentialed in both industrial control systems and cybersecurity is compressing deployment timelines and inflating implementation costs.
- Foreign Vendor Access Restrictions:The National Security and Investment Act's screening mechanisms are limiting technology transfer from certain overseas suppliers, constraining component sourcing flexibility.
- Legacy System Integration Friction:Decades-old operational technology infrastructure in water and energy utilities resists seamless interfacing with modern cyber-physical platforms.
Strategic Opportunities
- Managed Security Service Expansion:Mid-tier utility operators lacking in-house cyber expertise are creating demand for outsourced continuous monitoring and threat intelligence capabilities.
- Scottish Renewables Infrastructure:Offshore wind expansion in Scottish waters requires new physical and cyber protection frameworks for geographically dispersed generation assets.
- AI-Driven Threat Detection:Machine learning-powered anomaly detection converging with automated incident response is opening premium service tiers for critical national infrastructure operators.
Industry Challenges
- Cross-Domain Certification Complexity:Security professionals must simultaneously satisfy CPNI physical security standards and NCSC cyber assurance frameworks, elongating workforce development cycles.
- Multi-Vector Attack Surface Management:Operators must defend converged OT-IT environments against simultaneous physical intrusion and ransomware campaigns, straining security operations centre capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Critical Infrastructure Protection Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Risk Assessment, Compliance Management, Incident Response End User: Government Agencies, Utilities, Telecommunications, Transportation Technology: Surveillance Systems, Access Control, Fire Protection, Cybersecurity Application: Threat Detection, Vulnerability Management, Emergency Response, Physical Security |
| Companies Covered | BAE Systems PLC, Vision Security Group Ltd, Silobreaker Limited, Wilson James Ltd, Sophos Group PLC, Acuity Risk Management Limited, G4S PLC, Advance Security (United Kingdom) Limited, BT Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Critical Infrastructure Protection Market Evolving Landscape
Technological substitution and regulatory tightening are compressing product lifecycles across the UK Critical Infrastructure Protection Market, with automation and service-based delivery models displacing traditional capital-intensive security procurement.
Zero-trust network architectures are displacing perimeter-based security models in UK utility and transport operator environments. Water companies and regional rail networks are adopting micro-segmentation at pace, driven by NCSC guidance. This shift is compressing demand for legacy firewall hardware while expanding recurring revenue pools for identity and access management services.
The UK's National Security and Investment Act is reshaping vendor eligibility criteria for sensitive infrastructure contracts. Industrial consequence includes mandatory domestic supply chain substantiation for critical component categories. Energy sector procurement teams are responding by pre-qualifying UK-registered security integrators ahead of foreign competitors.
Outcome-based service contracting is replacing traditional equipment purchase models among Thames Valley data centre operators. Fixed-fee managed detection and response agreements are supplanting capital expenditure cycles for threat monitoring infrastructure. This pattern is most visible in London's colocation facilities, where operational expenditure predictability outweighs ownership preferences.
UK Critical Infrastructure Protection Market Segmentation
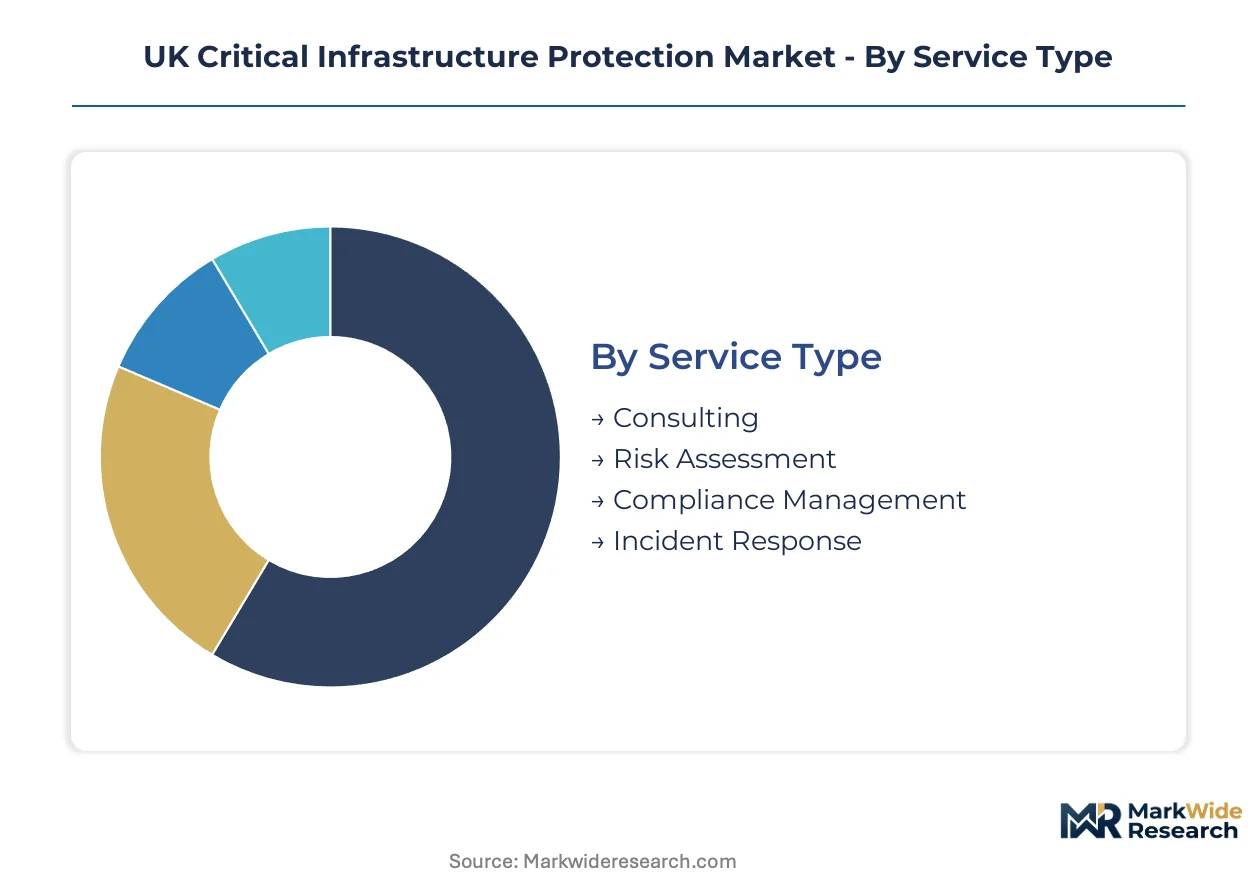
Segmentation in UK Critical Infrastructure Protection reveals how procurement budgets fragment across converging cyber-physical domains. Understanding these divides exposes where vendor specialization creates defensible positions versus where integration pressure erodes traditional category boundaries.
Service Type:
Substitution pressure concentrates in commoditized compliance documentation services, while high-touch advisory functions resist automation displacement.
- Consulting:Strategic advisory encompassing security architecture design and resilience planning for CNI operators. Demand clusters around Thames Valley data centre developments where multi-vector threat modelling requires bespoke engagement.
- Risk Assessment:Systematic evaluation of vulnerabilities across operational technology and physical perimeters. Water utilities in England's regional monopolies are expanding procurement here as Ofwat resilience requirements tighten.
- Compliance Management:Ongoing adherence monitoring against CPNI protective security guidance and sector-specific mandates.
- Incident Response:Retained capabilities for breach containment and forensic investigation following cyber-physical intrusions.
Consulting retains volume leadership; Incident Response holds the steepest expansion curve.
End User:
Customer-type stratification shows government agencies commanding premium pricing power while utilities face the steepest cost-to-value compression.
- Government Agencies:Central government departments and devolved administrations procuring sovereign-grade protection for classified facilities. NCSC-mandated continuous monitoring requirements are driving sustained budget allocation across Whitehall and Scottish Government sites.
- Utilities:Energy, water, and wastewater operators subject to sector-specific resilience regulation. Offshore wind developers in Scottish waters are emerging as high-growth spenders on geographically dispersed asset protection.
- Telecommunications:Network operators safeguarding 5G infrastructure and submarine cable landing stations.
- Transportation:Rail, aviation, and port authorities managing passenger safety and freight continuity.
Utilities dominate procurement volume; telecommunications infrastructure builds are climbing fastest.
Technology:
Technology maturity gradients separate legacy physical systems facing digitization pressure from native cyber platforms capturing incremental margin.
- Surveillance Systems:Video analytics and perimeter monitoring hardware integrated with command-and-control centres. London's financial district colocation facilities are upgrading to AI-enhanced optical detection following 2023 regulatory guidance.
- Access Control:Biometric and credential-based entry management spanning personnel and vehicle flows. Nuclear licenced sites are driving demand for multi-factor authentication convergence with cyber identity systems.
- Fire Protection:Detection, suppression, and compartmentalization systems for critical facility integrity.
- Cybersecurity:Network defence, endpoint protection, and operational technology security for converged environments.
Surveillance Systems maintain the largest installed base; Cybersecurity demonstrates the most rapid share gain.
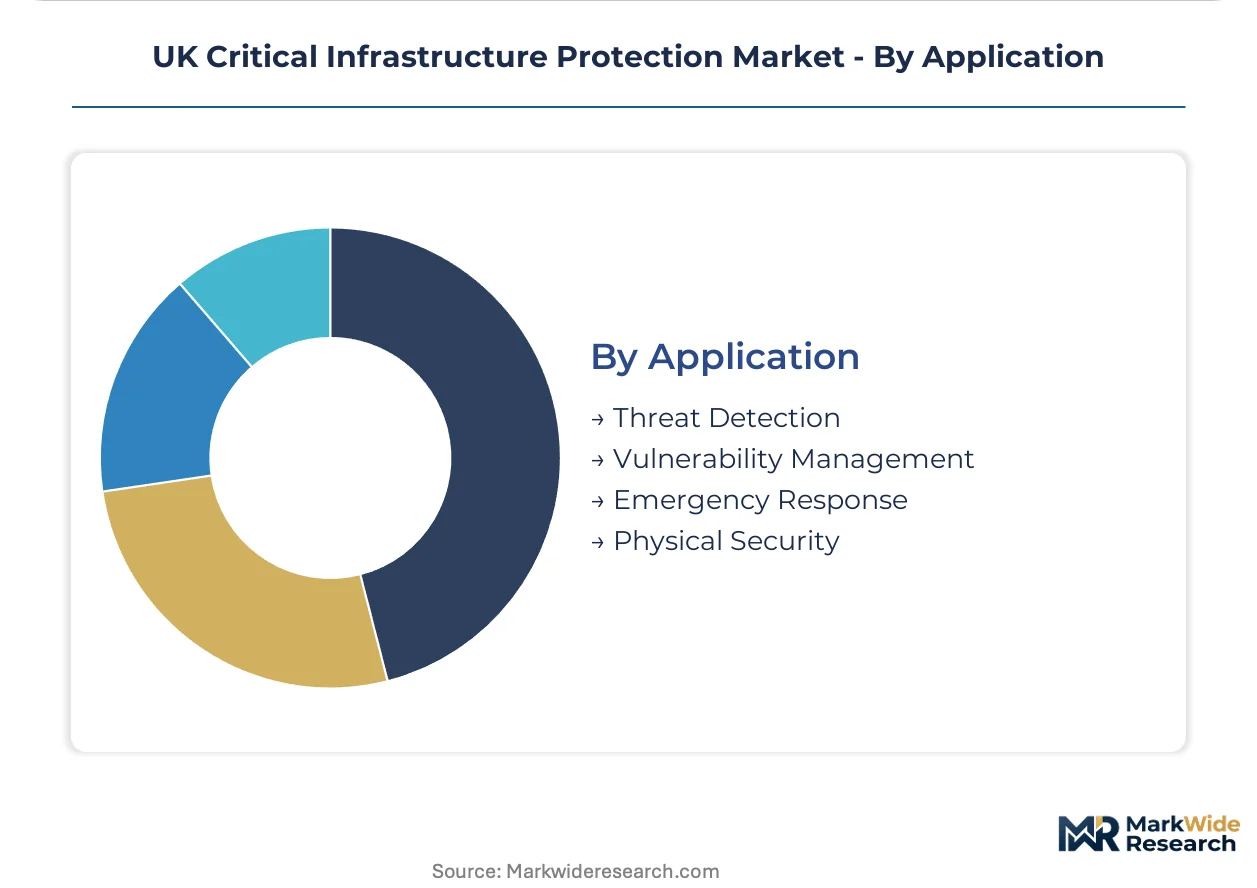
Application:
Application-layer segmentation tracks how operational expenditure shifts from reactive physical guarding toward predictive threat intelligence.
- Threat Detection:Real-time identification of anomalous behaviour across cyber and physical domains. National rail infrastructure operators are deploying sensor fusion platforms combining network traffic analysis with platform surveillance.
- Vulnerability Management:Continuous scanning and remediation prioritization for attack surface reduction. Regional water companies are procuring managed services here to address OT-IT convergence gaps.
- Emergency Response:Coordinated mobilization protocols for business continuity and public safety.
- Physical Security:Manned guarding, barriers, and environmental hardening of critical sites.
Physical Security commands the greatest absolute spend; Threat Detection is expanding most quickly as AI-enabled platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland's offshore wind expansion demands protection frameworks for geographically dispersed assets, while London's financial district concentrates spending on data centre security. This geographic split between distributed generation and clustered digital infrastructure shapes divergent procurement patterns across the UK.
London and the Southeast
The City of London and Thames Valley corridor host the densest concentration of critical data centres and financial infrastructure. NCSC-mandated continuous monitoring requirements drive sovereign-grade cybersecurity procurement across colocation facilities. Operators here are shifting toward outcome-based managed detection contracts rather than capital expenditure cycles.
Scotland
Offshore wind developments in Scottish waters require new physical and cyber protection frameworks for remote generation assets. The Scottish Government's resilience procurement aligns with UK-wide CPNI standards while addressing devolved infrastructure priorities. Aberdeen's energy sector expertise is transferring into offshore wind security integration.
North England
Industrial legacy infrastructure in Yorkshire and the Humber presents acute legacy system integration challenges for water and energy utilities. Regional monopolies under Ofwat resilience requirements are expanding risk assessment procurement. Manchester's emerging technology corridor is attracting cyber-physical security vendors.
Wales
Energy transition infrastructure and port facilities drive protection demand along Welsh coastlines. The Welsh Government's infrastructure investment programme intersects with UK national security frameworks. Milford Haven's energy terminal complex anchors physical security spending in the region.
Midlands
Transport nodes including Birmingham's rail hub and East Midlands logistics corridors concentrate physical security integration demand. CPNI protective security guidance mandates systematic upgrades across regional transport authorities. Coventry's automotive and battery manufacturing sites are emerging as cyber-physical convergence priorities.
UK Critical Infrastructure Protection Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed competitive structure. Defence heritage contractors dominate high-assurance government contracts through established security clearances and sovereign capability claims. Mid-tier specialists compete on cloud-native architectures and managed service flexibility. The dominant competitive moves are strategic partnerships bridging cyber and physical domains, and portfolio diversification into converged OT-IT protection.
Among UK-based defence contractors, BAE Systems PLC exemplifies the integrated leader archetype through its high-assurance government positioning. Sophos Group PLC and G4S PLC represent contrasting specialist paths—cloud-native cyber platforms and physical guarding infrastructure respectively. These three anchors illustrate how vendor eligibility criteria under the National Security and Investment Act are reshaping competitive access to sensitive infrastructure contracts.
| Leading Market Players |
|---|
| BAE Systems PLC |
| Vision Security Group Ltd |
| Silobreaker Limited |
| Wilson James Ltd |
| Sophos Group PLC |
| Acuity Risk Management Limited |
| G4S PLC |
| Advance Security (United Kingdom) Limited |
| BT Group |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for industrial control system components concentrate pricing power among UK-registered security integrators eligible under the National Security and Investment Act, while compressed inventory cycles for cyber-physical platforms intensify cost pass-through to mid-tier utility operators lacking sovereign-grade procurement channels.
Pricing Analysis
Long-term managed service contracts dominate high-assurance government procurement, while project-based pricing prevails among Thames Valley data centre operators seeking operational expenditure predictability. Three-tier pricing structure across sovereign-grade, commercial-grade, and commodity-grade certification levels reflects CPNI protective security guidance alignment. Pricing pressure stems from talent scarcity inflating implementation costs for converged OT-IT deployments. Government agencies exhibit lowest price sensitivity given NCSC-mandated continuous monitoring requirements; regional water utilities under Ofwat resilience mandates face steepest cost-to-value compression.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for optical detection hardware and biometric sensor components sourced from Taiwan, South Korea, and Germany. UK critical infrastructure protection draws from semiconductor fabs in Taiwan, industrial control system manufacturers in Germany, and cloud-native security software development in the United States. Single-source vulnerability concentrates in sovereign-cleared component categories subject to National Security and Investment Act screening. Distribution runs through CPNI-accredited security integrators with established government security clearances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Critical Infrastructure Protection Market is approaching a platform-economics inflection as NCSC-mandated interoperability standards force vendor consolidation around unified cyber-physical command architectures, collapsing point-solution margins into ecosystem orchestration premiums.
For Market Incumbents: Consolidate around managed detection and response capabilities to offset margin compression from AI-driven automation displacing traditional physical guarding contracts. Acquire CPNI-accredited mid-tier specialists in Scottish offshore wind security to preempt foreign vendor exclusion under tightened ownership screening. Deepen vertical integration into operational technology security software to capture recurring revenue pools as Thames Valley data centres shift toward outcome-based contracting.
For New Entrants and Emerging Players: NCSC Cyber Essentials Plus certification fast-tracks vendor eligibility for Whitehall and devolved administration contracts previously captured by defence heritage incumbents. White-space concentrates in AI-enhanced sensor fusion for national rail infrastructure and automated threat detection for geographically dispersed Scottish renewables assets. Channel partnerships with established CPNI-accredited integrators accelerate credibility transfer without sovereign clearance investment.
For Investors and Strategic Acquirers: Carve-out targets emerge from defence contractors divesting non-core physical security divisions amid cyber-physical convergence pressures. Five-to-ten-year viability hinges on OT-IT integration depth rather than legacy guarding scale. Acquisition focus: cloud-native security platforms with existing NCSC assured service connections. Signal to watch: Scottish Government devolved procurement diverging from UK-wide frameworks to favor local supply chain substantiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies cyber-physical command centres under NCSC interoperability mandates, collapsing point-solution procurement. |
| Managed Security Service Expansion | Captures recurring revenue as Thames Valley data centres abandon capital expenditure cycles for outcome-based contracts. |
| Acquisition of Specialist Firm | Consolidates CPNI-accredited capabilities in Scottish offshore wind protection ahead of foreign vendor exclusion. |
| Strategic Partnership | Accelerates new entrant credibility transfer through channel alliances with established government security clearances. |
| Geographic Expansion | Targets Manchester technology corridor and Scottish renewables clusters as London financial district saturates. |
Research Methodology
The analysis maps cyber-physical security platforms, managed service delivery models, and protective security compliance services, each validated through security operations centre directors, CPNI protective security consultants, utility resilience officers, and defence procurement officials. Primary fieldwork combined structured interviews with secondary validation against NCSC incident reporting databases, CPNI protective security guidance documentation, Ofwat resilience requirement filings, and National Security and Investment Act transaction screening records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the UK critical infrastructure value chain.
Consistency checks validated volume and value outputs against external benchmarks including sector-specific procurement disclosures and regulatory compliance expenditure patterns. The analytical framework modeled service type, end user, technology, and application dimensions across the projection horizon, with particular attention to cyber-physical convergence intensity and sovereign-grade certification tier. CAGRs derived from regression analysis of historical procurement cycles and regulatory mandate implementation timelines, incorporating offshore wind capacity buildout trajectories and data centre colocation expansion as industry-specific demand drivers.
Decision-makers should treat outputs as directional under assumptions of continued National Security and Investment Act enforcement and stable NCSC guidance evolution; material deviation in foreign ownership screening intensity or protective security mandate scope would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Infrastructure Protection Market
Critical Infrastructure Protection
Middle East and Africa Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
Europe Pipeline Security Market
Critical Infrastructure Protection
Tele Protection Market
Critical Infrastructure Protection
Global Hazardous Area Equipment Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Railway Platform Security Market
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Insider Threat Protection Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Utilities Security Market
Critical Infrastructure Protection
Blast Resistant and Bulletproof Buildings Market
Critical Infrastructure Protection
Europe Tank Protection Market