
 Deflagration Flame Arresters Market | 2026-2036
Deflagration Flame Arresters Market Size, Share, and Industry Trends Forecast 2026-2036
Deflagration Flame Arresters Market Analytics
Multi-source procurement for critical safety components is restructuring supply relationships across the deflagration flame arrester industry. Emerson Electric Co. leverages its integrated automation platform to bundle flame safety with process control systems. PROTEGO Braunschweiger Flammenfilter GmbH anchors its position through German-engineered mechanical arresting technology and deep specialization in ATEX-certified designs. Elmac Technologies competes from the United Kingdom with focused engineering on offshore and marine applications.
Deflagration flame arresters are passive safety devices constructed from wound metal ribbons or sintered metal matrices with precisely controlled channel gaps measured in millimeters, designed to quench propagating flames by extracting heat through thermal conduction while permitting gas flow. Horizontal arresters dominate pipeline installations due to standardized mounting configurations and lower pressure drop characteristics, though hybrid technology combining thermal and mechanical quenching elements is gaining share in high-cycle chemical processing environments. Inline configurations occupy the densest margin pool because they integrate directly into existing piping infrastructure without vessel modifications, reducing total installed cost for retrofit projects.
OSHA's Process Safety Management standards and the EPA's Risk Management Program mandate flame arrester deployment in facilities handling flammable substances above threshold quantities. The EU's ATEX Directive 2014/34/EU and ISO 16852 certification requirements shape product design standards and market access across European chemical processing. Stakeholders must monitor evolving hydrogen economy infrastructure codes, as electrolysis and ammonia cracking applications introduce new deflagration risk profiles requiring adapted arrester specifications.
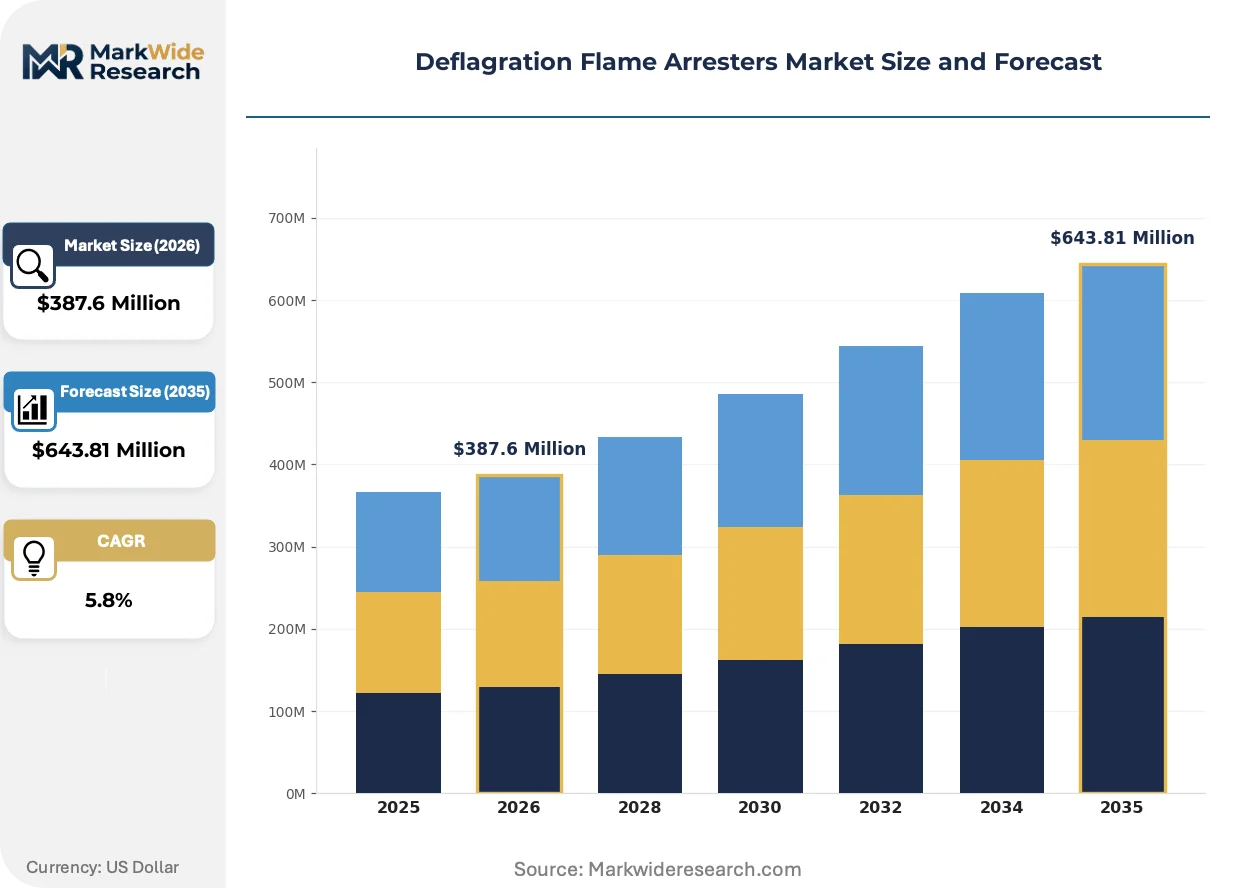
Market Dynamics
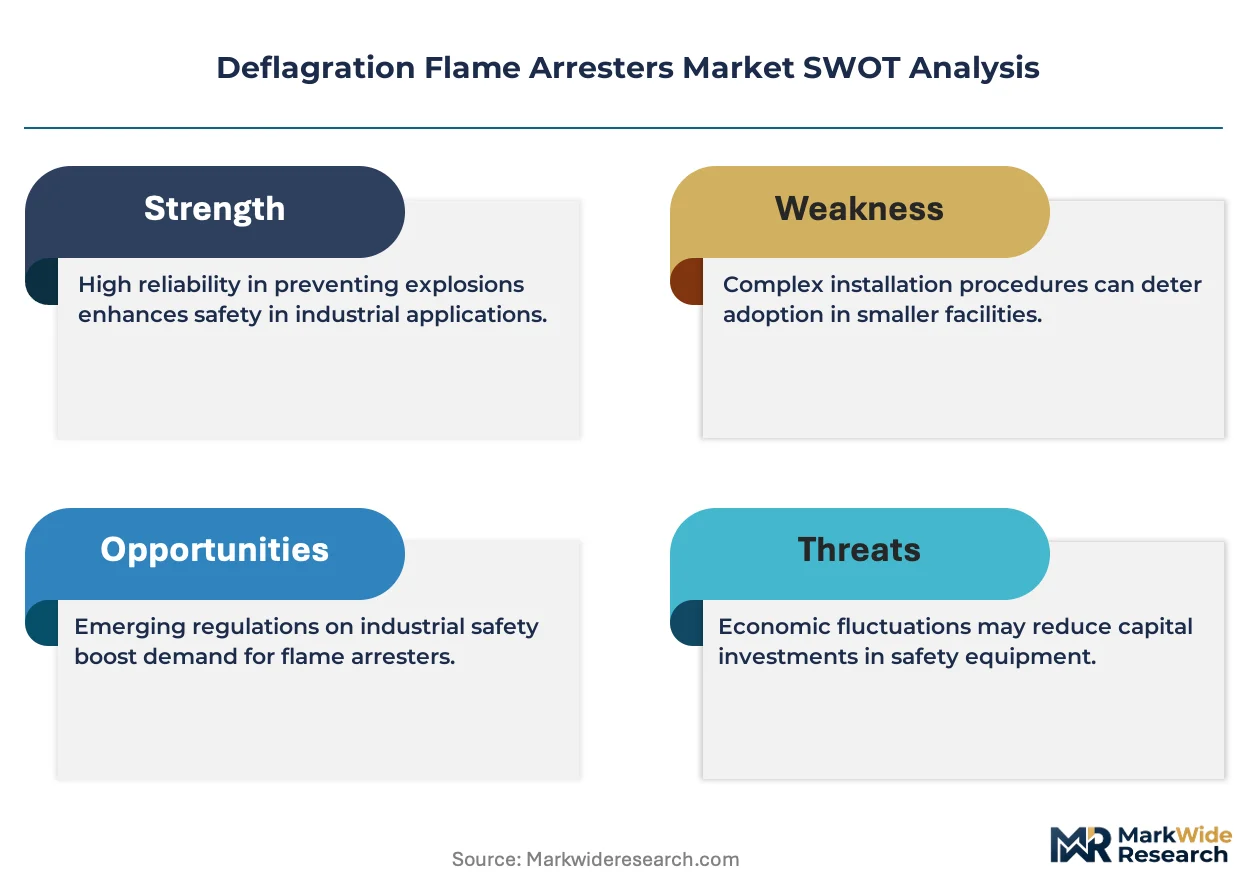
The deflagration flame arrester market is being fundamentally restructured by tightening regulatory mandates on vapor recovery systems, which now require certified equipment across petrochemical, refining, and emerging hydrogen infrastructure applications.
Growth Catalysts
- EPA National Emission Standards:Mandates for hazardous air pollutant control in US oil refineries drive procurement of certified inline arresters for vapor recovery units and storage tank venting systems.
- Hydrogen economy infrastructure:Electrolysis facilities and ammonia cracking plants in Germany and the Netherlands introduce new deflagration risk profiles requiring adapted arrester specifications for high-purity gas streams.
- Offshore platform expansion:Marine and subsea processing installations across the UK North Sea and Norwegian continental shelf demand corrosion-resistant arresters with ATEX Zone 1 certification.
Market Restraints
- Specialized alloy supply concentration:Nickel-based wound ribbon matrices and sintered stainless steel substrates face sourcing constraints from concentrated European and Japanese metallurgical suppliers.
- Extended ISO 16852 certification timelines:Third-party testing protocols for flame quenching performance and endurance burning create 12-18 month product approval cycles that delay market entry.
- Computational fluid dynamics simulation:Advanced modeling software for flame propagation analysis reduces physical testing requirements for some applications, threatening traditional arrester specification methods.
Strategic Opportunities
- India's petrochemical corridor:Reliance Industries' Jamnagar complex and proposed refineries in Andhra Pradesh lack mature flame safety infrastructure, creating first-mover positioning for certified equipment suppliers.
- Modular skid-mounted systems:Pre-assembled vapor recovery units with integrated arresters reduce field installation labor and accelerate commissioning timelines for US Gulf Coast brownfield projects.
- EU Green Deal hydrogen backbone:The European Hydrogen Backbone initiative mandates flame arresting equipment at compression stations and storage caverns across the proposed 28,000 km pipeline network.
Industry Challenges
- Computational thermal engineering expertise:Finite element analysis capabilities for optimizing channel gap geometry and heat sink design remain scarce among mid-tier manufacturers.
- Legacy piping integration:Retrofitting horizontal arresters into existing vessel vent lines requires custom flange adaptations and pressure drop recalculation that extends project timelines.
- ATEX-IECEX dual certification:Maintaining parallel compliance with European and international explosion protection standards fragments quality management systems and audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deflagration Flame Arresters Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Inline, Tank Technology: Mechanical, Thermal, Electrical, Hybrid End User: Chemical Plants, Oil Refineries, Pharmaceuticals, Waste Management Installation Type: Piped, Portable, Stationary, Mobile |
| Companies Covered | Emerson Electric Co., PROTEGO Braunschweiger Flammenfilter GmbH, Groth Corporation, Elmac Technologies, Protectoseal, Ergil, ACME Valves Industries, Pentair Safety Systems, Bs&B Safety Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deflagration Flame Arresters Market Evolving Landscape
Material science advances and digital specification tools are compressing product development cycles while regulatory harmonization efforts are reshaping certification requirements across major chemical processing regions.
Hybrid arresters combining wound metal ribbon thermal elements with mechanical flame front detection are overtaking conventional passive designs in high-cycle chemical processing environments. BASF's Ludwigshafen complex and Dow's Texas Operations have specified these units for ethylene oxide and propylene oxide handling systems. The technology is overtaking standard configurations by enabling real-time status monitoring and predictive maintenance scheduling that reduces unplanned shutdowns.
REACH restrictions on chromium VI compounds in surface treatments are forcing manufacturers to substitute trivalent chromium passivation or ceramic coatings on sintered metal matrices. The EU's Chemicals Strategy for Sustainability accelerates this transition, with German arresters suppliers reporting qualification delays for alternative corrosion protection. Marine and offshore applications in the North Sea and Baltic regions face the steepest reformulation timelines due to salt spray exposure requirements.
Engineering-procurement-construction firms are consolidating flame safety component sourcing through integrated automation platform vendors rather than standalone mechanical suppliers. This pattern concentrates specification authority with process control system integrators and compresses margins for pure-play arrester manufacturers. The shift is most pronounced in US Gulf Coast greenfield petrochemical investments, where lump-sum turnkey contracts bundle safety equipment into larger automation packages.
Deflagration Flame Arresters Market Segmentation
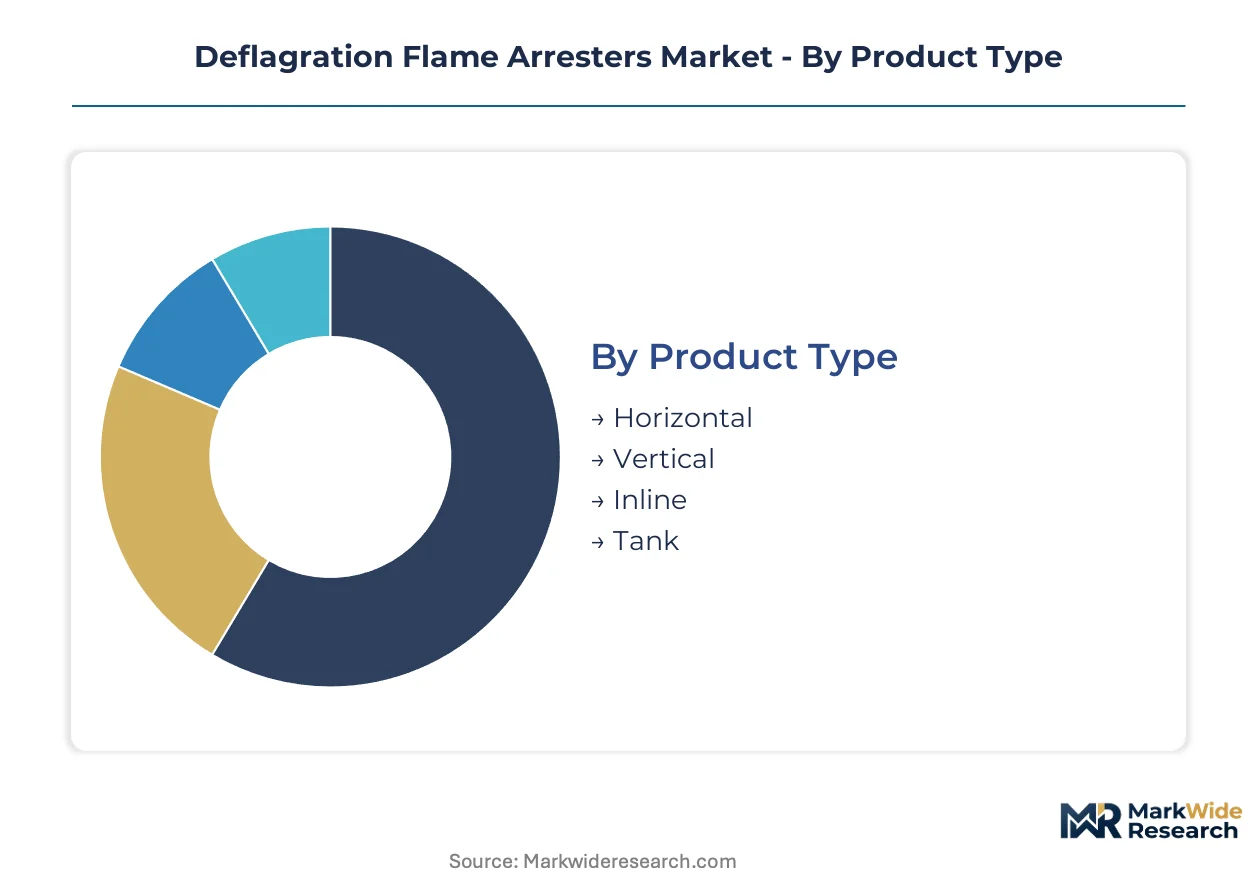
Deflagration flame arresters serve divergent integration requirements across process infrastructure. Product architecture and mounting configuration determine whether arresters operate as standalone safety layers or embed within broader vapor recovery and process control systems.
Product Type:
Horizontal and inline configurations dominate retrofit installations where piping geometry constrains placement, while vertical and tank-mounted units anchor new vessel construction.
- Horizontal:Wound metal ribbon matrices mounted perpendicular to gas flow extract flame heat through extended surface contact. US Gulf Coast refineries specify these for crude tank vent lines where pressure drop minimization overrides space constraints.
- Inline:Cylindrical housings insert directly into existing piping runs without vessel modifications, slashing installed cost for brownfield chemical plants. Germany's Ludwigshafen chemical cluster and eastern China's refining belt drive procurement of ISO 16852-certified inline units for vapor recovery retrofits.
- Vertical:Top-mounted configurations on storage tanks and pressure vessels suit new construction where elevation clearance permits.
- Tank:Specialized vent-mounted designs protect fixed-roof and floating-roof storage tanks in petrochemical terminals.
Horizontal arresters lead volumes today; inline configurations are gaining share fastest.
Technology:
Technology selection tracks hazard severity and duty cycle, with passive thermal designs yielding to active hybrid systems in high-frequency processing environments.
- Mechanical:Static flame front arresting through narrow channel gaps formed by wound ribbons or sintered matrices. These units anchor low-cycle applications in bulk liquid storage where simplicity trumps monitoring capability.
- Hybrid:Combines thermal quenching elements with flame detection sensors and status signaling. BASF's Ludwigshafen complex and Dow's Texas Operations have specified hybrid arresters for ethylene oxide handling systems where real-time monitoring enables predictive maintenance.
- Thermal:Pure passive designs relying solely on heat extraction through metal mass remain prevalent in cost-sensitive installations.
- Electrical:Spark-extinguishing systems for specialized applications where conventional thermal arresting proves insufficient.
Thermal technology leads volumes today; hybrid systems are expanding most quickly.
End User:
End-use concentration mirrors hazardous material throughput intensity, with continuous processing operations commanding premium-certified equipment.
- Oil Refineries:Atmospheric and vacuum distillation units, fluid catalytic crackers, and coking operations require arresters on vent headers and vapor recovery trains. EPA National Emission Standards for Hazardous Air Pollutants mandate certified equipment across US refining capacity.
- Chemical Plants:Ethylene, propylene, and methanol handling systems in petrochemical complexes demand ATEX-certified arresters for Zone 0 and Zone 1 hazardous areas. The EU's chemical manufacturing corridor around Antwerp, Rotterdam, and Ludwigshafen concentrates specification authority.
- Pharmaceuticals:Solvent recovery operations and API manufacturing vent systems require corrosion-resistant matrices for aggressive vapor streams.
- Waste Management:Landfill gas collection and biogas upgrading facilities deploy arresters on compressor suction lines and storage vessel vents.
Oil refineries lead volumes today; chemical plants are climbing the fastest.
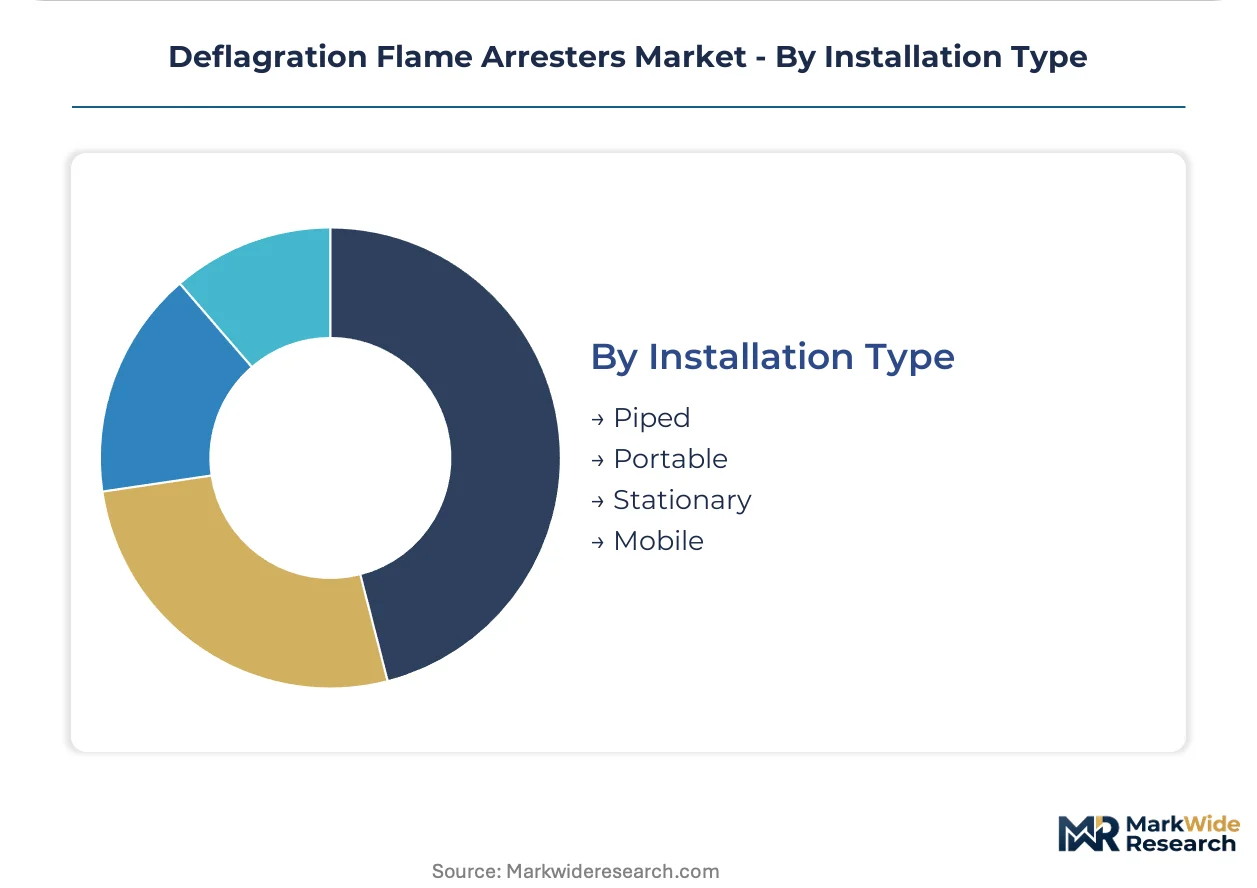
Installation Type:
Mounting flexibility determines deployment speed and capital efficiency, with permanent piped installations dominating base-load infrastructure.
- Piped:Hard-plumbed integration into fixed process piping provides maximum reliability for continuous-duty applications. Offshore platforms across the UK North Sea and Norwegian continental shelf specify piped ATEX Zone 1 arresters for permanent process trains.
- Stationary:Skid-mounted vapor recovery units with pre-integrated arresters accelerate commissioning for US Gulf Coast brownfield expansions.
- Portable:Temporary deployment for maintenance turnarounds and emergency response in tank farms and terminal operations.
- Mobile:Trailer-mounted systems for drilling rig support and pipeline construction phases.
Piped installations lead volumes today; stationary skid-mounted systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as producers migrate toward jurisdictions with streamlined ATEX and ISO 16852 certification pathways. Cost-of-compliance gaps between mature European frameworks and emerging Asian accreditation systems are redirecting investment toward Southeast Asian fabrication hubs while preserving specification authority in German and US engineering centers.
United States
EPA National Emission Standards for Hazardous Air Pollutants mandate certified arresters across Gulf Coast refining capacity. OSHA Process Safety Management enforcement intensified following 2023 petrochemical incidents. The Texas-Louisiana chemical corridor dominates procurement, with ExxonMobil's Baytown complex and Dow's Texas Operations specifying hybrid arresters for ethylene handling systems.
Germany
ATEX Directive 2014/34/EU and REACH restrictions on chromium VI surface treatments drive qualification timelines for alternative corrosion protection. The EU Green Deal hydrogen backbone initiative mandates flame arresting equipment at compression stations. BASF's Ludwigshafen complex anchors demand, specifying hybrid systems for ethylene oxide processing with real-time monitoring capabilities.
China
Eastern China's refining belt around Shanghai and Ningbo expands procurement of ISO 16852-certified inline units for vapor recovery retrofits. GB standards for hazardous area equipment are converging toward ATEX equivalence. Sinopec's Zhenhai complex and private refineries in Shandong Province drive specification volumes for horizontal arresters on crude tank vent lines.
India
Reliance Industries' Jamnagar complex and proposed Andhra Pradesh refineries lack mature flame safety infrastructure, creating first-mover positioning for certified suppliers. Petroleum and Natural Gas Regulatory Board guidelines are tightening on vapor recovery system mandates. The Gujarat petrochemical corridor concentrates procurement authority for brownfield automation upgrades.
Netherlands
Electrolysis facilities and ammonia cracking plants in Rotterdam and Eemshaven introduce new deflagration risk profiles for high-purity hydrogen streams. The European Hydrogen Backbone initiative designates Dutch territory for 1,200 km of pipeline infrastructure. Shell's Pernis refinery and Air Products' Rotterdam hydrogen import terminal anchor equipment specification.
Deflagration Flame Arresters Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular skid integration and hydrogen-specific certifications. The vendor base concentrates around German-engineered mechanical specialists, US automation-integrated platforms, and UK marine application experts. Three archetypes dominate: integrated automation bundlers, ATEX-certified mechanical specialists, and offshore corrosion-resistant fabricators. Competitive moves center on strategic partnerships with engineering-procurement-construction firms and geographic expansion into India's petrochemical corridor.
Among Germany-based specialists, PROTEGO Braunschweiger Flammenfilter GmbH exemplifies the ATEX-certified mechanical archetype through deep specialization in flame filter engineering. Emerson Electric Co. represents the integrated automation platform approach, bundling flame safety with process control systems. Elmac Technologies occupies a position among UK-based fabricators focused on marine and offshore applications. These three anchors illustrate how competitive positioning fragments across certification authority, automation integration, and application-specific corrosion resistance rather than concentrating around scale or price.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| PROTEGO Braunschweiger Flammenfilter GmbH |
| Groth Corporation |
| Elmac Technologies |
| Protectoseal |
| Ergil |
| ACME Valves Industries |
| Pentair Safety Systems |
| Bs&B Safety Systems |
| Others |
Value Network & Pricing Analysis
Nickel-based wound ribbon matrices and sintered stainless steel substrates flow from concentrated European and Japanese metallurgical suppliers through three pricing tiers before reaching end-users. Specialty alloy costs cascade through ATEX-certified premium designs, ISO-standard mid-tier units, and economy-grade thermal arresters, with certification grade and volume scale separating price bands.
Pricing Analysis
Input-cost pass-through from nickel alloy spot markets intensifies pricing pressure across mid-tier manufacturers lacking long-term supply contracts. Three-tier pricing structure across premium, standard, and economy levels reflects ATEX Zone 0 certification, ISO 16852 endurance testing, and aftermarket service bundling. Cost compression in standard-grade inline units is intensifying because engineering-procurement-construction firms consolidate procurement through automation platform vendors. Brownfield retrofit buyers exhibit highest price sensitivity; offshore platform operators show lowest sensitivity due to corrosion-resistance requirements.
Supply Chain Analysis
Specialty alloy supply rests on German, Japanese, and Swedish metallurgical producers controlling nickel-based wound ribbon and sintered matrix production. Critical inputs include Inconel-grade nickel alloys, 316L stainless steel substrates, and trivalent chromium passivation chemistries. Single-source vulnerability concentrates in ATEX-certified testing facilities, where 12-18 month ISO 16852 approval cycles create bottleneck risk. Distribution runs through engineering-procurement-construction firms and integrated automation platform vendors rather than direct mechanical supplier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as hydrogen economy infrastructure codes shift procurement toward hybrid arresters with real-time monitoring capabilities. Specification authority is migrating from standalone mechanical suppliers to process control integrators demanding certified, traceable safety layers.
For Market Incumbents: Extend certification coverage into hydrogen-specific applications before electrolysis facility codes harden, and anchor plant engineering relationships through pre-integrated skid-mounted vapor recovery systems. Computational fluid dynamics simulation tools threaten traditional specification methods; counter by embedding predictive maintenance software into hybrid arrester designs. Backward integration into specialty alloy sourcing reduces exposure to Japanese and Swedish supplier concentration. For New Entrants and Emerging Players: Launch via modular skid-mounted systems targeting India's Gujarat petrochemical corridor, where Reliance Industries' Jamnagar complex and proposed Andhra Pradesh refineries lack mature flame safety infrastructure. White-space concentration sits in hydrogen backbone compression stations across the Netherlands and Germany, where EU Green Deal mandates create first-mover certification windows. Partner with regional EPC firms to bypass entrenched automation platform bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack finite element analysis capabilities for optimizing channel gap geometry. Long-term viability favors ATEX-certified specialists with in-house thermal engineering expertise and established hydrogen qualification pathways. Acquisition target archetype: German-engineered mechanical specialists with ISO 16852 testing infrastructure and Ludwigshafen-area customer concentration. Watch for EPA enforcement intensity around OSHA Process Safety Management violations as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ATEX-Hydrogen Dual Certification Investment | Positions suppliers for EU Green Deal hydrogen backbone equipment mandates across Dutch and German compression stations. |
| Backward Integration into Specialty Alloys | Reduces exposure to concentrated Japanese and Swedish nickel-based matrix suppliers amid sourcing constraints. |
| Skid-Mounted Vapor Recovery System Partnerships | Accelerates commissioning timelines for US Gulf Coast brownfield projects through pre-integrated arrester designs. |
| Predictive Maintenance Software Embedding | Enables real-time status monitoring that BASF's Ludwigshafen complex and Dow's Texas Operations now specify. |
| India Petrochemical Corridor Market Entry | Captures first-mover positioning where Petroleum and Natural Gas Regulatory Board guidelines tighten vapor recovery mandates. |
Research Methodology
Multiple input streams — primary interviews with plant safety engineers, EPC procurement leads, and ATEX certification specialists; secondary validation through EPA enforcement databases, EU ATEX notified body registries, and SEC filings from integrated automation vendors; customs and trade flow data — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned maintenance directors at US Gulf Coast refineries, technical R&D directors at German arrester specialists, and hydrogen project developers in Rotterdam and Eemshaven.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include mounting configuration, technology type, end-use industry, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and replacement cycle analysis. Industry-specific forecast inputs incorporated hydrogen infrastructure buildout timelines and REACH restriction implementation schedules for chromium VI surface treatments.
Several conditions sit outside the modeled scope, including unannounced regulatory harmonization between ATEX and IECEx frameworks, breakthrough flame suppression technologies displacing passive thermal designs, and geopolitical disruption of nickel alloy supply corridors. Forecasts reflect documented assumptions about certification timeline stability and EPC firm procurement consolidation trajectories. Material deviation in EPA enforcement intensity or EU hydrogen backbone funding allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Heptafluoropropane Fire Suppression System Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Passive Fire Proofing System Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Cellulosic Fire Protection Market