
 Fire Suppression Equipment Market | 2026-2036
Fire Suppression Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Suppression Equipment Market Analysis
NFPA 2001-compliant clean agent specifications are rotating toward the center of procurement decisions in high-value facilities. Johnson Controls leverages its building systems integration to bundle suppression with HVAC and access control. Honeywell International anchors its position through in-house production of detection electronics and agent storage vessels. Siemens AG competes on protocol interoperability, embedding suppression controllers within its Desigo building automation architecture.
Fire suppression equipment encompasses active fire protection systems designed to detect, control, or extinguish combustion through manual or automatic discharge of extinguishing media, with operating pressures for gas-based systems typically ranging from 2,070 to 4,150 kPa at 21 degrees Celsius. These systems serve to limit property damage, protect occupant egress paths, and maintain operational continuity in facilities where fire-induced downtime carries severe economic consequences. Sprinkler systems occupy the largest installed base across commercial buildings, though gas suppression commands premium pricing in data center and museum applications where water damage poses equivalent risk to flame. Chemical agent technology is gaining share as facilities phase out halocarbon agents under environmental regulations, while foam systems dominate hydrocarbon processing and aviation fuel storage.
The National Fire Protection Association sets installation and maintenance standards that govern product eligibility across North American projects, while the EU F-Gas Regulation restricts fluorinated greenhouse gases in new suppression systems throughout member states. China's GB standards for fire protection equipment mandate domestic testing certification, creating a parallel compliance pathway for market access. Stakeholders must monitor the pace of fluorine-free agent commercialization and the alignment of regional certification regimes to avoid stranded inventory in cross-border projects.
Market Dynamics
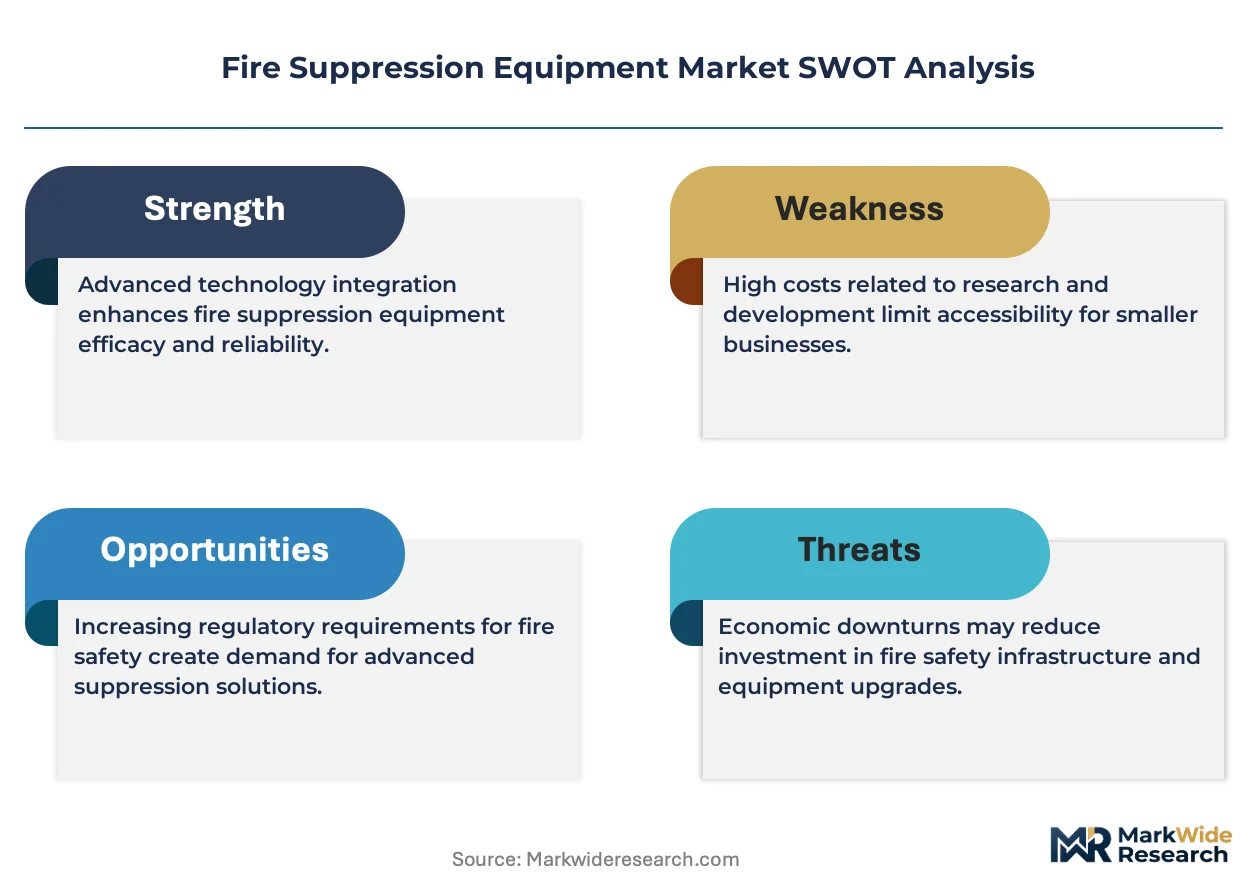
The EU F-Gas Regulation is compressing the addressable market for fluorinated clean agents while simultaneously expanding the commercial runway for fluorine-free alternatives. This regulatory pivot is redrawing competitive positioning across the suppression equipment value chain as incumbent chemistries face forced obsolescence.
Growth Catalysts
- Data center asset density:Hyperscale facilities in Northern Virginia and Frankfurt are mandating gas-based suppression for server halls where water damage exceeds flame risk. Rack power densities above 30kW per cabinet are rendering sprinkler systems economically untenable.
- F-Gas phase-down schedules:The European Union's mandated reduction in fluorinated greenhouse gas availability is accelerating specification changes in new construction tenders across member states.
- China's eastern manufacturing corridor:Industrial facility construction in Jiangsu and Zhejiang provinces is concentrating demand for foam suppression systems in petrochemical and aviation fuel storage applications.
Market Restraints
- Fluorine-free agent cost premiums:Next-generation clean agents command 40-60% price premiums over legacy halocarbon alternatives, compressing project margins for systems integrators.
- Specialized steel vessel supply:High-pressure storage cylinder production concentrates among a limited set of qualified European and East Asian metallurgical suppliers, creating input bottlenecks.
- Legacy system incompatibility:Existing halon and HFC-227ea infrastructure cannot accommodate fluorine-free agent pressure curves and discharge characteristics without complete hardware replacement.
Strategic Opportunities
- India's industrial corridor expansion:The country's PLI scheme for manufacturing is driving greenfield facility construction in Gujarat and Tamil Nadu where fire suppression specifications remain underdeveloped.
- Marine and offshore wind:Floating offshore platforms and turbine nacelles present unserved application space for compact, salt-resistant suppression systems.
- Building automation convergence:Integration of suppression controllers with HVAC and access control networks creates attach-rate expansion for systems-level vendors.
Industry Challenges
- Agent requalification timelines:UL and FM Global certification cycles for novel fluorine-free chemistries extend 18-24 months, delaying revenue recognition for formulation developers.
- Cross-border specification fragmentation:China's GB standards mandate domestic testing that does not reciprocate with NFPA or EN approvals, forcing redundant engineering for multinational projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Suppression Equipment Market |
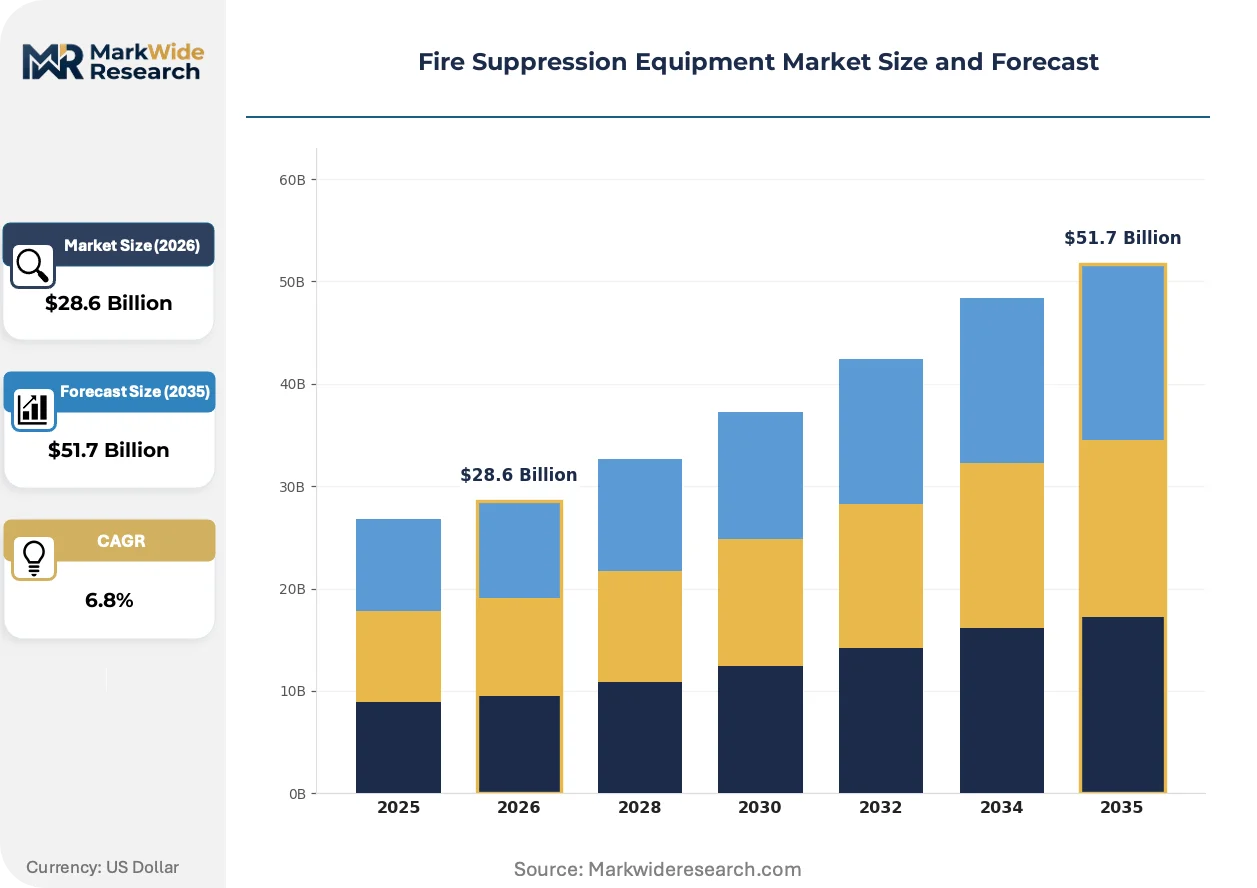
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire Extinguishers, Sprinkler Systems, Fire Hoses, Foam Systems Technology: Water-based, Chemical Agents, Foam, Gas Suppression Application: Industrial Facilities, Commercial Buildings, Residential Properties, Transportation End User: Manufacturers, Government, Fire Services, Healthcare |
| Companies Covered | Robert Bosch GmbH, Hochiki Corporation, Johnson Controls, Minimax Viking Group, Carrier Global Corporation, Honeywell International, Halma plc, Amerex Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Suppression Equipment Market Emerging Trajectories
Agent chemistry innovation is outpacing hardware evolution as the primary vector of competitive differentiation. The industry is pivoting from pressure-vessel engineering toward molecular design capabilities.
Fluorine-free clean agents derived from hydrofluoroolefin and fluoroketone chemistries are displacing legacy HFC-227ea and FK-5-1-12 specifications in European data center tenders. Colocation operators in Amsterdam and Dublin are mandating these alternatives in new-build RFPs to preempt F-Gas quota restrictions. The transition is compressing margins for incumbent agent suppliers while opening formulation partnerships between equipment OEMs and specialty chemical producers.
The EU F-Gas Regulation's quota allocation mechanism is tightening fluorinated gas availability for suppression applications. This policy constraint is forcing specification changes in fire safety tenders across Germany, France, and the Netherlands. Systems integrators are responding by building inventory buffers and accelerating supplier qualification for fluorine-free alternatives ahead of 2027 phase-down milestones.
Specification authority is migrating from facility managers to sustainability officers and ESG compliance teams. This shift is elevating whole-life carbon footprint and ozone depletion potential metrics alongside traditional performance criteria in procurement evaluations. The phenomenon is most pronounced in Nordic markets and among multinational corporations with Science Based Targets initiative commitments.
Fire Suppression Equipment Market Segmentation
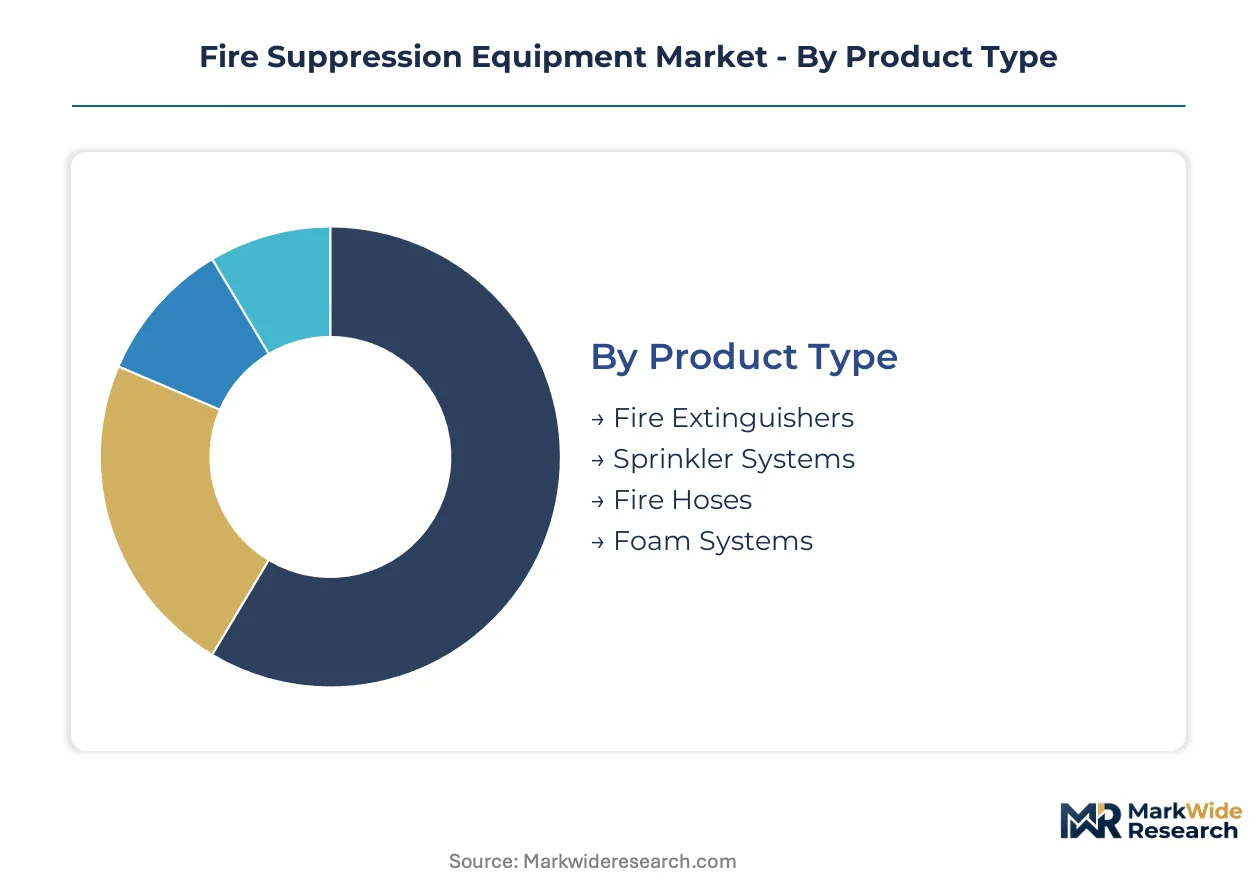
Fire suppression equipment segmentation reveals distinct compliance pathways and specification hierarchies that determine procurement authority and margin structure across facility types. Regulatory fragmentation between NFPA, EN, and GB standards forces parallel product development tracks that reshape competitive positioning within each category.
Product Type:
Regulatory differentiation separates portable equipment governed by mobile pressure vessel codes from fixed installations subject to building system integration mandates.
- Sprinkler Systems:Wet-pipe, dry-pipe, and pre-action configurations dominate commercial building codes with mandated coverage densities. Demand concentrates in US multi-story construction where NFPA 13 compliance drives specification, though European tenders increasingly require water-mist variants for heritage structures.
- Fire Extinguishers:Portable units span ABC dry chemical, CO2, and clean agent chemistries with pressure ratings from 1,034 to 2,760 kPa. Adoption is climbing fastest in India's manufacturing corridors where BIS certification requirements are tightening enforcement.
- Fire Hoses:Rubber-lined and thermoplastic constructions serve municipal fire services with burst pressures exceeding 2,070 kPa.
- Foam Systems:AFFF and fluorine-free protein concentrates protect aviation fuel storage and petrochemical processing with expansion ratios from 3:1 to 12:1.
Established volume favors sprinkler systems; emerging adoption favors foam systems.
Technology:
Cost tier separation distinguishes commodity water infrastructure from premium gas suppression requiring specialized metallurgy and agent chemistry.
- Gas Suppression:Inert gas blends and halocarbon alternatives discharge at 2,070-4,150 kPa with hold times exceeding 600 seconds for Class A and B hazards. Demand concentrates in Frankfurt and Northern Virginia data centers where rack densities above 30kW preclude water-based protection.
- Chemical Agents:Dry chemical powders and wet chemical formulations address kitchen suppression and industrial metal fires with specific application densities per square meter.
- Water-based:Sprinkler and water-mist systems occupy the lowest cost tier with broad code acceptance.
- Foam:Low-, medium-, and high-expansion concentrates serve hydrocarbon processing with fluorine-free formulations gaining share under EU F-Gas Regulation phase-down schedules.
Gas suppression commands premium pricing; water-based technology maintains volume dominance.
Application:
Customer type fragmentation splits procurement between owner-operated facilities and third-party managed properties with divergent specification authority.
- Industrial Facilities:Petrochemical, semiconductor, and battery manufacturing plants require integrated detection and suppression with SIL-rated control loops. Demand is expanding most quickly in China's Jiangsu and Zhejiang provinces where greenfield construction is accelerating.
- Commercial Buildings:Office towers and retail complexes prioritize sprinkler coverage with gas suppression limited to electrical rooms and archives.
- Residential Properties:Single-family and multi-family dwellings operate under prescriptive code minimums with limited agent diversity.
- Transportation:Rail, maritime, and aviation applications demand compact, vibration-resistant systems with marine approvals from Lloyd's Register or DNV.
Industrial facilities drive specification innovation; commercial buildings sustain replacement demand.
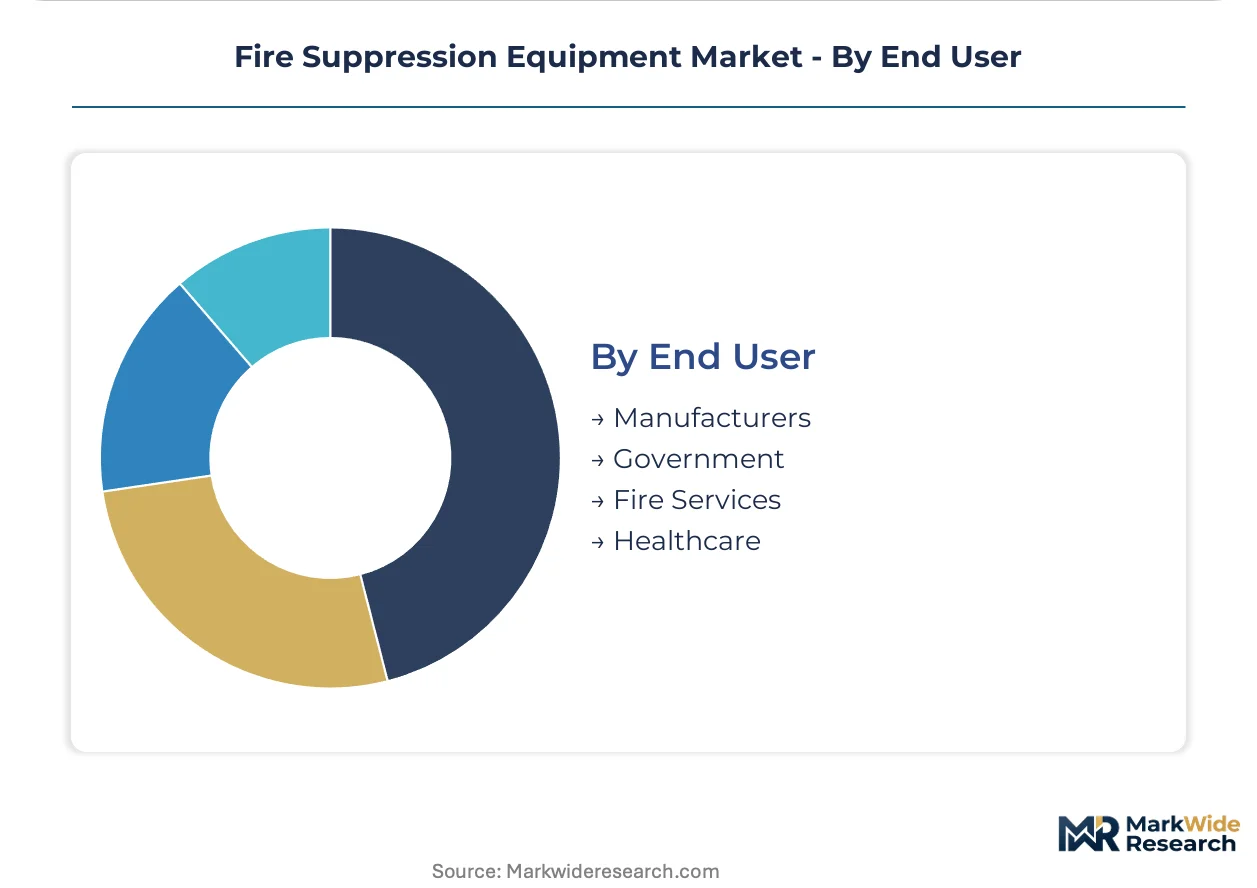
End User:
Margin structure varies sharply between price-sensitive government tenders and performance-critical private manufacturing with divergent lifecycle cost calculations.
- Manufacturers:Automotive, electronics, and pharmaceutical producers mandate system uptime guarantees with penalty clauses for fire-induced production stoppages.
- Government:Defense installations and civilian infrastructure projects operate under federal procurement rules with domestic content requirements.
- Fire Services:Municipal departments prioritize equipment interoperability and training standardization across regional fleets.
- Healthcare:Hospitals and laboratories require clean agent protection for MRI suites and pharmaceutical storage with zero-residue discharge specifications.
Healthcare and manufacturing segments sustain premium pricing; government procurement enforces cost discipline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in fire suppression equipment tilt toward import dependence in emerging manufacturing corridors while established industrial economies sustain export surpluses in specialized gas-based systems. Currency volatility and regional certification fragmentation amplify procurement complexity for multinational facility operators.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives specification of NFPA 2001-compliant clean agent systems. EPA regulations under the AIM Act phase down HFC availability, accelerating transitions to fluorine-free alternatives. Chicago and Phoenix industrial corridors concentrate demand for pre-action sprinkler systems in cold-storage logistics facilities.
Germany
Frankfurt's data center cluster mandates gas suppression for facilities exceeding 10MW capacity under stringent insurer requirements. The EU F-Gas Regulation's quota mechanism restricts fluorinated agent availability through 2030, forcing tender specification changes. Bavarian automotive manufacturing plants in Ingolstadt and Munich integrate SIL-rated suppression with production line automation.
China
Greenfield construction across Jiangsu and Zhejiang provinces concentrates demand for foam suppression in petrochemical processing. GB standards mandate domestic testing certification, creating parallel compliance pathways for multinational suppliers. Shanghai and Shenzhen data center operators are trialing fluorine-free agents ahead of anticipated national phase-down schedules.
India
The PLI scheme for manufacturing drives facility construction in Gujarat and Tamil Nadu where fire protection specifications remain underdeveloped. BIS certification requirements are tightening enforcement for imported equipment. Mumbai-Pune and Delhi-NCR industrial belts show fastest adoption of integrated detection-suppression systems in pharmaceutical manufacturing.
United Arab Emirates
Dubai and Abu Dhabi commercial tower construction sustains demand for water-mist variants in heritage-sensitive hospitality projects. UAE Fire and Life Safety Code adoption aligns with NFPA standards while permitting alternative compliance routes. Jebel Ali petrochemical zone specifications favor fluorine-free foam concentrates for aviation fuel storage.
Fire Suppression Equipment Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and regional distribution reach. The vendor base stratifies into three tiers: multinational building systems integrators with captive agent supply, standalone suppression equipment manufacturers with regional certification depth, and specialty chemical formulators supplying agent to OEMs. Dominant competitive moves include backward integration into high-pressure vessel metallurgy and strategic partnerships with data center developers for bundled mechanical-electrical packages.
Among diversified building technology conglomerates, Johnson Controls and Honeywell International exemplify the systems-integration archetype, embedding suppression controllers within broader HVAC and access control architectures. Siemens AG occupies a position emphasizing protocol interoperability across its Desigo automation platform. These three listed entities anchor the premium tier through in-house production of detection electronics and agent storage infrastructure.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Hochiki Corporation |
| Johnson Controls |
| Minimax Viking Group |
| Carrier Global Corporation |
| Honeywell International |
| Halma plc |
| Amerex Corporation |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between data center operators and fluorine-free agent suppliers lock in supply access and price visibility across the transition from legacy halocarbon chemistries. These contracts insulate buyers from F-Gas quota volatility while committing capital to metallurgical vessel procurement and certification testing.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels based on UL/FM Global certification tier and after-sales service bundling. Price differentiation separates FM Global-approved systems from economy-grade domestic certification in China's GB standards. Cost compression in standard-tier gas suppression is intensifying because fluorine-free agent production scales unevenly across European and Asian supply bases. Government procurement teams exhibit highest price sensitivity due to fixed-budget constraints, while hyperscale data center operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Strategic stockpiling of high-pressure steel cylinders dominates inventory strategy as lead times from qualified European and East Asian metallurgical suppliers extend beyond project commissioning windows. Geographic supply concentration centers on Germany, Japan, and South Korea for specialized vessel production. Raw material dependencies draw from nickel-alloy steel plate, fluoroketone precursor chemicals, and precision valve assemblies. Single-source vulnerability in cylinder forging capacity creates supply chain risk during capacity expansion cycles. Distribution runs through systems integrators with regional certification depth rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized metallurgical forging capabilities for high-pressure containment vessels represent the critical scarcity constraining expansion timelines for fluorine-free system deployment.
For Market Incumbents: Consolidate backward integration into nickel-alloy cylinder production to capture margin from metallurgical bottlenecks. Lock in exclusive offtake agreements with fluoroketone precursor suppliers before capacity constraints harden. Defensive positioning against emerging chemical formulators requires accelerating UL/FM Global certification pipelines for next-generation agent blends. For New Entrants and Emerging Players: Anchor in India's PLI-driven manufacturing corridors where fire suppression specifications remain underdeveloped and BIS certification enforcement is tightening. Target pharmaceutical manufacturing clusters in Gujarat and Tamil Nadu with integrated detection-suppression packages. Go-to-market leverage rests on bundling SIL-rated control loops with local service networks. For Investors and Strategic Acquirers: Regional specialists with GB standards certification and established relationships with China's state-owned petrochemical operators present asymmetric upside. Long-term viability hinges on positioning for fluorine-free chemistry transition rather than legacy halocarbon infrastructure. Watch F-Gas quota allocation mechanics as the inflection signal for agent chemistry substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vessel Metallurgy | Captures margin from qualified forging capacity concentrated in Germany and Japan. |
| Fluorine-Free Agent Certification Acceleration | Preempts revenue recognition delays from 18-24 month UL/FM Global approval cycles. |
| Regional Certification Depth Expansion | Unlocks access to China's GB-mandated testing pathways for multinational projects. |
| Building Automation Convergence | Expands attach rates through integration with HVAC and access control networks. |
| Marine and Offshore Wind Specialization | Addresses unserved demand from floating platforms and turbine nacelles. |
Methodological Framework
Desk research of NFPA technical standards documentation, EU F-Gas regulatory filings, and customs trade data preceded structured interviews with data center facilities managers, fire protection systems integrators, metallurgical vessel procurement leads, and specialty chemical R&D directors. Primary fieldwork combined facility site assessments in Northern Virginia and Frankfurt with validation against secondary sources including SEC 10-K disclosures from listed building technology conglomerates and BIS certification registries. Bottom-up demand modeling triangulated against top-down market sizing from equipment shipment analysis.
Variance decomposition across product type, technology tier, application vertical, and end-user segment anchored the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by fluorine-free agent substitution curves and data center construction pipelines. Industry-specific forecast inputs incorporated F-Gas quota allocation mechanics and GB standards reciprocity negotiations.
Decision-makers should treat outputs as directional under assumptions of regulatory phase-down adherence and metallurgical supply elasticity; material deviation would warrant model refresh. Revision becomes warranted when fluorine-free agent certification timelines or China's domestic content requirements cross thresholds that alter competitive access patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Global Fixed Firefighting Misting System Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
Fire Alarm and Detection System Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
Europe Fire-Resistant Glass Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Fireproof Insulation Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
GCC Firefighting Foam Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
China Thermal Protector Market