
 Flap Track Fairing Drag Reduction Upgrade Kits Market | 2026-2036
Flap Track Fairing Drag Reduction Upgrade Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Flap Track Fairing Drag Reduction Upgrade Kits Market Insights
Modular kit bundling is hardening as the dominant procurement pattern, with buyers preferring integrated packages that combine fairing shells, mounting hardware, and aerodynamic coatings over discrete component sourcing. Aviation Partners Boeing leverages its structural design heritage to anchor positions on Boeing platform retrofits. FACC AG specializes in composite manufacturing scale, sustaining European aftermarket channels through MRO partnerships. Spirit AeroSystems controls OEM-grade production lines, extending its influence into retrofit supply through certified kit variants.
Flap track fairing drag reduction upgrade kits are aerodynamic modification assemblies installed on existing wing structures to reduce form drag and interference drag at flap mechanism interfaces, typically incorporating carbon fiber reinforced polymer shells with specialized edge sealing to maintain laminar flow profiles. Their primary purpose is to deliver measurable fuel burn reduction on in-service aircraft without requiring complete wing redesign. Lightweight kits lead the product type landscape due to operator emphasis on minimal weight penalty against fuel savings, while advanced kits integrating aerodynamic coatings represent the fastest-growing category as airlines seek compound efficiency gains. Composite materials dominate the technology dimension, though modular design approaches are gaining traction by reducing installation downtime and expanding MRO eligibility.
FAA airworthiness certification standards and EASA CS-25 structural modification requirements govern kit approval pathways, with both agencies intensifying scrutiny of fatigue life impact from fairing geometry changes. The EU Green Deal emissions benchmarks are indirectly shaping demand by pressuring operators toward proven retrofit solutions that deliver immediate CO2 reduction without fleet replacement. Stakeholders must monitor evolving certification reciprocity between FAA and EASA as divergence in approval timelines could fragment retrofit scheduling and inventory deployment across operator networks.
Market Dynamics
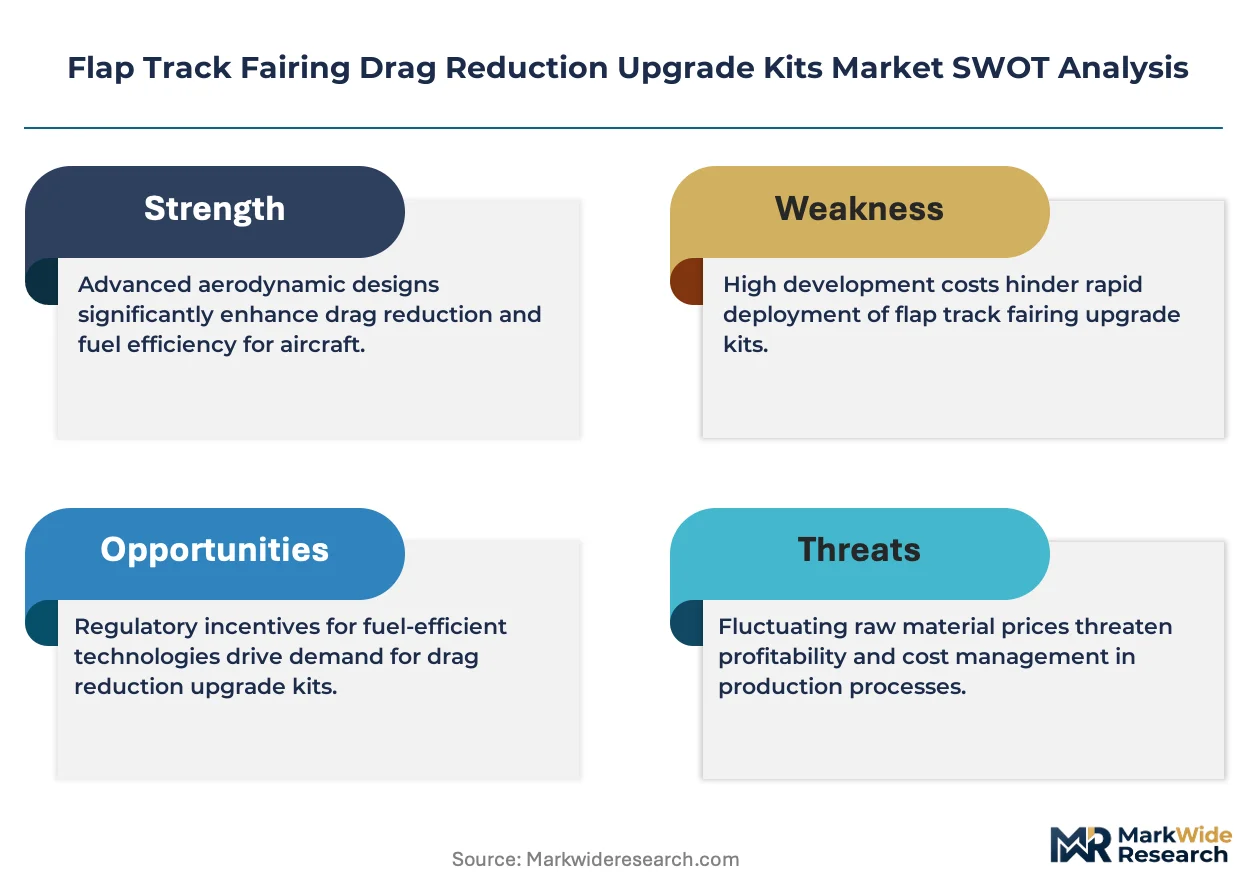
Commercial airline fleet retrofit economics are compressing decision cycles for flap track fairing upgrades, as carriers prioritize fuel burn reduction over new aircraft acquisition amid sustained jet fuel price volatility.
Growth Catalysts
- EU Green Deal emissions benchmarks:Pressure on operators to demonstrate immediate CO2 reduction without fleet replacement is accelerating retrofit program approvals across European narrow-body operators.
- Carbon fiber reinforced polymer manufacturing scale:Expanded composite production capacity is reducing kit lead times and enabling faster MRO turnaround scheduling for aging Boeing 737NG and A320ceo fleets.
- FAA-EASA certification reciprocity improvements:Streamlined dual-approval pathways are reducing time-to-installation for multinational carrier fleets operating under split regulatory jurisdictions.
Market Restraints
- Prepreg carbon fiber supply concentration:Japanese and US-based raw material suppliers control critical aerospace-grade fiber feedstocks, exposing kit manufacturers to input cost volatility and allocation constraints.
- Fatigue life certification complexity:FAA airworthiness directives require extensive structural modification validation, extending approval timelines and freezing inventory deployment until full compliance documentation is submitted.
- Next-generation aircraft substitution threat:Boeing 737 MAX and Airbus A320neo deliveries with factory-optimized aerodynamics reduce the retrofit addressable market for drag reduction kits on new fleet additions.
Strategic Opportunities
- Indian subcontinent MRO expansion:Emerging third-party maintenance hubs in Hyderabad and Bengaluru lack certified flap track fairing installation capabilities, creating first-mover advantage for kit providers establishing local technical partnerships.
- Aerodynamic coating convergence with base fairing kits:Integration of specialized laminar flow surface treatments with structural shells is unifying previously separate upgrade decisions into single procurement events.
- EASA CS-25 structural modification pathway harmonization:Proposed regulatory alignment with FAA damage tolerance standards would compress dual-certification costs and accelerate pan-European fleet retrofit campaigns.
Industry Challenges
- Composite repair technician scarcity:MRO facilities face certified technician shortages for carbon fiber shell installation and edge sealing, constraining fleet-wide rollout velocity despite kit availability.
- Legacy aircraft documentation fragmentation:Incomplete as-built wing geometry records for pre-2010 narrow-body fleets complicate kit customization engineering and extend pre-installation survey timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flap Track Fairing Drag Reduction Upgrade Kits Market |
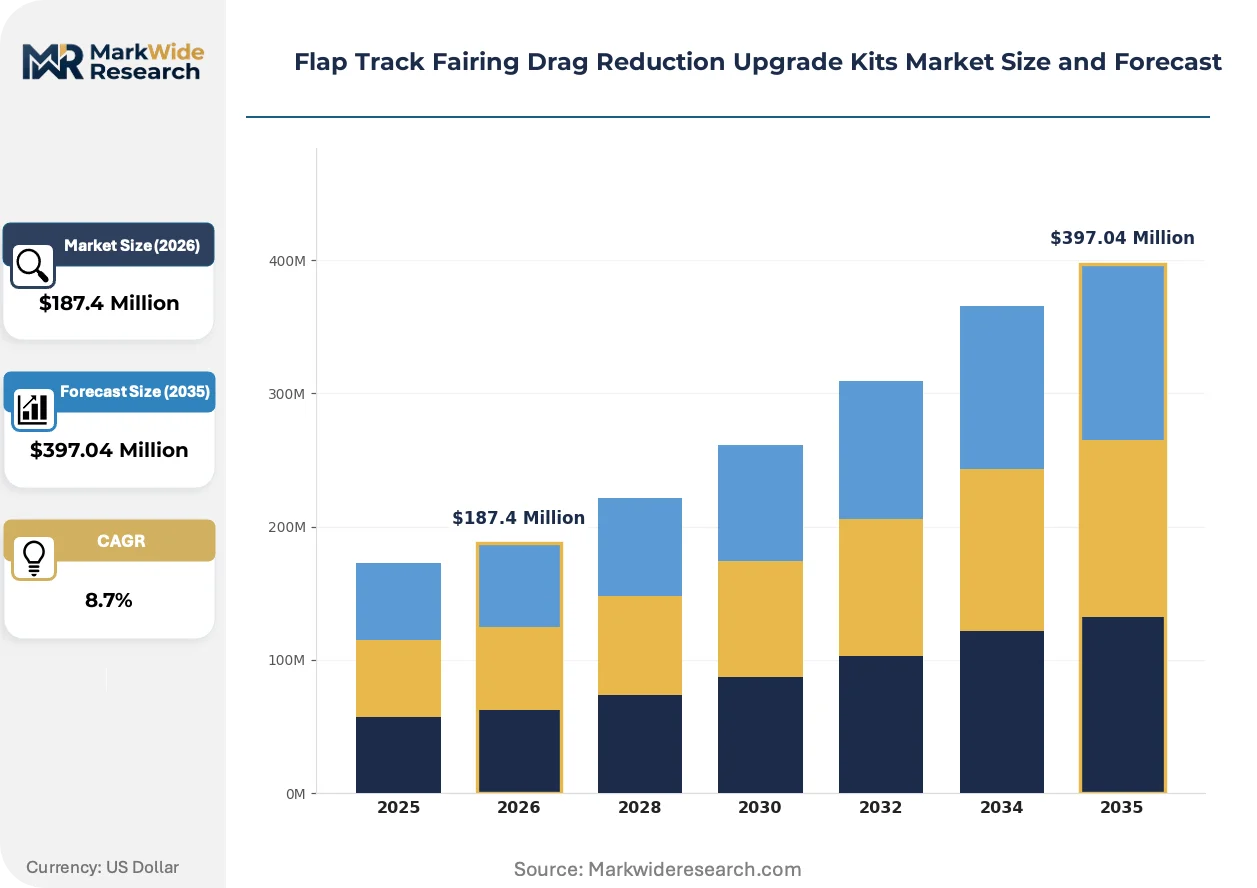
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Kits, Advanced Kits, Lightweight Kits, Custom Kits Technology: Composite Materials, Aerodynamic Coatings, Modular Design, Reinforced Polymers Application: Commercial Airliners, Business Jets, Military Aircraft, Private Helicopters End User: Aircraft Manufacturers, Maintenance Repair Organizations, Aerospace Retrofitters, Leasing Companies |
| Companies Covered | Aero Design Labs, Aviation Partners Boeing, Vortex Control Technologies, SACS Aerospace, ALOFT AeroArchitects, The NORDAM Group, Lufthansa Technik, FACC AG, Spirit AeroSystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flap Track Fairing Drag Reduction Upgrade Kits Market Trends and Innovations
Modular design architectures are displacing monolithic fairing structures across the retrofit supply base, enabling distributed manufacturing and reducing single-source dependency for complex aerodynamic assemblies.
Multi-piece fairing systems with standardized interface geometries are unifying previously bespoke installation procedures across Boeing and Airbus platform variants. Low-cost carriers in Southeast Asia and Latin America are adopting these kits most aggressively, compressing MRO downtime from weeks to days and expanding the eligible technician pool beyond OEM-certified specialists.
EASA intensified scrutiny of fatigue life impact from fairing geometry modifications under revised CS-25 Amendment 25-148 guidance. This regulatory tightening is forcing kit developers to submit expanded damage tolerance documentation, particularly for high-cycle operations on short-haul routes. European operators with dense domestic networks are experiencing the longest certification delays and are pressing suppliers for pre-validated structural analysis packages.
Carrier procurement departments are consolidating previously fragmented upgrade decisions into integrated fleet efficiency programs. Discrete component sourcing for fairing shells, mounting hardware, and surface treatments is giving way to single-vendor kit contracts with performance-guaranteed fuel burn reduction clauses. This behavioral shift is most pronounced among US legacy carriers managing mixed Boeing-Airbus fleets under unified technical operations departments.
Flap Track Fairing Drag Reduction Upgrade Kits Market Segmentation
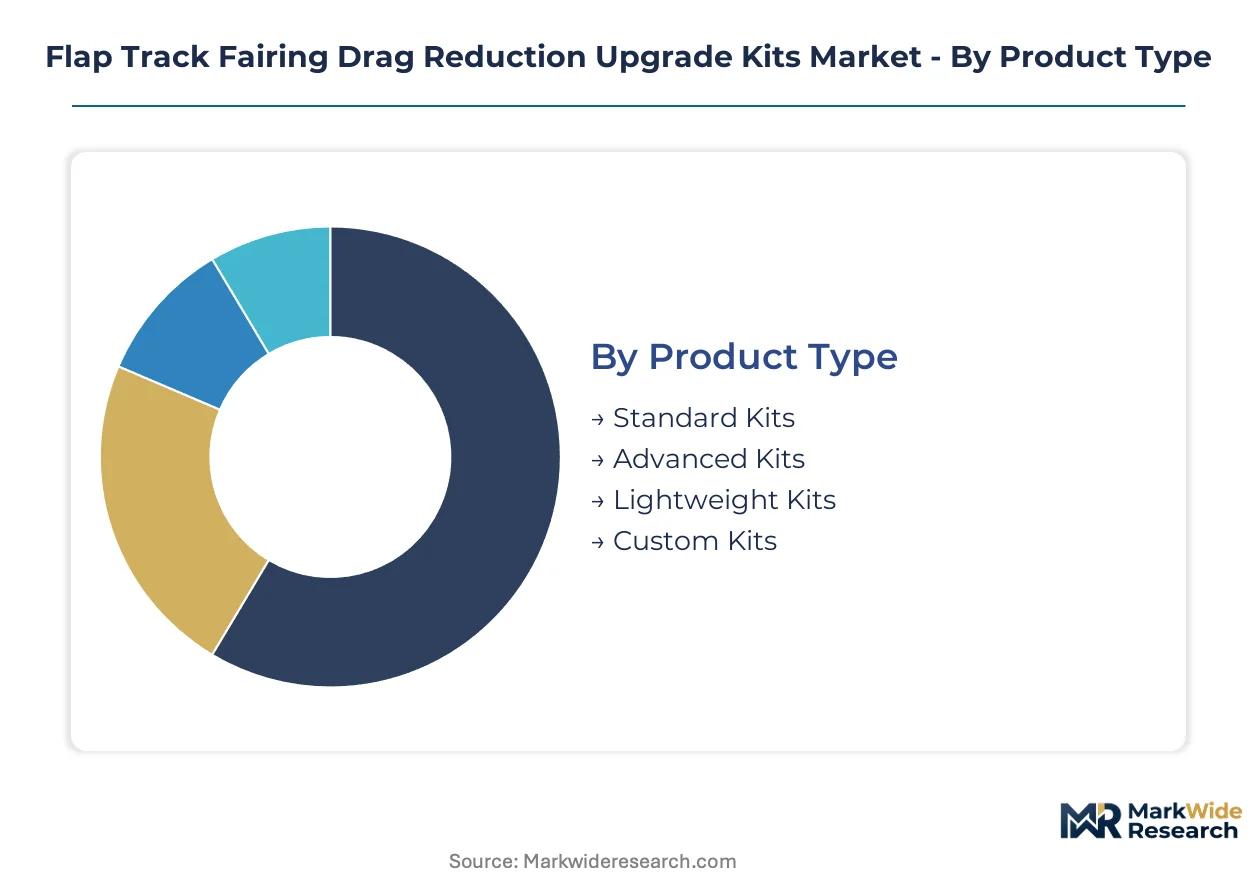
Segmentation in the flap track fairing drag reduction upgrade kits market reveals how procurement priorities diverge across operational contexts. Airlines prioritize weight-minimal solutions for fuel burn reduction, while MROs favor installation-speed technologies that compress hangar downtime. Military operators demand ruggedized specifications that diverge sharply from commercial laminar-flow optimization.
Product Type:
Technical specification tiers define the product landscape, with weight penalty tolerance and aerodynamic sophistication separating procurement decisions across operator categories.
- Lightweight Kits:Carbon fiber reinforced polymer shells minimize mass addition per unit of drag reduction achieved. Commercial airlines operating aging Boeing 737NG and Airbus A320ceo fleets in the United States concentrate procurement here, driven by FAA fuel efficiency mandates and sustained jet fuel price pressure.
- Advanced Kits:Integrated assemblies combining structural fairing shells with specialized laminar-flow surface treatments deliver compound efficiency gains. European narrow-body operators under EU Green Deal emissions benchmarks are expanding most quickly in this category, seeking immediate CO2 reduction without fleet replacement.
- Standard Kits:Baseline aerodynamic modifications using conventional composite formulations serve cost-sensitive retrofit programs.
- Custom Kits:Bespoke engineering for non-standard wing geometries or specialized mission profiles addresses documentation-fragmented legacy fleets.
Lightweight kits lead on scale; advanced kits lead on momentum.
Technology:
Material science and manufacturing methodology choices determine certification pathways, MRO eligibility, and installation throughput across regulatory jurisdictions.
- Composite Materials:Carbon fiber reinforced polymers dominate structural shell production, leveraging aerospace-grade prepreg manufacturing scale. Japanese and US-based raw material suppliers control critical fiber feedstocks, exposing kit manufacturers to input cost volatility and allocation constraints that shape procurement timing.
- Modular Design:Multi-piece fairing systems with standardized interface geometries reduce installation downtime from weeks to days. Southeast Asian low-cost carriers concentrate demand here, expanding the eligible technician pool beyond OEM-certified specialists.
- Aerodynamic Coatings:Specialized surface treatments maintaining laminar flow profiles are gaining integration with base structural kits.
- Reinforced Polymers:Alternative structural formulations serve secondary applications where carbon fiber cost or supply access limits adoption.
Composite materials anchor volume; modular design climbs the fastest.
Application:
Platform operational profiles dictate aerodynamic priority, certification stringency, and retrofit economics across aviation sectors.
- Commercial Airliners:High-cycle narrow-body operations prioritize fuel burn reduction per available seat-mile. US legacy carriers managing mixed Boeing-Airbus fleets under unified technical operations departments concentrate procurement in integrated kit contracts with performance-guaranteed clauses.
- Business Jets:Range-extension and operating cost reduction drive adoption among fleet operators seeking competitive differentiation.
- Military Aircraft:Ruggedized specifications and damage tolerance requirements diverge from commercial laminar-flow optimization priorities.
- Private Helicopters:Limited addressable market due to rotary-wing aerodynamic architecture differences from fixed-wing flap track configurations.
Commercial airliners dominate absolute volume; business jets show steepest expansion trajectory.
End User:
Procurement authority and technical capability distribution shape channel structure and vendor relationship intensity.
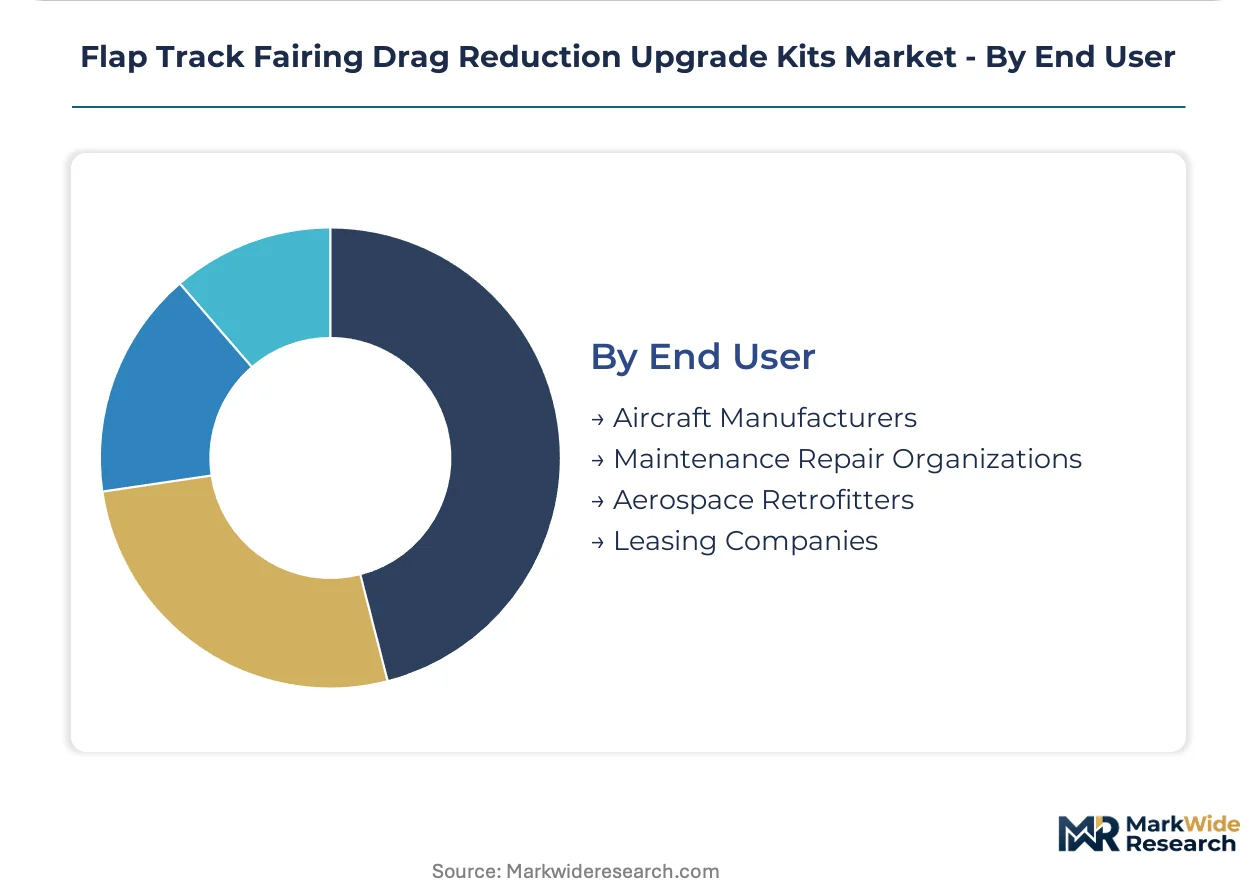
- Maintenance Repair Organizations:Third-party MROs control retrofit execution for in-service fleets, creating kit demand through direct technical specification influence. Indian subcontinent hubs in Hyderabad and Bengaluru lack certified installation capabilities, creating first-mover opportunity for providers establishing local partnerships.
- Aircraft Manufacturers:OEM production line integration and factory-new aircraft optimization limits addressable market as next-generation platforms arrive with pre-optimized aerodynamics.
- Aerospace Retrofitters:Specialized modification shops serve niche platforms and non-standard engineering requirements.
- Leasing Companies:Asset value preservation and lease-rate competitiveness drive portfolio-wide efficiency program sponsorship.
Maintenance repair organizations command channel influence; leasing companies gain procurement authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flap track fairing drag reduction upgrade kits originated in the United States aerospace manufacturing corridor, where Boeing's commercial aircraft dominance created early demand for aftermarket aerodynamic efficiency solutions. FAA certification pathways established in the 1990s provided the regulatory template now adopted across multiple jurisdictions.
United States
Major carriers including American Airlines, Delta, and United operate aging narrow-body fleets requiring immediate fuel burn reductions. FAA airworthiness directives for Boeing 737NG and MD-80 series aircraft mandate structural modification compliance timelines. Dallas-Fort Worth and Seattle-Tacoma aerospace clusters host specialized MRO facilities performing certified flap track fairing installations at scale.
Germany
Lufthansa Group's technical operations drive European retrofit program adoption across A320ceo and Boeing 737-800 fleets. EASA CS-25 Amendment 25-148 intensifies fatigue life documentation requirements for structural modifications. Hamburg's aviation manufacturing ecosystem integrates composite kit production with adjacent MRO infrastructure serving Central European operators.
United Kingdom
British Airways and easyJet prioritize fuel efficiency retrofits amid sustained jet fuel price volatility and carbon offset obligations. UK CAA alignment with EASA certification reciprocity streamlines dual-approval pathways for multinational fleet operators. London Gatwick and Manchester maintenance hubs concentrate third-party installation capacity for low-cost carrier segments.
India
IndiGo and SpiceJet expand retrofit programs on high-utilization domestic narrow-body networks facing emissions disclosure pressure. DGCA adoption of FAA-EASA harmonized standards accelerates import certification for foreign-manufactured kits. Hyderabad and Bengaluru emerging MRO clusters lack certified flap track fairing installation capabilities, creating technical partnership opportunities for established providers.
Japan
ANA and JAL retrofit decisions emphasize operational range extension on aging Boeing 767 and 737-800 fleets serving regional routes. METI carbon neutrality roadmaps for aviation indirectly support aftermarket efficiency investment through fleet modernization incentives. Nagoya aerospace manufacturing corridor supplies composite material feedstocks to regional kit assemblers serving Asia-Pacific operators.
Flap Track Fairing Drag Reduction Upgrade Kits Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and OEM relationship depth. The market structures around three participant categories: OEM-affiliated kit developers leveraging factory engineering access, independent aerodynamic specialists with proprietary design IP, and MRO-integrated providers controlling installation channel access. Consolidation pressure intensifies as airlines consolidate procurement authority under unified technical operations departments. Dominant competitive moves include strategic partnerships between kit designers and MRO networks, plus backward integration into carbon fiber composite manufacturing to secure supply chain control.
Within the OEM-affiliated tier, Aviation Partners Boeing and Spirit AeroSystems exemplify structural design heritage extending into certified retrofit variants. FACC AG occupies a position representing European composite manufacturing scale sustained through aftermarket channel partnerships. Independent specialists including Vortex Control Technologies and SACS Aerospace sit within the aerodynamic IP-focused segment, competing on installation speed and platform customization flexibility rather than production volume.
| Leading Market Players |
|---|
| Aero Design Labs |
| Aviation Partners Boeing |
| Vortex Control Technologies |
| SACS Aerospace |
| ALOFT AeroArchitects |
| The NORDAM Group |
| Lufthansa Technik |
| FACC AG |
| Spirit AeroSystems |
| Others |
Pricing and Supply Chain Analysis
Airline procurement consolidation under unified technical operations departments is forcing kit manufacturers toward bundled performance-guaranteed contracts, compressing margins on discrete component sales while rewarding suppliers with integrated design-to-installation capabilities. This demand shift elevates pricing power for vendors controlling both composite manufacturing scale and certified MRO channel access.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified advanced kits with laminar-flow coatings from baseline composite shells and unbundled hardware-only configurations. Price differentiation rests on certification tier depth and installation speed guarantees, with FAA-EASA dual-approval kits commanding substantial premiums. Pricing pressure stems from low-cost carrier procurement aggregation in Southeast Asia, where volume scale negotiations erode standard-tier margins. Leasing companies show least price sensitivity, prioritizing asset value preservation clauses over per-unit kit costs.
Supply Chain Analysis
Domestic-content mandates under India's Production Linked Incentive scheme and proposed US Buy American provisions for federal fleet contractors are reshaping sourcing decisions for kit assemblers serving government-tied operators. Manufacturing concentrates in the United States, Germany, and Japan, with carbon fiber prepreg feedstocks drawing from Japanese Toray and US Hexcel facilities. Single-source vulnerability runs through aerospace-grade resin systems, where Huntsman and Solvay control formulated product supply. Distribution runs through OEM-authorized MRO networks and independent retrofit shops, with emerging third-party hubs in India lacking certified installation capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as airline technical departments consolidate procurement authority and shift specifications toward integrated kits with guaranteed fuel burn outcomes.
For Market Incumbents: Cement composite manufacturing scale advantages through captive carbon fiber prepreg supply agreements, insulating against Japanese and US fiber supplier allocation constraints. Deepen MRO channel control via exclusive technical partnerships with Indian subcontinent emerging hubs, preempting new entrant access to high-growth retrofit demand. Prioritize EASA CS-25 Amendment 25-148 pre-validated structural analysis packages to compress certification timelines for European short-haul operators. For New Entrants and Emerging Players: Launch via modular design technology licensing to Southeast Asian low-cost carriers seeking installation-speed advantages without OEM-certified technician dependencies. Target the custom kit segment for documentation-fragmented pre-2010 narrow-body fleets, where incomplete as-built wing geometry records create engineering barriers for standardized kit providers. Establish technical training partnerships with Hyderabad and Bengaluru MRO clusters to capture first-mover advantage in uncertified installation capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with independent aerodynamic specialists holding proprietary laminar-flow surface treatment IP and platform customization flexibility. Long-term viability favors acquisition targets with backward integration into composite shell manufacturing and established dual-approval certification portfolios. Watch for EASA-FAA reciprocity divergence as the inflection signal, where approval timeline fragmentation would concentrate kit demand with providers holding parallel certification capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Prepreg | Captive supply from Toray and Hexcel fiber feedstocks insulates kit manufacturers against allocation volatility. |
| MRO Channel Partnership Expansion | Exclusive technical agreements with Indian subcontinent hubs unlock access to uncertified installation capacity. |
| Dual-Certification Pre-Validation Investment | Pre-submitted EASA CS-25 damage tolerance documentation accelerates European narrow-body retrofit approvals. |
| Aerodynamic Coating Convergence R&D | Integrated laminar-flow surface treatment development unifies previously separate upgrade procurement decisions. |
| Modular Design Platform Standardization | Multi-piece fairing systems with standardized interface geometries expand eligible technician pools beyond OEM specialists. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airline fleet planning directors, MRO facility managers, composite manufacturing procurement leads, and FAA/EASA certification engineers with secondary validation from FAA airworthiness directive filings, EASA CS-25 amendment documentation, and airline technical operations expenditure disclosures. Bottom-up kit shipment modeling and top-down fleet retrofit penetration estimates triangulated market sizing across the analysis window.
Segment-weighting approaches applied product type, technology, application, and end-user dimensions to derive volume and value outputs, with CAGRs calculated from fitted growth curves against historical installation rates and projected fleet age profiles. Industry-specific forecast inputs incorporated jet fuel price volatility scenarios and next-generation aircraft delivery schedules affecting retrofit addressable market calculations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained prepreg carbon fiber supply disruption or accelerated Boeing 737 MAX and Airbus A320neo fleet replacement. Forecasts reflect documented assumptions regarding certification reciprocity stability and MRO technician training pipeline expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
Aircraft Mounts Market
Aircraft
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market
Aircraft
Commercial Aerospace Market
Aircraft
Aircraft Jack Market
Aircraft
Latin America Commercial Aircraft Market
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
Air Starter Market
Aircraft
Middle-East and Africa Business Jet Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
America Freighter Aircraft Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Aircraft Ailerons Market
Aircraft
Aircraft Cargo Winches Market