
 Aircraft Waste Tank Market | 2026-2036
Aircraft Waste Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Waste Tank Market Analysis
North American specialty composites producers is rebalancing capacity toward aviation-grade thermoplastic resins. RTX Corporation leverages its propulsion systems integration to extend waste management subsystem offerings across regional jet platforms. Safran SA anchors European OEM supply through Diehl Stiftung & Co. KG, which sustains dual-source manufacturing in Germany and Mexico. JAMCO Corporation competes on narrow-body retrofit programs with FAA-certified vacuum waste architectures.
Aircraft waste tanks are sealed containment vessels engineered to store lavatory and galley effluent during flight, typically fabricated from glass-reinforced epoxy composites or corrosion-resistant stainless steel alloys rated for pressure differentials up to 75 psi and temperature cycles between -55°C and 70°C. These systems serve the essential commercial purpose of maintaining cabin hygiene standards while minimizing aircraft weight penalty and preventing leakage at altitude. Composite tanks now lead OEM installations for next-generation single-aisle programs, whereas stainless steel variants dominate military retrofit and aftermarket replacement where cost sensitivity and field repairability override weight savings. Fixed tanks capture the majority of installed base value, while portable configurations represent the fastest-growing niche for VIP and medevac conversions requiring rapid reconfiguration.
FAA airworthiness directives and EASA CS-25 certification requirements mandate fire-resistant materials and structural integrity testing for all cabin waste containment, effectively raising barriers for non-certified suppliers. EPA effluent handling guidelines and REACH chemical compliance in Europe further constrain material selection and end-of-life disposal pathways for composite formulations. Military procurement through NAVAIR and Defense Logistics Agency specifications adds a parallel compliance layer for defense applications. Stakeholders must monitor evolving MEE environmental standards in China and emerging SAMR import certification timelines as these jurisdictions expand indigenous narrow-body production.
Market Dynamics
Fleet modernization programs across commercial aviation are forcing a wholesale transition from stainless steel to thermoplastic composite waste containment architectures, compressing qualification timelines for incumbent suppliers while opening entry points for materials specialists.
Growth Catalysts
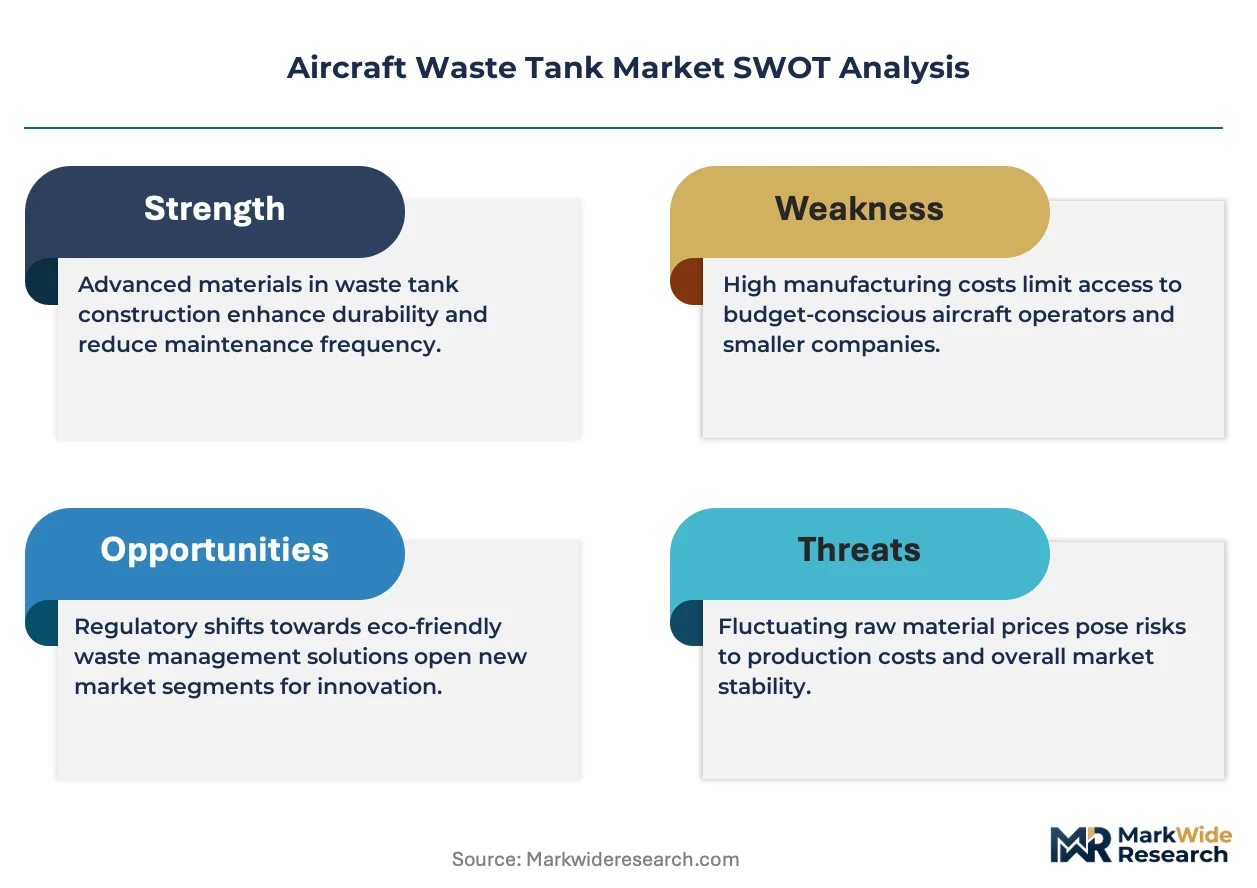
- FAA Airworthiness Directives:Mandates for fire-resistant, lightweight containment systems are accelerating OEM adoption of glass-reinforced epoxy composites in next-generation narrow-body platforms.
- Galley effluent expansion:Premium cabin configurations with enhanced food service capabilities are doubling waste generation per flight hour, expanding tank capacity requirements.
- MRO infrastructure concentration:The United States hosts the world's densest network of certified aircraft maintenance facilities, anchoring aftermarket replacement demand.
Market Restraints
- Epoxy resin price volatility:Aviation-grade thermoset feedstocks face cyclical supply constraints from petrochemical upstream, squeezing composite tank margins unpredictably.
- German-Mexico supply concentration:Dual-source manufacturing for European OEM programs creates geographic vulnerability to trade disruption or logistics bottlenecks.
- REACH chemical compliance:European end-of-life disposal restrictions on composite formulations add compliance overhead and limit material recovery options.
Strategic Opportunities
- China indigenous narrow-body production:Expanding COMAC C919 manufacturing is creating demand for SAMR-certified waste systems from qualified tier-one suppliers.
- VIP and medevac conversions:Portable tank configurations for rapid cabin reconfiguration represent an underpenetrated niche with premium pricing power.
- MEE environmental standards evolution:China's tightening effluent handling guidelines are creating first-mover advantage for compliant containment technologies.
Industry Challenges
- CS-25 certification timeline compression:EASA structural integrity testing protocols for fire-resistant materials extend product qualification cycles, delaying revenue recognition.
- Legacy platform integration friction:Retrofitting vacuum waste architectures into older narrow-body fleets requires custom mounting adaptations and plumbing reconfiguration.
- Composite repair skill scarcity:Field-level damage assessment and restoration capabilities for thermoplastic tanks lag stainless steel weld-repair familiarity among line maintenance crews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Waste Tank Market |
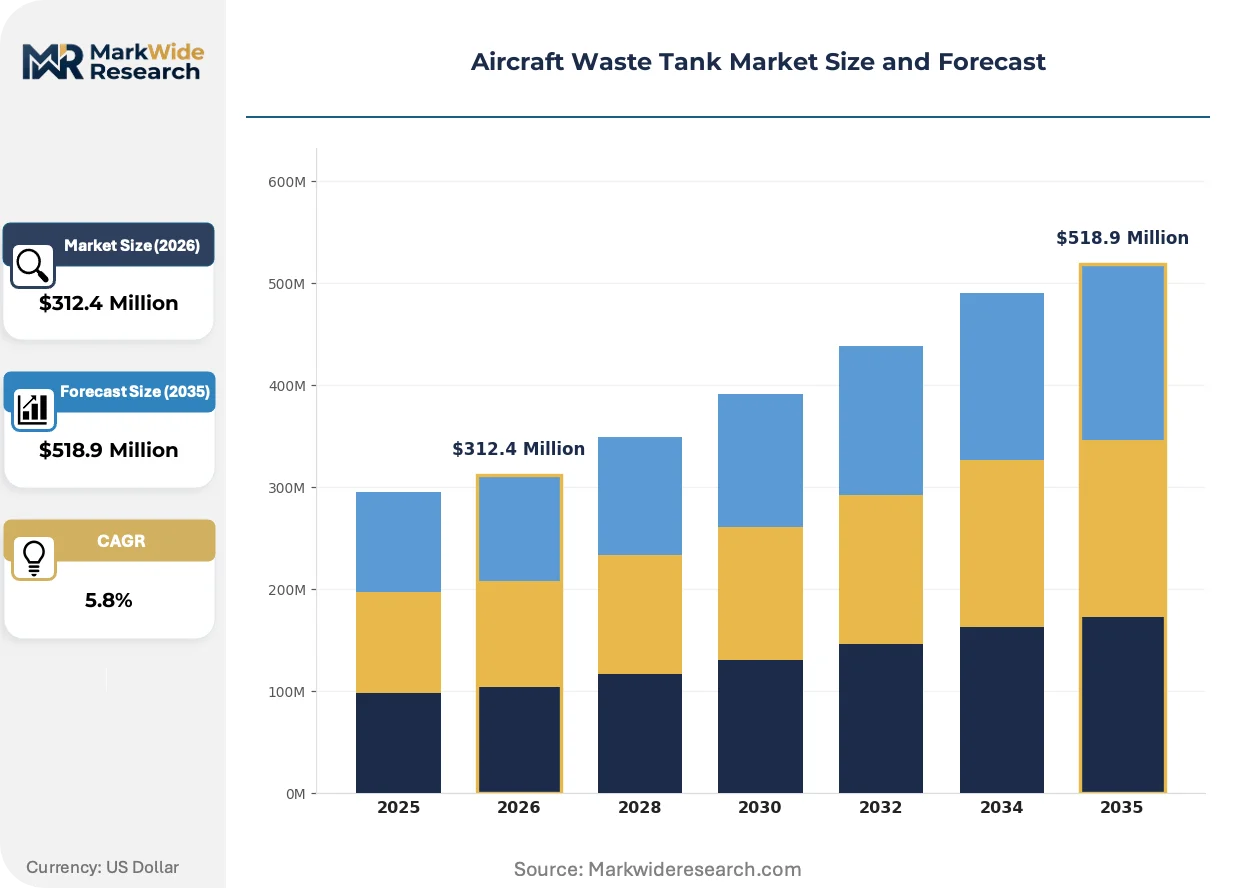
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Tanks, Fixed Tanks, Composite Tanks, Stainless Steel Tanks End User: Commercial Airlines, Military Aviation, Private Jets, Cargo Airlines Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers Installation Type: Aftermarket Installation, OEM Installation, Integrated Systems, Custom Solutions |
| Companies Covered | RTX Corporation, Safran SA, Diehl Stiftung & Co. KG, JAMCO Corporation, Collins Aerospace, AeroControlex Group Inc., Yokohama Aerospace America, Inc., CIRCOR Aerospace and Defense, Inc., The NORDAM Group LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Waste Tank Market Emerging Trajectories
Active materials science advancement is collapsing the performance gap between thermoplastic composites and legacy metal architectures while regulatory jurisdictions compete to set the dominant certification standard for next-generation containment.
Thermoplastic resin systems with integrated fire-suppression additives are converging with automated fiber placement manufacturing to produce monocoque tank structures with 15-20% weight reduction over thermoset equivalents. Narrow-body OEM programs are qualifying these architectures for 2027-2030 entry-into-service platforms. The technology is converging with predictive maintenance analytics, enabling real-time leak detection and structural health monitoring that compresses unscheduled removal rates.
REACH chemical compliance in Europe is tightening restrictions on bisphenol-based curing agents and halogenated flame retardants used in legacy composite formulations. Industrial consequence forces reformulation of resin systems toward bio-based or non-toxic alternatives, adding 18-24 months to requalification cycles. Regional jet and turboprop segments are most affected, with manufacturers accelerating testing of compliant alternatives to avoid program delays.
Airline procurement departments are consolidating vendor relationships around full-service waste management subsystem providers rather than discrete tank suppliers. This behavior disrupts traditional component-tier sourcing, replacing it with integrated lavatory module contracts that bundle tanks, sensors, and control electronics. The shift is most visible among US network carriers modernizing single-aisle fleets, where procurement teams prioritize single-source accountability for cabin system performance.
Aircraft Waste Tank Market Segmentation
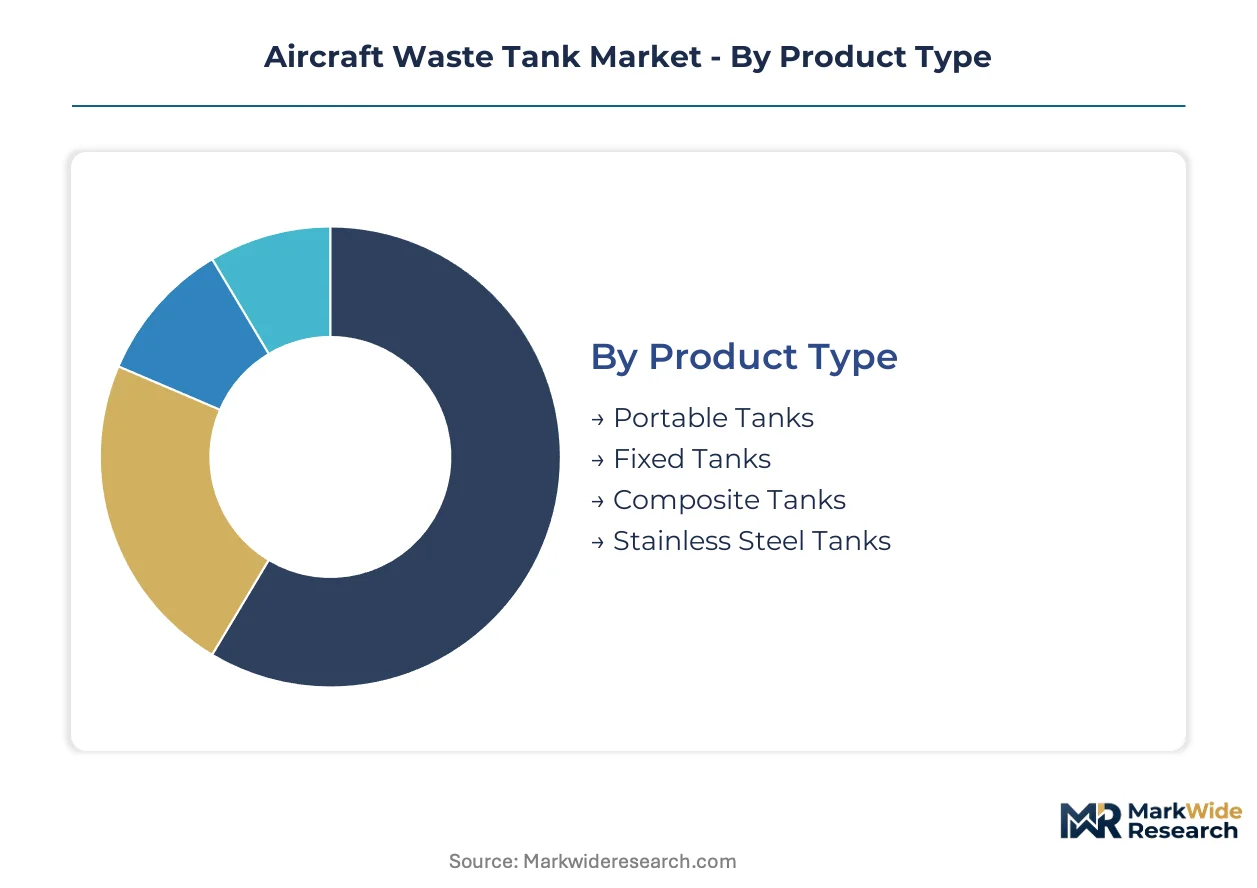
Waste tank architectures fragment sharply between embedded OEM systems and standalone retrofit configurations. Each segment carries distinct qualification burdens, margin profiles, and supplier relationship structures that shape competitive positioning across the value chain.
Product Type:
Integration depth separates tanks designed for permanent airframe embedding from those engineered for rapid cabin reconfiguration.
- Fixed Tanks:Permanently mounted containment vessels integrated into airframe structure during assembly or heavy maintenance events. Commercial narrow-body OEM programs in the United States anchor procurement volumes, with FAA certification requirements compressing supplier qualification timelines.
- Composite Tanks:Glass-reinforced epoxy or thermoplastic resin constructions achieving 15-20% weight reduction over metal equivalents. Fleet modernization across US network carriers accelerates displacement of legacy stainless steel in next-generation single-aisle platforms.
- Portable Tanks:Self-contained units with quick-disconnect interfaces for VIP and medevac conversions requiring rapid cabin reconfiguration.
- Stainless Steel Tanks:Corrosion-resistant alloy constructions rated for field weld-repair and pressure cycling to 75 psi. Military retrofit programs favor these architectures where maintenance simplicity outweighs weight penalties.
Volume placements concentrate in fixed tank configurations; the faster expansion belongs to portable systems for specialized conversion markets.
End User:
Customer scale and procurement sophistication create tiered demand patterns across aviation operational models.
- Commercial Airlines:Network carriers and low-cost operators with centralized procurement functions negotiating multi-year lavatory subsystem contracts. US-based legacy carriers dominate order backlogs as single-aisle fleet renewal accelerates.
- Military Aviation:Defense procurement through NAVAIR and Defense Logistics Agency specifications with parallel compliance layers for airworthiness and combat survivability.
- Private Jets:Fractional ownership fleets and ultra-high-net-worth operators specifying custom tank capacities for extended-range configurations.
- Cargo Airlines:Express freight operators with converted passenger aircraft requiring waste system retention for remaining crew facilities.
Procurement scale peaks with commercial airline contracts; military specification work sustains the most predictable long-term revenue streams.
Distribution Channel:
Channel selection tracks directly with customer technical sophistication and order complexity thresholds.
- Direct Sales:OEM and tier-one supplier relationships managing integrated lavatory module contracts. Major US carriers now consolidate vendor relationships around full-service waste management subsystem providers rather than discrete tank procurement.
- Distributors:Authorized stocking distributors serving MRO facilities with certified replacement units and same-day availability requirements.
- Online Sales:Digital procurement platforms capturing standard aftermarket replacements for routine maintenance events.
- Retailers:Limited presence for specialized aviation hardware resellers serving general aviation segments.
Revenue concentration sits with direct sales relationships; distributor channels capture the steepest expansion trajectory as MRO network density increases.
Installation Type:
Installation timing relative to airframe lifecycle determines engineering complexity and margin capture potential.
- OEM Installation:Factory-integrated systems specified during airframe design and qualified through CS-25 structural integrity protocols. Boeing supply chain integration in the United States anchors this segment's value concentration.
- Aftermarket Installation:Replacement events during scheduled maintenance intervals or damage recovery. The densest US MRO facility networks compress turnaround requirements and favor pre-certified drop-in replacements.
- Integrated Systems:Complete lavatory module procurement bundling tanks, sensors, and control electronics under single-source accountability.
- Custom Solutions:Bespoke engineering for VIP conversions, experimental aircraft, or specialized mission profiles requiring non-standard capacities or mounting configurations.
Factory placements dominate absolute unit volumes; aftermarket events generate the most attractive margin profiles per installation.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation-grade thermoplastic resin production concentrates near Wichita, Kansas, and the broader US Midwest aerospace corridor, with composite precursor supply chains extending into Germany's Ruhr industrial region and China's Yangtze River Delta petrochemical hubs.
United States
Boeing's supply chain integration and dense MRO facility networks in Oklahoma and Washington State drive procurement volumes for next-generation narrow-body platforms. FAA airworthiness directives for fire-resistant containment systems compress supplier qualification timelines. Wichita's aerospace manufacturing cluster anchors composite tank fabrication for OEM installations.
Germany
Diehl Stiftung's dual-source manufacturing with Mexican operations serves European OEM programs through EASA CS-25 certification pathways. REACH chemical compliance restrictions on bisphenol-based curing agents force resin system reformulation. Bavaria's aerospace supplier ecosystem concentrates structural integrity testing capabilities for composite architectures.
China
COMAC C919 indigenous narrow-body production creates demand for SAMR-certified waste systems from qualified tier-one suppliers. MEE environmental standards tightening on effluent handling guidelines advantage compliant containment technologies. Shanghai's Pudong aerospace industrial zone hosts emerging composite fabrication capacity for domestic aviation programs.
Japan
JAMCO Corporation competes on narrow-body retrofit programs with FAA-certified vacuum waste architectures serving regional carrier fleets. METI industrial standards coordinate with international airworthiness protocols for export market access. Nagoya's aerospace manufacturing corridor sustains precision fabrication capabilities for specialized tank configurations.
Mexico
Querétaro's aerospace supplier park hosts Diehl's secondary manufacturing site for European OEM dual-source strategies, creating geographic diversification from German primary production. NAFTA-origin certification requirements shape procurement eligibility for US carrier programs. The Bajío region's growing MRO infrastructure captures aftermarket replacement demand from Latin American operators.
Aircraft Waste Tank Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent subsystem integration opportunities. The supplier base organizes around three maturity tiers: legacy metal fabricators defending retrofit markets, composite specialists capturing OEM qualification slots, and integrated module providers bundling tanks with sensors and electronics. Consolidation pressures favor full-service waste management subsystem contracts over discrete component procurement. Strategic moves concentrate on backward integration into resin formulation and geographic expansion into China's indigenous aviation supply chain.
Among diversified aerospace conglomerates, RTX Corporation and Safran SA exemplify tier-one subsystem integration strategies spanning propulsion and cabin systems. Diehl Stiftung & Co. KG represents the European specialist archetype with dual-continent manufacturing footprints. JAMCO Corporation occupies a position within the narrow-body retrofit specialist tier, while Collins Aerospace anchors the integrated avionics-and-cabin-systems portfolio approach among US-based suppliers.
| Leading Market Players |
|---|
| RTX Corporation |
| Safran SA |
| Diehl Stiftung & Co. KG |
| JAMCO Corporation |
| Collins Aerospace |
| AeroControlex Group Inc. |
| Yokohama Aerospace America, Inc. |
| CIRCOR Aerospace and Defense, Inc. |
| The NORDAM Group LLC |
| Others |
Supply Flow & Price Mechanics
Backward integration into aviation-grade thermoplastic resin formulation anchors supplier pricing power across the Aircraft Waste Tank Market, with Wichita-based composite producers and Ruhr Valley chemical specialists capturing margin premiums through captive feedstock control.
Pricing Analysis
Warranty and field-service bundling separate OEM-integrated lavatory subsystem contracts from unbundled aftermarket tank replacements. Three-tier pricing structure across premium, standard, and economy levels tracks FAA certification grade and volume scale, with US network carriers commanding standard-tier discounts through multi-year commitments. Pricing pressure stems from epoxy resin feedstock volatility squeezing composite tank margins. Military retrofit buyers exhibit highest price sensitivity, prioritizing field-repairable stainless steel over weight-optimized composites.
Supply Chain Analysis
NAFTA-origin certification requirements and China's SAMR localization mandates are reshaping sourcing patterns for US and European OEM programs. Feedstock supply concentrates in the United States, Germany, and China, with aviation-grade thermoplastic resins drawing from Wichita's aerospace corridor, the Ruhr industrial region, and Shanghai's Pudong petrochemical zone. Carbon fiber prepreg and fire-suppression additive dependencies create single-source vulnerability for qualified resin formulations. Distribution runs through Boeing's tier-one supplier network and Diehl's dual-source German-Mexico manufacturing footprint.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aircraft Waste Tank Market functions as a vertical-integration race, with subsystem providers pursuing backward control over thermoplastic resin formulation to defend margin structures against petrochemical feedstock volatility.
For Market Incumbents: Hedge against composite repair skill scarcity by embedding predictive maintenance analytics into tank architectures, converting hardware sales into recurring service revenue. Lock in Wichita and Querétaro capacity additions before SAMR certification timelines compress for COMAC C919 suppliers. Prioritize EASA CS-25 requalification investments as REACH chemical compliance forces 18-24 month resin reformulation cycles.
For New Entrants and Emerging Players: FAA airworthiness directives for fire-resistant containment systems open a window for materials specialists to capture narrow-body OEM qualification slots ahead of 2027-2030 entry-into-service platforms. Target portable tank configurations for VIP and medevac conversions where premium pricing power exceeds commercial airline procurement pressure. Pursue integrated lavatory module contracts rather than discrete tank supply to align with US carrier vendor consolidation behavior.
For Investors and Strategic Acquirers: Exit pathways concentrate in aerospace conglomerate divestiture of non-core cabin systems, with RTX and Safran portfolio reviews likely to surface specialist waste management assets. Five-to-ten year viability hinges on SAMR certification capture for China's indigenous narrow-body production. Monitor MEE environmental standard tightening as the inflection signal for compliant containment technology premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive thermoplastic feedstock supply insulates margins from petrochemical price cycles. |
| SAMR Certification Investment | COMAC C919 qualification unlocks access to China's expanding indigenous narrow-body production. |
| Predictive Maintenance Platform Development | Real-time leak detection capabilities convert hardware sales into recurring service revenue streams. |
| Dual-Source Manufacturing Expansion | Querétaro and German parallel production mitigates trade disruption risk for European OEM programs. |
| REACH-Compliant Resin Reformulation | Bio-based curing agent substitution future-proofs European market access against chemical restriction tightening. |
Methodological Framework
Multi-period observation of FAA airworthiness directive implementation, EASA CS-25 certification timelines, and COMAC supplier qualification progress anchored the trend analysis, supplemented by interviews with aircraft OEM procurement directors, MRO facility maintenance chiefs, thermoplastic resin R&D leads, and aviation regulatory compliance officers. Secondary validation drew from FAA type certificate databases, EASA certification documentation, SAMR public disclosure records, and SEC filings from publicly traded aerospace suppliers. Bottom-up tank unit demand modeling triangulated against top-down fleet modernization projections.
Segment-weighting across fixed versus portable tank architectures, composite versus stainless steel material classes, and OEM versus aftermarket installation channels structured the analytical framework. CAGRs were derived from installed base replacement cycles, narrow-body production rate assumptions, and military retrofit program pacing. Industry-specific forecast inputs incorporated REACH chemical compliance transition timelines and MEE environmental standard evolution scenarios.
The model assumes a particular technology adoption path favoring thermoplastic composite displacement of stainless steel; alternative pathways involving advanced alloy formulations or hybrid architectures would alter the outlook. Forecasts reflect assumptions regarding fleet modernization pacing, regulatory certification timeline compression, and petrochemical feedstock availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Environment Control
Aerospace Flight Control System Market
Aircraft Environment Control
Gas Turbine Air Filtration Market
Aircraft Environment Control
Ice Protection Systems Market
Aircraft Environment Control
Aircraft Air Conditioning Unit Market
Aircraft Environment Control
Turbine Air Filtration Market
Aircraft Environment Control
Commercial Aircraft Air Management System Market
Aircraft Environment Control
HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market
Aircraft Environment Control
Airborne Molecular Contamination Control Services Market