
 Civil Aviation Simulator Market | 2026-2036
Civil Aviation Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Civil Aviation Simulator Market Insights
LED-based visual projection systems are decoupling simulator economics from legacy CRT and lamp-based architectures, cutting lifecycle maintenance costs by half while extending fidelity refresh cycles. CAE Inc. leverages in-house motion platform manufacturing to control supply chain margins across its installed base. Thales Group anchors its position through software-defined cockpit environments that reduce hardware retrofit costs for airline customers. L3Harris Technologies competes in the defense-adjacent segment where military flight training protocols overlap with civil certification requirements.
A civil aviation simulator is a ground-based training system replicating aircraft flight dynamics, cockpit environments, and external visual scenes through computationally modeled aerodynamic databases and six-degree-of-freedom motion platforms. These systems enable zero-risk repetition of emergency procedures, instrument approaches, and crew coordination exercises that live aircraft cannot safely reproduce. Full Flight Simulators retain the dominant value share due to regulatory Level D qualification requirements for type-rating certification, while Flight Training Devices gain ground in ab-initio programs where cost-per-hour economics favor reduced-motion configurations. Software Platforms extract disproportionate margin pools as airlines prioritize networked training management systems and data analytics for competency tracking.
FAA Part 60 and EASA CS-FSTD standards mandate recurrent qualification testing that forces simulator obsolescence cycles and sustains replacement demand across the installed base. ICAO Doc 9625 establishes international baseline proficiency requirements that national regulators transpose into binding procurement specifications for training organizations. China's CAAC maintains distinct certification protocols that create localized compliance barriers for imported systems. Stakeholders must weigh the capital efficiency of visual system upgrades against full platform replacements as next-generation aircraft types enter service volumes.
Market Dynamics
Fleet renewal cycles across major carriers are compressing simulator replacement timelines as airlines transition training infrastructure from legacy wide-body platforms to next-generation single-aisle aircraft types. This hardware refresh imperative collides with stricter FAA Part 60 and EASA CS-FSTD qualification mandates that disqualify older visual and motion systems from type-rating certification.
Growth Catalysts
- FAA Part 60 Recertification Mandates:Airlines in the United States must upgrade or retire simulators that fail recurrent qualification testing, forcing capital deployment into Level D Full Flight Simulators for narrow-body fleet transitions.
- CAAC Localization Requirements:China's distinct certification protocols for imported training systems create captive demand for domestically qualified platforms as Chinese carriers expand pilot training capacity.
- LED Visual System Adoption:Solid-state projection architectures cut lifecycle maintenance expenditures while extending fidelity refresh cycles, improving total cost of ownership for training organizations.
Market Restraints
- Motion Platform Supply Concentration:Electro-hydraulic actuators and electric motion bases depend on a limited supplier base in Germany and the United States, exposing procurement timelines to capacity constraints.
- Computational Hardware Cost Volatility:GPU clusters and real-time computing nodes for aerodynamic modeling face input cost fluctuations from semiconductor foundry allocation priorities.
- Regulatory Divergence Friction:EASA CS-FSTD and FAA Part 60 maintain non-harmonized test criteria, forcing manufacturers to engineer parallel qualification pathways for transatlantic customers.
Strategic Opportunities
- India Ab-Initio Training Expansion:DGCA-mandated pilot hour requirements and fleet growth at Indian low-cost carriers create demand for Flight Training Devices with reduced-motion configurations.
- Software-Defined Cockpit Convergence:Modular avionics emulation is converging with cloud-based scenario management to enable rapid reconfiguration across aircraft types without hardware retrofit.
- Extended Reality Channel Innovation:Mixed reality headsets for procedure training complement full simulators, opening subscription-based distribution models for recurrent training modules.
Industry Challenges
- Level D Certification Timeline Compression:New aircraft type entry into service demands simultaneous simulator qualification, straining engineering resources and stretching validation schedules.
- Legacy System Integration Complexity:Airlines operating mixed-generation fleets must maintain interoperability between 1990s-era host computers and modern visual databases, complicating networked training architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Civil Aviation Simulator Market |
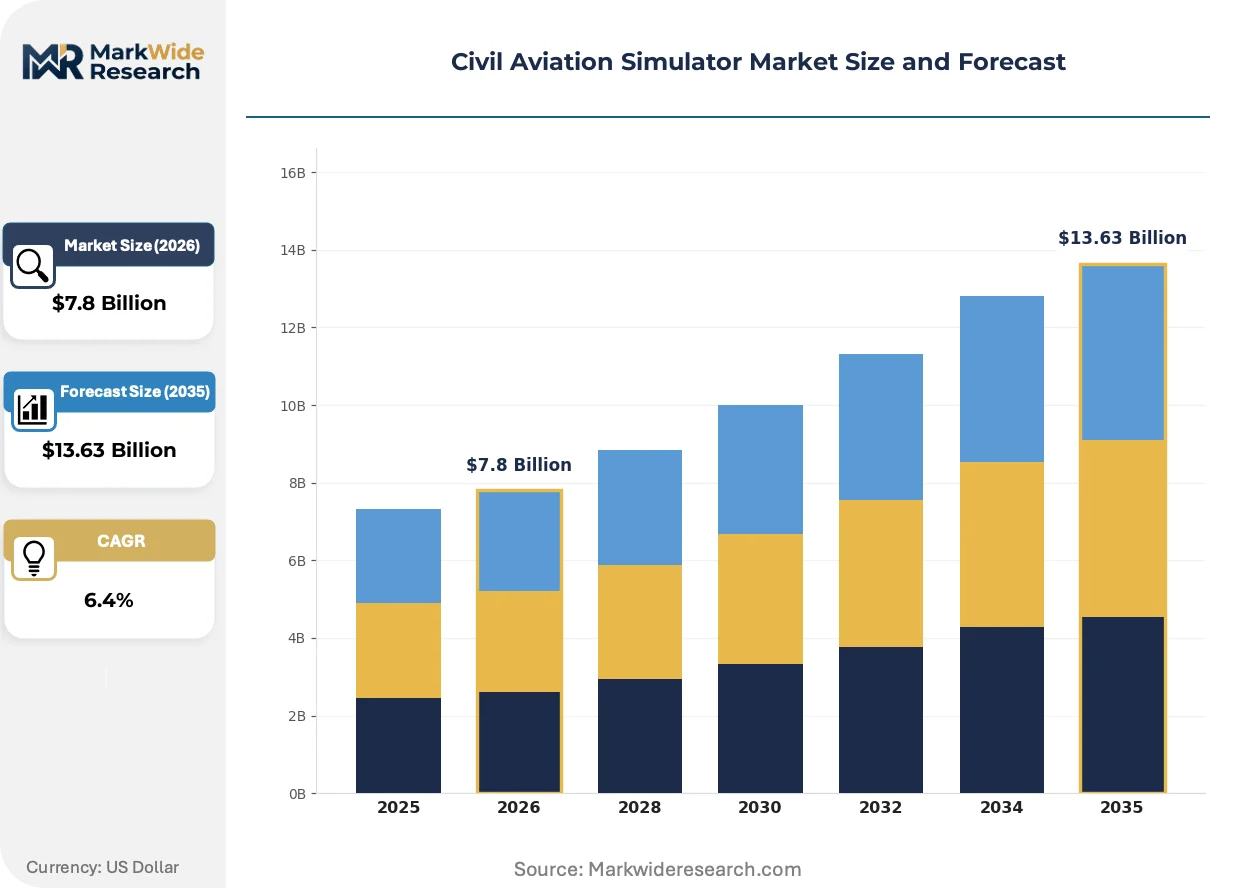
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Flight Simulator, Flight Training Device, Fixed-Base Simulator, Part Task Trainer Technology: Visual Systems, Motion Systems, Software Platforms, Audio Systems, Haptic Feedback Application: Pilot Training, Crew Resource Management, Safety Assessment, Procedural Training, Aircraft Familiarization End User: Airlines, Flight Schools, Defense Forces, Aviation Maintenance Providers, Certification Bodies |
| Companies Covered | CAE Inc., Thales Group, FlightSafety International, L3Harris Technologies, Boeing, Airbus, Lockheed Martin, Honeywell, Rockwell Collins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Civil Aviation Simulator Market Trends and Innovations
Computational advances and regulatory harmonization pressures are restructuring how training systems are architected, procured, and deployed across commercial aviation. These shifts favor modular platforms over monolithic replacements.
Real-time ray-traced visual rendering is converging with LED-based dome projection to eliminate lamp replacement cycles and reduce thermal management overhead. Full Flight Simulator operators in the United States and Germany are adopting these systems to extend qualification intervals. The technology is converging with aerodynamic database streaming to enable faster scenario loading and reduced downtime between training sessions.
EASA CS-FSTD Amendment 3 tightens motion cueing fidelity requirements for Level D qualification, compelling manufacturers to recalibrate washout algorithms and platform response latency. European training organizations face retrofit decisions on installed bases. Narrow-body transition programs at carriers in Germany and France absorb the steepest compliance costs.
Airlines are unbundling after-sales service contracts from initial platform procurement, selecting specialized third-party maintainers for visual system upgrades and motion platform overhauls. This disintermediation fragments vendor lock-in and shifts margin pools toward software updates and data analytics subscriptions. The pattern is most visible among US major carriers with large mixed-fleet simulator inventories.
Civil Aviation Simulator Market Segmentation
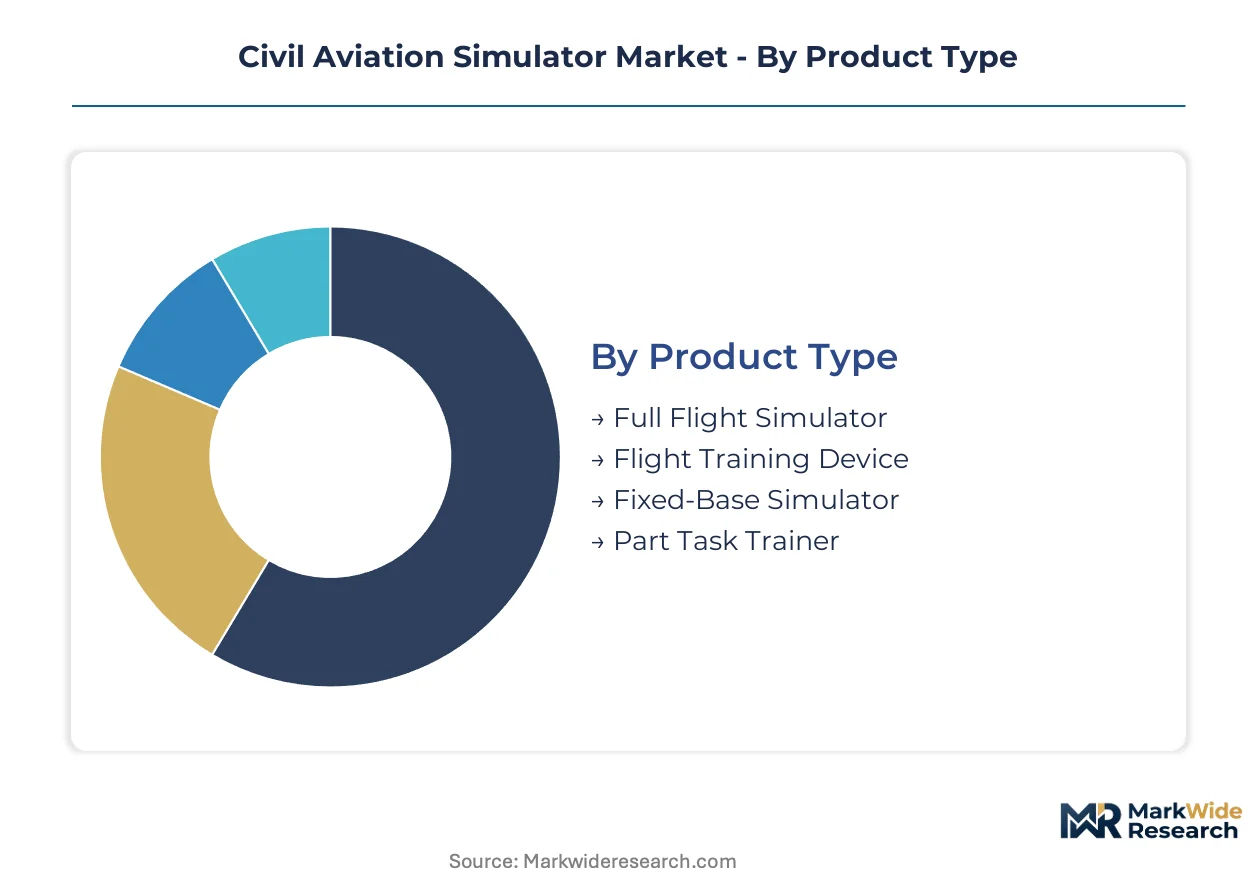
Segmentation in civil aviation simulators reflects divergent capital intensity and regulatory stringency across training applications. Airlines prioritize Level D qualified platforms for type-rating certification, while ab-initio programs seek cost-optimized configurations. Procurement patterns vary sharply by end-user sophistication and fleet complexity.
Product Type:
Standardization dominates high-end certification equipment, while customization proliferates in reduced-motion training devices where airlines balance fidelity against hourly economics.
- Full Flight Simulator:Six-degree-of-freedom motion platforms paired with 220-degree collimated visual systems replicate aircraft flight dynamics for Level D qualification. Demand concentrates at major US and German carriers transitioning narrow-body fleets under FAA Part 60 and EASA CS-FSTD mandates.
- Flight Training Device:Reduced-motion or fixed-base configurations emulate cockpit procedures without motion cueing, targeting ab-initio hour-building and instrument rating preparation. Indian flight schools under DGCA regulations absorb volume growth as the country's low-cost carriers expand pilot pipelines.
- Fixed-Base Simulator:Static cockpit replicas for procedure drilling and systems familiarization at lower capital outlay.
- Part Task Trainer:Modular units isolating specific skills — autopilot management, emergency checklists, or navigation — for targeted competency development.
Leading the category by volume: Flight Training Device. Expanding most quickly: Full Flight Simulator.
Technology:
Cost tier separation runs deepest in visual and motion systems, where LED solid-state architectures displace legacy lamp-based projection at premium price points while software platforms extract recurring revenue.
- Visual Systems:LED dome projection and real-time ray-traced rendering eliminate lamp replacement cycles and reduce thermal management overhead. German and US operators adopt these systems to extend qualification intervals and cut lifecycle maintenance expenditures.
- Software Platforms:Aerodynamic database hosting, scenario management tools, and competency tracking analytics generate subscription revenue streams. Airlines unbundle these from hardware procurement, fragmenting vendor lock-in.
- Motion Systems:Electro-hydraulic and electric actuators delivering six-degree-of-freedom cueing for spatial disorientation and turbulence replication.
- Audio Systems:Spatial sound reproduction of engine noise, weather, and cockpit alerts for immersive environment construction.
- Haptic Feedback:Force-feedback controls replicating control loading and trim forces in sidestick and yoke interfaces.
Dominating procurement spend: Visual Systems. Climbing the fastest: Software Platforms.
Application:
Customer type determines fidelity requirements, with commercial airlines demanding maximum certification utility while military and maintenance operators accept reduced configurations.
- Pilot Training:Type-rating certification, recurrent proficiency checks, and transition training between aircraft types. Chinese carriers under CAAC protocols drive demand for domestically qualified Full Flight Simulators.
- Crew Resource Management:Multi-crew coordination exercises emphasizing communication, decision-making, and workload distribution in abnormal scenarios.
- Safety Assessment:Controlled exposure to emergency procedures — engine failures, decompression, rejected takeoffs — impractical in live aircraft.
- Procedural Training:Repetitive drilling of checklist execution, FMS programming, and approach briefing protocols.
- Aircraft Familiarization:Initial exposure to cockpit layout, systems architecture, and handling characteristics for new type introductions.
Capturing the largest training hour allocation: Pilot Training. Gaining share fastest: Crew Resource Management.
End User:
Volume concentration sits with fleet operators, while margin accrues to specialized training providers and certification bodies with technical audit authority.
- Airlines:In-house training departments at major carriers maintaining mixed-fleet simulator inventories. US network carriers fragment after-sales service contracts across third-party maintainers.
- Flight Schools:Ab-initio and advanced training organizations supplying pilots to regional and low-cost operators.
- Defense Forces:Military flight training protocols overlapping with civil certification requirements, particularly in dual-use platform procurement.
- Aviation Maintenance Providers:Troubleshooting and systems diagnostics training for line and base maintenance technicians.
- Certification Bodies:Regulator-operated or designated facilities conducting initial and recurrent qualification testing under FAA, EASA, and CAAC authority.
Commanding installed base share: Airlines. Steepest expansion trajectory: Flight Schools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for civil aviation simulators concentrates in the United States, China, and Germany, where fleet renewal cycles and regulatory compliance requirements drive procurement of next-generation training systems. Each geography presents distinct certification protocols and procurement patterns that shape vendor market access.
United States
FAA Part 60 recertification mandates force airlines to upgrade or retire simulators failing recurrent qualification testing. Major network carriers fragment after-sales service contracts across third-party maintainers to reduce vendor lock-in. Dallas-Fort Worth and Atlanta host the densest concentrations of Level D Full Flight Simulators serving narrow-body fleet transitions.
China
CAAC maintains distinct certification protocols for imported training systems that create localized compliance barriers and captive demand for domestically qualified platforms. Chinese carriers expanding pilot training capacity must navigate these protocols when procuring Full Flight Simulators. Shanghai and Beijing anchor the country's simulator infrastructure development.
Germany
EASA CS-FSTD Amendment 3 tightens motion cueing fidelity requirements for Level D qualification, compelling manufacturers to recalibrate washout algorithms. German training organizations face retrofit decisions on installed bases as narrow-body transition programs absorb steep compliance costs. Munich and Frankfurt concentrate the country's simulator maintenance expertise.
India
DGCA-mandated pilot hour requirements and fleet growth at Indian low-cost carriers create demand for Flight Training Devices with reduced-motion configurations. Flight schools under DGCA regulations absorb volume growth as the country's aviation sector expands. Mumbai and Delhi house the primary training infrastructure clusters.
United Kingdom
UK training organizations operate under EASA-derived certification standards with some retained national variations post-Brexit. British Airways and Virgin Atlantic maintain mixed-fleet simulator inventories requiring interoperability across generations. London and the Southeast concentrate the country's aviation training capacity.
Civil Aviation Simulator Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform builders commanding premium positioning in Level D Full Flight Simulators while component suppliers capture recurring revenue in visual system upgrades. The market structure favors incumbents with captive motion platform manufacturing and established regulatory qualification pathways. Three archetypes dominate: vertically integrated platform builders, software-defined cockpit specialists, and defense-adjacent dual-use providers. Competitive moves center on unbundling after-sales service contracts from initial procurement and converging modular avionics emulation with cloud-based scenario management.
Among North American integrated specialists, CAE Inc., L3Harris Technologies, and FlightSafety International exemplify distinct strategic positions. CAE Inc. occupies a position as a vertically integrated platform builder with in-house motion platform manufacturing. L3Harris Technologies sits within the defense-adjacent segment where military flight training protocols overlap with civil certification requirements. FlightSafety International represents the specialized training provider archetype with deep airline customer relationships.
| Leading Market Players |
|---|
| CAE Inc. |
| Thales Group |
| FlightSafety International |
| L3Harris Technologies |
| Boeing |
| Airbus |
| Lockheed Martin |
| Honeywell |
| Rockwell Collins |
| Others |
Pricing and Supply Chain Analysis
Major airline training departments in the United States, China, and Germany concentrate procurement authority for Level D Full Flight Simulators, enabling value-based pricing tied to regulatory qualification timelines rather than commoditized hardware costs. This buyer concentration permits manufacturers to extract premium positioning through bundled after-sales service contracts and software subscription tiers.
Pricing Analysis
Volume concentrates in Flight Training Devices while margin pools accrue to Full Flight Simulators and software platforms. Three-tier pricing structure across Level D certification-grade systems, intermediate motion platforms, and fixed-base training devices reflects fidelity differentials and regulatory utility. Cost compression in visual system upgrades intensifies as LED-based architectures extend refresh cycles and fragment vendor lock-in. Flight schools under DGCA regulations in India exhibit the highest price sensitivity, while major network carriers in the United States prioritize certification speed over unit economics.
Supply Chain Analysis
China's CAAC localization requirements and domestic-content mandates for imported training systems are reshaping sourcing patterns toward joint-venture manufacturing partnerships. Electro-hydraulic actuators and electric motion bases draw from concentrated production in Germany and the United States, while GPU clusters for real-time aerodynamic modeling hinge on semiconductor foundry allocation in Taiwan and South Korea. Single-source vulnerability in motion platform manufacturing exposes procurement timelines to capacity constraints. Distribution runs through direct OEM sales to airline training departments and specialized third-party maintainers unbundling after-sales service from initial platform procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Civil aviation simulator manufacturing is becoming a vertical-integration race as players pursue captive control over motion platform production to defend margin pools against third-party visual system upgraders.
For Market Incumbents: Acquire motion platform manufacturing capabilities to insulate supply chain margins from electro-hydraulic actuator capacity constraints in Germany and the United States. Consolidate software platform subscriptions with hardware procurement to counter disintermediation by specialized third-party maintainers. Lock in CAAC qualification pathways ahead of Chinese fleet expansion to preempt domestic competitor certification. For New Entrants and Emerging Players: Enter via Flight Training Device supply to Indian flight schools under DGCA-mandated hour requirements, where reduced-motion configurations lower capital barriers and price sensitivity favors new suppliers. Target cloud-based scenario management and competency analytics as unbundled software layers where incumbent hardware vendors retain legacy architectures. Pursue partnership routes with regional airline training departments seeking alternatives to integrated platform builders. For Investors and Strategic Acquirers: The window for entry favors software-defined cockpit specialists with modular avionics emulation capabilities that enable rapid aircraft type reconfiguration without hardware retrofit. Long-term viability rests on convergence between civil certification requirements and military flight training protocols in dual-use procurement. Watch EASA-FAA regulatory harmonization progress as the signal indicating whether parallel qualification pathway investments will yield stranded engineering assets or expanded transatlantic market access.| Strategic Initiative | Industry Significance |
|---|---|
| Motion Platform Manufacturing Integration | Captive supply of electro-hydraulic actuators insulates CAE Inc. from German supplier capacity constraints. |
| Software-Defined Cockpit Development | Thales Group's modular avionics emulation reduces hardware retrofit costs for airline fleet transitions. |
| CAAC Localization Partnership | Joint ventures with Chinese manufacturers unlock access to domestically qualified Full Flight Simulator procurement. |
| Third-Party Maintenance Unbundling | US network carriers fragment after-sales contracts to reduce vendor lock-in and shift margin to specialized upgraders. |
| Extended Reality Training Module Launch | Mixed reality headsets for procedure training open subscription-based distribution for recurrent training at flight schools. |
Research Methodology
Regulatory filing databases, airline fleet planning disclosures, and CAAC certification records formed the secondary backbone of this analysis. Primary interviews with simulator procurement directors at major carriers, flight training organization managers, motion platform engineering leads, and EASA qualification test specialists triangulated against customs trade data and OEM order backlogs. Bottom-up segmentation modeling across product type, technology tier, and end-user category converged with top-down market sizing from installed base replacement cycles.
Historical trendline analysis of simulator delivery patterns and qualification timelines established baseline growth trajectories across the projection horizon. The forecast framework models product type, technology architecture, application intensity, and end-user sophistication as primary segmentation dimensions. CAGRs derive from regression analysis of fleet renewal cycles correlated with FAA Part 60 and EASA CS-FSTD mandate implementation schedules. Inputs include narrow-body fleet transition timelines, LED visual system adoption curves, and CAAC localization requirement enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios between FAA and EASA or accelerated CAAC domestic-content mandates. Forecasts reflect assumptions around semiconductor foundry capacity allocation for GPU clusters and motion platform supplier expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Flight Simulator Market
Simulation and Training
Civil Aerospace Simulation and Training Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
Dynamic Flight Training Compartments Market
Simulation and Training
Trainer Aircraft Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
Asia-Pacific Ship Bridge Simulators Market
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Simulators Market
Simulation and Training
Middle East Civil Aviation Flight Training and Simulation Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
Pilot Training Market
Simulation and Training
Satellite Simulator Market
Simulation and Training
Air Traffic Control Simulator and Training Market