
 Aerotropolis Market | 2026-2036
Aerotropolis Market Size, Share, and Industry Trends Forecast 2026-2036
Aerotropolis Market Analysis
The capital-intensity divergence between full-service airport operators and design-engineering firms is collapsing as brownfield retrofit projects multiply. Aéroports de Paris SA leverages its integrated real estate development arm to sustain revenue streams beyond aeronautical charges. TAV Havalimanlari Holding A.S. anchors its competitive stance through operational control across emerging market terminals. VINCI Airports SAS differentiates via long-term concession contracts that extend across multiple continents.
An aerotropolis constitutes a metropolitan subregion whose infrastructure, land use, and economic activity are organized around and serviced by a multimodal airport, typically encompassing logistics parks, commercial zones, and transit corridors within a 30-kilometer radius. The primary commercial purpose centers on minimizing time-cost friction for air-cargo-dependent industries, high-value manufacturing, and business services requiring rapid global connectivity. Greenfield developments lead absolute investment volume, though brownfield expansions capture accelerating interest where urban density precludes fresh land assembly. Mixed-use zoning configurations concentrate margin pools by blending commercial, residential, and industrial land use within single master plans. Public-private partnership investment structures dominate transaction flow, particularly in jurisdictions where sovereign capital bridges infrastructure gaps that private capital alone cannot close.
FAA airport improvement program guidelines, EU Green Deal carbon-neutrality mandates, and EASA aerodrome design standards collectively shape permissible development density, emissions thresholds, and safety-critical spatial separations. The EU F-Gas Regulation specifically constrains cooling and climate-control infrastructure choices across European aerotropolis commercial cores. Stakeholders must monitor how evolving national carbon-accounting rules recalibrate the feasibility horizon for aviation-anchored real estate in jurisdictions where regulatory stringency outpaces infrastructure depreciation cycles.
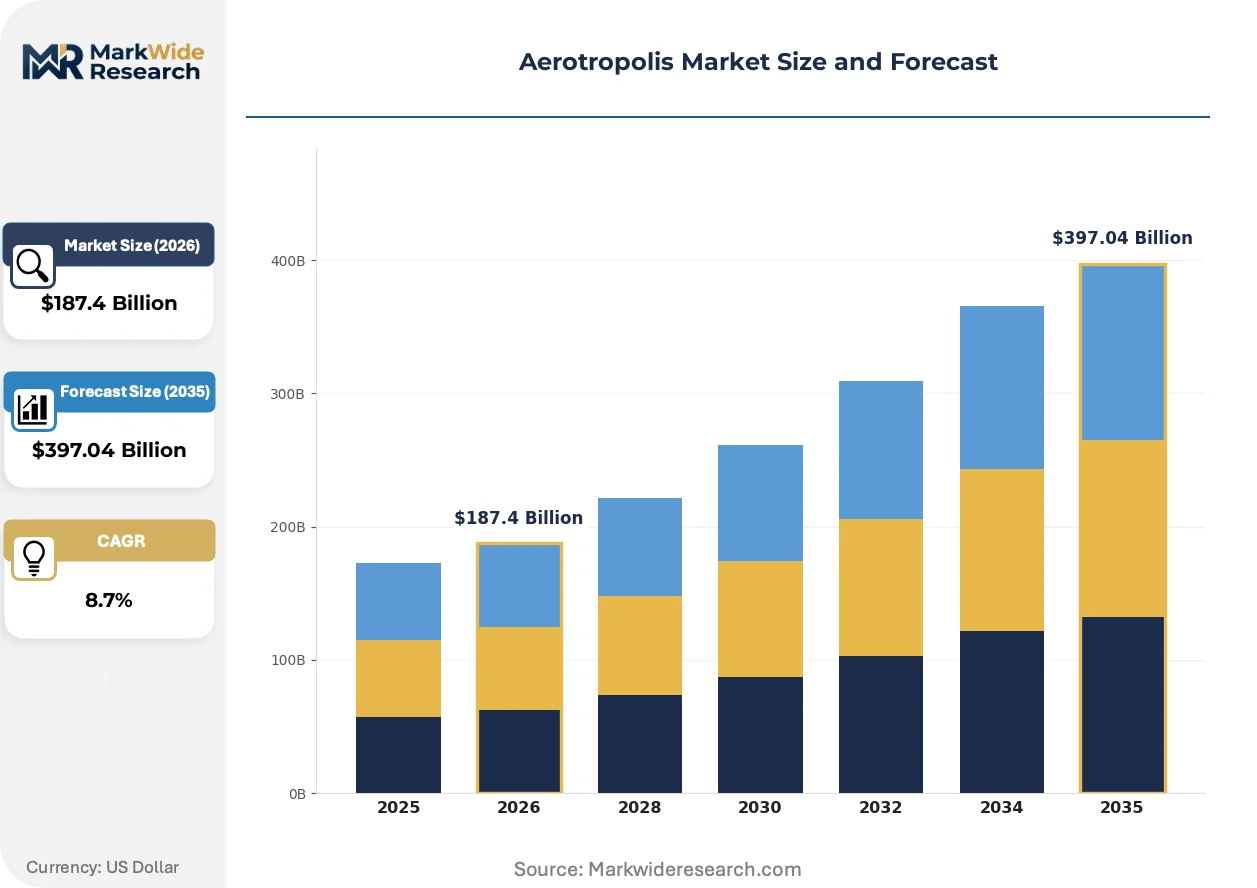
Market Dynamics
EU F-Gas Regulation mandates are compressing infrastructure replacement cycles across European airport cities, forcing developers to front-load capital into low-carbon cooling systems before depreciation schedules justify the spend.
Growth Catalysts
- E-commerce fulfillment density:Logistics operators cluster within 30-kilometer airport radii to minimize last-mile friction for air-cargo-dependent inventory. This spatial compression accelerates land absorption rates in master-planned aviation zones.
- EU Green Deal carbon-neutrality mandates:European aerotropolis developments secure preferential financing terms when embedding renewable energy generation and electric ground transport into initial site plans.
- Dubai Airports Company master-planning authority:Sovereign-backed capital deployment in the United Arab Emirates demonstrates how integrated aviation-real estate development can anchor metropolitan economic subregions.
Market Restraints
- Capital intensity of brownfield retrofits:Existing terminal-adjacent districts require extensive utility reconfiguration to meet modern multimodal connectivity standards, stretching payback periods beyond private capital tolerance.
- Regulatory fragmentation across jurisdictions:FAA airport improvement program guidelines diverge from EASA aerodrome design standards, complicating cross-border developer playbooks and inflating compliance overhead.
- Land assembly constraints in dense urban cores:Cities with mature airport infrastructure lack contiguous parcels for integrated logistics-residential-commercial zoning, fragmenting development potential.
Strategic Opportunities
- Underpenetrated secondary aviation hubs:Mid-tier airports in India and Southeast Asia present greenfield aerotropolis potential where sovereign capital bridges infrastructure gaps private investors cannot close alone.
- Convergence of autonomous ground transport and smart building management:Integrated digital infrastructure layers enable real-time cargo flow optimization across multimodal transit corridors.
- Public-private partnership standardization:Jurisdictions refining concession contract templates reduce transaction friction for long-term infrastructure investors seeking multi-decade revenue visibility.
Industry Challenges
- Specialized urban planning talent scarcity:Developers struggle to recruit professionals fluent in both aviation operations and large-scale real estate master planning, slowing project velocity.
- Legacy system integration complexity:Brownfield expansions must interface with decades-old terminal IT and baggage handling infrastructure, inflating technical risk during phased construction.
- Carbon accounting certification timelines:Emerging national frameworks for aviation-anchored real estate emissions reporting lack harmonization, delaying project financing approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerotropolis Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Development Type: Greenfield, Brownfield, Mixed-Use, Transit-Oriented Land Use: Commercial, Residential, Industrial, Recreational Transportation Mode: Aviation, Rail, Road, Public Transport Investment Source: Public Sector, Private Sector, PPP, Venture Capital |
| Companies Covered | Aéroports de Paris SA, Dubai Airports Company P.J.S.C., AECOM, Royal Schiphol Group N.V., Fraport AG, Aena SME, S.A., Beijing Capital International Airport Company Limited, TAV Havalimanlari Holding A.S., VINCI Airports SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerotropolis Market Emerging Trajectories
Digital twin infrastructure modeling is compressing design-validation cycles for complex multimodal developments. This capability shift enables real-time scenario testing before physical ground-breaking.
Geothermal and ambient loop cooling systems are fragmenting the traditional mechanical-HVAC specification lock-in for large-scale commercial cores. Airport developers in Northern Europe are piloting these technologies to preempt EU F-Gas Regulation compliance costs. The technology is fragmenting vendor concentration in climate-control procurement, opening specification windows for specialized engineering firms.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant infrastructure obsolescence across European aerotropolis commercial zones. Developers must now specify ultra-low global warming potential alternatives in initial construction rather than retrofitting later. Logistics operators with long-term lease commitments in Amsterdam, Frankfurt, and Paris airport cities face the steepest compliance cost curves.
Consolidated procurement by global logistics platforms is compressing lease negotiation timelines for prime aerotropolis land parcels. Third-party fulfillment operators now demand pre-certified, move-in-ready facilities rather than build-to-suit arrangements. This pattern concentrates development risk with infrastructure owners in the United Arab Emirates and selective Southeast Asian hubs where speculative construction precedes tenant commitment.
Aerotropolis Market Segmentation
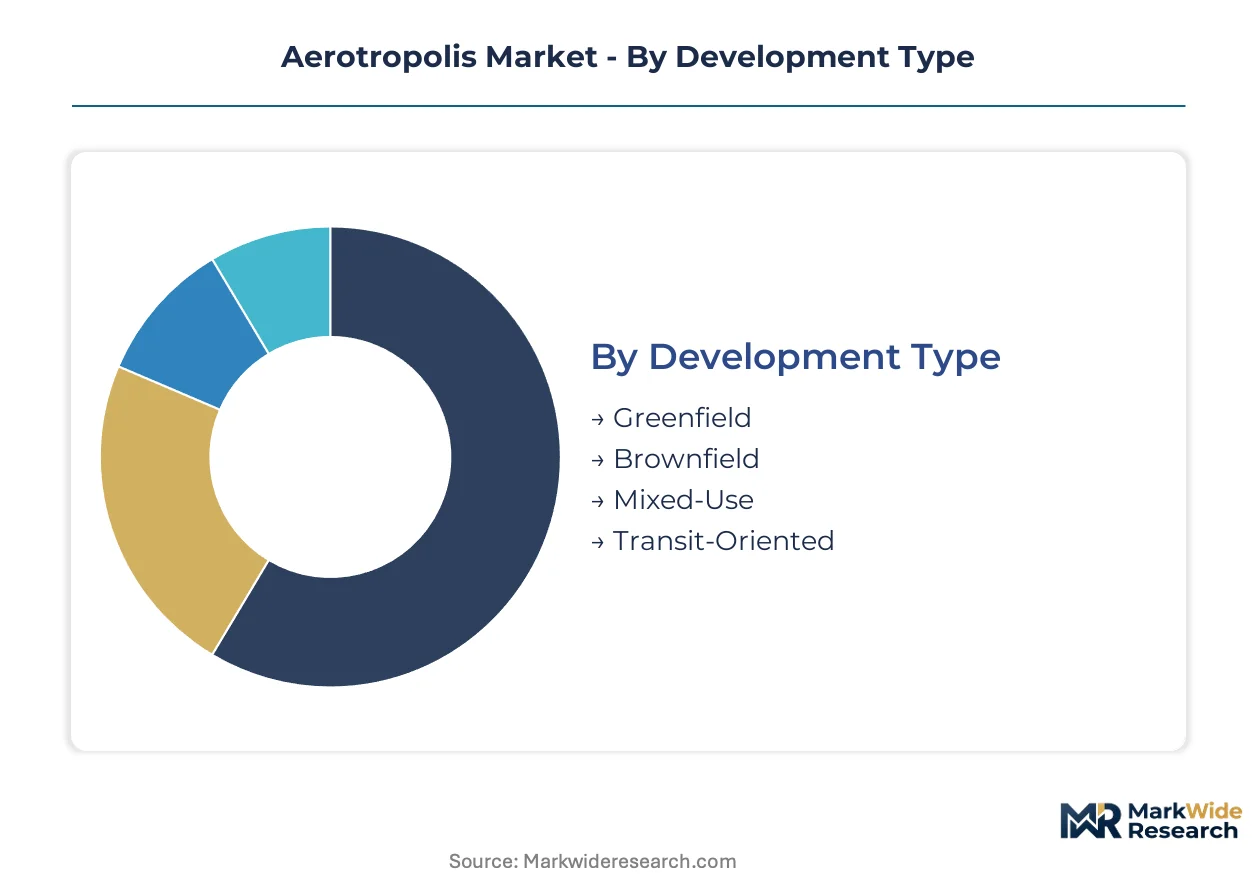
Aerotropolis developments fragment across development approach, land allocation, modal connectivity, and capital structure. Each segmentation axis determines risk-return profiles and regulatory exposure for infrastructure investors.
Development Type:
Greenfield master plans flow through sovereign wealth funds and long-dated infrastructure vehicles, while brownfield retrofits channel through operational improvement funds seeking yield compression.
- Greenfield:Fresh land assembly enables integrated zoning from inception. Dubai Airports Company deploys this model across desert-adjacent parcels where sovereign capital absorbs upfront earthworks and utility backbone costs.
- Brownfield:Existing terminal districts require phased reconstruction around active aviation operations. Amsterdam Schiphol and Frankfurt Airport face the steepest EU F-Gas Regulation compliance costs as they retrofit legacy cooling infrastructure.
- Mixed-Use:Blends logistics, commercial, and residential within single master plans. Singapore Changi and Incheon International anchor regional exemplars.
- Transit-Oriented:Prioritizes multimodal rail and metro integration over highway dependency. Paris Charles de Gaulle and London Heathrow concentrate development risk around Crossrail and RER extensions.
Greenfield dominates installed base. Brownfield is where expansion concentrates.
Land Use:
Cost tiers separate premium commercial frontage from volume industrial absorption, with residential zoning capturing residual land value in mature markets.
- Commercial:Office and retail clusters command lease premiums within 10 kilometers of terminal cores. Frankfurt Airport City and Amsterdam Zuidas demonstrate rent escalation tied to financial services tenant density.
- Industrial:Logistics parks and light manufacturing absorb the largest contiguous footprints. E-commerce fulfillment operators in the United Arab Emirates and India pre-commit to build-to-suit specifications before construction completion.
- Residential:Workforce housing and executive accommodations complete the 24-hour activity cycle. Incheon and Songdo International Business District integrate Korean national housing policy with aviation employment targets.
- Recreational:Hotels, conference facilities, and entertainment venues capture transit passenger dwell time. Singapore Jewel Changi integrates retail-entertainment hybrid programming directly adjacent to arrival halls.
Industrial land absorbs capital fastest. Commercial yields the steepest rent per square meter.
Transportation Mode:
Modal hierarchy determines cargo velocity and passenger catchment radius, with aviation-rail interchanges commanding the highest development priority.
- Aviation:Runway and apron capacity constraints dictate ultimate throughput ceilings. Dubai International and Al Maktoum International coordinate dual-airport capacity allocation through Emirates airline network planning.
- Rail:High-speed and commuter rail extensions compress ground access times. France's SNCF and Germany's Deutsche Bahn operate dedicated airport express services feeding Paris CDG and Frankfurt terminals.
- Road:Highway and arterial networks handle last-mile distribution for time-definite cargo. Los Angeles World Airports struggles with Interstate 405 congestion affecting LAX-adjacent logistics parks.
- Public Transport:Metro and bus systems anchor workforce accessibility in dense urban cores. London Heathrow's Elizabeth Line connection reduced central London journey times below 30 minutes.
Rail integration determines premium land values. Road networks handle residual freight volume.
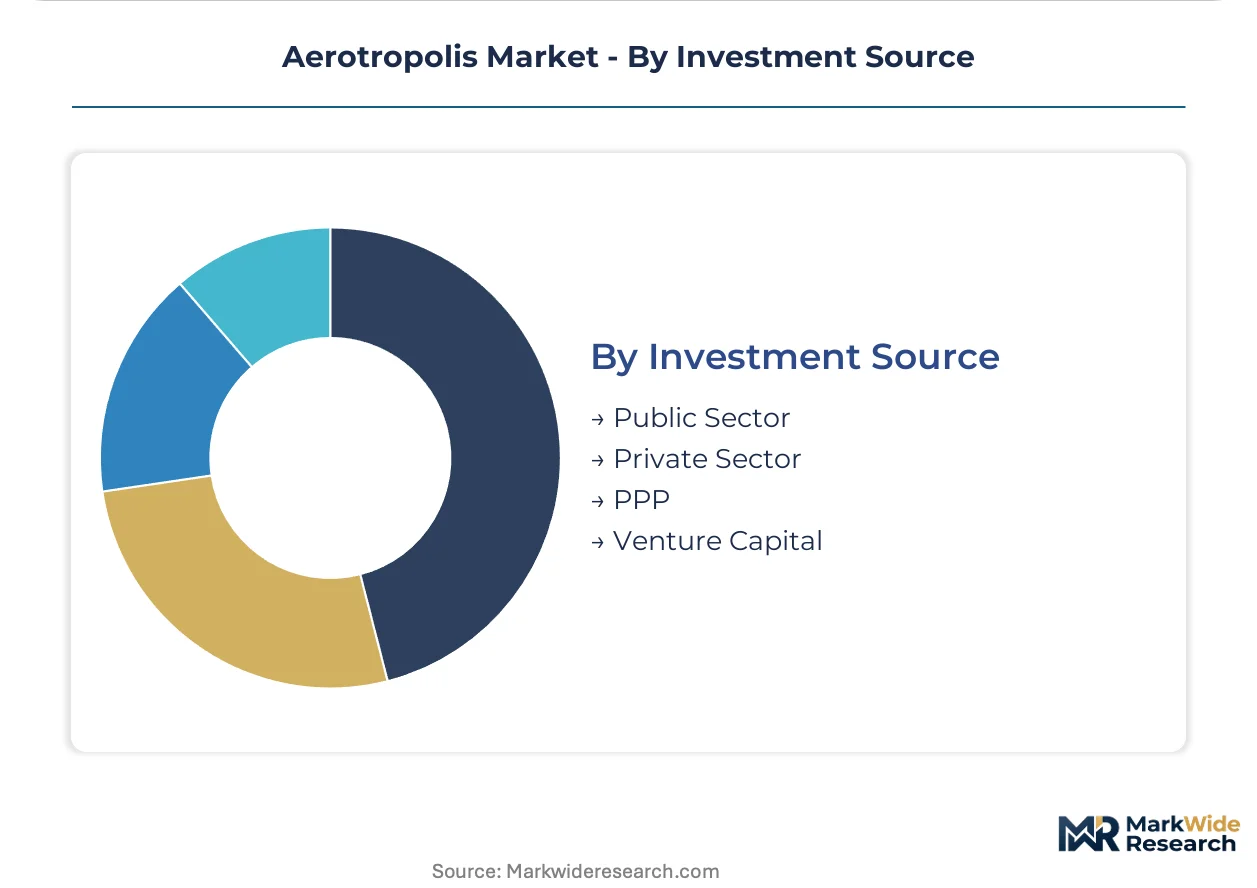
Investment Source:
Capital maturity separates construction-phase risk from operational yield, with blended structures dominating jurisdictions where private capital cannot close infrastructure gaps alone.
- Public Sector:Sovereign and municipal capital absorbs land assembly and environmental remediation costs. India's National Investment and Infrastructure Fund channels public capital into Navi Mumbai and Jewar aerotropolis greenfields.
- Private Sector:Institutional investors and REITs acquire stabilized income-producing assets. Groupe ADP and VINCI Airports recycle concession cash flows into development-ready land banks.
- PPP:Availability-payment and revenue-risk contracts split construction and operational phases. Turkey's TAV Havalimanlari structures Istanbul and Ankara expansions through build-operate-transfer frameworks.
- Venture Capital:Early-stage technology and propulsion ventures cluster near research-intensive aviation zones. Urban air mobility startups concentrate around Dallas-Fort Worth and Los Angeles test corridors.
PPP structures dominate transaction flow. Private capital concentrates in operational assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import intensity determines aerotropolis investment viability across major aviation hubs. Sovereign capital flows concentrate where trade corridors intersect with passenger volume scale, compressing development timelines for integrated aviation-real estate zones.
United States
E-commerce fulfillment operators cluster within 30-kilometer radii of Memphis and Louisville cargo hubs, minimizing time-definite distribution friction. FAA airport improvement program guidelines shape permissible development density around active runways. Dallas-Fort Worth anchors autonomous ground transport pilot corridors linking terminal-adjacent logistics parks to regional distribution networks.
Germany
High-value manufacturing supply chains demand rapid air-cargo connectivity for just-in-time component flows. EU F-Gas Regulation mandates accelerate cooling infrastructure replacement cycles across Frankfurt Airport City commercial cores. Deutsche Bahn coordinates dedicated airport express services feeding terminal-adjacent development zones with 15-minute central city access.
United Arab Emirates
Sovereign-backed capital deployment absorbs upfront earthworks costs for desert-adjacent greenfield master plans. Dubai Airports Company exercises integrated planning authority across dual-airport capacity allocation. Al Maktoum International anchors the largest contiguous logistics-residential-commercial zoning footprint in the Middle East aviation corridor.
China
Dual carbon goals recalibrate cooling and ground transport specifications for aviation-anchored real estate in Beijing and Shanghai airport cities. Beijing Capital International Airport Company channels state capital into terminal-adjacent mixed-use districts. Yangtze River Delta aerotropolis developments prioritize high-speed rail interchange capacity over highway-dependent cargo flows.
India
National Investment and Infrastructure Fund bridges land assembly gaps that private capital cannot close alone at Navi Mumbai and Jewar greenfields. PLI scheme incentives attract electronics manufacturers requiring air-cargo connectivity for component imports. Bangalore and Hyderabad airport cities concentrate venture capital for urban air mobility testing corridors.
Aerotropolis Market Vendor Landscape
Concentration sits with full-service airport operators possessing integrated real estate development arms. The competitive terrain splits between sovereign-backed aviation authorities and concession-holding infrastructure investors. Strategic archetypes encompass vertically integrated airport developers, design-engineering consortiums, and long-term concession operators. Dominant competitive moves include brownfield retrofit project accumulation and multi-decade concession contract extension across emerging market terminals.
Among European integrated developers, Aéroports de Paris SA and Fraport AG exemplify the vertically integrated archetype combining terminal operations with adjacent commercial real estate control. Royal Schiphol Group N.V. occupies a position within the transit-oriented development tier, anchoring multimodal rail integration strategies. Dubai Airports Company P.J.S.C. represents sovereign-backed capital deployment at scale, demonstrating how integrated aviation-real estate planning can anchor metropolitan economic subregions across desert-adjacent greenfields.
| Leading Market Players |
|---|
| Aéroports de Paris SA |
| Dubai Airports Company P.J.S.C. |
| AECOM |
| Royal Schiphol Group N.V. |
| Fraport AG |
| Aena SME, S.A. |
| Beijing Capital International Airport Company Limited |
| TAV Havalimanlari Holding A.S. |
| VINCI Airports SAS |
| Others |
Supply Flow & Price Mechanics
Dual-airport capacity coordination in Dubai generates scale economies that compress per-unit land development costs across desert-adjacent greenfields, anchoring price floors that brownfield retrofits in Frankfurt and Amsterdam cannot match without sovereign capital subsidies. This scale divergence concentrates supply-side pricing power with integrated aviation authorities possessing contiguous land banks, while fragmenting procurement leverage for logistics operators locked into multi-year lease commitments.
Pricing Analysis
Industrial logistics buyers anchor a three-tier pricing structure across premium, standard, and economy facility levels, with rent escalation tied to proximity-to-terminal metrics and pre-certification status for EU F-Gas Regulation compliance. Price differentiation separates build-to-suit specifications from speculative shell deliveries, with the steepest premiums commanding 10-kilometer terminal radii in Frankfurt and Paris. Cost compression in standard-tier logistics facilities is intensifying because consolidated procurement by global fulfillment platforms compresses lease negotiation timelines. E-commerce operators exhibit the highest price sensitivity, while sovereign-backed aviation authorities demonstrate the least due to long-dated infrastructure holding periods.
Supply Chain Analysis
Container availability fluctuations across Asia-Europe trade lanes directly affect HVAC equipment and specialized cooling infrastructure lead times for European aerotropolis retrofits. Manufacturing concentration for low-global-warming-potential refrigerant systems centers on Germany, Japan, and South Korea, while geothermal drilling equipment and ambient loop components draw from Danish and Swiss engineering specialists. Single-source vulnerability sits with specialized urban planning talent fluent in both aviation operations and large-scale real estate master planning. Distribution runs through concession-holding infrastructure investors with multi-decade land control rather than speculative developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerotropolis development sits within an early-cycle expansion phase, with e-commerce fulfillment density and sovereign capital deployment in secondary aviation hubs driving penetration gains faster than mature market saturation models project.
For Market Incumbents: Secure brownfield retrofit project accumulation in European airport cities before EU F-Gas Regulation phase-down schedules accelerate compliance cost curves beyond private capital tolerance. Deepen upstream control over specialized engineering talent pools to defend against design-engineering consortiums capturing specification influence in emerging market terminals.
For New Entrants and Emerging Players: Lead with digital twin infrastructure modeling capabilities to compress design-validation cycles for complex multimodal developments in underpenetrated secondary hubs across India and Southeast Asia. Target mid-tier airports where sovereign capital bridges infrastructure gaps that private investors cannot close alone, positioning around real-time cargo flow optimization as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among concession-holding infrastructure investors with multi-decade land control and operational improvement fund structures. Long-term viability over extended holding periods hinges on acquisition targets possessing integrated real estate development arms rather than pure terminal operators. Watch for harmonization in national carbon-accounting frameworks for aviation-anchored real estate as the signal for financing approval velocity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Retrofit Accumulation | Captures EU F-Gas Regulation compliance premiums before depreciation cycles justify replacement spend. |
| Digital Twin Infrastructure Deployment | Compresses design-validation timelines for Amsterdam and Frankfurt multimodal corridor expansions. |
| Sovereign Capital Partnership Structuring | Bridges land assembly gaps at Navi Mumbai and Jewar greenfields that private capital cannot close alone. |
| Geothermal Cooling System Specification | Preempts EU F-Gas Regulation phase-down costs across Northern European aerotropolis commercial cores. |
| Rail Integration Priority Development | Determines premium land values at Paris CDG and London Heathrow through Crossrail and RER extensions. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of concession contract filings, EU regulatory submissions, and infrastructure investment databases, cross-checking insights from airport real estate development executives, logistics facility procurement leads, urban planning directors, and sovereign wealth fund infrastructure officers. Secondary validation draws from EASA aerodrome design standards documentation, FAA airport improvement program guidelines, EU Green Deal implementation reports, and customs data on HVAC equipment trade flows. Bottom-up project pipeline aggregation triangulates against top-down macroeconomic demand modeling.
Segmentation dimensions modeled span development type, land use allocation, modal connectivity hierarchy, and capital structure across the projection horizon. CAGRs derive from scenario-weighted demand curves incorporating e-commerce fulfillment density trajectories, carbon-neutrality mandate compliance timelines, and sovereign capital deployment patterns. Industry-specific forecast inputs include runway capacity utilization rates and high-speed rail interchange completion schedules.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce growth trajectories, stable sovereign capital availability, or harmonized carbon-accounting frameworks would require recalibration. Forecasts reflect documented assumptions regarding logistics operator spatial compression preferences and regulatory stringency pacing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Telescopic Masts Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Runway Lighting System Market
Airport Infrastructure
Engineered Material Arresting System Market
Airport Infrastructure
Airport Kiosk Market
Airport Infrastructure
Airport Services Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Airport Moving Walkways Market
Airport Infrastructure
Airfield Ground Lighting Market