
 Airport Passenger Boarding Bridge Market | 2026-2036
Airport Passenger Boarding Bridge Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Passenger Boarding Bridge Market Outlook
Aftermarket maintenance contracts and software-defined docking automation is rebalancing how OEMs capture lifetime value from each installed boarding bridge. JBT AeroTech leverages its North American service infrastructure to lock in long-term airport contracts. ThyssenKrupp Airport Solutions anchors European demand through precision-engineered electric drive systems. CIMC-Tianda Holdings dominates volume manufacturing for Asia-Pacific greenfield projects with cost-competitive modular designs.
An airport passenger boarding bridge is a covered, movable connector that extends from an airport terminal gate to an aircraft doorway, typically spanning 3 to 5 meters in width and accommodating vertical movement ranges of 2.5 to 6 meters to service aircraft from regional jets to A380 configurations. Electric drive segments lead unit shipments due to lower energy consumption and reduced hydraulic fluid maintenance, while smart systems integrating LiDAR docking and IoT sensors represent the fastest-growing technology category as airports prioritize autonomous alignment and predictive maintenance capabilities.
FAA certification standards for aircraft docking safety systems and EASA airside equipment directives shape product design requirements and market access conditions for manufacturers serving transatlantic supply chains. China's GB standards for airport ground support equipment and India's Bureau of Civil Aviation Security mandates further fragment compliance obligations for multinational OEMs. Stakeholders must monitor which regulatory jurisdictions will mandate remote-controlled or fully automated docking first, as this timing will determine R&D allocation and regional manufacturing partnerships.
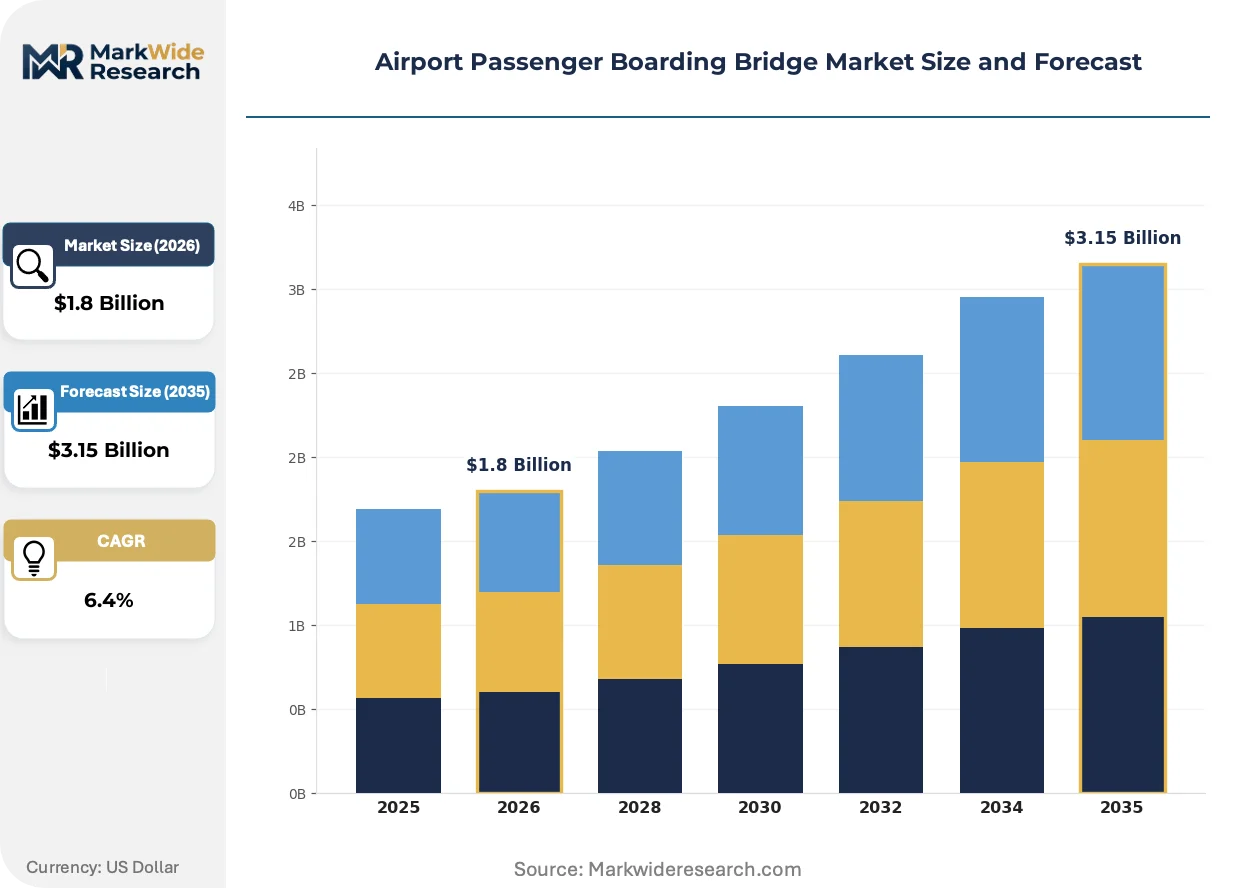
Market Dynamics
Electric drive systems and autonomous docking automation are compressing replacement cycles as airports face simultaneous pressure from EASA and FAA certification mandates for next-generation airside equipment.
Growth Catalysts
- Greenfield Airport Construction:China, India, and the United Arab Emirates are commissioning modular boarding bridge fleets for new terminal capacity, with hydraulically actuated units dominating initial procurement waves.
- FAA Certification Pressure:Advanced docking automation requirements under updated aircraft safety standards are forcing North American airports to retire legacy mechanical systems ahead of scheduled end-of-life.
- Wide-Body Fleet Expansion:Asia-Pacific carriers are adding A350 and 787 configurations, driving demand for extended-reach boarding bridges with 6-meter vertical adjustment ranges.
Market Restraints
- Steel and Aluminum Input Volatility:Structural frame manufacturing depends on commodity metals pricing, with Chinese GB standard steel grades experiencing supply inconsistency.
- European Supply Concentration:Precision electric drive component production clusters in Germany and Switzerland, creating single-source vulnerability for OEMs outside the region.
- Hydraulic System Substitution:Electric actuation is displacing hydraulic power units, stranding maintenance infrastructure and technical expertise at incumbent airports.
Strategic Opportunities
- Indian Terminal Modernization:Bureau of Civil Aviation Security mandates for enhanced perimeter security are unlocking retrofit budgets at Tier-2 airports previously deferred from capital planning.
- IoT-LiDAR Convergence:Sensor fusion between optical positioning and predictive maintenance algorithms is creating premium pricing tiers for autonomous alignment systems.
- Outcome-Based Service Contracts:Availability-based maintenance agreements are displacing transactional spare parts purchasing, locking OEMs into 10-15 year lifecycle revenue streams.
Industry Challenges
- Certification Timeline Compression:EASA airside equipment directives and FAA safety system approvals now run in parallel rather than sequence, doubling documentation burden for transatlantic suppliers.
- Legacy System Integration:1990s-era terminal infrastructure with analog control architectures requires complete electrical backbone replacement to support smart bridge connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Passenger Boarding Bridge Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electric, Manual, Modular End User: Airlines, Airports, Ground Handlers, Maintenance Providers Application: Domestic Flights, International Flights, VIP Services, Cargo Handling Technology: Smart Systems, Standard Systems, Remote Control, Safety Mechanisms |
| Companies Covered | ADELTE Group, FMT Aircraft Gate Support Systems, ThyssenKrupp Airport Solutions, Mitsubishi Heavy Industries, Oshkosh Corporation, JBT AeroTech, ShinMaywa Industries, HÜBNER, CIMC-Tianda Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Passenger Boarding Bridge Market Strategic Shifts
Software-defined functionality is migrating from aftermarket add-on to factory-standard configuration, redefining how boarding bridge OEMs capture value across equipment lifecycles.
LiDAR-based autonomous docking is rewriting operational protocols at high-volume hubs. The technology eliminates manual alignment by emitting pulsed laser measurements to calculate aircraft door position in real time. Dubai International and Singapore Changi are deploying these systems for 90-second connection targets. This capability is compressing ground time budgets and enabling tighter flight scheduling density.
Europe's F-Gas Regulation is accelerating refrigerant phase-out in climate-controlled bridge cabins. Manufacturers must redesign HVAC systems using natural refrigerants or low-global-warming-potential alternatives by mandated deadlines. Electric drive suppliers with integrated thermal management capabilities are capturing specification preference from airport engineering consultants.
Airport engineering departments are consolidating vendor relationships around full-fleet service accountability. Single-source contracting for installation, maintenance, and software updates is displacing fragmented procurement across multiple suppliers. This concentration is most visible in the United States, where municipal airport authorities face audit pressure to demonstrate lifecycle cost transparency.
Airport Passenger Boarding Bridge Market Segmentation
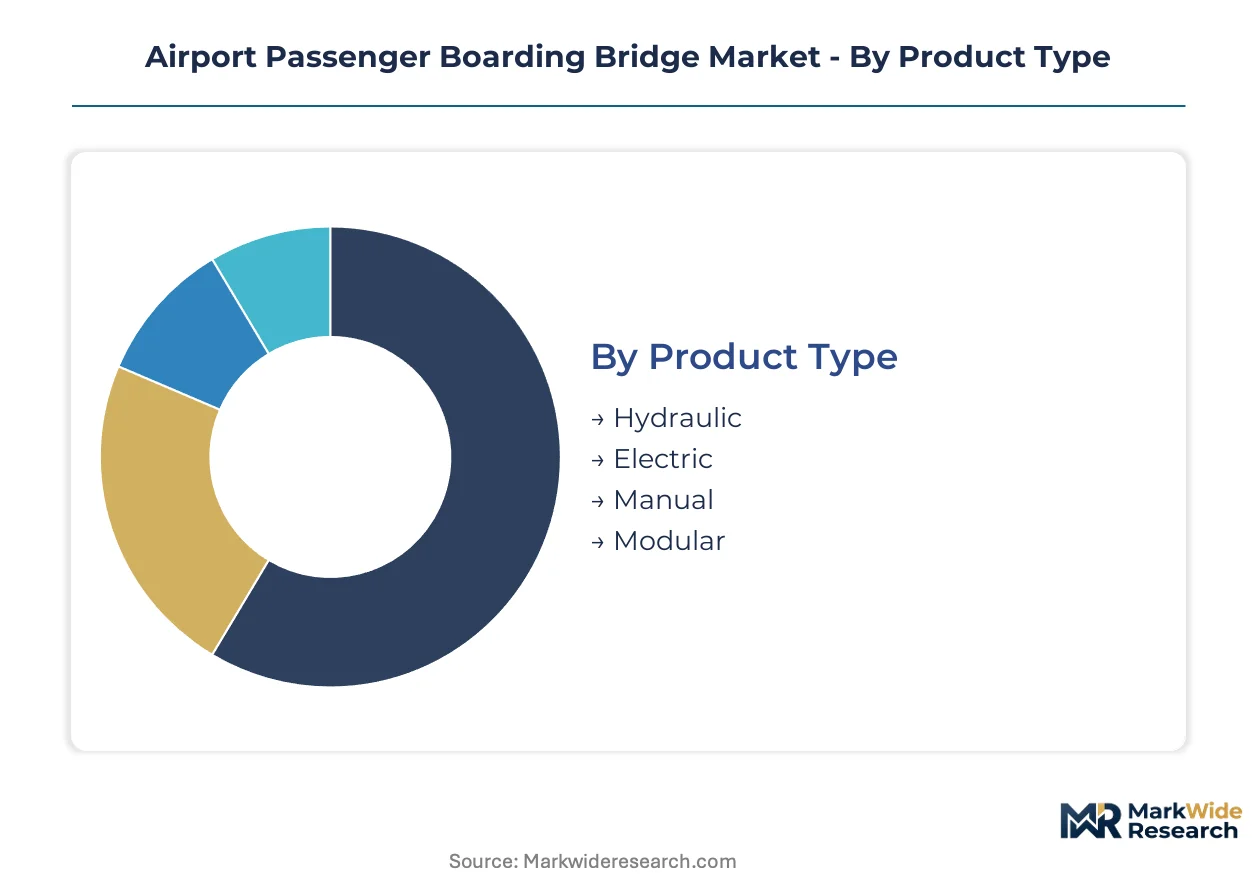
Segmentation in the airport passenger boarding bridge market reveals how procurement decisions split between operational requirements and capital constraints. Electric and smart-system configurations command specification preference at major hubs, while hydraulic units retain volume share at cost-sensitive greenfield developments. Understanding these fracture lines helps OEMs align R&D investment with where purchasing authority actually resides.
Product Type:
Drive mechanism and structural modularity define the core specification axis for boarding bridge procurement, with energy efficiency and maintenance burden driving specification divergence across airport tiers.
- Electric:Permanent magnet motors and regenerative drives eliminate hydraulic fluid handling and reduce energy draw by 40% versus legacy systems. Demand clusters at Frankfurt, Amsterdam Schiphol, and Singapore Changi where EASA and FAA certification timelines pressure rapid fleet turnover.
- Hydraulic:Fluid power units with piston-cylinder actuation deliver higher initial lifting capacity at lower capital cost. Procurement concentrates at Chinese and Indian greenfield airports where first-cost sensitivity outweighs lifecycle operating expense calculations.
- Manual:Hand-crank or towable units for regional jet operations at Tier-3 airports with limited electrification infrastructure.
- Modular:Pre-fabricated tunnel sections enabling rapid terminal expansion without structural core drilling.
Mature deployment sits with hydraulic systems at legacy terminals. Newer deployment is concentrated in electric configurations at airports facing EASA airside equipment directives.
End User:
Purchasing authority fragmentation creates divergent specification priorities between asset owners and service contractors.
- Airports:Municipal and privatized terminal operators owning fixed infrastructure prioritize 20-year lifecycle cost models and smart-system integration for gate utilization optimization.
- Airlines:Network carriers at hub airports specify extended-reach units accommodating A350 and 787 door sill heights, with preference for autonomous docking to protect narrow turnaround windows.
- Ground Handlers:Swissport, dnata, and Menzies Aviation procure mobile units for apron flexibility where fixed bridges are unavailable or congested.
- Maintenance Providers:JBT AeroTech and ThyssenKrupp service divisions capture aftermarket contracts through availability-based agreements rather than equipment ownership.
Capital ownership concentrates with airport authorities. Operational control is migrating toward ground handlers through outsourced ramp management contracts.
Application:
Flight type and passenger service tier determine dimensional requirements and amenity specifications.
- International Flights:Wide-body docking with climate-controlled cabins, biometric boarding integration, and 6-meter vertical adjustment ranges. Dubai International and Heathrow Terminal 5 specify these for premium carrier contracts.
- Domestic Flights:Narrow-body optimized units with faster deployment cycles and lower capital intensity, dominant at Chinese domestic terminals and Indian metro airports.
- VIP Services:Private jet terminals and royal flight facilities specify compact units with discrete tunnel geometry and enhanced finishing.
- Cargo Handling:Freighter-specific configurations with elevated floor heights and reinforced structural ratings for main deck loading.
Volume deployment tracks domestic flight infrastructure expansion. Value concentration is climbing fastest in international flight configurations at hub transfer terminals.
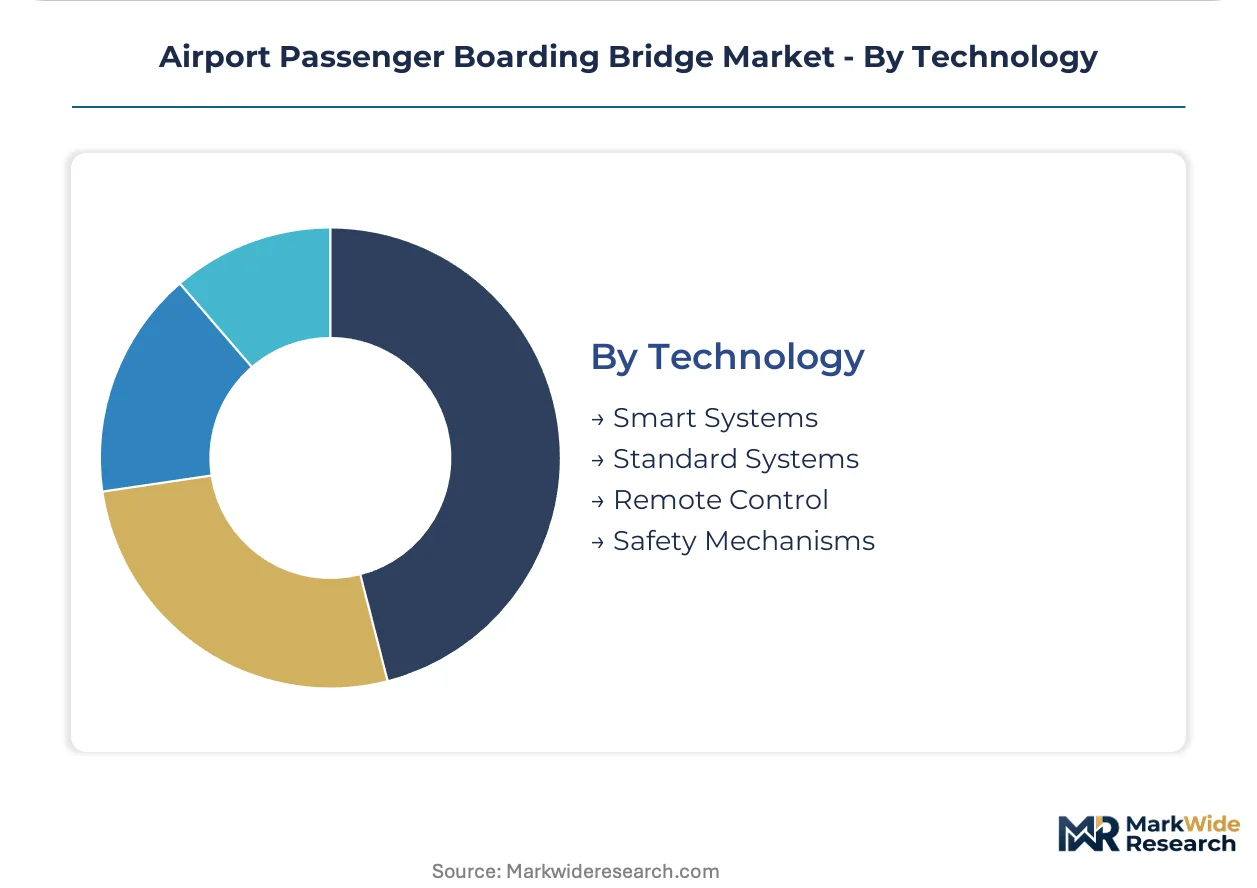
Technology:
Automation depth and sensor integration are redefining competitive differentiation beyond mechanical specifications.
- Smart Systems:LiDAR docking, IoT predictive maintenance, and fleet management software. Singapore Changi and Dubai International deploy these for sub-90-second connection targets and autonomous alignment.
- Standard Systems:Basic electro-mechanical control with manual operator alignment, retaining share at secondary airports with limited IT infrastructure.
- Remote Control:Operator-station docking from centralized control rooms, reducing ground staff exposure and enabling single-operator multi-gate management.
- Safety Mechanisms:Collision avoidance sensors, emergency stop systems, and wind load monitoring as standalone upgrade packages or integrated modules.
Specification preference is diverging between smart-system mandates at Tier-1 hubs and standard-system procurement at regional airports with constrained capital budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors procurement intensity for smart-system boarding bridges, with Emirates' hub operations driving specification preference for LiDAR-equipped autonomous docking at Dubai International's Terminal 3 expansion zones.
United States
FAA certification mandates for advanced aircraft safety systems are accelerating replacement cycles at Atlanta Hartsfield-Jackson and Dallas-Fort Worth. Municipal airport authorities face audit pressure to demonstrate lifecycle cost transparency through consolidated vendor contracts. Chicago O'Hare's Terminal 5 modernization exemplifies this shift toward single-source service accountability.
Germany
EASA airside equipment directives and the F-Gas Regulation are reshaping procurement specifications at Frankfurt and Munich airports. Precision electric drive component production clusters in Baden-Württemberg and Bavaria, creating single-source vulnerability for OEMs sourcing outside the region. ThyssenKrupp Airport Solutions anchors European demand through precision-engineered systems.
China
Greenfield airport construction at Chengdu Tianfu and Beijing Daxing is driving bulk orders for modular boarding bridges. GB standards for airport ground support equipment fragment compliance obligations for multinational suppliers. CIMC-Tianda Holdings dominates volume manufacturing for Asia-Pacific projects with cost-competitive designs.
India
Bureau of Civil Aviation Security mandates for enhanced perimeter security are unlocking retrofit budgets at Tier-2 airports including Bangalore and Hyderabad. Terminal modernization programs previously deferred from capital planning now advance with central government infrastructure financing. Mumbai's Chhatrapati Shivaji Maharaj International Airport specifies extended-reach units for wide-body operations.
United Arab Emirates
Etihad Airways' hub operations at Abu Dhabi Zayed International drive demand for climate-controlled cabins with biometric boarding integration. MOHAP aviation safety standards align with EASA frameworks for transatlantic equipment certification. Sharjah Airport's cargo expansion specifies freighter-specific configurations with elevated floor heights.
Airport Passenger Boarding Bridge Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the boarding bridge supply base. Integrated OEMs with captive manufacturing and service infrastructure capture multi-decade airport contracts through availability-based agreements. Three archetypes dominate: full-stack system integrators bundling hardware, software and lifecycle services; component specialists supplying electric drives and sensor modules; and regional fabricators focused on cost-optimized modular structures. Consolidation pressure is concentrating procurement authority around OEMs with FAA and EASA certification track records, while technology licensing partnerships accelerate smart-system capability diffusion.
Among Asia-Pacific volume manufacturers, CIMC-Tianda Holdings occupies a position exemplifying cost-competitive modular production for greenfield developments. ThyssenKrupp Airport Solutions and JBT AeroTech represent the integrated service archetype, anchoring long-term contract capture through North American and European maintenance infrastructure. These three entities illustrate how geographic manufacturing concentration and certification depth determine competitive positioning across procurement tiers.
| Leading Market Players |
|---|
| ADELTE Group |
| FMT Aircraft Gate Support Systems |
| ThyssenKrupp Airport Solutions |
| Mitsubishi Heavy Industries |
| Oshkosh Corporation |
| JBT AeroTech |
| ShinMaywa Industries |
| HÜBNER |
| CIMC-Tianda Holdings |
| Others |
Value Chain & Pricing Dynamics
Municipal airport authorities and privatized terminal operators concentrate procurement authority around availability-based service contracts, anchoring pricing models to equipment uptime guarantees rather than capital expenditure thresholds. This buyer-archetype dominance shifts value capture toward lifecycle revenue streams and locks OEMs into long-term performance accountability.
Pricing Analysis
Uptime-guarantee contracts set the value-based pricing anchor, with availability thresholds of 98-99% commanding premium service fees. Price differentiation rests on certification depth — FAA and EASA dual-certification tiers separate premium integrators from regional fabricators — and smart-system integration levels. Cost compression in hydraulic-actuated units is intensifying because Chinese and Indian greenfield projects prioritize first-cost minimization over lifecycle operating expense. Tier-2 airports in India and Southeast Asia exhibit highest price sensitivity, while hub operators at Dubai International and Singapore Changi prioritize throughput optimization over capital constraints.
Supply Chain Analysis
Refurbishment flows for 1990s-era legacy bridges are creating secondary component markets, with electric drive retrofits and control system upgrades extending asset lifecycles. Manufacturing concentrates in China for cost-optimized modular structures, Germany for precision electric drive components, and the United States for integrated smart-system assemblies. Structural steel and aluminum extrusions draw from commodity metals markets with Chinese GB standard grades, while permanent magnet motors and LiDAR sensors hinge on semiconductor supply chains centered in Taiwan and South Korea. Single-source vulnerability in German and Swiss electric drive component production creates supply chain risk. Distribution runs through OEM-direct contracting for major hub installations and regional distributor networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric drive systems and autonomous docking automation are displacing hydraulic infrastructure, compressing replacement cycles and redefining competitive positioning around software-defined functionality rather than mechanical specifications.
For Market Incumbents: To counter margin erosion from Chinese modular fabricators, JBT AeroTech and ThyssenKrupp Airport Solutions should deepen captive control over North American and European service infrastructure, locking in 10-15 year availability contracts. Certification investment in FAA-EASA dual-track approval capabilities creates defensive moats against emerging Asian competitors lacking transatlantic regulatory track records. For New Entrants and Emerging Players: Tier-2 Indian airports facing Bureau of Civil Aviation Security retrofit mandates represent the most penetrable buyer segment, with deferred capital budgets now unlocked through central government infrastructure financing. A go-to-market angle bundling modular electric bridges with integrated perimeter security compliance offers specification preference against incumbent hydraulic offerings. Regional fabricators in Southeast Asia can capture share by targeting greenfield Vietnamese and Indonesian terminals with cost-competitive smart-system configurations. For Investors and Strategic Acquirers: The window for entry favors component specialists with LiDAR and IoT sensor capabilities, as autonomous docking becomes factory-standard rather than aftermarket add-on. Full-stack integrators bundling hardware, software, and lifecycle services command premium valuation multiples over asset-light designers. The signal to watch is which regulatory jurisdiction mandates fully automated docking first, as this timing will determine acquisition premiums for certification-ready targets.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-System Certification Investment | FAA-EASA dual-track approvals unlock transatlantic procurement at Atlanta and Frankfurt hubs. |
| Availability-Based Service Contracting | 10-15 year lifecycle agreements displace transactional spare parts purchasing at municipal airports. |
| LiDAR-IoT Sensor Module Development | Autonomous alignment capabilities command specification preference from Singapore Changi engineering teams. |
| Regional Manufacturing Partnership | Local assembly in India and Vietnam reduces delivery costs for greenfield terminal projects. |
| Hydraulic-to-Electric Retrofit Program | Legacy bridge upgrades extend asset life while capturing deferred maintenance budgets at Tier-2 airports. |
Study Parameters
Multi-period observation of procurement contract structures, regulatory certification timelines, and fleet replacement cycles anchored the trend analysis, supplemented by interviews with airport engineering directors, OEM aftermarket service heads, ground handling procurement managers, and EASA-FAA regulatory affairs specialists. Secondary validation drew from FAA airworthiness directives, EASA airside equipment certification databases, airport authority capital expenditure disclosures, and customs trade data on steel and aluminum inputs. Bottom-up unit shipment estimates across electric, hydraulic, and smart-system configurations triangulated against top-down market value assessments from OEM revenue disclosures and service contract announcements.
Segment-weighting approaches modeled drive mechanism type, end-user purchasing authority, flight application requirements, and automation technology depth across the projection horizon. CAGRs were derived from fitted growth curves calibrated to greenfield construction pipelines, regulatory mandate effective dates, and wide-body fleet delivery schedules. Forecast inputs incorporated EASA F-Gas Regulation compliance deadlines, India's Bureau of Civil Aviation Security retrofit mandates, and Chinese GB standard evolution for ground support equipment.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory automation mandates and commodity metals pricing volatility. Projections reflect assumptions on certification timeline convergence and electric drive cost curves. Practitioners should monitor EASA and FAA automated docking standard releases, Chinese steel export policy shifts, and Indian infrastructure financing disbursement rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Airport Logistics Systems Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
Runway Lighting System Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Europe Airport Baggage Handling Systems Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
North America Ground Handling System Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Airport Ground Support Equipment Market